


 |
市場調查報告書
商品編碼
2120575
清潔劑:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Detergents - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
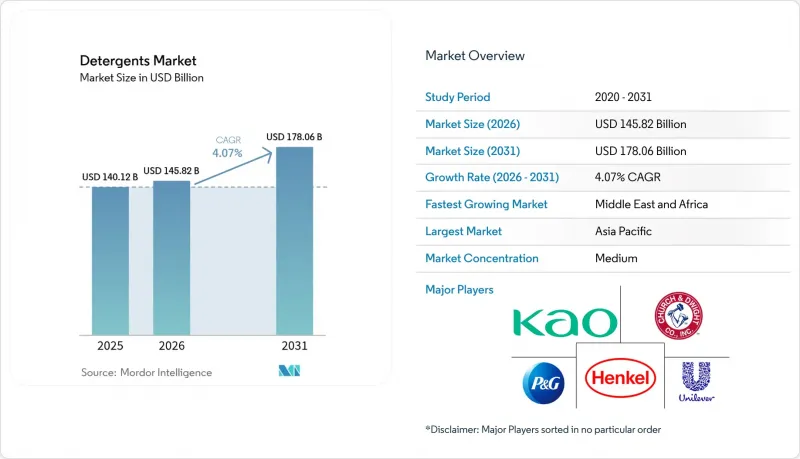
據 Mordor Intelligence 稱,2025 年清潔劑市值為 1401.2 億美元,預計到 2031 年將達到 1780.6 億美元,而 2026 年為 1458.2 億美元,預測期(2026-2031 年)的複合年成長率為 4.07%。
本報告按類型(陰離子清潔劑、陽離子清潔劑、非離子清潔劑、兩性離子(兩性)清潔劑)、應用(洗衣、家用清潔劑、洗碗清潔劑、燃料添加劑、生物試劑及其他)和地區(亞太地區、北美、歐洲、南美、中東和非洲)進行細分。市場預測以美元計價。
全球清潔劑市場趨勢及洞察
新興國家洗衣機普及率不斷提高
印度的自動洗衣機擁有率從2020年的14%成長到2024年的28%。這導致人均清潔劑用量增加,因為滾筒式洗衣機比手洗多用30%到40%的清潔劑。 250毫升的小包裝液體洗滌劑和10次用量的包裝有助於降低入門價格,同時維持40%以上的利潤率。印尼和越南也出現了類似的普及曲線,兩國都受惠於家電補貼和分期付款計畫。目前,配方研發人員會指定針對30分鐘、20 度C洗滌週期最佳化的酶,而BASF的蛋白酶「Lavergy」在提供類似去污效果的同時,還能降低35%的能耗。
清潔劑市場電子商務和D2C通路的快速成長
2024年,直接面對消費者的訂閱銷售額達到42億美元,較去年同期成長38%。這主要歸功於品牌繞過了零售商25%至35%的利潤率。較低的獲客成本(每位用戶18美元)以及第三次配送後低於15%的解約率是盈利的基礎。北美地區的線上銷售額佔總銷售額的32%,中國則高達41%。這主要得益於當日送達服務和強調成分透明度的網紅行銷。濃縮型洗衣凝珠和洗衣片比同類液體清潔劑輕70%,不僅降低了0.12美元的末端配送成本,還減少了60%的包裝廢棄物。
全球和區域層面的嚴格化學品法規
2023年10月,歐洲化學品管理局(ECHA)根據REACH法規附件XVII,對微塑膠進行監管,並禁止在沖洗型清潔劑中故意使用微塑膠,過渡期為4至12年。 2024年4月,美國環保署(EPA)擴大了其PFAS法規的適用範圍,要求製造商證明界面活性劑和加工助劑中全氟烷基和多氟烷基物質的含量不超過十億分之一(ppb)。這實際上禁止了在工業和商用清潔產品中使用傳統的含氟表面活性劑。這些法規對缺乏研發預算、難以快速調整配方的小規模區域品牌影響尤為嚴重,而跨國公司則可以將合規成本分攤到年產量超過50萬噸的全球業務中。
細分市場分析
到2025年,陰離子界面活性劑將佔據清潔劑市場45.84%的佔有率。這主要得益於低成本的直鏈磺酸鹽碸,它們支撐著南亞和非洲的旗艦粉狀和液體洗滌劑產品。非離子醇乙氧基化物和烷基聚葡萄糖苷因其快速的端到端生物分解性而備受青睞,預計將以4.95%的複合年成長率成長,這主要得益於歐盟法規要求在28天內進行好氧分解。 2024年,漢高公司改良了「Persil Sensitive」的配方,以源自玉米粉的烷基聚葡萄糖苷取代了40%的直鏈烷基苯碸。此舉在維持產品性能的同時,成功地將水生毒性降低了35%。
由於帶正電荷,陽離子季銨鹽界面活性劑與陰離子界面活性劑的相容性有限,因此在軟水器以外的領域仍屬於小眾產品。在環保署對季銨鹽界面活性劑進行嚴格審查後,目前正在進行試點研究,以尋找更易生物分解的酯類季銨鹽界面活性劑替代品。兩性離子椰油醯胺丙基甜菜鹼預計到2024年將佔市場總量的6%,它能穩定中東和北非硬水市場的泡沫,並且其廣泛的pH穩定性使其適用於不使用礦物螯合劑的冷水軟化器。
區域分析
預計到2025年,亞太地區將佔全球洗衣液銷售量的44.10%。這主要得益於印度和印尼洗衣機擁有量翻倍、中國電子商務的蓬勃發展以及消費者對富含酵素的優質化清潔劑的需求成長。在中國,藍月(Blue Moon)和利比(Libby)等領先本土企業透過線上客戶參與和提供客製化香型,佔據了清潔劑市場38%的佔有率。 2024年,印度市場成長了7.2%,這主要得益於針對首次使用洗衣機用戶的250毫升經濟型包裝。在日本和韓國等成熟市場,消費者關注的焦點是生物基異硫氰酸界面活性劑,可將去污速度提高30%。
預計中東和非洲將經歷最快的成長,由於都市化,人均消費量將超過3公斤,年複合成長率將達到4.78%。沙烏地阿拉伯的「2030願景」計畫正在推動基礎設施建設,使洗衣機普及率接近65%,並促進了對適用於硬水的洗衣凝珠的需求。在電力供應不穩定的情況下,酶基粉狀清潔劑即使在冷水洗滌週期中也能發揮良好作用,這推動了南非市場在2024年銷量成長5.8%。雖然粉狀清潔劑在撒哈拉以南非洲的農村地區仍然佔據主導地位,但隨著滾筒洗衣機的普及,拉各斯和內羅畢對液體清潔劑的需求正在成長。
儘管歐洲和北美地區的成長速度有所放緩,但這些地區在永續性方面正引領創新。在德國,2024年有環保標章的產品佔清潔劑銷售額的42%。在美國,洗衣凝珠和洗衣片佔洗衣總量的32%,而加拿大和英國在雜貨店安裝的補充裝站點已使包裝減少了40%。南美洲在2024年實現了4.2%的成長。粉狀清潔劑仍佔68%的市場佔有率,但在巴西和阿根廷的都市區,液體清潔劑的市場佔有率正在不斷成長,這兩個國家的洗衣機擁有率超過55%。
其他福利
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 新興國家洗衣機普及率不斷上升
- 清潔劑市場電子商務和D2C通路的快速成長
- 消費者轉向環保和可生物分解產品
- 低溫酶技術的顯著進步降低了能源消耗
- 碳排放稅導致對超高高等級精礦的需求增加。
- 市場限制因素
- 全球和區域層面的嚴格化學品法規
- 原料價格波動(界面活性劑、酵素)
- 由於微塑膠過濾過濾的實施,產品配方變更成本增加。
- 價值鏈分析
- 波特五力模型
第5章 市場規模與成長預測
- 按類型
- 陰離子清潔劑
- 陽離子清潔劑
- 非離子型清潔劑
- 兩性離子(兩性)清潔劑
- 透過使用
- 洗衣店
- 家用清潔劑
- 清潔劑
- 燃油添加劑
- 生物試劑
- 其他
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- ASEAN
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 義大利
- 法國
- 俄羅斯
- 西班牙
- 北歐國家
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- Blue Moon Group
- Church & Dwight Co., Inc.
- Guangzhou Liby Group Co. Ltd
- Henkel AG & Co. KGaA
- Johnson & Johnson Private Limited
- Kao Corporation
- Lion Corporation
- Nice Group
- Procter & Gamble
- Reckitt Benckiser Group plc
- RSPL Group
- SC Johnson
- Seventh Generation Inc.
- Unilever
第7章 市場機會與未來展望
According to Mordor Intelligence, the detergents market size was valued at USD 140.12 billion in 2025 and estimated to grow from USD 145.82 billion in 2026 to reach USD 178.06 billion by 2031, at a CAGR of 4.07% during the forecast period (2026-2031).
This report is Segmented by Type (Anionic, Cationic, Non-Ionic, and Zwitterionic), Application (Laundry, Household Cleaning, Dishwashing, Fuel Additives, Biological Reagents, and Other Applications), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). Market Forecasts are Provided in Terms of Value (USD).
Global Detergents Market Trends and Insights
Rising Washing-Machine Penetration in Emerging Economies
Automatic washer ownership in India increased from 14% in 2020 to 28% in 2024, resulting in a rise in per-capita detergent usage, as drum cycles require 30%-40% more product than hand-washing. Smaller 250ml liquid packs and 10-wash sachets help keep entry prices low while sustaining margins above 40%. Similar adoption curves in Indonesia and Vietnam benefit from appliance subsidies and installment-payment schemes. Formulators now specify enzymes optimized for 30-minute, 20°C cycles, with BASF's Lavergy protease delivering equivalent stain removal at 35% lower energy consumption.
Boom in E-Commerce and D2C Channels for Detergents
Direct-to-consumer subscriptions generated USD 4.2 billion in 2024, representing a 38% year-over-year growth as brands bypass retailers' 25%-35% markup. Lower acquisition costs (USD 18 per subscriber) and churn below 15% after the third delivery underpin profitability. Online sales reached 32% in North America and 41% in China, driven by same-day logistics and influencer marketing that emphasize ingredient transparency. Concentrated pods and strips, 70% lighter than equivalent liquids, shave USD 0.12 from last-mile freight while reducing packaging waste by 60%.
Stringent Global and Regional Chemical Regulations
In October 2023, the European Chemicals Agency, under REACH Annex XVII, restricted microplastics, banning their intentional use in rinse-off detergents with transition periods of 4 to 12 years. In April 2024, the US Environmental Protection Agency expanded PFAS restrictions, requiring manufacturers to certify that surfactants and processing aids contain no per- and polyfluoroalkyl substances above 1 part per billion, effectively banning legacy fluorosurfactants in industrial and institutional cleaning products. These regulations disproportionately affect smaller regional brands, which lack the R&D budgets for rapid reformulation, while multinationals spread compliance costs over global volumes exceeding 500,000 metric tons annually.
Other drivers and restraints analyzed in the detailed report include:
- Consumer Shift to Eco-Friendly and Biodegradable Formulations
- Cold-Water Enzyme Breakthroughs Cut Energy Use
- Raw-Material Price Volatility (Surfactants, Enzymes)
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Anionic surfactants held 45.84% of the Detergents market share in 2025, supported by low-cost linear alkylbenzene sulfonates that anchor powder and liquid staples in South Asia and Africa. Non-ionic alcohol ethoxylates and alkyl polyglucosides, prized for rapid ultimate biodegradation, are forecast to grow at a 4.95% CAGR, lifted by EU rules requiring aerobic breakdown within 28 days. Henkel reformulated Persil Sensitive in 2024 by substituting 40% of LAS with corn-starch-derived alkyl polyglucosides, thereby lowering aquatic toxicity by 35% while retaining the product's performance.
Cationic quaternary ammonium surfactants remain niche outside fabric softeners because their positive charge limits co-formulation with anionics. EPA scrutiny of quats is prompting pilots of faster-biodegrading ester-quat alternatives. Zwitterionic cocamidopropyl betaine, 6% of 2024 volume, stabilizes foam in hard-water markets across the Middle East and North Africa, and its broad pH stability suits cold-water pods that avoid mineral chelators.
Complete Report Scope:
- By Type
- Anionic Detergents
- Cationic Detergents
- Non-ionic Detergents
- Zwitterionic (Amphoteric) Detergents
- By Application
- Laundry Cleaning Products
- Household Cleaning Products
- Dishwashing Products
- Fuel Additives
- Biological Reagents
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- Italy
- France
- Russia
- Spain
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
The Asia-Pacific region accounted for 44.10% of the global 2025 volume, driven by a doubling of washing-machine ownership in India and Indonesia, robust e-commerce in China, and a shift toward premiumization of enzyme-rich liquids. Local champions such as Blue Moon and Liby hold a 38% share of China's liquid category through direct online engagement and tailored fragrances. India's market expanded by 7.2% in 2024, driven by affordable 250 ml packs targeting first-time machine users. Mature Japan and South Korea focus on bio-based isethionate surfactants that accelerate soil release by 30%.
The Middle East & Africa are forecast to deliver the fastest growth, with a 4.78% CAGR, as urbanization lifts per-capita consumption above 3 kg. Saudi Arabia's Vision 2030 infrastructure push raises washer penetration toward 65%, spurring demand for hard-water-tolerant pods. South Africa's market increased by 5.8% in volume in 2024, driven by enzyme-fortified powders that perform well in cold cycles, a necessity amid intermittent electricity supply. Sachet-priced powders dominate rural Sub-Saharan Africa, but liquid formats are gaining traction in Lagos and Nairobi as front-load adoption increases.
Europe and North America register slower growth but lead sustainability innovation. Germany's eco-labeled segment reached 42% of 2024 detergent sales. US pods and strips command 32% of laundry volume, and refill stations in Canadian and UK grocers reduce packaging by 40%. South America grew by 4.2% in 2024; powders still hold a 68% share, but liquids are rising in urban Brazil and Argentina, alongside washer ownership above 55%.
- Blue Moon Group
- Church & Dwight Co., Inc.
- Guangzhou Liby Group Co. Ltd
- Henkel AG & Co. KGaA
- Johnson & Johnson Private Limited
- Kao Corporation
- Lion Corporation
- Nice Group
- Procter & Gamble
- Reckitt Benckiser Group plc
- RSPL Group
- SC Johnson
- Seventh Generation Inc.
- Unilever
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising washing-machine penetration in emerging economies
- 4.2.2 Boom in e-commerce and D2C channels for detergents
- 4.2.3 Consumer shift to eco-friendly/biodegradable formulations
- 4.2.4 Cold-water enzyme breakthroughs cut energy use
- 4.2.5 Carbon-tax driven demand for ultra-concentrates
- 4.3 Market Restraints
- 4.3.1 Stringent global and regional chemical regulations
- 4.3.2 Raw-material price volatility (surfactants, enzymes)
- 4.3.3 Micro-plastic filtration mandates raise reformulation costs
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size & Growth Forecasts (Volume)
- 5.1 By Type
- 5.1.1 Anionic Detergents
- 5.1.2 Cationic Detergents
- 5.1.3 Non-ionic Detergents
- 5.1.4 Zwitterionic (Amphoteric) Detergents
- 5.2 By Application
- 5.2.1 Laundry Cleaning Products
- 5.2.2 Household Cleaning Products
- 5.2.3 Dishwashing Products
- 5.2.4 Fuel Additives
- 5.2.5 Biological Reagents
- 5.2.6 Other Applications
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 Italy
- 5.3.3.4 France
- 5.3.3.5 Russia
- 5.3.3.6 Spain
- 5.3.3.7 NORDIC Countries
- 5.3.3.8 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Blue Moon Group
- 6.4.2 Church & Dwight Co., Inc.
- 6.4.3 Guangzhou Liby Group Co. Ltd
- 6.4.4 Henkel AG & Co. KGaA
- 6.4.5 Johnson & Johnson Private Limited
- 6.4.6 Kao Corporation
- 6.4.7 Lion Corporation
- 6.4.8 Nice Group
- 6.4.9 Procter & Gamble
- 6.4.10 Reckitt Benckiser Group plc
- 6.4.11 RSPL Group
- 6.4.12 SC Johnson
- 6.4.13 Seventh Generation Inc.
- 6.4.14 Unilever
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

 乙二胺四乙酸市場:全球市場預測,2026-2032年
 清潔劑用酒精:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)清潔劑市場-2026-2032年全球市場預測
 2026 年至 2035 年清潔劑洗滌劑市場的商業機會、成長要素、產業趨勢分析與預測。清潔劑化學品市場:按技術、產品類型、劑型、最終用戶、分銷管道和應用分類-2026-2032年全球市場預測
 2026年全球可生物分解清潔劑市場報告2026年全球天然葉醇市場報告
 清潔劑化學品市場分析及預測(至2035年):依類型、產品類型、應用、劑型、材料類型、製程、最終用戶、功能及技術分類清潔劑酒精市場分析及預測(至2035年):類型、產品類型、應用、劑型、材料類型、製程、技術、最終用戶、功能、解決方案
 全球清潔劑市場規模、佔有率、趨勢和成長分析報告(2026-2034年)