


 |
市場調查報告書
商品編碼
2120502
碳酸鈣:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Calcium Carbonate - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2026 年碳酸鈣市場規模預計為 1.6949 億噸,高於 2025 年的 1.6468 億噸,預計到 2031 年將達到 1.9569 億噸。
預計從 2026 年到 2031 年,其複合年成長率將達到 2.92%。
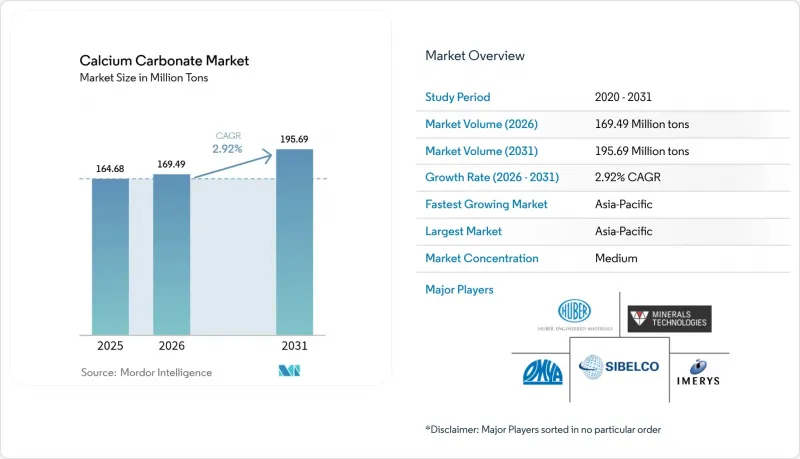
本報告按類型(研磨碳酸鈣 (GCC)、沉澱碳酸鈣 (PCC))、應用(建築原料、營養補充劑、熱塑性塑膠添加劑、填料和顏料、其他)、最終用戶產業(造紙、塑膠、黏合劑和密封劑、建築、其他)以及地區(亞太地區、北美、歐洲、南美、中東和非洲)進行分類。
全球碳酸鈣市場趨勢及洞察
加速建設和基礎設施開發
亞太地區公共工程支出的激增推動了碳酸鈣市場的發展,建築商對經濟高效的礦物填料的需求日益成長,這些填料可用於水泥、聚合物改質混凝土、建築塗料和密封劑。為滿足此需求,綜合性製造商正在擴大產能。例如,伊梅里斯公司已將其位於阿拉巴馬州塞拉科加工廠的產量加倍,以供應建築級材料並縮短向北美客戶的交貨時間。城市負責人對低碳建築材料的推動也增加了對ReMined等產品的需求。 ReMined是一種100%預生產回收的碳酸鈣,可在維持強度和耐久性標準的同時減少碳排放。這些與永續性相關的細分市場使經銷商能夠在銷售穩定成長的同時,維持更高的利潤率。
塑膠聚合物應用範圍的擴大
奈米級研磨技術和表面處理化學的快速發展提高了薄膜、母粒和工程塑膠的性能上限。奈米碳酸鈣能夠改善包裝材料的拉伸強度、阻隔性和熱穩定性,同時保持其透明度,使加工商能夠按以重量為準減少高達5%的樹脂用量。中國製造商湖北微晶新材料有限公司已證明,分散在可生物分解聚合物中的粒徑小於100奈米的顆粒可以精細調節分解速率,同時提高薄膜韌性,從而直接滿足循環經濟中的包裝需求。汽車OEM廠商和電子品牌正擴大將這些功能性填料作為產品規格,以實現輕量化、耐熱性和可回收性的目標。
與碳酸鈣相關的健康問題
在工人接觸可吸入碳酸鈣粉塵後,監管力道加大,要求降低工廠和下游加工設施的暴露限值,並制定更嚴格的防護標準。奈米顆粒毒性的研究仍在進行中,食品和藥品申請核准現在通常需要進行廣泛的風險評估。這可能導致產品上市時間延長和合規成本增加。資金有限的小規模生產商往往難以實施封閉回路型加工系統和高效過濾設備,從而限制了供應的柔軟性。
細分市場分析
由於石灰石礦床豐富且研磨製程能耗低,粉狀碳酸鈣(GCC)仍將是碳酸鈣市場的主力軍,預計到2025年將佔76.92%的市場佔有率。在普通造紙、聚烯薄膜和預拌混凝土等以銷售主導的產業中,GCC卓越的成本績效仍是決定性因素。同時,沉澱碳酸鈣(PCC)正以3.31%的複合年成長率推動市場成長,預計2031年將持續成長。客戶願意為其窄粒徑分佈、高白度和可客製化的表面化學性質支付溢價。研究人員利用大豆尿素酶成功實現酵素沉澱,進一步凸顯了這項轉變,這為降低成本、拓展PCC的應用範圍提供了可能。
因此,成熟的碳酸鈣生產商正在升級工廠設備,引入分選研磨系統和乾塗設備,以期在無需碳化反應器所需的大量資本投入的情況下,達到與碳酸鈣相當的性能。同時,碳酸鈣供應商正在擴大其內部二氧化碳捕集和可再生能源的使用,以減少碳足跡,這正日益成為跨國公司客戶的重要採購標準。儘管這些相互交織的策略加劇了競爭,但鑑於建築、塑膠和生命科學產業不同的需求特點,預計這兩個細分市場的碳酸鈣市場規模都將穩定成長。
區域分析
預計到2025年,亞太地區將以48.25%的市佔率主導碳酸鈣市場,並將以3.62%的複合年成長率持續成長至2031年。中國是該地區的主要需求來源,伊梅里斯在蕪湖、青陽和岳陽設有工廠,為包裝、建築和生命科學領域的客戶提供產品。東南亞國家也正在透過提高塗佈板和PVC管材的產能來擴大該地區的需求基礎。
北美憑藉其先進的塑膠和醫藥供應鏈保持著強勁的市場地位,這些供應鏈優先考慮技術等級產品並實施嚴格的品管。近期在阿拉巴馬州和喬治亞的投資凸顯了該地區對在地採購的迫切需求,以減少運輸排放並確保快速的技術支援。在歐洲,嚴格的碳排放減量法規和採石場修復條例使得再生材料和節能型沉澱廠成為必需品。南美洲受益於巴西和阿根廷的建築熱潮,以及農產品的成長帶動了土壤處理產品的消費。中東地區石化聯合企業和大規模基礎設施專案帶來了穩定的需求。同時,非洲的採石潛力尚未充分開發,但前景可期,尤其是在埃及、奈及利亞和南非。優質石灰石礦床的地理分佈將繼續影響貿易流動和區域定價,但本地建立的沉澱廠和現代化的研磨設施正在逐步減輕全球碳酸鈣市場的運輸負擔。
其他福利
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 加速建設和基礎設施開發
- 塑膠聚合物應用範圍的擴大
- 紙張和包裝產業的需求不斷成長
- 醫療和製藥應用領域的擴展
- 市場限制因素
- 與碳酸鈣相關的健康問題
- 有關環境和採礦的法規
- 物流和供應鏈面臨的挑戰
- 價值鏈分析
- 波特五力模型
- 進出口貿易統計數據
第5章 市場規模與成長預測
- 按類型
- 細磨碳酸鈣(GCC)
- 沉澱碳酸鈣(PCC)
- 透過使用
- 建築材料原料
- 營養補充品
- 熱塑性塑膠添加劑
- 填料和顏料
- 黏合劑組件
- 燃料氣脫硫
- 土壤中和劑
- 其他
- 按最終用戶行業分類
- 紙
- 塑膠
- 黏合劑和密封劑
- 建造
- 油漆和塗料
- 製藥
- 車
- 農業
- 橡皮
- 其他
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- ASEAN
- 澳洲和紐西蘭
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 俄羅斯
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 伊朗
- 伊拉克
- 科威特
- 卡達
- 其他中東國家
- 非洲
- 南非
- 其他非洲地區
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- ACCM
- GCCP Resources Limited
- Gulshan Polyols Ltd.
- Huber Engineered Materials
- Imerys
- Jordan Carbonate Company
- Manaseer Group
- Minerals Technologies Inc.
- Nigtas
- OKUTAMA KOGYO CO.,LTD.
- Omya International AG
- Provencale SA
- SaudiCarbonate
- SCHAEFER KALK GmbH & Co. KG
- Shiraishi Group
- Sibelco
- SigmaRoc Plc
- VMPC Joint Stock Company.
- Zantat Sdn. Bhd.
第7章 市場機會與未來展望
According to Mordor Intelligence, calcium carbonate market size in 2026 is estimated at 169.49 million tons, growing from 2025 value of 164.68 million tons with 2031 projections showing 195.69 million tons, growing at 2.92% CAGR over 2026-2031.
This report is Segmented by Type (Ground Calcium Carbonate and Precipitated Calcium Carbonate), Application (Raw Substance for Construction Material, Dietary Supplement, Additive for Thermoplastics, Filler and Pigment, and More), End-User Industry (Paper, Plastic, Adhesives and Sealants, Construction, and More), and Geography (Asia-Pacific, North America, Europe, South America, Middle-East, and Africa).
Global Calcium Carbonate Market Trends and Insights
Accelerating Construction and Infrastructure Development
Surging public-works spending across Asia-Pacific is boosting the calcium carbonate market as builders seek cost-effective mineral fillers for cement, polymer-modified concrete, architectural coatings, and sealants. Integrated producers have ramped up capacity to meet this requirement: Imerys doubled output at its Sylacauga, Alabama unit to supply construction-grade material and improve lead times for North American customers. Urban planners' push for low-carbon building materials is also raising demand for products such as ReMined, a 100% pre-consumer recycled calcium carbonate that reduces embodied carbon while maintaining strength and durability benchmarks. These sustainability-linked niches allow sellers to command higher margins even as bulk volumes grow steadily.
Expanding Plastic and Polymer Applications
Rapid advances in nano-scale grinding and surface-treatment chemistries have shifted the performance ceiling for film, masterbatch, and engineered-plastic grades. Nano-calcium carbonate enhances tensile strength, barrier properties, and thermal stability in packaging while preserving clarity, letting converters cut resin intensity by up to 5% on a weight basis. Chinese producer Hubei Micro Crystal New Materials demonstrated how sub-100 nm particles dispersed in biodegradable polymers can both toughen films and fine-tune degradation rates, directly supporting circular-economy packaging mandates. Automotive OEMs and electronics brands are increasingly specifying these functional fillers to meet lightweighting, heat-resistance, and recyclability targets.
Health Hazards Associated with Calcium Carbonate
Worker exposure to respirable calcium carbonate dust has sharpened regulatory oversight, prompting lower permissible exposure limits and more stringent containment norms in mills and downstream plants. Nanoparticle toxicology remains under study, and approvals for food or pharma applications now routinely require extensive risk assessments, which can prolong commercialization timelines and inflate compliance costs. Small producers with limited capital often struggle to install closed-loop handling and high-efficiency filtration, constraining supply flexibility.
Other drivers and restraints analyzed in the detailed report include:
- Growing Demand from the Paper and Packaging Industry
- Rising Healthcare and Pharmaceutical Usage
- Environmental and Mining Regulations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Ground calcium carbonate continues to anchor the calcium carbonate market, claiming 76.92% of 2025 demand thanks to abundant limestone deposits and low-energy milling routes. In volume-driven sectors such as basic paper, polyolefin film, and ready-mix concrete, GCC's favorable price-performance ratio remains decisive. Yet precipitated calcium carbonate is setting the pace with a 3.31% CAGR through 2031 as customers pay premiums for narrow particle-size distribution, higher brightness, and customizable surface chemistry. This shift was underscored when researchers achieved enzyme-induced precipitation using soybean urease, signaling cost-reduction paths that could widen PCC's reach.
Mature GCC producers are therefore retooling plants with classified grinding systems and dry-coating units to edge closer to PCC performance without incurring the steep capex of carbonation reactors. Meanwhile, PCC suppliers are scaling captive carbon-dioxide recovery and renewable-energy inputs to shrink their carbon footprint, an increasingly important procurement criterion for multinational customers. As these strategies converge, competitive intensity is rising, but the calcium carbonate market size for both sub-segments is projected to expand steadily, given differentiated demand profiles across construction, plastics, and life-science industries.
Complete Report Scope:
- Type
- Ground Calcium Carbonate (GCC)
- Precipitated Calcium Carbonate (PCC)
- Application
- Raw Substance for Construction Material
- Dietary Supplement
- Additive for Thermoplastics
- Filler and Pigment
- Component of Adhesives
- Desulfurization of Fuel Gas
- Neutralizing Agent in Soil
- Other Applications
- End-user Industry
- Paper
- Plastic
- Adhesives and Sealants
- Construction
- Paints and Coatings
- Pharmaceutical
- Automotive
- Agriculture
- Rubber
- Other End-user Industries
- Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Australia and New Zealand
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East
- Saudi Arabia
- United Arab Emirates
- Iran
- Iraq
- Kuwait
- Qatar
- Rest of the Middle-East
- Africa
- South Africa
- Rest of Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific dominated the calcium carbonate market with a 48.25% share in 2025 and is projected to advance at a 3.62% CAGR through 2031. China accounts for the lion's share of regional demand; Imerys operates facilities in Wuhu, Qingyang, and Yueyang to supply packaging, construction, and life-science customers. Southeast Asian economies are also adding coated-board and PVC-pipe capacity, broadening the regional demand base.
North America maintains a solid foothold owing to advanced plastics and pharmaceutical supply chains that prioritize technical grades and stringent quality control. Recent investments in Alabama and Georgia underscore the region's appetite for localized supply that cuts freight emissions and ensures rapid technical support. Europe's stringent carbon-reduction and quarry-rehabilitation rules make recycled feedstocks and energy-efficient precipitation plants critical. South America is leveraging construction booms in Brazil and Argentina alongside agribusiness growth that lifts soil-treatment consumption. The Middle East sees steady demand from petrochemical complexes and large-scale infrastructure projects, while Africa's quarrying potential remains underdeveloped but promising, particularly in Egypt, Nigeria, and South Africa. Geographic dispersion of high-grade limestone deposits will continue to influence trade flows and regional pricing, but localized precipitation units and upgraded grinding hubs are gradually trimming transport intensity across the global calcium carbonate market.
- ACCM
- GCCP Resources Limited
- Gulshan Polyols Ltd.
- Huber Engineered Materials
- Imerys
- Jordan Carbonate Company
- Manaseer Group
- Minerals Technologies Inc.
- Nigtas
- OKUTAMA KOGYO CO.,LTD.
- Omya International AG
- Provencale SA
- SaudiCarbonate
- SCHAEFER KALK GmbH & Co. KG
- Shiraishi Group
- Sibelco
- SigmaRoc Plc
- VMPC Joint Stock Company.
- Zantat Sdn. Bhd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerating Construction and Infrastructure Development
- 4.2.2 Expanding Plastic and Polymer Applications
- 4.2.3 Growing Demand from the Paper and Packaging Industry
- 4.2.4 Rising Healthcare and Pharmaceutical Usage
- 4.3 Market Restraints
- 4.3.1 Health Hazards Associated with Calcium Carbonate
- 4.3.2 Environmental and Mining Regulations
- 4.3.3 Logistics and Supply Chain Challenges
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products and Services
- 4.5.5 Degree of Competition
- 4.6 Import/Export Trade Statistics
5 Market Size and Growth Forecasts (Volume)
- 5.1 Type
- 5.1.1 Ground Calcium Carbonate (GCC)
- 5.1.2 Precipitated Calcium Carbonate (PCC)
- 5.2 Application
- 5.2.1 Raw Substance for Construction Material
- 5.2.2 Dietary Supplement
- 5.2.3 Additive for Thermoplastics
- 5.2.4 Filler and Pigment
- 5.2.5 Component of Adhesives
- 5.2.6 Desulfurization of Fuel Gas
- 5.2.7 Neutralizing Agent in Soil
- 5.2.8 Other Applications
- 5.3 End-user Industry
- 5.3.1 Paper
- 5.3.2 Plastic
- 5.3.3 Adhesives and Sealants
- 5.3.4 Construction
- 5.3.5 Paints and Coatings
- 5.3.6 Pharmaceutical
- 5.3.7 Automotive
- 5.3.8 Agriculture
- 5.3.9 Rubber
- 5.3.10 Other End-user Industries
- 5.4 Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Australia and New Zealand
- 5.4.1.7 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Iran
- 5.4.5.4 Iraq
- 5.4.5.5 Kuwait
- 5.4.5.6 Qatar
- 5.4.5.7 Rest of the Middle-East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Rest of Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 ACCM
- 6.4.2 GCCP Resources Limited
- 6.4.3 Gulshan Polyols Ltd.
- 6.4.4 Huber Engineered Materials
- 6.4.5 Imerys
- 6.4.6 Jordan Carbonate Company
- 6.4.7 Manaseer Group
- 6.4.8 Minerals Technologies Inc.
- 6.4.9 Nigtas
- 6.4.10 OKUTAMA KOGYO CO.,LTD.
- 6.4.11 Omya International AG
- 6.4.12 Provencale SA
- 6.4.13 SaudiCarbonate
- 6.4.14 SCHAEFER KALK GmbH & Co. KG
- 6.4.15 Shiraishi Group
- 6.4.16 Sibelco
- 6.4.17 SigmaRoc Plc
- 6.4.18 VMPC Joint Stock Company.
- 6.4.19 Zantat Sdn. Bhd.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment
- 7.2 Emerging Importance of Green Applications
- 7.3 Advancements in High-Performance Plastics and Polymers

 2026-2034年食品級碳酸鈣全球市場規模、佔有率、趨勢和成長分析報告
 食品級碳酸鈣市場規模、佔有率和趨勢分析報告:按類型、應用、地區和細分市場預測(2026-2033 年)
 合成碳酸鈣市場分析及預測(至2035年):依類型、產品、技術、應用、形態、材料類型、製程及最終用戶分類
 碳酸鈣市場:依類型、等級、形態、原料、純度、應用及通路分類-2026-2032年全球市場預測碳酸鈣市場規模、佔有率、成長率、全球產業分析、區域趨勢及2026-2034年預測。
 食品級碳酸鈣市場規模、佔有率和成長分析:按類型、應用、終端用戶產業和地區分類-2026-2033年產業預測
 2026-2030年全球碳酸鈣(CACO3)市場
 碳酸鈣市場:按類型、應用和地區分類活性碳酸鈣市場:依等級、形態、應用和最終用途產業分類-2026-2032年全球市場預測
 美國碳酸鈣市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)