


 |
市場調查報告書
商品編碼
2119039
品牌形象服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Brand Identity Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
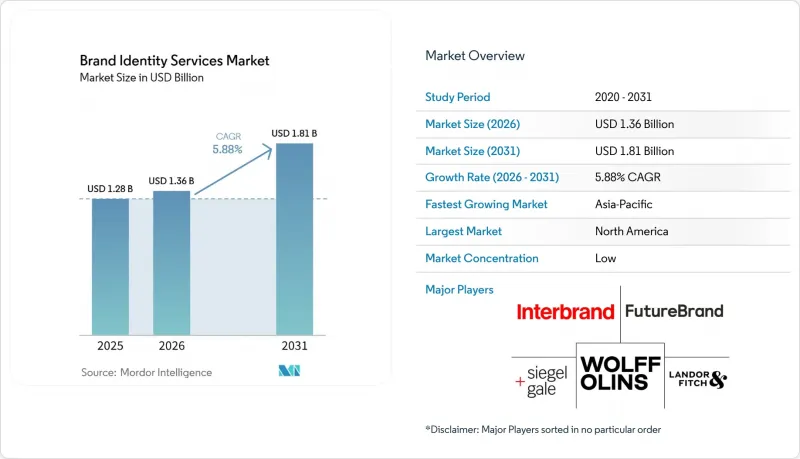
根據 Mordor Intelligence 預測,品牌識別服務市場規模將從 2025 年的 12.8 億美元成長到 2026 年的 13.6 億美元,到 2031 年將達到 18.1 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 5.88%。
本報告按服務類型(品牌策略與定位、品牌識別設計等)、組織規模(大型企業、中小企業)、終端用戶產業(藝術與文化、零售與電子商務、媒體與娛樂、醫療保健與生命科學、時尚與奢侈品等)以及地區進行細分。市場預測以美元計價。
全球品牌識別服務市場趨勢與洞察
在全通路策略中,品牌一致性至關重要。
品牌識別服務市場正受益於對跨所有管道(包括行動應用、社交視訊、零售陳列架、智慧電視和人工智慧生成內容)保持一致且易於識別的品牌系統的需求。一致性是一項至關重要的營運要求,因為客戶可能在短時間內透過多個管道與同一家公司互動。 2026年7月,可口可樂公司在200多個市場部署了統一的視覺識別系統,該系統採用了動態絲帶、Arden Square和Spencerian Script字體。此次部署表明,老字型大小企業正在更新其核心資產,以確保其在包裝、陳列裝置、零售空間和數位體驗中保持一致性。 2026年4月,Adobe推出了Brand Intelligence,該系統在行銷工作流程中提供了一個由人工智慧驅動的識別層。這表明,品牌識別交付物正在超越靜態規則的範疇。這種轉變提升了那些能夠在不損害視覺和語言一致性的前提下指導人員和自動化工具的系統的價值。
投資組合簡化推動了併購和品牌重塑的需求
併購活動催生了品牌識別服務市場的需求,因為合併後的公司需要向員工、客戶、投資者和合作夥伴展現清晰的組織架構。這些交易通常包括命名、產品組合架構、視覺和語言系統、數位資產遷移以及商標註冊。如果一家公司經營多個業務、業務遍及多個國家或擁有遺留資產庫,那麼這個過程可能需要 6 到 24 個月的時間。 Interbrand 將品牌識別符號描述為“錨點”,它們有助於在所有權變更期間維護客戶和員工的信任。 2026 年 7 月,Interbrand 巴西完成了 Arbex 的品牌識別建設,Arbex 是 Suzano 和 Kimberly-Clark 的合資企業。該項目涵蓋 9,000 名員工、22 個製造地以及 70 多個市場的營運。分拆和剝離也面臨類似的挑戰,因為缺乏清晰品牌識別的新實體可能會繼續沿用其原始母公司的傳統分類。
人工智慧和模板主導的低價位商品化
人工智慧工具和模板主導平台正對品牌識別服務市場的低階領域構成壓力。這些產品能夠快速產生標誌概念,並以低於5000美元的價格提供承包品牌識別方案。在中國的圖形商標設計市場,預計到2025年,人工智慧輔助設計工具的採用率將達到78.6%,交付時間將從數週縮短至數天。這種影響在僅包含視覺元素的工作中最為顯著,例如標誌系統、調色板和標準指南,使客戶能夠以更低的成本獲得合格的交付成果。如果通用工作室的服務僅限於這些基本交付成果,它們將面臨更直接的競爭。策略諮詢、文化詮釋、版權管理、人工智慧管治和複雜的組合系統等領域,仍然是專業服務提供者能夠保持價值的領域。
細分市場分析
到2025年,品牌實施與部署將成為品牌識別服務市場中最大的細分領域,佔據30.32%的市場。這項工作旨在重塑全球企業發展中的品牌形象,通常包括商標註冊、數位資產遷移、包裝更新、標誌更換和內部培訓。大規模企業可能需要管理遺留文件和眾多本地應用程式,這可能會延長專案週期。此細分領域的優勢在於交付成果明確且生產流程可重複。與上游策略工作相比,這些特點使得部署工作受創新不確定性的影響較小。
從2026年到2031年,品牌策略和定位預計將在品牌識別服務市場中以6.44%的複合年成長率(CAGR)實現最高成長。企業在委託視覺製作之前,越來越傾向於尋求定位簡報,因為缺乏策略方向的複雜設計可能無法支援商業性目標。 2026年3月,FutureBrand在不到一年的時間內,為Hexagon計畫推出的軟體衍生公司Octave制定了名稱、產品組合架構、語言、視覺識別和動態設計原則。該項目反映了科技客戶對整合式方法的日益重視。能夠同時主導策略和設計的服務商可以贏得更多高價值項目的佔有率。
區域分析
預計到2025年,北美將佔品牌識別服務市場收入的39.41%。該地區擁有大量科技、消費品、金融服務和醫療保健行業的客戶,這些行業都對清晰的品牌差異化有著強烈的需求。美國擁有許多財富500強企業的總部,分別位於紐約、芝加哥、舊金山和洛杉磯,同時也是多家全球顧問公司旗艦辦公室的所在地。 2026年7月,Interbrand和Clootrack聯合推出一個平台,旨在將品牌績效監測從定期評估轉變為持續分析。加拿大和墨西哥也對區域需求做出了貢獻,尤其是墨西哥的出口型製造商,他們對國際品牌體系的需求尤其迫切。
在企業轉型、老牌品牌更新以及ESG相關定位的重新評估的推動下,歐洲仍然是品牌識別服務市場的重要參與者。英國、德國和法國是該地區的核心需求國。倫敦匯集了許多全球顧問公司,例如Wolf Ohlins、Pentagram、Randall & Fitch、Coto Studio和Design Studio,這些公司為客戶提供線索開發和專案執行方面的支援。 DEUTZ AG於2026年5月發布了其全球品牌標識,以支持其從引擎製造向永續交通和能源解決方案的轉型。歐洲之翼航空也在2026年更新了企業形象設計,重新定位為歐洲的超值航空公司。
在亞太地區,品牌識別服務市場預計將在2026年至2031年間以7.51%的複合年成長率成長。印度市場潛力巨大,隨著時尚、金融科技和消費品行業獨角獸企業和D2C(直接面對消費者)業務的推出湧現,對專業品牌系統的需求日益成長。在中國,於2026年2月生效的《T/WBA 001-2025》指令確立了產品品牌策略和行銷的統一規則。 Interbrand於2026年6月將沙烏地阿拉伯電力公司重新定位為“SE Saudi Energy”,清晰地體現了這一發展方向。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 在全通路中保持品牌一致性已成為企業成功的關鍵。
- 透過併購和簡化產品組合實現品牌更新的需求。
- 持續內容創作所必需的品牌體系
- 在競爭激烈的產業中,對身分投資報酬率可衡量性的需求日益成長。
- 適用於人工智慧工作流程的機器可讀品牌規則
- AI搜尋可見性帶來更清晰的語言特徵。
- 市場限制因素
- 低階市場中人工智慧和模板主導的商品化
- 仔細審查預算和短期投資報酬率,這很難證明。
- 人工智慧產生的身份資產的版權授權風險
- 在整個傳統資產庫中,與品牌重組相關的負債發展。
- 宏觀經濟因素對市場的影響
- 產業價值鏈分析
- 科技趨勢
- 監理情勢
- 波特五力分析
第5章 市場規模與成長預測
- 報價
- 品牌策略與定位
- 品牌形象設計
- 品牌引進與發展
- 其他配送方式
- 按組織規模
- 大公司
- 小型企業
- 按最終用戶行業分類
- 藝術與文化
- 零售與電子商務
- 媒體與娛樂
- 醫療保健和生命科學
- 時尚與奢侈品
- 旅遊與飯店
- 消費品
- 其他終端用戶產業(銀行、金融服務與保險、教育、汽車、IT/電信等)
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲
- 其他亞太國家
- 中東
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 卡達
- 其他中東國家
- 非洲
- 南非
- 埃及
- 奈及利亞
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Interbrand International LLC.
- Landor & Fitch, Inc.
- Wolff Olins Ltd.
- FutureBrand Limited
- Siegel+Gale, Inc.
- Lippincott, LLC.
- Pentagram LLP
- MetaDesign GmbH
- COLLINS
- Koto Studio Ltd.
- DesignStudio Ltd.
- Prophet
- Monigle
- VSA Partners
- Matchstic LLC
- Red Antler
- Ragged Edge Ltd.
- Dragon Rouge
- Saffron Brand Consultants
- Chermayeff and Geismar and Haviv
第7章 市場機會與未來展望
According to Mordor Intelligence, the brand identity services market size is expected to increase from USD 1.28 billion in 2025 to USD 1.36 billion in 2026 and reach USD 1.81 billion by 2031, growing at a CAGR of 5.88% over 2026-2031.
This report is Segmented by Offering (Brand Strategy and Positioning, Brand Identity Design, and More), Organization Size (Large Enterprises, and Small and Medium-Sized Enterprises), End User Industry (Art and Culture, Retail and E-Commerce, Media and Entertainment, Healthcare and Life Sciences, Fashion and Luxury, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Brand Identity Services Market Trends and Insights
Omnichannel Brand Consistency Becomes Mission-Critical
The Brand Identity Services Market is benefiting as businesses need one recognizable system across mobile apps, social video, retail shelves, connected television, and AI-generated content. Consistency has become an operational need because customers may encounter the same company through several channels in a short period. In July 2026, The Coca-Cola Company launched a unified visual identity across more than 200 markets using the dynamic ribbon, Arden Square, and Spencerian script. The rollout showed how established companies are updating core assets so they work consistently across packaging, equipment, retail spaces, and digital experiences. Adobe introduced Brand Intelligence in April 2026 to provide an AI-accessible identity layer within marketing workflows, indicating that identity deliverables are moving beyond static rules. This change increases the value of systems that can guide people and automated tools without losing visual or verbal consistency.
Rebranding Demand From M&A and Portfolio Simplification
M&A activity creates demand in the Brand Identity Services Market because a merged business needs a clear structure for employees, customers, investors, and partners. These assignments commonly include naming, portfolio architecture, visual and verbal systems, digital asset migration, and trademark clearance. The work can continue for 6 to 24 months when a company has multiple businesses, operates in multiple countries, or maintains legacy asset libraries. Interbrand described identity symbols as anchors that can help maintain customer and employee confidence during ownership changes. In July 2026, Interbrand Brasil completed the Arbex identity for the Suzano-Kimberly-Clark joint venture, covering 9,000 employees, 22 manufacturing sites, and operations in more than 70 markets. Spin-offs and carve-outs face a similar challenge because a new entity without a distinct identity can remain defined by the former parent company's legacy category.
AI and Template-Led Commoditization at the Low End
AI tools and template-led platforms are putting pressure on the lower end of the Brand Identity Services Market. These products can generate logo concepts quickly and offer turnkey identity packages below USD 5,000. In China's graphic trademark design market, AI-assisted design tool penetration reached 78.6% in 2025, reducing delivery times from weeks to days. The effect is strongest in visual-only work such as logo systems, color palettes, and standard guidelines, where clients can obtain acceptable outputs at lower cost. Generalist studios face more direct price competition when their services do not extend beyond these basic deliverables. Strategic advice, cultural interpretation, rights oversight, AI governance, and complex portfolio systems remain areas where specialist providers can preserve value.
Other drivers and restraints analyzed in the detailed report include:
- Brand Systems Needed for Always-On Content Production
- Demand for Measurable Identity ROI in Crowded Categories
- Budget Scrutiny and Hard-to-Prove Short-Term ROI
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Brand implementation and rollout accounted for 30.32% of the Brand Identity Services Market share in 2025, making it the largest segment. This work activates an identity across global operations and often includes trademark registration, digital asset migration, packaging updates, signage replacement, and internal training. Large organizations must manage legacy files and many local applications, which can extend delivery schedules. The segment benefits from defined deliverables and repeatable production processes. These features can make rollout work less exposed to creative uncertainty than upstream strategic assignments.
Brand strategy and positioning are projected to record the highest CAGR of 6.44% in the Brand Identity Services Market size from 2026 to 2031. Organizations are increasingly seeking a positioning brief before commissioning visual work because design without strategic direction may appear polished but fail to support commercial goals. In March 2026, FutureBrand developed the name, portfolio architecture, verbal and visual identity, and motion principles for Hexagon's planned Octave software spin-off in less than 1 year. The assignment reflected the importance technology clients place on an integrated approach. Providers that lead both strategy and design can capture a larger portion of higher-value projects.
Complete Report Scope:
- By Offering
- Brand Strategy and Positioning
- Brand Identity Design
- Brand Implementation and Rollout
- Other Offerings
- By Organization Size
- Large Enterprises
- Small and Medium-Sized Enterprises
- By End User Industry
- Art and Culture
- Retail and E-commerce
- Media and Entertainment
- Healthcare and Life Sciences
- Fashion and Luxury
- Travel and Hospitality
- Consumer Goods
- Other End User Industries (BFSI, Education, Automotive and IT and Telecom amongst Others)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Qatar
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America accounted for 39.41% of 2025 revenue in the Brand Identity Services Market. The region benefits from a dense base of technology, consumer goods, financial services, and healthcare clients with strong differentiation needs. The United States is home to the headquarters of Fortune 500 companies in New York, Chicago, San Francisco, and Los Angeles, as well as the flagship offices of global consultancies. In July 2026, Interbrand and Clootrack launched a platform that shifts brand performance monitoring from periodic reviews to continuous analysis. Canada and Mexico also support regional demand, including export-oriented manufacturers in Mexico that need international brand systems.
Europe remains important to the Brand Identity Services Market, driven by corporate transformation, heritage-brand renewal, and ESG-related repositioning. The United Kingdom, Germany, and France form the core of regional demand. London hosts global consultancies such as Wolff Olins, Pentagram, Landor and Fitch, Koto Studio, and DesignStudio, supporting both client origination and project delivery. DEUTZ AG unveiled a global identity in May 2026 to support its move from engine manufacturing toward sustainable mobility and energy solutions. Eurowings also introduced a revised corporate design in 2026, repositioning itself as a European value airline.
Asia-Pacific is forecast to grow at a CAGR of 7.51% within the Brand Identity Services Market from 2026 to 2031. India offers substantial potential, with unicorn-stage businesses and direct-to-consumer launches in fashion, fintech, and consumer goods increasing the need for professional brand systems. China's T/WBA 001-2025, effective in February 2026, established unified rules for product brand strategy and marketing. Interbrand's June 2026 repositioning of Saudi Electricity Company as SE Saudi Energy illustrated this direction.
- Interbrand International LLC.
- Landor & Fitch, Inc.
- Wolff Olins Ltd.
- FutureBrand Limited
- Siegel+Gale, Inc.
- Lippincott, LLC.
- Pentagram LLP
- MetaDesign GmbH
- COLLINS
- Koto Studio Ltd.
- DesignStudio Ltd.
- Prophet
- Monigle
- VSA Partners
- Matchstic LLC
- Red Antler
- Ragged Edge Ltd.
- Dragon Rouge
- Saffron Brand Consultants
- Chermayeff and Geismar and Haviv
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Omnichannel Brand Consistency Becomes Mission-Critical
- 4.2.2 Rebranding Demand From MandA and Portfolio Simplification
- 4.2.3 Brand Systems Needed for Always-On Content Production
- 4.2.4 Demand for Measurable Identity ROI in Crowded Categories
- 4.2.5 Machine-Readable Brand Rules for AI Workflows
- 4.2.6 AI Search Visibility Rewards Sharper Verbal Identity
- 4.3 Market Restraints
- 4.3.1 AI and Template-Led Commoditization at the Low End
- 4.3.2 Budget Scrutiny and Hard-to-Prove Short-Term ROI
- 4.3.3 Rights Clearance Risk in AI-Generated Identity Assets
- 4.3.4 Rebrand Rollout Debt Across Legacy Asset Libraries
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value-Chain Analysis
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Offering
- 5.1.1 Brand Strategy and Positioning
- 5.1.2 Brand Identity Design
- 5.1.3 Brand Implementation and Rollout
- 5.1.4 Other Offerings
- 5.2 By Organization Size
- 5.2.1 Large Enterprises
- 5.2.2 Small and Medium-Sized Enterprises
- 5.3 By End User Industry
- 5.3.1 Art and Culture
- 5.3.2 Retail and E-commerce
- 5.3.3 Media and Entertainment
- 5.3.4 Healthcare and Life Sciences
- 5.3.5 Fashion and Luxury
- 5.3.6 Travel and Hospitality
- 5.3.7 Consumer Goods
- 5.3.8 Other End User Industries (BFSI, Education, Automotive and IT and Telecom amongst Others)
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Chile
- 5.4.2.4 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 India
- 5.4.4.4 South Korea
- 5.4.4.5 Australia
- 5.4.4.6 Rest of Asia-Pacific
- 5.4.5 Middle East
- 5.4.5.1 United Arab Emirates
- 5.4.5.2 Saudi Arabia
- 5.4.5.3 Qatar
- 5.4.5.4 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Egypt
- 5.4.6.3 Nigeria
- 5.4.6.4 Rest of Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Interbrand International LLC.
- 6.4.2 Landor & Fitch, Inc.
- 6.4.3 Wolff Olins Ltd.
- 6.4.4 FutureBrand Limited
- 6.4.5 Siegel+Gale, Inc.
- 6.4.6 Lippincott, LLC.
- 6.4.7 Pentagram LLP
- 6.4.8 MetaDesign GmbH
- 6.4.9 COLLINS
- 6.4.10 Koto Studio Ltd.
- 6.4.11 DesignStudio Ltd.
- 6.4.12 Prophet
- 6.4.13 Monigle
- 6.4.14 VSA Partners
- 6.4.15 Matchstic LLC
- 6.4.16 Red Antler
- 6.4.17 Ragged Edge Ltd.
- 6.4.18 Dragon Rouge
- 6.4.19 Saffron Brand Consultants
- 6.4.20 Chermayeff and Geismar and Haviv
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 品牌策略服務市場:全球市場預測,2026-2032年
 制服和品牌標識服裝市場規模、佔有率和趨勢分析報告:按應用、地區和細分市場預測(2026-2033 年)
 全罩杯胸罩市場規模、佔有率和成長分析:按產品類型、材質、尺寸、最終用戶、銷售管道和地區分類-2026-2033年產業預測
 2026年全球公共關係工具市場報告品牌代理服務市場:依服務類型、交付模式、定價模式、合約類型、最終用戶產業和公司規模分類-2026年至2032年全球預測全方位品牌代理商市場(依產品類型、應用、最終用戶、通路、技術、服務模式及價格範圍分類)-全球預測,2026-2032年
 公共關係工具市場報告:至2031年的趨勢、預測與競爭分析