


 |
市場調查報告書
商品編碼
2118899
OTT視訊轉碼:市佔率分析、產業趨勢與統計及成長預測(2026-2031年)Video Transcoding For OTT - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
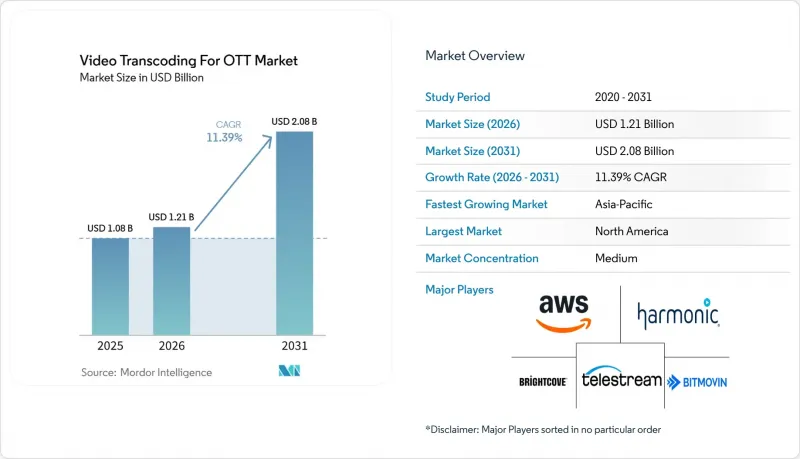
根據 Mordor Intelligence 預測,OTT影片轉碼市場規模將從 2025 年的 10.8 億美元和 2026 年的 12.1 億美元成長到 2031 年的 20.8 億美元,2026 年至 2031 年的年複合成長率(CAGR)為 11.39%。
本報告按組件(解決方案和服務)、處理類型(檔案式和視訊點播 (VOD) 轉碼、直播和線性即時轉碼)、最終用戶(OTT 和直接面對消費者 (DTC) 串流平台、廣播公司和電視網路等)以及地區進行細分。市場預測以美元 (USD) 計價。
全球OTT視訊轉碼市場趨勢及洞察
透過OTT與多螢幕技術拓展影片消費
OTT視訊轉碼支援在智慧電視、行動電話、平板電腦和連網型設備上觀看。每類設備對轉碼器的支援、解析度限制和位元率要求各不相同。因此,平台需要維護更廣泛的編碼體系,而不僅僅是增加文件數量。在影片轉碼市場,隨著聯網電視在成熟的串流媒體市場中日益普及,內容傳輸也正向4K方向發展,這增加了每個影片所需的處理量。即使市場日趨成熟,這種趨勢也不會消失,因為新的觀看設備不斷湧現,帶來了新的相容性需求。這種變化正在推動OTT市場對影片轉碼的需求,平台將使營運商能夠管理多種版本,而無需針對每種設備類別重新建立工作流程。
直播體育賽事、FAST頻道和互動串流媒體的成長
由於營運商無法依賴預處理素材或批量處理方案,直播體育賽事和FAST頻道帶來了巨大的工作負載壓力。 2026年初,主流串流平台上的體育節目年增52%,而從2024年中期到2025年2月,專門的體育FAST頻道成長了105%。因此,建立一個高彈性的基礎設施至關重要,因為它需要具備處理尖峰時段同時發生的賽事的能力,而不是僅僅應對平均流量。即使是小規模的聯賽現在也能採用FAST分發模式,這在傳統的廣播模式下是難以實現的。根據Amagi公司預測,2026年6月,在約6,500個頻道分發管道中,FAST觀看時間較去年同期成長55%,廣告曝光量也成長了53%。 OTT(Over-The-Top)市場的影片轉碼技術正受益於為多個觀眾和設備提供並行和即時渲染的需求。
高運算能力、儲存和能源需求
多格式和多編轉碼器傳輸正以遠超基礎設施成本降低的速度,推動運算能力、儲存和電力需求的成長。 NETINT 的一項調查顯示,72% 的受訪影片專業人士使用基於 GPU 的 HEVC 編碼,39% 的受訪者認為電力消耗是部署過程中的一項重大挑戰。該公司表示,其 Quadra T1U 視訊處理單元能夠以僅 17 瓦的功耗,並行處理多達 32 路 1080p 30fps 的 H.264、HEVC 和 AV1 格式的視訊串流。即使影片需求強勁,北美和歐洲資料中心的電力限制也可能限制容量擴展。這促使平台營運商積極探索部署專門設計的視訊處理單元和其他硬體,以提高編碼效率。 NETINT 的調查也發現,49% 的受訪者計劃在 2026 年評估視訊處理單元,而計畫評估 GPU 的受訪者比例為 53.6%。
細分市場分析
到2025年,解決方案將佔總收入的77.13%,其中軟體平台將是最大的組成部分。在OTT市場的影片轉碼領域,這些平台正從專用硬體設備轉向雲端部署部署的軟體,無需硬體更換即可添加格式支援。面向OTT市場的軟體主導視訊轉碼體現了與轉碼器解碼器無關的軟體的吸引力,這種軟體可以在GPU叢集、視訊處理單元和標準CPU資源上運作。透過將編碼邏輯與底層運算硬體分離,營運商在管理工作負載成本方面獲得了更多選擇。此外,還可以根據用例自訂平台基礎設施,而無需將所有作業綁定到同一設備上。大規模服務供應商可以將這種柔軟性應用於其所有現有庫,而小規模服務提供者也可以在無需大規模硬體投資的情況下採用這種靈活性。
2026年5月,Bitmovin透過AWS Marketplace收購了MUBI,後者是一家雲端視訊點播編碼客戶。 MUBI以一項支援AVC、HEVC、AV1、UHD和三次編碼的託管服務取代了其傳統的本地部署環境。此案例清楚地展示了託管平台對於需要多種轉碼器且不願維護專屬工程團隊的OTT影片轉碼服務至關重要的原因。預計到2031年,該服務市場將以11.91%的複合年成長率成長。實況活動營運尤其適合採用託管交付模式,因為並發活動可能會造成營運高峰,而內部團隊難以應對。能夠將基礎設施支援與監控和工作流程方面的專業知識相結合的服務提供者可以滿足這些需求。因此,OTT市場的影片轉碼正在轉向軟體平台與託管營運支援相結合的模式。
區域分析
預計到2025年,北美將佔全球銷售額的44.37%,成為貢獻最大的區域市場。北美在OTT視訊轉碼市場的地位得益於領先的串流平台、超大規模資料中心以及早期採用的雲端原生媒體基礎設施。 AWS Elemental、Azure Media Services和Google Cloud Transcoder在該地區擁有強大的處理能力,使營運商能夠充分利用成熟的媒體處理服務。廣播公司從C波段衛星傳輸遷移到IP工作流程,催生了對混合廣播到串流媒體處理的新需求。隨著營運商對其傳輸系統進行現代化改造,這項轉型正在整合傳輸和編碼決策。
預計到2031年,亞太地區將以11.93%的複合年成長率成長。在印度、印尼、韓國和東南亞,由於連網電視的普及和本地串流內容庫的豐富,OTT市場的影片轉碼技術正在蓬勃發展。鑑於該地區「行動優先」的觀看模式和多樣化的網路環境,高效的內容分發尤為重要。本地語言內容庫的成長也增加了平台需要管理的內容量和分發模式。 2026年7月,騰訊雲和RockStreamer宣佈建立合作夥伴關係,將在孟加拉和其他新興亞洲市場提供雲端、人工智慧、內容傳遞網路(CDN)和企業級OTT解決方案。
2025年,歐洲排名第三。向下一代廣播的轉型、OTT的發展以及對數據主權日益成長的期望,正在重塑該地區Over-The-Top市場的影片轉碼格局。 2026年,Qvest、ATEME和Scaleway宣佈建立合作夥伴關係,共同開發一個完全基於歐洲技術的完整OTT平台。在南美洲,巴西的DTV+轉型正在推動市場發展,Harmonic於2026年3月更新了其XOS高階媒體處理器以適應這項轉型。中東和非洲雖然絕對規模仍然小規模,但正透過對行動優先串流媒體和體育賽事轉播權的投資而發展壯大。對垂直影片和低頻寬傳輸的需求正在影響非洲市場使用的編碼配置。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- OTT和多螢幕技術拓展了影片觀賞方式
- 直播體育賽事、快速頻道和互動串流媒體的成長
- 雲端遷移和靈活的媒體處理需求
- 4K、8K、HDR 和身臨其境型視訊格式的普及
- 轉碼器解碼器組合多元化,涵蓋 AV1、HEVC 和 VVC。
- 基於邊緣的轉碼能夠實現低延遲和局部聚焦的傳輸。
- 市場限制因素
- 高運算能力、儲存容量和電源需求
- 整合傳統工作流程和格式相容性的複雜性。
- 轉碼器專利使用費的累積與授權不確定性
- 由於多個轉碼器導致的重複和快取效率低下
- 產業價值鏈分析
- 宏觀經濟因素對市場的影響
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按組件
- 解決方案
- 基於軟體的轉碼平台
- 硬體轉碼設備
- 服務
- 解決方案
- 透過加工方法
- 檔案式和視訊點播轉碼
- 即時線性轉碼
- 最終用戶
- OTT 和 DTC(直接面對消費者)串流平台
- 廣播公司及電視網路
- 提供OTT/IP視訊服務的付費電視和電信供應商。
- 工作室、內容擁有者、數位出版商
- 體育賽事版權擁有者和實況活動服務提供商
- 社群影片和用戶生成內容(UGC)平台
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 東南亞
- 澳洲和紐西蘭
- 其他亞太國家
- 中東
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 土耳其
- 以色列
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 埃及
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- Market Positioning Analysis
- 公司簡介
- Amazon Web Services, Inc.
- Harmonic Inc.
- Telestream, LLC
- Brightcove Inc.
- Bitmovin GmbH
- Akamai Technologies, Inc.
- Haivision Systems Inc.
- Synamedia Limited
- MediaKind Global Limited
- Imagine Communications Corp.
- Google LLC
- Tencent Holdings Limited
- Huawei Technologies Co., Ltd.
- Qencode, Inc.
- Kaltura, Inc.
- Wowza Media Systems, LLC
- ATEME SA
- Avid Technology, Inc.
- NETINT Technologies Inc.
- Vimeo, Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the OTT video transcoding market size is projected to expand from USD 1.08 billion in 2025 and USD 1.21 billion in 2026 to USD 2.08 billion by 2031, registering a CAGR of 11.39% between 2026 and 2031.
This report is Segmented by Component (Solutions, and Services), Processing Type (File-Based and Video-On-Demand Transcoding, and Live and Linear Real-Time Transcoding), End User (OTT and Direct-To-Consumer Streaming Platforms, Broadcasters and Television Networks, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Video Transcoding For OTT Market Trends and Insights
OTT and Multiscreen Video Consumption Expansion
The OTT video transcoding supports viewing across smart TVs, mobile phones, tablets, and connected devices. Each device group has different codec support, resolution limits, and bitrate needs. Platforms must therefore maintain broader encoding ladders rather than simply process more files. In video transcoding for the OTT market, connected TV use in mature streaming markets is also shifting delivery toward 4K, increasing the work required for each title. This effect does not disappear as markets mature because new viewing devices continue to create compatibility requirements. The change increases demand for video transcoding in the OTT market, enabling platforms to manage multiple renditions without requiring operators to rebuild their workflows for every device category.
Live Sports, FAST Channels, and Interactive Streaming Growth
Live sports and FAST channels create demanding workloads because operators cannot rely on pre-processed assets or batch scheduling. Sports programming on major streaming platforms increased 52% year over year in early 2026, while dedicated sports FAST channels had grown 105% between mid-2024 and February 2025. Capacity must be available for peak concurrent events, rather than average traffic, which favors elastic infrastructure. Smaller leagues can now pursue FAST distribution, which was previously less accessible under traditional broadcast economics. Amagi reported that FAST viewing hours grew 55% year over year, and ad impressions increased 53% across nearly 6,500 channel deliveries in June 2026. Video transcoding for the over-the-top (OTT) market benefits from the need for parallel, real-time renditions for multiple viewers and devices.
High Compute, Storage, and Energy Requirements
Multi-format and multi-codec delivery increases compute, storage, and power requirements faster than infrastructure costs can fall. NETINT found that 72% of surveyed video professionals used GPU-based HEVC encoding, and 39% identified power consumption as a critical deployment challenge. The company reported that its Quadra T1U video processing unit used 17 watts while supporting up to 32 parallel 1080p 30fps streams across H.264, HEVC, and AV1. Data center power constraints in North America and Europe can limit capacity expansion even when video demand remains strong. This encourages platforms to assess purpose-built video processing units and other hardware that improve encoding efficiency. NETINT also found that 49% of respondents planned to evaluate video processing units in 2026, compared with 53.6% who planned to evaluate GPUs.
Other drivers and restraints analyzed in the detailed report include:
- Cloud Migration and Elastic Media Processing Demand
- 4K, 8K, HDR, and Immersive Video Format Adoption
- Legacy Workflow Integration and Format Compatibility Complexity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solutions accounted for 77.13% of revenue in 2025, giving software-based platforms the largest component position. In the video transcoding for the OTT market, these platforms have shifted attention away from dedicated hardware appliances and toward cloud-deployable software that can add format support without a physical replacement cycle. The software-led video transcoding for the OTT market reflected the appeal of codec-agnostic software that can run across GPU clusters, video processing units, and standard CPU resources. This separation of encoding logic from underlying compute hardware gives operators more choice when managing workload costs. It also allows a platform to adjust its infrastructure by use case instead of tying every job to the same appliance. Larger providers can apply this flexibility across established libraries, while smaller services can adopt it without making a broad hardware investment.
Bitmovin signed MUBI as a cloud video-on-demand encoding client through AWS Marketplace in May 2026. MUBI replaced its legacy on-premises stack with a managed service supporting AVC, HEVC, AV1, UHD, and three-pass encoding. This case provides a clear example of why managed platforms are relevant for OTT video transcoding, services that need multiple codecs but do not want to maintain specialist engineering teams. Services are projected to expand at a CAGR of 11.91% through 2031. Live-event operations are particularly suited to managed delivery because parallel events can create operational peaks that an internal team struggles to manage. Providers that combine infrastructure support with monitoring and workflow expertise can address this need. The video transcoding for the OTT market is therefore moving toward a mix of software platforms and managed operational support.
Complete Report Scope:
- By Component
- Solutions
- Software-Based Transcoding Platforms
- Hardware Transcoding Appliances
- Services
- Solutions
- By Processing Type
- File-Based and Video-on-Demand Transcoding
- Live and Linear Real-Time Transcoding
- By End User
- OTT and Direct-to-Consumer Streaming Platforms
- Broadcasters and Television Networks
- Pay-TV and Telecom Operators with OTT/IP Video Services
- Studios, Content Owners, and Digital Publishers
- Sports Rights Holders and Live-Event Streaming Providers
- Social Video and User-Generated Content Platforms
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Southeast Asia
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Israel
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- North America
Geography Analysis
North America held 44.37% of revenue in 2025, making it the largest regional contributor. The regional position in the video transcoding for the OTT market is supported by major streaming platforms, hyperscale data centers, and early cloud-native media infrastructure. AWS Elemental, Azure Media Services, and Google Cloud Transcoder have substantial capacity in the region, giving operators access to established media-processing services. Broadcasters moving from C-band satellite distribution to IP workflows create another source of demand for hybrid broadcast-to-streaming processing. The shift brings distribution and encoding decisions together as operators modernize their delivery systems.
Asia-Pacific is projected to expand at a CAGR of 11.93% through 2031. Video transcoding for the OTT market is developing in India, Indonesia, South Korea, and Southeast Asia as connected television use and local streaming catalogs grow. The region's mobile-first viewing patterns and varied network conditions make efficient delivery particularly important. Local-language catalogs also widen the number of content and distribution profiles platforms must manage. Tencent Cloud and Rockstreamer announced a partnership in July 2026 to provide cloud, AI, content delivery network, and enterprise OTT solutions in Bangladesh and other emerging Asian markets.
Europe ranked third in 2025. Next-generation broadcast changes, OTT development, and stronger expectations around data sovereignty shape the video transcoding for the over-the-top (OTT) market in the region. Qvest, ATEME, and Scaleway announced a 2026 partnership to develop production-ready OTT platforms built entirely on European technology. South America is gaining support from Brazil's DTV+ transition, and Harmonic updated its XOS Advanced Media Processor in March 2026 to support that migration. The Middle East and Africa remain smaller in absolute value but are developing through mobile-first streaming and sports rights investment. Vertical video and low-bandwidth delivery needs are shaping the encoding configurations used in African markets.
- Amazon Web Services, Inc.
- Harmonic Inc.
- Telestream, LLC
- Brightcove Inc.
- Bitmovin GmbH
- Akamai Technologies, Inc.
- Haivision Systems Inc.
- Synamedia Limited
- MediaKind Global Limited
- Imagine Communications Corp.
- Google LLC
- Tencent Holdings Limited
- Huawei Technologies Co., Ltd.
- Qencode, Inc.
- Kaltura, Inc.
- Wowza Media Systems, LLC
- ATEME S.A.
- Avid Technology, Inc.
- NETINT Technologies Inc.
- Vimeo, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 OTT and Multiscreen Video Consumption Expansion
- 4.2.2 Growth in Live Sports, FAST Channels, and Interactive Streaming
- 4.2.3 Cloud Migration and Elastic Media Processing Demand
- 4.2.4 Adoption of 4K, 8K, HDR, and Immersive Video Formats
- 4.2.5 Codec Portfolio Diversification Across AV1, HEVC, and VVC
- 4.2.6 Edge-Based Transcoding for Low-Latency and Localized Delivery
- 4.3 Market Restraints
- 4.3.1 High Compute, Storage, and Energy Requirements
- 4.3.2 Legacy Workflow Integration and Format Compatibility Complexity
- 4.3.3 Codec Patent Royalty Stacking and Licensing Uncertainty
- 4.3.4 Multi-Codec Duplication and Cache Inefficiency
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Solutions
- 5.1.1.1 Software-Based Transcoding Platforms
- 5.1.1.2 Hardware Transcoding Appliances
- 5.1.2 Services
- 5.1.1 Solutions
- 5.2 By Processing Type
- 5.2.1 File-Based and Video-on-Demand Transcoding
- 5.2.2 Live and Linear Real-Time Transcoding
- 5.3 By End User
- 5.3.1 OTT and Direct-to-Consumer Streaming Platforms
- 5.3.2 Broadcasters and Television Networks
- 5.3.3 Pay-TV and Telecom Operators with OTT/IP Video Services
- 5.3.4 Studios, Content Owners, and Digital Publishers
- 5.3.5 Sports Rights Holders and Live-Event Streaming Providers
- 5.3.6 Social Video and User-Generated Content Platforms
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 India
- 5.4.4.3 Japan
- 5.4.4.4 South Korea
- 5.4.4.5 Southeast Asia
- 5.4.4.6 Australia and New Zealand
- 5.4.4.7 Rest of Asia-Pacific
- 5.4.5 Middle East
- 5.4.5.1 United Arab Emirates
- 5.4.5.2 Saudi Arabia
- 5.4.5.3 Turkey
- 5.4.5.4 Israel
- 5.4.5.5 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Nigeria
- 5.4.6.3 Egypt
- 5.4.6.4 Rest of Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Positioning Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Amazon Web Services, Inc.
- 6.4.2 Harmonic Inc.
- 6.4.3 Telestream, LLC
- 6.4.4 Brightcove Inc.
- 6.4.5 Bitmovin GmbH
- 6.4.6 Akamai Technologies, Inc.
- 6.4.7 Haivision Systems Inc.
- 6.4.8 Synamedia Limited
- 6.4.9 MediaKind Global Limited
- 6.4.10 Imagine Communications Corp.
- 6.4.11 Google LLC
- 6.4.12 Tencent Holdings Limited
- 6.4.13 Huawei Technologies Co., Ltd.
- 6.4.14 Qencode, Inc.
- 6.4.15 Kaltura, Inc.
- 6.4.16 Wowza Media Systems, LLC
- 6.4.17 ATEME S.A.
- 6.4.18 Avid Technology, Inc.
- 6.4.19 NETINT Technologies Inc.
- 6.4.20 Vimeo, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 全球線上影片平台市場規模、佔有率、趨勢和成長分析報告(2026-2034)Frost Radar™:面向媒體和娛樂的線上影片平台,2026 年
 線上影片平台市場-2026-2032年全球市場預測媒體與娛樂產業線上影片平台市場:2026-2032年全球市場預測
 短影片平台市場 - 全球產業規模、佔有率、趨勢、機會、預測:按類型、部署方式、最終用途、地區和競爭格局分類,2021-2031年
 線上影片平台:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 線上影片平台市場規模、佔有率、趨勢和預測:按模型類型、應用、產品類型和地區分類,2026-2034 年視訊轉碼市場:按組件、應用程式和地區分類(2026-2034 年)
 線上影片平台市場:按組件、分發方式、最終用戶產業和地區分類。
 2026年全球線上英語教師一對一平台市場報告