


 |
市場調查報告書
商品編碼
2118896
聯盟行銷服務:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Affiliate Marketing Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
聯盟行銷服務市場預計將從 2025 年的 53.7 億美元成長到 2026 年的 59.8 億美元,然後在 2031 年達到 106 億美元,2026 年至 2031 年的複合年成長率為 12.13%。
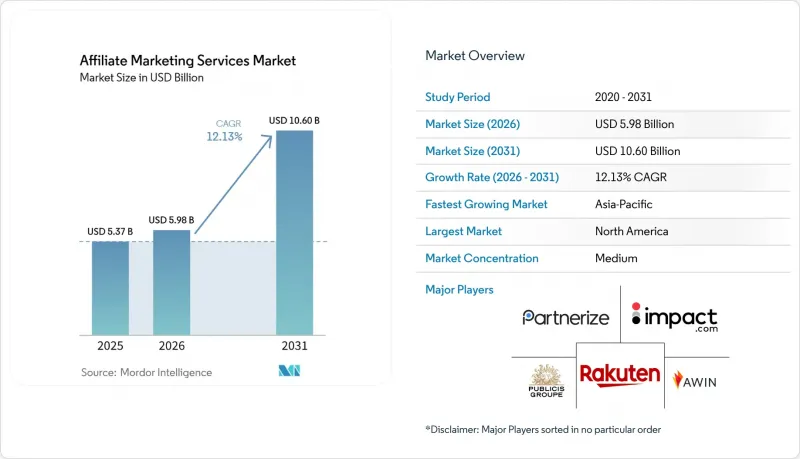
本報告按服務類型(託管聯盟計畫服務、聯盟平台和SaaS許可、合作夥伴招募和入駐服務等)、組織規模(中小企業和大型企業)、最終用戶(零售和電子商務、銀行、金融服務和保險、醫療保健和生命科學、媒體和娛樂等)以及地區進行細分。市場預測以價值(美元)表示。
全球聯盟行銷服務市場趨勢與洞察
基於績效的客戶獲取方式可以擴大預算佔有率。
效果行銷正將預算從展示廣告和付費搜尋廣告轉向聯盟行銷管道,以集中資金用於已驗證有效的行銷活動。近年來,美國的聯盟行銷支出顯著成長,推動了電子商務銷售,並帶來了高投資報酬率 (ROI)。研究表明,聯盟行銷在美國電子商務中佔據了相當大的佔有率,這表明該管道已成為線上銷售活動中不可或缺的一部分。在澳大利亞,許多受訪廣告商在上年度增加了聯盟行銷的投入,其中大多數預計該管道將對其業績產生策略性影響。企業級專案正擴大採用增量檢驗佣金結構,根據透過預留組檢驗的新客戶的貢獻來確定佣金。這種方法為廣告主提供了一個更清晰的基準,以便將聯盟行銷服務的市場支出與基於展示次數的管道進行比較,同時也避免了對即使沒有發布商貢獻也會發生的交易的佣金過高估計。
擴大電子商務和社群電商的商家群體
商家對聯盟行銷計劃的日益普及推動了電子商務和社交電商領域對聯盟行銷服務的需求。由於使用者友善的軟體平台,商家現在無需像過去那樣組建專門團隊或使用客製化工具即可輕鬆實施聯盟行銷計劃。在東南亞主要平台上,創作者主導的聯盟行銷收入已佔據相當大的佔有率。隨著TikTok Shop商品交易總額(GMV)的成長,Lazada和Shopee也加強了各自的聯盟行銷計畫。 Shopify Collabs允許商家透過現有控制面板設定費用結構並管理與創作者的關係,從而最大限度地降低前期成本。進入門檻的降低促使更多小規模商家參與其中,並帶動了聯盟行銷服務市場對設定、招募、追蹤和專案支援等方面的需求成長。尤其是在商家需要協助創作者篩選、費用設定和合作主導銷售品質監控的領域,這種需求更為旺盛。這些工具的廣泛應用將使與創作者的關係與經銷商的營運更加緊密地聯繫起來,從而更容易在常規電商流程中建立聯盟行銷計劃。
封閉式平台導致的隱私控制和歸因損失
第三方 Cookie 和瀏覽器級隱私控制的逐步淘汰正在降低聯盟行銷服務市場歸因的準確性。 Safari 的智慧型追蹤預防 (ITP) 功能縮短了 Cookie 的有效期,將某些 JavaScript 設定的 Cookie 限制在 24 小時以內。這對於保險、金融產品和零售等考慮期較長的行業來說並不適用,因為這些行業的考慮週期長達數天。谷歌的隱私沙盒機制使專案經理的預算編制更加困難,因為歸因訊號的遺失並非一次性發生,而是隨著時間的推移而逐漸分散。隨著 GDPR 的實施,廣告商如果想要在合規義務範圍內保持轉換可見性,就需要伺服器到伺服器的回傳追蹤。這項變更需要工程資源、使用者授權管理和可靠的資料共用流程,而許多中型廣告商恰恰缺乏這些資源。英國競爭與市場管理局 (CMA) 已將Google的搜尋和人工智慧產品指定為 2026 年具有戰略市場定位的平台。
細分市場分析
2025年,託管式聯盟行銷專案服務將佔聯盟行銷服務市場收入的32.62%。許多廣告主將發布商招募、合規性檢查、費用談判和績效報告等工作外包給專業機構。這種模式在金融服務和醫療保健行業尤其重要,因為這些行業需要投入大量資源進行內部管理,以應對GDPR合規、FTC揭露審計以及特定產業的KYC(了解你的客戶)義務。分析和最佳化服務預計將成為成長最快的服務類型,2026年至2031年的複合年成長率將達到13.03%。這一成長反映了歸因方式從最終點擊衡量轉向增量歸因,這要求平台能夠解讀更複雜的發布商訊號。
根據 Partnerize 的一份報告,與透過最後一次點擊追蹤相比,發布商透過人工智慧驅動的發現所產生的可衡量購買影響高出 3.84 倍。 「聯盟平台和 SaaS 授權」也在不斷擴展,因為中型廣告主正在尋求無需完全外包的自助工具。 「追蹤與歸因服務」正面臨壓力,因為伺服器端追蹤正在取代基於瀏覽器的像素整合。傳統供應商必須更新其系統,否則將面臨市場佔有率被符合隱私權保護規定的工具蠶食的風險。預計到 2025 年,全球活躍聯盟發布商的數量將達到 320 萬,比 2024 年的 270 萬增加 18.5%。這將推動聯盟行銷服務市場對招募和入職服務的需求。此外,隨著發布商層級的擴大,篩檢、關係管理和系統化的入職流程對於希望在專案發展過程中保持品質的廣告商變得越來越重要。
區域分析
到2025年,北美將佔聯盟行銷服務市場收入的37.05%。美國將在全球專案活動、發布商數量和企業支出方面佔據最大佔有率。 2024年,美國聯盟行銷支出達到136.3億美元,創造了1,130億美元的電子商務銷售額。聯盟行銷活動占美國電子商務的9.4%,這表明基於效果的合作夥伴計劃在該地區已深度滲透。企業品牌正從基於最後點擊和30天cookie的模式轉向基於伺服器端追蹤和經檢驗的新客戶獲取貢獻的佣金模式。
預計亞太地區將成為所有地區中成長最快的地區,2026年至2031年的複合年成長率將達到14.10%。印度、東南亞和澳洲正受惠於數位商務和內容創作者主導聯盟行銷模式的快速成長。 IAB澳洲的一項調查顯示,64%的受訪者預計聯盟行銷對其業務成果的重要性將日益凸顯;而Partnerize亞太區的一項調查則顯示,參與調查的品牌首席行銷長(CMO)對聯盟行銷的投資信心指數為4-5分(滿分5分)。 2026年中期,在東南亞主要平台上,內容創作者主導聯盟行銷將佔電商收入的50-70%。面對TikTok Shop的競爭,Lazada和Shopee已加強了其聯盟行銷計劃。
歐洲是第二大區域市場,而《一般資料保護規則》(GDPR) 對聯盟行銷服務的架構提出了獨特的要求。預計到 2025 年,英國的聯盟行銷總支出將達到 18 億英鎊(22.8 億美元),並產生 207 億英鎊(261 億美元)的聯盟行銷收入。南美洲、中東和非洲規模較小,但發展迅速。巴西在南美洲扮演主導角色,阿拉伯聯合大公國和沙烏地阿拉伯在中東地區也扮演重要角色。同時,南非、奈及利亞和埃及正在發展金融科技和行動優先的電子商務基礎設施。阿根廷和智利也在成長,但國際支付處理的複雜性可能會阻礙它們的擴張。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 基於效果的客戶獲取方式正在擴大其預算佔有率。
- 擴大電子商務和社群電商的商家群體
- 擴大人工智慧在合作夥伴發現和最佳化方面的應用
- 拓展金融服務、旅遊和電信業的聯盟行銷。
- 搜尋和人工智慧驅動的推薦的去中心化,增加了對多樣化績效管道的需求。
- 跨境創作者和出版商的獲利模式正在擴大合作夥伴的數量。
- 市場限制因素
- 隱私措施和封閉式平台導致的歸因損失
- 聯盟行銷詐騙、優惠券洩漏和獎勵。
- 搜尋演算法的不穩定性削弱了內容聯盟行銷的經濟可行性。
- 跨國稅務、KYC(了解你的客戶)和支付流程的複雜性正在減緩業務擴張。
- 產業價值鏈分析
- 宏觀經濟因素對市場的影響
- 監理情勢
- 技術展望
- 波特五力分析
- 歸因和佣金模型的發展趨勢
第5章 市場規模與成長預測
- 按服務類型
- 聯盟計畫管理服務
- 聯盟平台和SaaS許可
- 追蹤與歸因服務
- 合作夥伴招募和入職服務
- 費用和支付管理服務
- 詐欺偵測和合規服務
- 分析和最佳化服務
- 按組織規模
- 小型企業
- 大公司
- 按最終用戶行業分類
- 零售與電子商務
- 資訊科技/通訊
- BFSI
- 醫療保健和生命科學
- 媒體與娛樂
- 旅遊與飯店
- 製造業和工業部門
- 其他(汽車、公共部門等)
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲
- 其他亞太國家
- 中東
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 卡達
- 其他中東國家
- 非洲
- 南非
- 埃及
- 奈及利亞
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Awin
- impact Tech, Inc.(impact.com)
- Publicis Groupe SA(CJ Affiliate)
- Rakuten Group, Inc.(Rakuten Advertising)
- Partnerize
- AppDirect, Inc.(PartnerStack)
- TUNE
- Affise
- Refersion
- FlexOffers.com
- Admitad
- Quality Unit, sro(Post Affiliate Pro)
- Tradedoubler AB
- Sovrn Holdings, Inc.
- ClickBank
- Tapfiliate
- SureSwift Capital, Inc.(LeadDyno)
- Everflow
- Webgains
- eBay Inc.(eBay Partner Network)
第7章 市場機會與未來展望
According to Mordor Intelligence, the affiliate marketing services market size is expected to grow from USD 5.37 billion in 2025 to USD 5.98 billion in 2026 and is forecast to reach USD 10.60 billion by 2031 at 12.13% CAGR over 2026-2031.
This report is Segmented by Service Type (Managed Affiliate Program Services, Affiliate Platform and SaaS Licensing, Partner Recruitment and Onboarding Services, and More), Organization Size (SMEs, and Large Enterprises), End-User (Retail and E-Commerce, BFSI, Healthcare and Life Sciences, Media and Entertainment, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Affiliate Marketing Services Market Trends and Insights
Performance-Based Customer Acquisition Gains Budget Share
Performance-based marketing directs spending toward verified outcomes, which shifts budgets away from display advertising and paid search toward affiliate channels. U.S. affiliate spending increased significantly in recent years, generating substantial e-commerce sales and delivering strong returns on investment. The same study reported that affiliate activity represented a meaningful share of U.S. e-commerce, demonstrating that the channel has become an established part of online sales activity. In Australia, many surveyed advertisers increased affiliate investment during the prior year, and most expected the channel to gain strategic importance for business results. Enterprise programs increasingly use incrementality-tested commission structures that link payouts to verified new-customer contribution through holdout groups. This approach gives advertisers a clearer basis for comparing Affiliate marketing services market spending with impression-based channels, while reducing credit for transactions that would have occurred without a publisher's contribution.
Expansion of E-commerce and Social Commerce Merchant Bases
The growth of merchant adoption is expanding demand for the Affiliate marketing services market across e-commerce and social commerce. Accessible software platforms let merchants introduce affiliate programs without the dedicated teams and bespoke tools that were once required. Creator-led affiliate commerce accounted for a substantial share of e-commerce revenue on major Southeast Asian platforms, which encouraged Lazada and Shopee to strengthen their programs as TikTok Shop gained gross merchandise value. Shopify Collabs lets merchants establish commission structures and manage creator relationships through an existing dashboard with minimal upfront cost. These lower entry barriers broaden participation by smaller merchants and extend the Affiliate marketing services market's need for setup, recruitment, tracking, and program support, particularly where merchants need help selecting creators, setting commissions, and monitoring the quality of partner-led sales. The spread of these tools also connects creator relationships more directly with merchant operations, making affiliate programs easier to establish within ordinary e-commerce workflows.
Attribution Loss From Privacy Controls and Closed Platforms
Third-party cookie deprecation and browser-level privacy controls reduce the accuracy of attribution across the Affiliate marketing services market. Safari Intelligent Tracking Prevention has shortened cookie lifespans, with certain JavaScript-set cookies limited to 24 hours, which does not fit multiday consideration cycles in insurance, financial products, and higher-consideration retail. Google's Privacy Sandbox rollout distributes attribution signal loss over time rather than through a single cutoff, making budget decisions more difficult for program managers. GDPR enforcement requires server-to-server postback tracking when advertisers need to preserve conversion visibility within compliance obligations. This change requires engineering capacity, consent controls, and reliable data sharing processes that many mid-market advertisers do not have. The United Kingdom's Competition and Markets Authority designated Google as a platform with strategic market status for its search and AI products in 2026.
Other drivers and restraints analyzed in the detailed report include:
- Rising Use of AI-Enabled Partner Discovery and Optimization
- Growth of Affiliate Use in Financial Services, Travel, and Telecom
- Affiliate Fraud, Coupon Leakage, and Incentive Misalignment
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Managed Affiliate Program Services accounted for 32.62% of the Affiliate marketing services market revenue in 2025. Many advertisers outsource publisher recruitment, compliance reviews, commission negotiation, and performance reporting to specialized agencies. The model is especially relevant in financial services and healthcare, where GDPR alignment, FTC disclosure audits, and sector-specific KYC obligations make internal management resource-intensive. Analytics and Optimization Services is projected to be the fastest-growing service type, with a 13.03% CAGR from 2026 to 2031. The growth reflects the shift from last-click measurement to incrementality-based attribution, which requires platforms to interpret more complex publisher signals.
Partnerize reported that publishers generated 3.84 times more measurable purchase influence through AI-mediated discovery than through last-click records. Affiliate Platform and SaaS Licensing is also expanding as mid-market advertisers seek self-service tools without full outsourcing. Tracking and Attribution Services face pressure as server-side tracking replaces browser-based pixel integrations. Legacy providers must update their systems or risk losing ground to privacy-compliant tools. The global publisher base reached 3.2 million active affiliates in 2025, up 18.5% from 2.7 million in 2024, supporting Affiliate marketing services market demand for recruitment and onboarding services. The wider publisher pool also makes screening, relationship management, and structured onboarding more important for advertisers that want to maintain quality as their programs grow.
Complete Report Scope:
- By Service Type
- Managed Affiliate Program Services
- Affiliate Platform and SaaS Licensing
- Tracking and Attribution Services
- Partner Recruitment and Onboarding Services
- Commission and Payout Management Services
- Fraud Detection and Compliance Services
- Analytics and Optimization Services
- By Organization Size
- Small and Medium-sized Enterprises
- Large Enterprises
- By End-User Industry
- Retail and E-commerce
- IT and Telecommunications
- BFSI
- Healthcare and Life Sciences
- Media and Entertainment
- Travel and Hospitality
- Manufacturing and Industrials
- Others (Automotive, Public Sector, Others)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Qatar
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America held 37.05% of the affiliate marketing services market revenue in 2025. The United States concentrated the largest share of global program activity, publisher volume, and enterprise spending. U.S. affiliate spending reached USD 13.63 billion in 2024 and generated USD 113 billion in e-commerce sales. Affiliate activity represented 9.4% of U.S. e-commerce, which shows the region's deep adoption of performance-led partner programs. Enterprise brands are moving from last-click 30-day cookie models toward server-side tracking and commissions based on verified new-customer contribution.
Asia-Pacific is projected to record the highest regional CAGR at 14.10% from 2026 to 2031. India, Southeast Asia, and Australia are benefiting from faster digital commerce growth and creator-led affiliate models. IAB Australia found that 64% of respondents expected affiliate marketing to become more important to their business outcomes, while the Partnerize APAC board recorded CMO-level investment conviction of 4-5 out of 5 among participating brands. Creator-led affiliate commerce represented 50% to 70% of e-commerce revenue on major Southeast Asian platforms in mid-2026. Lazada and Shopee strengthened their affiliate programs as they competed with TikTok Shop.
Europe is the second-largest geographic segment, and GDPR creates distinct requirements for the Affiliate marketing services market architecture. U.K. affiliate spending totaled GBP 1.8 billion, or USD 2.28 billion, in 2025 and generated GBP 20.7 billion, or USD 26.1 billion, in attributed revenue. South America, the Middle East, and Africa are smaller but developing regions, with Brazil leading South America, the United Arab Emirates and Saudi Arabia leading Middle Eastern activity, and South Africa, Nigeria, and Egypt building fintech and mobile-first e-commerce infrastructure. Argentina and Chile are also growing, although international payout complexity can slow expansion.
- Awin
- impact Tech, Inc. (impact.com)
- Publicis Groupe S.A. (CJ Affiliate)
- Rakuten Group, Inc. (Rakuten Advertising)
- Partnerize
- AppDirect, Inc. (PartnerStack)
- TUNE
- Affise
- Refersion
- FlexOffers.com
- Admitad
- Quality Unit, s.r.o. (Post Affiliate Pro)
- Tradedoubler AB
- Sovrn Holdings, Inc.
- ClickBank
- Tapfiliate
- SureSwift Capital, Inc. (LeadDyno)
- Everflow
- Webgains
- eBay Inc. (eBay Partner Network)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Performance-Based Customer Acquisition Gains Budget Share
- 4.2.2 Expansion of E-commerce and Social Commerce Merchant Bases
- 4.2.3 Rising Use of AI-Enabled Partner Discovery and Optimization
- 4.2.4 Growth of Affiliate Use in Financial Services, Travel, and Telecom
- 4.2.5 Search and AI Referral Fragmentation Increases Need for Diversified Performance Channels
- 4.2.6 Cross-Border Creator and Publisher Monetization Expands Partner Supply
- 4.3 Market Restraints
- 4.3.1 Attribution Loss from Privacy Controls and Closed Platforms
- 4.3.2 Affiliate Fraud, Coupon Leakage, and Incentive Misalignment
- 4.3.3 Search Algorithm Volatility Weakens Content Affiliate Economics
- 4.3.4 Cross-Border Tax, KYC, and Payout Complexity Slows Expansion
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Affiliates and Publishers
- 4.8.3 Bargaining Power of Advertisers and Brands
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
- 4.9 Attribution and Commission Model Trends
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Managed Affiliate Program Services
- 5.1.2 Affiliate Platform and SaaS Licensing
- 5.1.3 Tracking and Attribution Services
- 5.1.4 Partner Recruitment and Onboarding Services
- 5.1.5 Commission and Payout Management Services
- 5.1.6 Fraud Detection and Compliance Services
- 5.1.7 Analytics and Optimization Services
- 5.2 By Organization Size
- 5.2.1 Small and Medium-sized Enterprises
- 5.2.2 Large Enterprises
- 5.3 By End-User Industry
- 5.3.1 Retail and E-commerce
- 5.3.2 IT and Telecommunications
- 5.3.3 BFSI
- 5.3.4 Healthcare and Life Sciences
- 5.3.5 Media and Entertainment
- 5.3.6 Travel and Hospitality
- 5.3.7 Manufacturing and Industrials
- 5.3.8 Others (Automotive, Public Sector, Others)
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Chile
- 5.4.2.4 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 India
- 5.4.4.4 South Korea
- 5.4.4.5 Australia
- 5.4.4.6 Rest of Asia-Pacific
- 5.4.5 Middle East
- 5.4.5.1 United Arab Emirates
- 5.4.5.2 Saudi Arabia
- 5.4.5.3 Qatar
- 5.4.5.4 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Egypt
- 5.4.6.3 Nigeria
- 5.4.6.4 Rest of Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Awin
- 6.4.2 impact Tech, Inc. (impact.com)
- 6.4.3 Publicis Groupe S.A. (CJ Affiliate)
- 6.4.4 Rakuten Group, Inc. (Rakuten Advertising)
- 6.4.5 Partnerize
- 6.4.6 AppDirect, Inc. (PartnerStack)
- 6.4.7 TUNE
- 6.4.8 Affise
- 6.4.9 Refersion
- 6.4.10 FlexOffers.com
- 6.4.11 Admitad
- 6.4.12 Quality Unit, s.r.o. (Post Affiliate Pro)
- 6.4.13 Tradedoubler AB
- 6.4.14 Sovrn Holdings, Inc.
- 6.4.15 ClickBank
- 6.4.16 Tapfiliate
- 6.4.17 SureSwift Capital, Inc. (LeadDyno)
- 6.4.18 Everflow
- 6.4.19 Webgains
- 6.4.20 eBay Inc. (eBay Partner Network)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 聯盟行銷代理服務市場:全球市場預測,2026-2032年
 聯盟行銷軟體:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 聯盟行銷市場規模、佔有率和成長分析:按平台類型、補償模式、聯盟類型、廣告主類型、產業、實施模式和地區分類-2026-2033年產業預測
 全球聯盟行銷軟體市場規模、佔有率、趨勢和成長分析報告(2026-2034)聯盟行銷平台市場:依通路類型、經營模式、部署方式、組織規模與產業分類-2026-2032年全球市場預測
 2026年全球聯盟行銷軟體市場報告2026年全球聯盟行銷追蹤軟體市場報告2026年全球聯盟行銷創作者網路市場報告
 聯盟行銷平台市場規模、佔有率和趨勢分析報告:按定價模式、應用、最終用途、地區和細分市場預測(2026-2033 年)聯盟行銷解決方案市場按產品類型、發布商類型、部署模式、應用和最終用戶行業分類 - 全球預測,2026-2032 年