


 |
市場調查報告書
商品編碼
2117217
離心式鼓風機:市佔率分析、產業趨勢與統計、成長預測(2026-2031)Centrifugal Blowers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
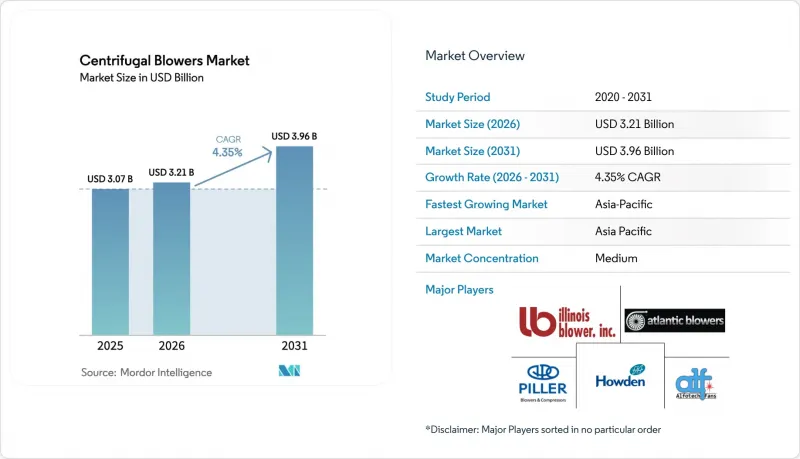
據 Mordor Intelligence 稱,離心式鼓風機市場預計到 2026 年價值 32.1 億美元,高於 2025 年的 30.7 億美元,預計到 2031 年將達到 39.6 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 4.35%。
本報告按壓力(高壓、中壓、低壓)、級數(單級、多級、高速渦輪等)、驅動系統(直驅、皮帶驅動、整合變頻驅動等)、終端用戶行業(採礦、水泥、紙漿和造紙、建築、鋼鐵、化工和石化等)以及地區進行細分。市場預測以美元(USD)為單位。
全球離心式鼓風機市場趨勢及分析
能源效率法規和設備升級
加州第20號法規於2024年4月實施,規定風機能效指數( 冷暖氣空調 )閾值為1.00,鼓勵工業設施業主以變速離心式鼓風機機組取代傳統風扇。聯合愛迪生公司每年為每個合格的暖通空調(HVAC)升級帳戶提供高達100萬美元的補貼,進一步縮短了投資回收期。儘管美國能源局已於2025年1月撤銷了聯邦標準,但各州法規和歐盟生態設計要求仍在持續推動全球營運商轉向高效葉輪-馬達組合。由於業主要求根據歷史數據和遠端合規報告來評估性能,擁有工廠預裝驅動裝置和預測分析能力的供應商正在贏得訂單。這些發展趨勢正在推動離心式鼓風機市場預期的成長。
擴大全球污水處理能力
2022年,全球整體2,680億立方公尺的污水中僅有58%得到安全處理,凸顯了污水處理設施擴建的迫切需求。在南灣污水處理廠,一項耗資6億美元的計畫強制採用無油高效曝氣鼓風機,使其處理能力加倍,達到每日5000萬加侖(gpd)。 2024會計年度,美國清潔水戰略資源基金(水質淨化基金)撥款8.512億美元,飲用水戰略資源基金提供4.944億美元,支持了數百個市政計畫的競標。蘇爾壽公司的HST渦輪壓縮機在英國德比的一家污水處理廠實現了34%的節能效果,這解釋了為什麼公共產業選擇更換而非維修老舊的羅茨鼓風機。處理能力的提升和節能目標的共同作用,推動市場成長曲線上升了0.9個百分點。
高速渦輪鼓風機的高購買成本和維護成本
磁浮渦輪機的價格遠高於多級和螺桿式渦輪機。阿特拉斯·科普柯2025年第一季財報顯示,由於預算壓力巨大,大型壓縮機的訂單成長乏力。高速轉子的現場支援需要專用診斷設備,而許多區域性OEM合作夥伴缺乏此類設備。根據畢馬威的產業分析,流程資產的EV/2024E EBITDA倍數為15.6倍,而這部分溢價最終會轉嫁給終端用戶。這一成本障礙正在對離心式鼓風機市場產生負面影響。
細分市場分析
2025年,高壓設備將佔離心式鼓風機市場42.35%的佔有率,預計到2031年將以4.71%的年均成長率成長。在氣動輸送、催化劑再生和地下通風等設備中,壓力穩定性至關重要,因此採用雙相鋼外殼和精密加工葉輪可以提高獲利能力。包括Epiroc客戶在內的礦業營運商正在部署依靠穩定氣流來清除粉塵和甲烷氣體積聚的自動化系統。
中壓離心式鼓風機的市場規模依然可觀,這主要得益於一般製造業、水泥窯和生質鍋爐等對可靠氣流的需求,這些應用對壓力要求並不高。低壓鼓風機仍廣泛應用於暖通空調和簡單的燃燒空氣供應系統,但由於業主採用更有效率的軸流式鼓風機,其需求有所下降。氫氣和沼氣專案正在加速對耐脆化的高壓不銹鋼或鎳合金鼓風機的需求,即使不同壓力等級的銷售量維修變化,也能改善收入結構。
多級配置的離心式鼓風機以其穩健的性能和易於檢修的特點,預計到2025年將佔離心式鼓風機市場36.62%的佔有率。使用者青睞轉速低於4000轉/分的機型,因為這種轉速便於現場平衡和軸承更換。然而,由於磁力軸承葉輪在高精度終端應用的廣泛應用,高速渦輪機組的市佔率正以5.28%的複合年成長率迅速成長。這些無油機組正被應用於大型污水處理廠,以降低能源成本並避免潤滑油浪費。
雖然單級懸臂式葉輪在低壓暖通空調應用中仍佔據主導地位,但在安裝空間有限且排氣壓力介於多級和渦輪式葉輪性能範圍之間的場合,整合齒輪式葉輪則更受歡迎。原始設備製造商 (OEM) 正在所有配置中整合雲端感測器,從而實現運作對比,並幫助買家選擇最佳的生命週期成本曲線。隨著預測分析量化成本節約,預計離心式鼓風機的市佔率將逐漸向能夠維持性能保證的渦輪式設計轉移。
區域分析
預計到2025年,亞太地區將佔離心鼓風機市場47.55%的佔有率,並預計到2031年將維持4.47%的年均成長率。印度石化產能從2,962萬噸成長至4,600萬噸,推動了高壓製程對空氣的持續需求。中國煉油廠的擴建以及東南亞特種化學品計畫的推進,提升了該地區的累積訂單。馬來西亞的化工產業藍圖和稅收優惠政策吸引了全球聚烯生產商,這些生產商需要用於漿料循環反應器的耐腐蝕鼓風機。古吉拉突邦和山東省的本地鑄造產業叢集透過縮短前置作業時間和控制運輸成本,維持了具有競爭力的現貨價格。
北美市場雖已成熟,但仍充滿機會。市政部門的需求仍然強勁,這主要得益於諸如南灣污水處理廠維修等項目以及其他由州循環基金(SRF)資助的類似項目。加州第20號法規和紐約州的公共產業獎勵正在加速用變速驅動(VSD)裝置取代恆速風機。透過《基礎設施投資與就業法案》資金籌措的氫能中心需要用於電解槽的無油鼓風機,這為未來十年帶來了大量訂單。
在歐洲,預計將保持穩定成長,但會受到政策的影響。受廢水處理法規和煉油廠檢修的推動,蘇爾壽公司2024年在歐洲、中東和非洲地區的訂單量增加了15.6%。耐壓無油空氣對於PEM燃料電池和鹼性燃料電池堆至關重要,以實現歐盟到2040年生產3,400萬噸氫氣的目標。在中東,隨著阿布達比國家石油公司(ADNOC)和沙烏地阿美公司將業務轉向氨和化學產品,訂單進一步成長。這些項目需要在空氣分離、硫回收和硝酸鹽循環製程的每個階段都配備專用的鼓風機系統。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 能源效率法規和維修工程
- 擴大全球污水處理能力
- 擴大亞太地區化工和石化產業的產能。
- 沼氣和氫氣注入專案需要耐腐蝕鼓風機。
- 用於預測性維護的OEM整合式工業物聯網鼓風機組件
- 旨在降低都市區噪音的暖通空調維修獎勵
- 市場限制因素
- 高速渦輪鼓風機的高購買成本和維護成本
- 透過替代鼓風機技術展開競爭
- 重要合金的價格波動
- 磁軸承維修技術人員短缺
- 產業生態系分析
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 壓力
- 高壓
- 中壓
- 低壓
- 按階段/配置
- 單級
- 多階段
- 高速渦輪
- 整合齒輪類型
- 透過驅動系統
- 直驅
- 皮帶傳動
- 整合式VSD驅動器
- 磁浮驅動
- 按最終用途行業分類
- 礦業
- 水泥
- 紙漿和造紙
- 建造
- 鋼
- 化工/石油化工
- 發電
- 供水和廢水處理
- 食品/飲料
- 暖通空調和商業建築
- 其他行業
- 按地區
- 北美洲
- 美國
- 加拿大
- 南美洲
- 巴西
- 阿根廷
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 俄羅斯
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- ASEAN
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 非洲
- 南非
- 奈及利亞
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Atlas Copco AB
- Howden Group
- Ingersoll Rand Inc.(Gardner Denver)
- Kaeser Kompressoren SE
- Aerzen Maschinenfabrik GmbH
- Sulzer Ltd.
- EBARA Corp.
- Piller Blowers and Compressors
- Boldrocchi Group
- Aeromeccanica Stranich SpA
- Illinois Blower Inc.
- Spencer Turbine Company
- Continental Blower LLC
- Atlantic Blowers LLC
- Alfotech Fans
- Aerotek Equipment
- Lontra Ltd.
- Xylem Inc.(Flygt)
- Tuthill Corp.
- Multi-Wing Group
第7章 市場機會與未來展望
According to Mordor Intelligence, the centrifugal blowers market size in 2026 is estimated at USD 3.21 billion, growing from 2025 value of USD 3.07 billion with 2031 projections showing USD 3.96 billion, growing at 4.35% CAGR over 2026-2031.
This report is Segmented by Pressure (High Pressure, Medium Pressure, and Low Pressure), Stage (Single-Stage, Multistage, High-Speed Turbo and More), Drive Type (Direct Drive, Belt Drive, Integrated VSD Drive, and More), End-Use Industry (Mining, Cement, Pulp and Paper, Construction, Steel, Chemicals and Petrochemicals, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Centrifugal Blowers Market Trends and Insights
Energy-efficiency regulations and retrofits
California's Title 20 rules that took effect in April 2024 set a 1.00 Fan Energy Index threshold, prompting industrial owners to swap legacy fans for variable-speed centrifugal packages. Con Edison pays up to USD 1 million per account each year toward qualified HVAC upgrades, further compressing payback periods. Although the U.S. Department of Energy withdrew a federal standard in January 2025, state codes and EU Ecodesign requirements continue to push global operators toward high-efficiency impeller and motor combinations. Suppliers with factory-integrated drives and predictive analytics win bids because owners want documented performance and remote compliance reporting. These moves adds to the projected growth for the centrifugal blowers market.
Expansion of global wastewater treatment capacity
Only 58% of the world's 268 billion m3 of wastewater received safe treatment in 2022, creating an urgent build-out agenda. The South Bay plant is doubling throughput to 50 million gpd under a USD 600 million program that specifies oil-free high-efficiency aeration blowers. U.S. Clean Water SRF allotments reached USD 851.2 million in fiscal 2024, while the Drinking Water SRF provided USD 494.4 million, underwriting hundreds of municipal tenders. Sulzer's HST turbocompressors showed 34% energy savings at a Derby plant in the U.K., demonstrating why utilities upgrade instead of repairing dated roots blowers. Capacity growth combined with energy-reduction targets adds 0.9 percentage points to the market growth curve.
High capital and maintenance cost of high-speed turbo blowers
Magnetic-bearing turbo models list well above multistage or rotary-screw alternatives. Atlas Copco's Q1 2025 update showed softness in large compressor bookings where budget pressure is acute.Field support for high-speed rotors requires specialized diagnostic rigs that many regional OEM partners lack. KPMG's sector review cites EV/2024E EBITDA multiples of 15.6X for process-flow assets, a premium that eventually trickles down to end-user costs. This cost hurdle adversaly impacts the centrifugal blowers market.
Other drivers and restraints analyzed in the detailed report include:
- Chemical and petrochemical capacity build-out in Asia-Pacific
- Biogas and hydrogen blending demand
- Competition from alternative blower technologies
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
High-pressure machines held 42.35% share of the centrifugal blowers market in 2025 and are forecast to grow 4.71% annually through 2031. Plants handling pneumatic transport, catalyst regeneration and underground ventilation prioritize pressure stability, which supports higher margins on duplex-steel casings and precision-machined impellers. Mining operators, including Epiroc customers, add automation that relies on stable airflow to clear dust and methane pockets.
The centrifugal blowers market size for medium-pressure units remains sizeable as general manufacturing, cement kilns and biomass boilers require dependable airflow without extreme pressure levels. Low-pressure models continue to serve HVAC and simple combustion air but face retrofit losses as owners adopt high-efficiency axial designs. Hydrogen-ready and biogas projects accelerate demand for high-pressure stainless or nickel-alloy blowers that resist embrittlement, improving the revenue mix even as volumes shift among pressure classes.
Multistage configurations delivered 36.62% of centrifugal blowers market size in 2025 by offering rugged performance and easy overhaul. Operators appreciate rotational speeds below 4,000 rpm that allow field balancing and straightforward bearing swaps. However, high-speed turbo packages are gaining at a 5.28% CAGR owing to magnetic-bearing impellers finding application in high precision edn-use application. Utility-scale wastewater plants adopt these oil-free units to cut energy bills and avoid lube-oil disposal.
Single-stage overhung wheels still dominate low-pressure HVAC jobs, while integrally-geared models find favor where floor space is tight and discharge pressure falls between multistage and turbo capabilities. OEMs integrate cloud sensors across all configurations, enabling runtime comparisons that guide buyers toward the optimum life-cycle-cost curve. As predictive analytics quantify savings, centrifugal blowers market share is expected to tilt gradually toward turbo designs that sustain performance guarantees.
Complete Report Scope:
- By Pressure
- High Pressure
- Medium Pressure
- Low Pressure
- By Stage/Configuration
- Single-Stage
- Multistage
- High-Speed Turbo
- Integrally Geared
- By Drive Type
- Direct Drive
- Belt Drive
- Integrated VSD Drive
- Magnetic-Bearing Drive
- By End-use Industry
- Mining
- Cement
- Pulp and Paper
- Construction
- Steel
- Chemicals and Petrochemicals
- Power Generation
- Water and Wastewater Treatment
- Food and Beverage
- HVAC and Commercial Buildings
- Other Industries
- By Geography
- North America
- United States
- Canada
- South America
- Brazil
- Argentina
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Africa
- South Africa
- Nigeria
- Middle East
- North America
Geography Analysis
Asia-Pacific held 47.55% of centrifugal blowers market share in 2025 and is forecast to grow 4.47% annually to 2031. India's petrochemical capacity expansion from 29.62 million tons to 46 million tons drives continuous bids for high-pressure process air. Chinese refinery additions and Southeast Asian specialty-chemicals projects bolster regional order books. Malaysia's chemicals roadmap and tax incentives attract global polyolefin players that need corrosion-resistant blowers for slurry-loop reactors. Local casting clusters in Gujarat and Shandong shorten lead times and cushion freight costs, sustaining competitive landed pricing.
North America remains a mature but opportunity-rich territory. The South Bay wastewater upgrade and similar SRF-funded projects keep municipal demand steady. California's Title 20 and New York utility incentives accelerate replacement of fixed-speed fans with VSD units. Hydrogen hubs financed through the Infrastructure Investment and Jobs Act require oil-free blowers for electrolyzers, opening a pipeline of orders that extends through the decade.
Europe delivers consistent but policy-linked growth. Sulzer recorded 15.6% order uptick in Europe, the Middle East and Africa during 2024 driven by wastewater mandates and refinery turnarounds. The bloc's 34 million-tonne hydrogen goal by 2040 necessitates pressure-stable, oil-free air for PEM and alkaline stacks. The Middle East supplements volumes as ADNOC and Saudi Aramco shift toward ammonia and chemicals, each requiring dedicated blower trains for air separation, sulfur recovery and nitric-acid loops.
- Atlas Copco AB
- Howden Group
- Ingersoll Rand Inc. (Gardner Denver)
- Kaeser Kompressoren SE
- Aerzen Maschinenfabrik GmbH
- Sulzer Ltd.
- EBARA Corp.
- Piller Blowers and Compressors
- Boldrocchi Group
- Aeromeccanica Stranich SpA
- Illinois Blower Inc.
- Spencer Turbine Company
- Continental Blower LLC
- Atlantic Blowers LLC
- Alfotech Fans
- Aerotek Equipment
- Lontra Ltd.
- Xylem Inc. (Flygt)
- Tuthill Corp.
- Multi-Wing Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Energy-efficiency regulations and retrofits
- 4.2.2 Expansion of global wastewater treatment capacity
- 4.2.3 Chemical and petrochemical capacity build-out in Asia-Pacific
- 4.2.4 Biogas and hydrogen blending projects need corrosion-resistant blowers
- 4.2.5 OEM-integrated IIoT blower packages for predictive maintenance
- 4.2.6 Urban low-noise incentives for HVAC upgrades
- 4.3 Market Restraints
- 4.3.1 High capital and maintenance cost of high-speed turbo blowers
- 4.3.2 Competition from alternative blower technologies
- 4.3.3 Critical-alloy price volatility
- 4.3.4 Shortage of magnetic-bearing service technicians
- 4.4 Industry Ecosystem Analysis
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Pressure
- 5.1.1 High Pressure
- 5.1.2 Medium Pressure
- 5.1.3 Low Pressure
- 5.2 By Stage/Configuration
- 5.2.1 Single-Stage
- 5.2.2 Multistage
- 5.2.3 High-Speed Turbo
- 5.2.4 Integrally Geared
- 5.3 By Drive Type
- 5.3.1 Direct Drive
- 5.3.2 Belt Drive
- 5.3.3 Integrated VSD Drive
- 5.3.4 Magnetic-Bearing Drive
- 5.4 By End-use Industry
- 5.4.1 Mining
- 5.4.2 Cement
- 5.4.3 Pulp and Paper
- 5.4.4 Construction
- 5.4.5 Steel
- 5.4.6 Chemicals and Petrochemicals
- 5.4.7 Power Generation
- 5.4.8 Water and Wastewater Treatment
- 5.4.9 Food and Beverage
- 5.4.10 HVAC and Commercial Buildings
- 5.4.11 Other Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Russia
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 ASEAN
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Atlas Copco AB
- 6.4.2 Howden Group
- 6.4.3 Ingersoll Rand Inc. (Gardner Denver)
- 6.4.4 Kaeser Kompressoren SE
- 6.4.5 Aerzen Maschinenfabrik GmbH
- 6.4.6 Sulzer Ltd.
- 6.4.7 EBARA Corp.
- 6.4.8 Piller Blowers and Compressors
- 6.4.9 Boldrocchi Group
- 6.4.10 Aeromeccanica Stranich SpA
- 6.4.11 Illinois Blower Inc.
- 6.4.12 Spencer Turbine Company
- 6.4.13 Continental Blower LLC
- 6.4.14 Atlantic Blowers LLC
- 6.4.15 Alfotech Fans
- 6.4.16 Aerotek Equipment
- 6.4.17 Lontra Ltd.
- 6.4.18 Xylem Inc. (Flygt)
- 6.4.19 Tuthill Corp.
- 6.4.20 Multi-Wing Group
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 離心式鼓風機市場-2026-2032年全球市場預測
 全球離心式鼓風機市場:市場規模、佔有率、趨勢和成長分析(2026-2034)
 離心式鼓風機市場:市場規模、佔有率和趨勢分析(按最終用途、壓力和地區分類),細分市場預測(2026-2033 年)
 離心式鼓風機市場報告:按壓力、最終用戶和地區分類(2026-2034 年)小型離心風機市場:依氣流方向、葉輪設計、驅動系統、安裝方式、材料、壓力範圍及應用分類,全球預測,2026-2032年超高壓離心風機市場:全球預測(2026-2032 年),按風機類型、壓力範圍、驅動系統、材質、最終用戶和銷售管道
 離心式鼓風機市場規模、佔有率和成長分析(按類型、驅動機構、壓力、應用、分銷管道和地區分類)—2026-2033年產業預測
 離心式呼吸器供氣設備:全球市場佔有率和排名、總收入和需求預測(2025-2031 年)
 離心鼓風機市場機會、成長動力、產業趨勢分析及 2025 - 2034 年預測