


 |
市場調查報告書
商品編碼
2117209
中東聚乙烯市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Middle East Polyethylene - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年中東聚乙烯市場價值為 132.3 億美元,預計到 2031 年將達到 167.9 億美元,而 2026 年為 137.7 億美元,預測期(2026-2031 年)的複合年成長率為 4.06%。
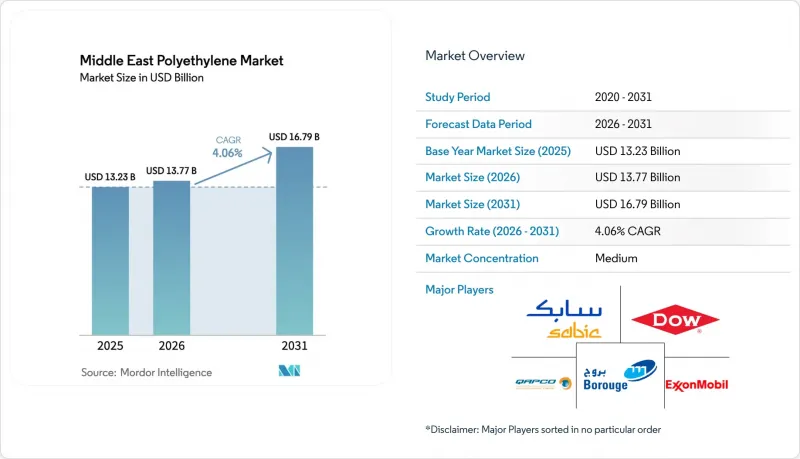
本報告按產品類型(HDPE、LDPE、LLDPE 及其他)、應用領域(吹塑成型、薄膜/片材、射出成型等)、終端用戶行業(包裝、運輸、電氣/電子、建築等)和地區(沙烏地阿拉伯、卡達、科威特、阿曼、伊朗等)進行細分。市場預測以美元計價。
中東聚乙烯市場趨勢與洞察
快速消費品和電子商務對硬質和軟質包裝的需求不斷成長。
根據沙烏地阿拉伯標準組織 (SASO) 2021 年的規定,預計到 2024 年,該地區的軟包裝市場規模將達到 100 億美元。沙烏地阿拉伯在採用可回收的單一材料薄膜方面領先,這些薄膜簡化了使用後的分類流程。快速發展的電子商務平台,例如 Amazon.ae 和 Noon,依賴聚乙烯郵寄信封、氣泡膜空氣枕枕,推動保護性包裝市場以接近 10% 的年成長率成長。品牌商轉向使用線性低密度聚乙烯 (LLDPE) 薄膜,不僅實現了可回收目標,還受益於薄膜更薄,材料用量最多可減少 15%。這些趨勢支撐了 LLDPE 預計 5.12% 的複合年成長率,鞏固了薄膜在整個預測期內作為最大應用領域的地位。
汽車、電氣和電子(E&E)替換零件的工業應用。
在阿布達比、杜拜和沙烏地阿拉伯的NEOM專案電動車組裝區,電池外殼、電纜絕緣層和引擎室組件均採用特定等級的聚乙烯材料。博日(Boruge)位於盧瓦伊斯(Luwais)的年產10萬噸交聯聚乙烯(XLPE)工廠,為連接不斷擴建的太陽能發電廠和國家電網的海底電力電纜提供特殊化合物。與各國政府人工智慧(AI)專案相關的資料中心建設,正在加速阻燃高密度聚乙烯(HDPE)導管的消耗,推動電氣和電子產業達到5.08%的複合年成長率。
可輕易取得的替代材料,例如PP和PET。
聚丙烯 (PP) 和聚對苯二甲酸乙二醇酯 (PET) 在熱填充容器、飲料瓶和汽車裝飾件等領域的市佔率不斷擴大,其耐熱性優於聚乙烯。博日公司將聚丙烯產能擴大至每年 72 萬噸,沙烏地基礎工業公司 (SABIC) 開發了 PP5707N 牌號,這些舉措豐富了產品系列,並有助於應對聚乙烯替代的壓力。原油價格波動時,價格差異在一個季度內可能變化 20% 至 30%,一旦出現成本優勢,加工商就會更換樹脂。
細分市場分析
2025年,高密度聚苯乙烯(HDPE)在中東聚乙烯市場將維持40.92%的佔有率,這主要得益於對吹塑成型桶、IBC噸桶和大口徑壓力管道的需求。塔斯尼公司位於朱拜勒的HDPE生產線年產能達40萬噸,根據ISO 4427標準,為拉菲草編織、射出成型成型和管道生產提供樹脂。低密度聚乙烯(LDPE)在收縮膜和層壓材料領域表現良好,而線性低密度聚乙烯(LLDPE)的成長最為強勁,這主要得益於「博斯塔增強型」(Borstar Enhanced)等級產品的推出,該等級產品可在不影響機械性能的前提下,將壁厚降低15-20%。
更薄的電商運輸袋、防刺穿拉伸膜和透明溫室覆蓋物正推動線性低密度聚乙烯 (LLDPE) 的預計複合年成長率達到 5.05%,預計到 2031 年,其在中東聚乙烯市場的佔有率將下降至約三分之一。超高分子量聚乙烯和 EVA 共聚物用於醫療、輸送機和太陽能發電等小眾應用領域,但即使兩者合計,其市佔率也低於 5%。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 快速消費品和電子商務對硬質和軟質包裝的需求不斷成長。
- 汽車、電氣和電子(E&E)替換零件的工業滲透率。
- 海灣合作理事會地區政府主導的石化產業多元化發展。
- 區域供冷和節水網路對聚乙烯(PE)管道的需求正在激增。
- 對再生材料含量的強制性要求導致原生聚乙烯和再生聚乙烯之間的混合物不斷擴大。
- 市場限制因素
- 現成的替代品包括PP和PET。
- 原油價格波動導致原物料價格波動
- 非洲新興市場的進口關稅阻礙了轉口貿易。
- 價值鏈分析
- 波特五力模型
第5章 市場規模與成長預測
- 依產品類型
- HDPE
- LDPE
- LLDPE
- 其他產品類型
- 透過使用
- 吹塑成型
- 薄膜
- 射出成型
- 管道和導管
- 電線電纜
- 其他用途
- 按最終用戶行業分類
- 包裝
- 運輸
- 電氣和電子設備
- 建築/施工
- 農業
- 其他終端用戶產業
- 按地區
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 卡達
- 科威特
- 阿曼
- 伊朗
- 其他中東國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率(%)/排名分析
- 公司簡介
- Advanced Petrochemical Company,
- Amir Kabir Petrochemical Co.(AKPC)
- Borouge
- Dow
- Eastern Petrochemical Company
- Exxon Mobil Corporation
- Ilam Petrochemical
- Jam Petrochemical Co.
- LyondellBasell Industries BV
- Marun Petrochemical Co.
- National Petrochemical Industrial Co.(NPIC)
- Qatar Chemical Company Ltd
- Qatar Petrochemical Company(QAPCO)
- SABIC
- Saudi Ethylene & Polyethylene Co.(Tasnee)
- Saudi Polymers LLC,
- TotalEnergies
第7章 市場機會與未來展望
According to Mordor Intelligence, the Middle East polyethylene market size was valued at USD 13.23 billion in 2025 and estimated to grow from USD 13.77 billion in 2026 to reach USD 16.79 billion by 2031, at a CAGR of 4.06% during the forecast period (2026-2031).
This report is Segmented by Product Type (HDPE, LDPE, LLDPE, and Other Product Types), Application (Blow Molding, Films and Sheets, Injection Molding, and More), End-User Industry (Packaging, Transportation, Electrical and Electronics, Building and Construction, and More), and Geography (Saudi Arabia, Qatar, Kuwait, Oman, Iran, and More). Market Forecasts are Provided in Terms of Value (USD).
Middle East Polyethylene Market Trends and Insights
Expansion of Rigid and Flexible Packaging Demand in FMCG and E-Commerce
The regional flexible-packaging market reached USD 10 billion in 2024, with Saudi Arabia leading adoption of recyclable mono-material films that simplify post-consumer sorting under SASO's 2021 regulations. Fast-growing e-commerce platforms such as Amazon.ae and Noon rely on polyethylene mailers, bubble wrap, and air pillows, driving annual protective packaging growth into the high teens. Brand owners shifting to linear low-density polyethylene films meet recyclability targets and benefit from downgauging that cuts material use by up to 15%. These dynamics underpin LLDPE's 5.12% CAGR outlook while cementing films as the single largest application throughout the forecast window.
Industrial Uptake for Automotive and E&E Replacement Parts
Electric-vehicle assembly zones in Abu Dhabi, Dubai, and Saudi Arabia's NEOM project specify polyethylene grades for battery housings, cable insulation, and under-hood components. Borouge's 100,000 tpa cross-linked polyethylene unit at Ruwais supplies specialty compounds for subsea power cables that link expanding solar farms to national grids. Data-center construction tied to sovereign artificial-intelligence programs accelerates consumption of flame-retardant HDPE conduits, supporting a 5.08% CAGR in the electrical and electronics segment.
Readily Available Substitutes Such as PP and PET
Polypropylene and polyethylene terephthalate gain market share in hot-fill containers, beverage bottles, and automotive trim, where thermal resistance outperforms that of polyethylene. Borouge's polypropylene capacity expansion to 720,000 tpa and SABIC's PP5707N grade development diversify portfolios and hedge against polyethylene substitution pressure. Price spreads can swing 20-30% within a quarter during crude oil volatility, prompting converters to switch resins when cost advantages emerge.
Other drivers and restraints analyzed in the detailed report include:
- State-Led Diversification into Petrochemicals Across GCC
- Surge in PE Pipe Demand for District Cooling and Water-Saving Networks
- Feedstock Price Volatility and Import Tariffs in African Outlets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
High-density polyethylene retained 40.92% of the 2025 Middle East polyethylene market share, buoyed by demand for blow-molded drums, IBCs, and large-diameter pressure pipes. Tasnee's 400,000 tpa HDPE train at Jubail supplies raffia, injection molding, and pipe resins that meet ISO 4427 standards. Low-density polyethylene performs well in shrink films and lamination layers, while linear low-density polyethylene experiences the strongest growth, aided by Borstar Enhanced grades that enable 15-20% downgauging without compromising mechanical properties.
Down-gauged e-commerce mailers, puncture-resistant stretch films, and clarity-enhanced greenhouse covers drive LLDPE's forecast CAGR to 5.05%, narrowing its contribution to the Middle East polyethylene market size to approximately one-third by 2031. Ultra-high-molecular-weight polyethylene and EVA copolymers occupy niche medical, conveyor, and photovoltaic applications, although they collectively account for a share below mid-single digits.
Complete Report Scope:
- By Product Type
- HDPE
- LDPE
- LLDPE
- Other Product Types
- By Application
- Blow Molding
- Films and Sheets
- Injection Molding
- Pipes and Conduits
- Wires and Cables
- Other Applications
- By End-user Industry
- Packaging
- Transportation
- Electrical and Electronics
- Building and Construction
- Agriculture
- Other End-user Industries
- By Geography
- Saudi Arabia
- United Arab Emirates
- Qatar
- Kuwait
- Oman
- Iran
- Rest of Middle East
List of Companies Covered in this Report:
- Advanced Petrochemical Company,
- Amir Kabir Petrochemical Co. (AKPC)
- Borouge
- Dow
- Eastern Petrochemical Company
- Exxon Mobil Corporation
- Ilam Petrochemical
- Jam Petrochemical Co.
- LyondellBasell Industries BV
- Marun Petrochemical Co.
- National Petrochemical Industrial Co. (NPIC)
- Qatar Chemical Company Ltd
- Qatar Petrochemical Company (QAPCO)
- SABIC
- Saudi Ethylene & Polyethylene Co. (Tasnee)
- Saudi Polymers LLC,
- TotalEnergies
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of rigid and flexible packaging demand in FMCG and e-commerce
- 4.2.2 Industrial uptake for automotive and E&E replacement parts
- 4.2.3 State-led diversification into petrochemicals across GCC
- 4.2.4 Surge in PE pipe demand for district cooling and water-saving networks
- 4.2.5 Mandatory recyclate-content rules boosting virgin-recycle PE blends
- 4.3 Market Restraints
- 4.3.1 Readily available substitutes such as PP and PET
- 4.3.2 Feedstock price volatility linked to crude swings
- 4.3.3 Import tariffs in African growth outlets curbing re-exports
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size & Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 HDPE
- 5.1.2 LDPE
- 5.1.3 LLDPE
- 5.1.4 Other Product Types
- 5.2 By Application
- 5.2.1 Blow Molding
- 5.2.2 Films and Sheets
- 5.2.3 Injection Molding
- 5.2.4 Pipes and Conduits
- 5.2.5 Wires and Cables
- 5.2.6 Other Applications
- 5.3 By End-user Industry
- 5.3.1 Packaging
- 5.3.2 Transportation
- 5.3.3 Electrical and Electronics
- 5.3.4 Building and Construction
- 5.3.5 Agriculture
- 5.3.6 Other End-user Industries
- 5.4 By Geography
- 5.4.1 Saudi Arabia
- 5.4.2 United Arab Emirates
- 5.4.3 Qatar
- 5.4.4 Kuwait
- 5.4.5 Oman
- 5.4.6 Iran
- 5.4.7 Rest of Middle East
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/ Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Advanced Petrochemical Company,
- 6.4.2 Amir Kabir Petrochemical Co. (AKPC)
- 6.4.3 Borouge
- 6.4.4 Dow
- 6.4.5 Eastern Petrochemical Company
- 6.4.6 Exxon Mobil Corporation
- 6.4.7 Ilam Petrochemical
- 6.4.8 Jam Petrochemical Co.
- 6.4.9 LyondellBasell Industries BV
- 6.4.10 Marun Petrochemical Co.
- 6.4.11 National Petrochemical Industrial Co. (NPIC)
- 6.4.12 Qatar Chemical Company Ltd
- 6.4.13 Qatar Petrochemical Company (QAPCO)
- 6.4.14 SABIC
- 6.4.15 Saudi Ethylene & Polyethylene Co. (Tasnee)
- 6.4.16 Saudi Polymers LLC,
- 6.4.17 TotalEnergies
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

 2026年全球聚乙烯市場報告
 聚乙烯:市佔率分析、產業趨勢與統計、成長預測(2026-2031)
 全球聚乙烯市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 2026-2030年全球聚乙烯市場
 聚乙烯編織袋市場規模、佔有率、成長和行業分析:按材料類型、產品類型、最終用途、地區分類,並預測至2034年2026年生物基聚乙烯全球市場報告聚乙烯市場規模、佔有率、成長及全球產業分析:按類型、應用和地區分類的洞察,2026-2034年預測全球聚乙烯(PE)蠟市場規模、佔有率、趨勢和成長分析報告:2026-2034年
 聚乙烯市場:依產品類型、回收製程、應用和最終用戶分類-2026-2032年全球市場預測
 聚乙烯(PE)母粒市場規模、佔有率和成長分析:按產品類型、載體樹脂等級、加工方法、最終用途產業和地區分類-2026-2033年產業預測