


 |
市場調查報告書
商品編碼
2116869
印度工業塗料市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)India Industrial Coatings - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,印度工業塗料市場規模將從 2025 年的 29.3 億美元成長到 2026 年的 30.9 億美元,然後在 2031 年達到 40.5 億美元,2026 年至 2031 年的複合年成長率為 5.52%。
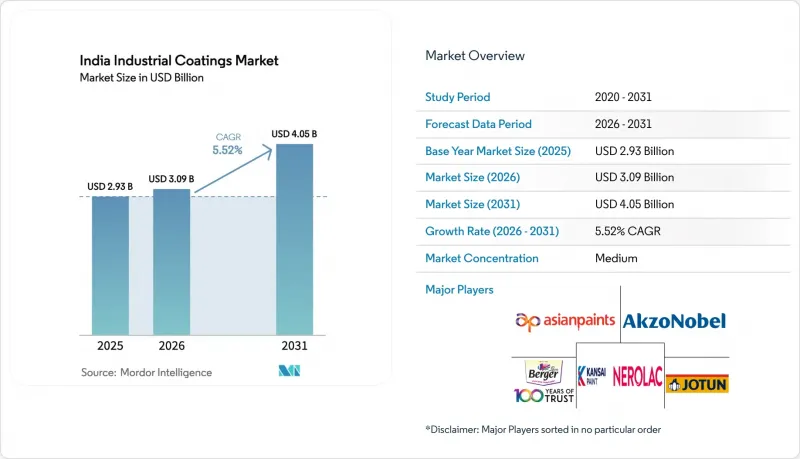
本報告按樹脂類型(環氧樹脂、聚氨酯、丙烯酸樹脂、聚酯樹脂及其他樹脂(例如醇酸樹脂))、技術(水性、溶劑型、粉末塗料及其他技術(例如紫外線/電子束固化))和終端用戶行業(通用工業塗料和防護塗料(例如石油天然氣和發電行業))進行細分。市場預測以美元計價。
印度工業塗料市場趨勢與洞察
擴大製造業和基礎設施項目
大規模石化、採礦和交通走廊的開發,為印度工業塗料市場帶來了未來幾年的良好前景。這是因為工程總承包商(EPC承包商)正在指定使用更堅固耐用、使用壽命更長的塗料系統來應對嚴苛的施工現場條件。古吉拉突邦和奧裡薩邦的主導化工園區正在簡化原料物流,並支持工廠層面環氧底漆和聚氨酯面漆的即時交付。在這些叢集附近設有服務中心的塗料製造商,正在降低運輸成本,並在此過程中能夠快速回應品質審核。綜合性鋼鐵廠、風力發電塔筒製造地和港口設施對塗料的需求日益成長,這些塗料需要能夠高度適應各種表麵條件,並且重塗週期短,從而縮短專案工期。因此,塗料系統正從單組分轉向雙組分,這提高了平均售價,並為後向整合的塗料生產商帶來了更高的利潤率。
汽車產量增加和對翻新車的需求擴大
印度汽車製造業的復甦和在用車輛數量的持續成長,推動了噴漆車間和翻新噴漆作業的產能擴張,導致預處理、底漆/面漆、底塗層和透明塗層等各個環節的油漆消耗量增加。電池式電動車的電池組和電力電子元件需要使用高絕緣性和高導熱性的油漆,因此每輛車的油漆用量約為內燃機汽車的三倍。由於粉末塗料的轉移效率高達98%,且溶劑零排放,一級供應商正轉向使用粉末塗料進行底盤和懸吊臂的噴塗。二線城市的汽車修補店為了符合當地污染控制部門的檢查要求,正在改用低VOC聚氨酯透明塗層,這也對相應的固化劑和稀釋劑的需求產生了連鎖反應。
嚴格的VOC和溶劑排放法規
《示範工廠規章》第123-M條規定,I類溶劑必須採用封閉回路型傳輸,促使企業投資建置蒸氣回收系統和防爆馬達。沒有蓄熱式熱氧化系統的工廠面臨批次規模的限制,導致高固態塗料和水溶性黏合劑的使用量增加。化合物設計人員在以二甲苯或甲基乙基酮(MEK)取代溶劑時,需要與客戶重新進行系統認證,這加劇了研發資源的緊張,並延長了產品上市時間。小規模合約製造商正將表面處理工程外包給大規模合約塗料公司,這使得能夠獲得環境保護資金的企業需求集中。此外,相關法規也對油漆工每班次的接觸量設定了限制,從而增加了對能夠縮短噴漆室使用時間的快乾塗料的需求。
細分市場分析
預計到2025年,環氧樹脂在印度工業塗料市場將佔最大佔有率,達到30.92%,反映了其在基礎設施和海洋防護領域的強勢地位。在預測期(2026-2031年)內,聚氨酯樹脂的市場佔有率將以6.01%的複合年成長率(CAGR)高速成長,這主要得益於汽車內飾、電動汽車電池組和風力渦輪機葉片外殼等領域對聚氨酯樹脂的日益成長的需求。由於其低滲透性和強黏合性,環氧樹脂在酸性或鹼性環境中仍能保持良好的性能。然而,雙組分聚氨酯樹脂在鹽霧試驗中展現出與環氧樹脂相當的性能,同時也具有更優異的柔軟性。非異氰酸酯聚氨酯(NIPU)正逐漸成為更環保的替代方案,其耐化學性比傳統聚氨酯高出30-50%,且不含遊離異氰酸酯的危害。
垂直整合液態環氧單體(LEM)和聚醚多元醇生產的樹脂化合物製造商正在獲得更高的利潤率和更穩定的供應。在印度工業塗料市場,丙烯酸樹脂在嚴苛環境下仍佔據一定佔有率,但在家用電器、暖通空調和外牆板等對保色性要求極高的應用領域佔據主導地位。受模組化廚房和辦公家具需求成長的推動,聚酯樹脂正逐漸成為室內家具粉末塗裝生產線的主流選擇。供應商正在嘗試由木質素和大豆油製成的生物基環氧樹脂,以在保持機械性能的同時減少碳排放。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 製造業和基礎設施項目的擴張
- 汽車產量增加和維修需求上升
- 石油和天然氣管道防腐蝕需求日益成長
- 政府致力於在戰略領域推廣高性能塗料的廣泛應用
- 需要特殊塗層的可再生能源設備
- 市場限制因素
- 對揮發性有機化合物和溶劑排放的嚴格監管
- 原物料價格波動,以原油為成本。
- 熟練工業油漆工短缺
- 價值鏈分析
- 波特五力模型
第5章 市場規模與成長預測
- 依樹脂類型
- 環氧樹脂
- 聚氨酯
- 丙烯酸纖維
- 聚酯纖維
- 其他樹脂(醇酸樹脂、氟樹脂)
- 透過技術
- 水溶液
- 溶劑型
- 粉末塗裝
- 其他技術(UV/EB固化型和高固態含量型)
- 按最終用戶行業分類
- 一般工業
- 保護塗層
- 石油和天然氣
- 發電
- 基礎設施
- 礦業
- 其他保護塗層
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- AkzoNobel India Ltd.
- Asian Paints PPG Pvt. Ltd
- Axalta Coating Systems
- BASF SE
- Beckers Group
- Berger Paints India Ltd.
- Carboline India Pvt Ltd
- Chugoku Marine Paints Ltd.
- Fosroc, Inc.
- Hempel A/S
- Jotun
- Kansai Nerolac Paints Limited
- Nippon Paint(India)Private Limited.
- RPM International Inc.
- Shalimar Paints LTD(Mumbai)
- Sika AG
- The Sherwin-Williams Company
- Wacker Chemie AG
第7章 市場機會與未來展望
According to Mordor Intelligence, the India industrial coatings market size is expected to grow from USD 2.93 billion in 2025 to USD 3.09 billion in 2026 and is forecast to reach USD 4.05 billion by 2031 at 5.52% CAGR over 2026-2031.
This report is Segmented by Resin Type (Epoxy, Polyurethane, Acrylic, Polyester, and Other Resins (Alkyd and More)), Technology (Water-Borne, Solvent-Borne, Powder Coatings, and Other Technologies (UV-/EB-Cured and More)), and End-User Industry (General Industrial and Protective Coatings (Oil and Gas, Power Generation, and More)). The Market Forecasts are Provided in Terms of Value (USD).
India Industrial Coatings Market Trends and Insights
Expanding Manufacturing and Infrastructure Projects
Large-scale petrochemical, mining, and transportation corridors are providing multi-year visibility into the India Industrial Coatings market, as EPC contractors specify higher build and longer-life systems for harsh on-site conditions. State-led chemical parks in Gujarat and Odisha simplify feedstock logistics, supporting plant-level just-in-time deliveries for epoxy primers and polyurethane finishes. Coaters that colocate service centers near these clusters lower freight costs and provide faster turnaround for in-process quality audits. Integrated steel plants, wind-tower yards, and port facilities require surface-tolerant coatings with rapid recoat windows, which shorten project schedules. The resulting shift from single-pack to two-pack systems is lifting average selling prices and strengthening margins for formulators that have backward-integrated resin assets.
Rising Automotive Production and Refurbishment Demand
India's vehicle output rebound and sustained growth in the car parc are expanding paint-shop throughput and refinish activities, lifting consumption across pretreatment, primer-surfacer, basecoat, and clearcoat stages. Battery-electric vehicles require highly insulative and thermally conductive coatings on packs and power-electronics, nearly tripling coating grams per vehicle compared with internal-combustion equivalents. OEM tier-1 suppliers are migrating to powder for chassis and suspension arms, citing 98% transfer efficiency and zero solvent emissions. Refinish shops in Tier-2 cities are upgrading to low-VOC polyurethane clearcoats to comply with local pollution-control board checks, creating a ripple effect in demand for matched hardeners and thinners.
Stringent VOC and Solvent-Emission Regulations
Rule 123-M of the Model Factory Rules enforces closed-loop transfer of Class-I solvents, prompting capex on vapor recovery and explosion-proof motors. Plants lacking regenerative thermal oxidizers are limited by batch size and are shifting toward high-solids or water-reducible binders. Formulators must re-qualify systems with customers when replacing xylene or MEK, stretching R&D resources and lengthening commercialization timelines. Smaller job shops are outsourcing finishing to larger toll coaters, consolidating demand among players that can finance environmental upgrades. The regulation also caps shift-time exposure levels for painters, intensifying demand for faster-curing coatings that reduce booth occupancy.
Other drivers and restraints analyzed in the detailed report include:
- Growing Demand for Corrosion-Protection in Oil and Gas Pipelines
- Government Push for High-Performance Coatings in Strategic Sectors
- Volatility in Crude-Oil Based Raw-Material Prices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The epoxy resin type had the largest share of 30.92% in the India Industrial Coatings Market in 2025, reflecting its entrenched status in infrastructure and marine protection. The market share of polyurethane resin types is growing at the fastest CAGR of 6.01% during the forecast period (2026-2031) due to OEM uptake in automotive trim, electric-vehicle battery packs, and wind-blade shells. Epoxy's low permeation and strong adhesion continue to outperform in acidic or alkaline environments; however, two-component polyurethanes now deliver comparable salt-spray performance with superior flexibility. Non-isocyanate polyurethane (NIPU) is emerging as an eco-friendlier alternative, delivering 30-50% higher chemical resistance than traditional polyurethane without the hazards of free isocyanate.
Resin formulators with vertical integration into liquid epoxy monomer (LEM) and polyether polyol production capture better margins and supply reliability. The India Industrial Coatings market share of acrylics remains niche in heavy-duty services but dominates in applications such as appliances, HVAC, and facade panels, where color retention is paramount. Polyester dominates interior furniture powder lines, supported by rising demand for modular kitchens and office furniture. Suppliers are pilot-running bio-based epoxies from lignin and soybean-oil routes to cut carbon footprints while preserving mechanical performance.
Complete Report Scope:
- By Resin Type
- Epoxy
- Polyurethane
- Acrylic
- Polyester
- Other Resins (Alkyd, Fluoropolymer)
- By Technology
- Water-borne
- Solvent-borne
- Powder Coatings
- Other Technologies (UV-/EB-Cured and High Solids)
- By End-user Industry
- General Industrial
- Protective Coatings
- Oil and Gas
- Power Generation
- Infrastructure
- Mining
- Other Protective Coatings
List of Companies Covered in this Report:
- AkzoNobel India Ltd.
- Asian Paints PPG Pvt. Ltd
- Axalta Coating Systems
- BASF SE
- Beckers Group
- Berger Paints India Ltd.
- Carboline India Pvt Ltd
- Chugoku Marine Paints Ltd.
- Fosroc, Inc.
- Hempel A/S
- Jotun
- Kansai Nerolac Paints Limited
- Nippon Paint (India) Private Limited.
- RPM International Inc.
- Shalimar Paints LTD (Mumbai)
- Sika AG
- The Sherwin-Williams Company
- Wacker Chemie AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expanding manufacturing and infrastructure projects
- 4.2.2 Rising automotive production and refurbishment demand
- 4.2.3 Growing demand for corrosion-protection in oil and gas pipelines
- 4.2.4 Government push for high-performance coatings in strategic sectors
- 4.2.5 Renewable-energy installations requiring specialized coatings
- 4.3 Market Restraints
- 4.3.1 Stringent VOC and solvent-emission regulations
- 4.3.2 Volatility in crude-oil based raw-material prices
- 4.3.3 Lack of skilled industrial-coating applicators
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size & Growth Forecasts (Value)
- 5.1 By Resin Type
- 5.1.1 Epoxy
- 5.1.2 Polyurethane
- 5.1.3 Acrylic
- 5.1.4 Polyester
- 5.1.5 Other Resins (Alkyd, Fluoropolymer)
- 5.2 By Technology
- 5.2.1 Water-borne
- 5.2.2 Solvent-borne
- 5.2.3 Powder Coatings
- 5.2.4 Other Technologies (UV-/EB-Cured and High Solids)
- 5.3 By End-user Industry
- 5.3.1 General Industrial
- 5.3.2 Protective Coatings
- 5.3.2.1 Oil and Gas
- 5.3.2.2 Power Generation
- 5.3.2.3 Infrastructure
- 5.3.2.4 Mining
- 5.3.2.5 Other Protective Coatings
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, Recent Developments)
- 6.4.1 AkzoNobel India Ltd.
- 6.4.2 Asian Paints PPG Pvt. Ltd
- 6.4.3 Axalta Coating Systems
- 6.4.4 BASF SE
- 6.4.5 Beckers Group
- 6.4.6 Berger Paints India Ltd.
- 6.4.7 Carboline India Pvt Ltd
- 6.4.8 Chugoku Marine Paints Ltd.
- 6.4.9 Fosroc, Inc.
- 6.4.10 Hempel A/S
- 6.4.11 Jotun
- 6.4.12 Kansai Nerolac Paints Limited
- 6.4.13 Nippon Paint (India) Private Limited.
- 6.4.14 RPM International Inc.
- 6.4.15 Shalimar Paints LTD (Mumbai)
- 6.4.16 Sika AG
- 6.4.17 The Sherwin-Williams Company
- 6.4.18 Wacker Chemie AG
7 Market Opportunities & Future Outlook
- 7.1 White-space and Unmet-Need Assessment

 水性工業防腐蝕塗料市場-全球預測(2026-2032年)
 2026年全球工業塗料市場報告
 全球工業塗料市場:依功能、樹脂類型、技術、終端應用產業及地區分類-預測至2031年工業塗料市場-2026-2032年全球市場預測
 德國工業塗料:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)
 全球工業塗料市場規模、佔有率、趨勢和成長分析報告(2026-2034年)工業塗料:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 工業塗料市場-全球產業規模、佔有率、趨勢、機會和預測:按產品、技術、最終用途、地區和競爭格局分類,2021-2031年
 工業塗料市場:按產品、技術、最終用戶和地區分類(2026-2034 年)工業色素市場按應用、顏料類型、顏色和形態分類-全球預測,2026-2032年