


 |
市場調查報告書
商品編碼
2116441
紫外光譜:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)UV Spectroscopy - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,紫外光譜市場預計到 2026 年價值 225.8 億美元,高於 2025 年的 215.2 億美元,預計到 2031 年將達到 286.9 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 4.92%。
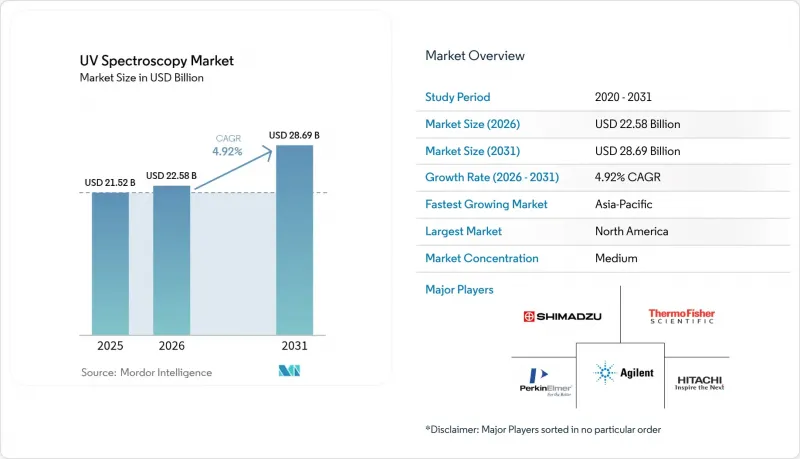
本報告按儀器類型(例如,桌上型分光光度計)、技術(例如,單光束)、應用(例如,藥品品管和交付前檢驗)、最終用戶(例如,製藥和生物技術公司)以及地區(北美、歐洲、亞太、中東和非洲、南美)進行細分。市場預測以美元(USD)為單位。
全球紫外光譜市場趨勢及洞察
對生物製藥品質保證的需求日益成長
目前,生物製藥管線主導藥物研發的後期階段,推動紫外光譜市場朝向更靈敏的蛋白質分析方向發展。諸如Solo VPE之類的可變光程儀器無需稀釋樣品即可直接測量濃度高達300 mg/mL的抗體,從而將檢測時間從數小時縮短至數分鐘。在蛋白A層析法中採用線上紫外線監測可提高宿主細胞蛋白的去除率和產量,滿足監管機構「品質源自設計 (QbD)」對即時控制的要求。為此,供應商正在整合化學計量學模型,該模型可在單次掃描中輸出濃度和純度測量結果,從而減輕操作人員的工作量並提高批次放行速度。隨著生物製造公司擴展其連續生產平台,對堅固耐用、適用於無塵室的紫外線探頭的需求預計將持續成長,從而推高紫外光譜市場的平均售價。
對即時診斷檢測的需求日益成長。
人口結構變化和對更快臨床決策的需求正在加速小型紫外線設備在分散式環境中的應用。微體積奈米分光光度計能夠定量檢測尿白蛋白和肌酸酐,其檢測極限適用於糖尿病腎病變的早期篩檢,而這項檢測先前僅限於中心檢查室。新創公司正在將紫外光學技術與人工智慧演算法相結合,以在30分鐘內提供細胞治療中的細菌污染檢測結果,取代了膜過濾通常需要14天的無菌確認期。亞太地區各國政府正在鼓勵採用即時檢測(POC)設備以緩解醫院堵塞,設備製造商也陸續推出可充電、支援藍牙功能且能與電子健康記錄平台同步的設備。光學、微流體和機器學習的融合正在將紫外光譜市場拓展到傳統藥物品管之外的領域。
對符合GMP規範的設備進行大量資本投入
完整的GMP認證設備、符合21 CFR Part 11標準的軟體以及USP <857>可追溯性要求,推高了紫外光譜平台的初始成本。配備波長驗證套件的桌上型系統價格可能超過85,000美元,這對小規模製造商和公共機構構成了重大障礙。即使是透過認證二手設備專案提供的翻新設備,也需要額外支付重新認證和文件編制費用,這些費用往往與設備購買價格相當。新興市場的公司面臨高額進口關稅和缺乏本地驗證專業知識,導致投資回收期延長。除非資金籌措方案和租賃模式得到更廣泛的應用,否則這些經濟因素將阻礙紫外光譜市場中最注重價格的細分市場採用這些設備。
細分市場分析
到2025年,桌上型紫外光譜儀將佔據紫外光譜市場55.12%的佔有率,其卓越的光度精度、可靠的認證套件以及豐富的配件生態系統將推動銷售成長。大型製藥廠傾向採用標準化的雙束平台,以統一跨多個地點的分析方法,並符合FDA的分析方法檢驗要求。同時,可攜式/手持式設備銷售成長最快,複合年成長率達7.12%,這主要得益於即時診斷(POC)、現場水質檢測以及連續生產設施中的原料檢驗等應用。供應商正透過微電子機械鏡和寬頻頻率梳等技術改進光學佈局,實現了高達1000萬的解析度,而此前只有旗艦級桌上型儀器才能達到這一水平。
在競爭激烈的市場環境中,能夠將小型化光學元件與可承受無塵室消毒劑的堅固機殼相結合的公司將更具優勢。支援雲端功能的韌體可以將加密頻譜流傳輸到中央伺服器,從而縮短資料聚合時間,這項特性正獲得監管機構的支援。隨著分散式醫療模式的成熟,可攜式將佔據主導地位。然而,在監管嚴格的批量放行環境中,桌上型設備預計仍將繼續主導紫外光譜市場。
到2025年,雙束光學元件仍將佔據41.10%的銷售佔有率,其在穩定性測試等長時間分析測試中展現的基準穩定性備受青睞。然而,預計到2031年,二極體陣列配置的成長速度將超過其他設計,複合年成長率將達到7.33%。這種在毫秒內捕獲整個頻譜的能力支持峰純度檢測和強制劣化分析,這對於ICH Q1指南至關重要。雖然單光束儀器在注重成本的實驗室中仍被應用,但工作波長低於200奈米的深紫外線儀器正在滿足基因治療研究中對高猝滅蛋白檢測日益成長的需求。
儀器製造商正大力投資於雜散光抑制技術,採用全像光柵,即使在極高的吸光度下也能保持線性度。軟體方面的進步已融入基於機器學習的頻譜庫匹配功能,可將人工資料審核工作量減少高達 40%。硬體精度與演算法分析的融合,增強了產品差異化優勢,並使其在紫外光譜市場這一領域保持了高階價格定位。
區域分析
預計到2025年,北美將佔全球銷售額的42.00%,並繼續維持其最大貢獻者的地位。這得歸功於北美強大的生物製藥基礎設施、嚴格的FDA監管以及主要分析儀器品牌的本地製造地。政府推出的經濟獎勵策略,例如《晶片和科學法案》,進一步促進了精密光學元件的國內生產,並加強了供應鏈。歐洲緊隨北美之後,主要得益於EMA(歐洲藥品管理局)的監管協調以及不斷擴大的生技藥品契約製造網路。
同時,亞太地區以6.18%的複合年成長率呈現最強勁的成長勢頭,預計到2030年,該地區將佔設備需求成長的三分之一以上。由於印度的「生產連結獎勵計畫計畫」以及中國省級政府對先進療法數十億美元的補貼,新工廠的建設正在加速推進。島津公司決定在卡納塔克邦興建一座工廠,該工廠將於2027年開始每年生產1萬台紫外-可見光分析儀,這清楚體現了這種本土化趨勢。日本和韓國透過基因治療和細胞治療研發管線的持續創新來維持較高的單價,而東南亞國家則優先考慮在當地診所引入即時檢測(POC)設備。
儘管中東、非洲和南美洲仍處於起步階段,但隨著當地監管機構加強藥品安全監測框架,人們對紫外光譜技術的興趣日益濃厚。巴西國家衛生監督局 (ANVISA) 的指導方針現已參考美國藥典 (USP) <857> 中的性能檢查,老舊的單光束紫外光譜儀也正在逐步更換。海灣合作理事會 (GCC) 成員國正在自由貿易區投資建設生物製藥灌裝和包裝設施,推動了整合式紫外線監測設備的初期訂單。這些趨勢共同預示著,未來五年紫外光譜市場將進一步拓展其地域範圍。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 對生物製藥品質保證的需求日益成長
- 對即時診斷檢測的需求日益成長。
- 監管機構強調藥品資料的完整性
- 擴大臨床研究規模並外包給合約研究組織
- 將紫外線微體積奈米光譜技術整合到基因組學中
- 引入使用在線PAT感測器的連續製造程序
- 市場限制因素
- 符合GMP標準的設備需要高額的資金投入。
- 臨床光譜領域熟練人員短缺
- 嚴格的檢驗和校準程序
- 與無標定光學生物感測器的競爭
- 監理情勢
- 波特五力分析
第5章 市場規模與成長預測
- 依設備類型
- 桌上型分光光度計
- 微體積奈米分光光度計
- 可攜式/手持設備
- 製程線上感測器
- 透過技術
- 單光束
- 雙束
- 二極體陣列
- 深紫外線系統
- 透過使用
- 藥品品管與出貨檢驗
- 臨床診斷(血液和尿液檢查)
- 基因組學和蛋白質組學的定量分析
- 生物過程監測和過程分析技術
- 學術和轉化研究
- 最終用戶
- 製藥和生物技術公司
- 合約研究組織(CRO/CDMO)
- 醫院/診斷檢查室
- 大學醫院
- 公共衛生和監管機構
- 地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 澳洲
- 韓國
- 其他亞太國家
- 中東和非洲
- GCC
- 南非
- 其他中東和非洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 市佔率分析
- 公司簡介
- Agilent Technologies, Inc.
- Thermo Fisher Scientific, Inc.
- Shimadzu Corporation
- PerkinElmer Inc.
- Hitachi High-Tech Corporation
- Bruker Corporation
- JASCO Inc.
- Analytik Jena GmbH
- Mettler Toledo(Implen)
- Hach Company
- Ocean Insight
- Biochrom Ltd.
- Cecil Instruments Ltd.
- Buck Scientific Inc.
- Cole-Parmer(Antylia)
- Scinco Co., Ltd.
- Metrohm AG
- Malvern Panalytical
- Jeol Ltd.
- Edinburgh Instruments
第7章 市場機會與未來展望
According to Mordor Intelligence, UV spectroscopy market size in 2026 is estimated at USD 22.58 billion, growing from 2025 value of USD 21.52 billion with 2031 projections showing USD 28.69 billion, growing at 4.92% CAGR over 2026-2031.
This report is Segmented by Instrument Type (Benchtop Spectrophotometers, and More), Technology (Single-Beam, and More), Application (Drug Quality Control & Release Testing, and More), End User (Pharmaceutical & Biotech Companies, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global UV Spectroscopy Market Trends and Insights
Escalating Demand for Biologics Quality Assurance
Biologics pipelines now dominate late-stage drug development, pushing the UV spectroscopy market toward higher-sensitivity protein analytics. Variable-pathlength instruments such as the Solo VPE allow direct measurement of antibody concentrations up to 300 mg/mL without sample dilution, cutting assay time from hours to minutes. Inline UV monitoring of Protein A chromatography improves host-cell-protein clearance and yields, aligning with regulators' Quality by Design expectations for real-time control. Vendors respond by integrating chemometric models that deliver concentration and purity outputs in a single scan, reducing operator workload and improving batch release speeds. As biomanufacturers scale continuous-processing platforms, demand for rugged, cleanroom-compatible UV probes should continue to rise, lifting average selling prices within the UV spectroscopy market.
Expanding Point-of-Care Diagnostic Testing Needs
Demographic shifts and the quest for faster clinical decisions are accelerating adoption of compact UV devices in decentralized settings. Microvolume nano-spectrophotometers quantify urinary albumin and creatinine at detection limits suitable for early diabetic kidney disease screening, a test traditionally confined to central laboratories. Start-ups have paired UV optics with AI algorithms to deliver bacteriological contamination results for cell therapies in under 30 minutes, replacing the 14-day sterility window typical of membrane filtration. Governments in Asia-Pacific back POC deployment to relieve hospital congestion, and instrument makers are introducing rechargeable, Bluetooth-enabled units that sync with electronic health-record platforms. This convergence between optics, microfluidics, and machine learning enlarges the UV spectroscopy market beyond classic pharmaceutical quality control.
High Capital Expenditure for GMP-Compliant Instruments
Full GMP qualification packages, 21 CFR Part 11 software, and USP <857> traceability requirements elevate upfront costs for UV platforms. A benchtop system bundled with wavelength validation kits can exceed USD 85,000, a hurdle for small manufacturers and public-sector laboratories. Even refurbished units offered under certified pre-owned programs incur added spend on re-qualification and documentation, often matching the purchase price. Emerging-market firms face higher import duties and scarce local validation expertise, extending payback periods. Unless financing tools or leasing models proliferate, these economics will curb unit penetration in the most price-sensitive tiers of the UV spectroscopy market.
Other drivers and restraints analyzed in the detailed report include:
- Regulatory Emphasis on Pharma Data Integrity
- Growth in Clinical Research and CRO Outsourcing
- Limited Skilled Workforce in Clinical Spectroscopy
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Benchtop units dominated sales with 55.12% of the UV spectroscopy market size in 2025 thanks to their superior photometric accuracy, robust qualification kits, and broad accessory ecosystems. Large pharma plants prefer standardized dual-beam platforms because they harmonize method transfer across multiple sites and align with FDA method-verification requirements. Portable/hand-held devices, however, posted the fastest unit growth at a 7.12% CAGR, fueled by POC diagnostics, on-site water testing, and raw-material verification in continuous-manufacturing suites. Vendors have improved optical layouts using micro-electromechanical mirrors and broadband frequency combs, achieving resolving power of up to 10 million-performance once limited to flagship benchtop instruments.
Competitive dynamics favor companies that combine miniaturized optics with rugged casings able to withstand cleanroom disinfectants. Cloud-ready firmware that streams encrypted spectra to centralized servers reduces data-aggregation time, a feature gaining regulatory favor. As decentralized healthcare models mature, portable formats will become mainstream, although benchtop units will keep commanding the lion's share of the UV spectroscopy market in highly regulated batch-release environments.
Dual-beam optics continued to hold 41.10% revenue share in 2025, admired for baseline stability during long analytical runs typical of stability studies. Diode-array configurations nonetheless logged a 7.33% CAGR and are positioned to outpace other designs through 2031. Their ability to capture entire spectra in milliseconds supports peak-purity checks and forced-degradation profiling, activities integral to ICH Q1 guidelines. Single-beam instruments survive in cost-sensitive labs, while deep-UV variants, operating below 200 nm, meet rising demand for high-extinction protein detection in gene-therapy research.
Instrument makers invest heavily in stray-light suppression, using holographic gratings that retain linearity even at extremely high absorbance values. Software advances embed spectral-library matching powered by machine learning, reducing manual data review by up to 40%. The blend of hardware precision and algorithmic analytics strengthens differentiation, sustaining premium price bands in this slice of the UV spectroscopy market.
Complete Report Scope:
- By Instrument Type
- Benchtop Spectrophotometers
- Microvolume Nano-Spectrophotometers
- Portable / Hand-Held Devices
- In-Line Process Sensors
- By Technology
- Single-Beam
- Dual-Beam
- Diode-Array
- Deep-UV Systems
- By Application
- Drug Quality Control & Release Testing
- Clinical Diagnostics (Blood & Urine Analysis)
- Genomics & Proteomics Quantification
- Bioprocess Monitoring & PAT
- Academic & Translational Research
- By End User
- Pharmaceutical & Biotech Companies
- Contract Research & Manufacturing Organizations (CROs/CDMOs)
- Hospitals & Diagnostic Laboratories
- Academic Medical Centers
- Public Health & Regulatory Agencies
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America maintained the largest contribution to global revenue with 42.00% in 2025 due to robust biopharma infrastructure, stringent FDA oversight, and local manufacturing bases for major analytical brands. Government stimulus-such as the CHIPS and Science Act-further encourages domestic production of precision optics, reinforcing supply-chain resilience. Europe follows closely, propelled by harmonized EMA regulations and an expanding biologics contract-manufacturing network.
Asia-Pacific, however, delivered the strongest growth momentum at a 6.18% CAGR and is expected to account for over one-third of incremental instrument demand by 2030. India's Production-Linked Incentive scheme and China's multi-billion-dollar provincial grants for advanced therapeutics are accelerating greenfield plant construction. Shimadzu's decision to build a Karnataka factory capable of producing 10,000 UV-visible units annually from 2027 exemplifies the localization trend. Japan and South Korea sustain high unit value through continued innovation in gene and cell-therapy pipelines, while Southeast Asian states prioritize POC deployment in rural clinics.
Middle East & Africa and South America remain early-stage but show rising interest as local regulators strengthen pharmacovigilance frameworks. Brazilian ANVISA guidelines now reference USP <857>performance checks, prompting replacement of aging single-beam models. Gulf Cooperation Council countries invest in biologics fill-finish facilities within free-trade zones, driving initial orders for integrated UV monitoring skids. Collectively, these dynamics ensure the geographic spread of the UV spectroscopy market will broaden over the next five years.
- Agilent Technologies
- Thermo Fisher Scientific
- Shimadzu
- PerkinElmer
- Hitachi
- Bruker
- JASCO Inc.
- Analytik Jena GmbH
- Mettler Toledo (Implen)
- Hach Company
- Ocean Insight
- Biochrom Ltd.
- Cecil Instruments Ltd.
- Buck Scientific Inc.
- Cole-Parmer (Antylia)
- Scinco Co., Ltd.
- Metrohm
- Malvern Panalytical
- Jeol Ltd.
- Edinburgh Instruments
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Escalating Demand for Biologics Quality Assurance
- 4.2.2 Expanding Point-of-Care Diagnostic Testing Needs
- 4.2.3 Regulatory Emphasis on Pharma Data Integrity
- 4.2.4 Growth In Clinical Research and CRO Outsourcing
- 4.2.5 Integration of UV Microvolume Nano-Spectroscopy in Genomics
- 4.2.6 Adoption of Continuous Manufacturing With in-Line PAT Sensors
- 4.3 Market Restraints
- 4.3.1 High Capital Expenditure for GMP-Compliant Instruments
- 4.3.2 Limited Skilled Workforce in Clinical Spectroscopy
- 4.3.3 Stringent Validation and Calibration Protocols
- 4.3.4 Competition from Label-Free Optical Biosensors
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Instrument Type
- 5.1.1 Benchtop Spectrophotometers
- 5.1.2 Microvolume Nano-Spectrophotometers
- 5.1.3 Portable / Hand-Held Devices
- 5.1.4 In-Line Process Sensors
- 5.2 By Technology
- 5.2.1 Single-Beam
- 5.2.2 Dual-Beam
- 5.2.3 Diode-Array
- 5.2.4 Deep-UV Systems
- 5.3 By Application
- 5.3.1 Drug Quality Control & Release Testing
- 5.3.2 Clinical Diagnostics (Blood & Urine Analysis)
- 5.3.3 Genomics & Proteomics Quantification
- 5.3.4 Bioprocess Monitoring & PAT
- 5.3.5 Academic & Translational Research
- 5.4 By End User
- 5.4.1 Pharmaceutical & Biotech Companies
- 5.4.2 Contract Research & Manufacturing Organizations (CROs/CDMOs)
- 5.4.3 Hospitals & Diagnostic Laboratories
- 5.4.4 Academic Medical Centers
- 5.4.5 Public Health & Regulatory Agencies
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials As Available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Agilent Technologies, Inc.
- 6.3.2 Thermo Fisher Scientific, Inc.
- 6.3.3 Shimadzu Corporation
- 6.3.4 PerkinElmer Inc.
- 6.3.5 Hitachi High-Tech Corporation
- 6.3.6 Bruker Corporation
- 6.3.7 JASCO Inc.
- 6.3.8 Analytik Jena GmbH
- 6.3.9 Mettler Toledo (Implen)
- 6.3.10 Hach Company
- 6.3.11 Ocean Insight
- 6.3.12 Biochrom Ltd.
- 6.3.13 Cecil Instruments Ltd.
- 6.3.14 Buck Scientific Inc.
- 6.3.15 Cole-Parmer (Antylia)
- 6.3.16 Scinco Co., Ltd.
- 6.3.17 Metrohm AG
- 6.3.18 Malvern Panalytical
- 6.3.19 Jeol Ltd.
- 6.3.20 Edinburgh Instruments
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

 雷射誘導擊穿光譜(LIBS):市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 聯用光譜市場規模、佔有率和成長分析:按光譜類型、產品類型、應用、最終用戶和地區分類 - 產業預測,2026-2033 年
 光譜學市場:按組件、技術、儀器類型、測量方法、操作模式、應用和最終用戶分類-2026-2032年全球市場預測線上紫外-可見光光譜市場:按組件、技術平台、分析儀器架構、應用和最終用戶分類-2026-2032年全球市場預測
 螢光光譜市場規模、佔有率和成長分析:按類型、應用和地區分類-2026-2033年產業預測雷射誘導破壞光譜儀市場:按產品類型、組件、雷射類型、脈衝持續時間、應用、最終用戶分類,全球預測,2026-2032年表面光電壓光譜設備市場(按組件、產品類型、技術、波長範圍、工作模式、應用、最終用途和銷售管道),全球預測,2026-2032年
 在線連續紫外-可見光光譜全球市場報告(2026年)
 全球雷射誘導破壞光譜儀市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 全球螢光光譜市場