


 |
市場調查報告書
商品編碼
2116120
美國葡萄酒包裝:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)United States Wine Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
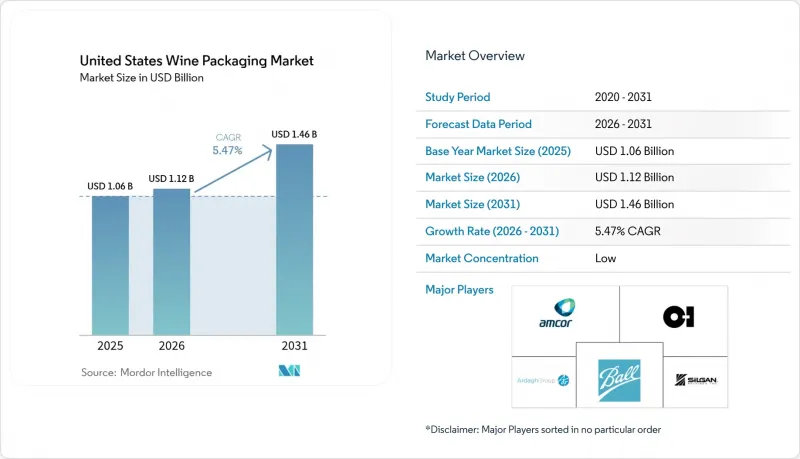
據 Mordor Intelligence 稱,2025 年美國葡萄酒包裝市場價值為 10.6 億美元,預計到 2031 年將從 2026 年的 11.2 億美元成長到 14.6 億美元,預測期(2026-2031 年)的複合年成長率為 5.47%。
本報告按材質(玻璃、塑膠、金屬、紙張)、產品類型(玻璃瓶等)、瓶塞類型(天然軟木塞、工業/合成軟木塞等)、葡萄酒類型(無氣泡葡萄酒、氣泡酒等)、容量(小於375毫升等)、分銷管道(直銷、間接銷售)和地區進行細分。市場預測以美元(USD)計價。
美國葡萄酒包裝市場的趨勢與洞察
對輕量環保玻璃的需求日益成長
玻璃供應商正在努力減輕酒瓶重量,以減少運輸排放並遏制不斷上漲的原料成本。 OI 的「Estampe」酒瓶將回收材料的比例提高到 82%,同時將重量減輕至 390 克,與傳統的 500 克酒瓶相比,碳排放量減少了 25%。對於納帕谷和索諾瑪谷的酒莊而言,採用更輕的產品所帶來的經濟效益日益顯著,因為預計到 2024 年玻璃容器的價格指數將上漲 16%。 Veralia 的新型全電熔爐可將生產過程中的二氧化碳排放量減少 60%,這體現了其對低碳玻璃供應的長期承諾。由於運輸約佔玻璃容器運輸相關排放量的 35%,因此重量減輕 10% 即可減少近 3% 的運輸排放量。對於需要揭露範圍 3 碳足跡的高階酒莊而言,這是一個極具吸引力的權衡方案。
外部部署銷售通路罐裝葡萄酒銷售快速成長
鋁材100%可回收、輕盈易攜,且用途廣泛,使其從曇花一現的潮流發展成為主流。 2024年,波爾公司在北美地區售出了480億個鋁製飲料容器,市場滲透率首次突破30%。消費者口味測試表明,年輕消費者更注重便攜性而非傳統,並且在從體育場到海灘等各種場合都更傾向於選擇不易碎的包裝。雖然不同製造商採用的內襯材料有所差異,但與硫化氫排放相關的品質問題正在透過改進內襯材料來緩解。例如,博格爾旗下的Element[AL]品牌推出了90克鋁瓶,重量僅為玻璃瓶的五分之一,但售價更高。
天然氣價格波動推高了國內玻璃生產成本。
能源成本約佔玻璃廠營運成本的20%,而天然氣價格飆升導致一系列工廠關閉,例如Ardaag位於休士頓的工廠在2024年裁員220人。 OI公司透露,由於買家轉向更便宜或更輕的替代品,銷售量下降了4.5%。儘管各公司正在將熔爐改造為氧氣或電力系統,但由於資本投資需求,設備升級的速度正在放緩,而且預計價格波動在可預見的未來仍將持續。
細分市場分析
到2025年,玻璃將占美國葡萄酒包裝市場佔有率的66.65%,價值約7.065億美元。以鋁為代表的金屬包裝預計將以8.31%的複合年成長率成長至2031年,因為品牌商優先考慮輕量化和閉合迴路回收。為此,玻璃供應商正在採取措施,例如推出390克環保瓶,並提高玻璃屑比例,以降低熔爐的能耗,同時保持高階的展示效果。紙基複合材料和可重複填充玻璃系統目前仍是小眾市場,但它們預示著下一波低碳包裝形式的發展趨勢,隨著其供應鏈的擴展,可能會蠶食玻璃的市場佔有率。
鋁製品的興起得益於運輸成本降低、100%可回收以及在注重破損的地區更容易被接受,而玻璃則憑藉其高階形像中的“真實性”優勢保持領先地位。波爾公司計劃在2030年將其再生材料含量提高到85%,這正是積極推動永續性目標以推動材料替代的典型例子。玻璃製造商正在投資電爐和氧氣燃燒器,以保護利潤率免受天然氣價格波動的影響,但這些設備的資本密集特性減緩了設備升級的步伐。最終,葡萄酒廠正在謹慎權衡碳排放揭露和品牌傳承之間的平衡,選擇逐步改變材料組成,而不是突然更換材料。
儘管預計到2025年玻璃瓶將佔市場佔有率的56.12%,但由於便攜性、可回收性以及活動場所法規傾向於使用不易碎容器,罐裝產品正以7.74%的複合年成長率快速成長。罐內塗層技術的改進降低了罐內襯化學物質產生的硫化氫風險,使其得以應用於更多種類的產品。盒中袋包裝在散裝和低價葡萄酒領域仍然佔據主導地位,因為葡萄園人手不足促使生產商尋求能夠最大限度減少搬運的包裝形式。 PET寶特瓶和軟包裝迎合了價格敏感型消費者和單份消費的需求,但其高階形象正面臨挑戰。
罐裝包裝迎合了年輕一代的需求,他們更注重環保而非傳統,例如Boglu推出的90克鋁瓶裝葡萄酒,售價16.99美元。裝瓶商也嘗試使用可重複密封的瓶蓋和紙質外包裝進行二次包裝,以提高貨架上的可見度。玻璃容器重量更輕,外形簡潔,既能減少運輸浪費,又不影響產品的品質,從而有助於保持其在貨架上的存在感。因此,酒莊得以實現產品線的多元化,並可根據銷售管道、價格區間和消費場景選擇合適的包裝類型。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 對輕量環保玻璃的需求日益成長。
- 外帶銷售管道的罐裝葡萄酒銷量激增。
- 47 個州的 DtC 運輸自由化正在推動電子商務包裝的普及。
- (奧勒岡州和密西根州的)瓶裝押金法提高了可使用的回收材料百分比的要求。
- 由於葡萄園人手不足,散裝包裝正逐漸被盒中袋包裝所取代。
- 自有品牌零售商正在擴大其對經濟實惠的PET/BIB產品的經營範圍。
- 市場限制因素
- 天然氣價格波動推高了國內玻璃生產成本。
- 當地社區因排放氣體反對新建玻璃廠。
- 人們對高階市場PET的品質持懷疑態度
- 食品級RPET的供應瓶頸已趨於穩定。
- 供應鏈分析
- 監理展望
- 技術展望
- 波特五力分析
- 葡萄酒包裝領域的重大創新
第5章 市場規模與成長預測
- 材料類型
- 玻璃
- 塑膠
- 金屬
- 紙
- 依產品類型
- 玻璃瓶
- 塑膠瓶
- 盒中袋
- 坎
- 小袋
- 透過封閉法
- 天然軟木
- 技術/合成軟木
- 螺帽
- 皇冠帽
- 其他類型的瓶塞(T型瓶塞、Vino-Lok瓶塞)
- 按葡萄酒類型
- 無氣泡葡萄酒
- 氣泡酒
- 加烈葡萄酒和甜葡萄酒
- 低酒精和無酒精葡萄酒
- 按產能
- 少於 375 毫升
- 375~750 mL
- 750~1,500 mL
- 1500毫升或更多
- 透過分銷管道
- 直銷
- 間接銷售
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Owens-Illinois Inc.
- Ardagh Group SA
- Gallo Glass Company
- Verallia North America
- Ball Corporation
- Amcor plc
- Crown Holdings Inc.
- Silgan Holdings Inc.
- Scholle IPN
- Tetra Laval International SA
- Plastipak Holdings Inc.
- CCL Industries Inc.
- Avery Dennison Corp.
- Berlin Packaging LLC
- TricorBraun Inc.
- Saxco International LLC
- Encore Glass Inc.
- Saverglass
- Guala Closure Group
- Smurfit Westrock
第7章 市場機會與未來展望
According to Mordor Intelligence, the United States wine packaging market size was valued at USD 1.06 billion in 2025 and estimated to grow from USD 1.12 billion in 2026 to reach USD 1.46 billion by 2031, at a CAGR of 5.47% during the forecast period (2026-2031).
This report is Segmented by Material Type (Glass, Plastic, Metal, Paper), Product Type (Glass Bottles, and More), Closure Type (Natural Cork, Technical/Synthetic Cork, and More), Wine Type (Still Wine, Sparkling Wine, and More), Capacity (Less Than 375 ML, and More), Distribution Channel (Direct Sales, and Indirect Sales), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
United States Wine Packaging Market Trends and Insights
Rising Demand for Lightweight Eco-Glass
Glass suppliers are cutting bottle weight to curb freight emissions and control surging input costs. O-I's Estampe bottle dropped to 390 g while pushing recycled content to 82%, lowering its carbon impact by 25% relative to legacy 500 g designs. Napa and Sonoma wineries saw glass-container price indexes jump 16% in 2024, reinforcing the economic case for lighter stock. Verallia's new all-electric furnace cut process CO2 by 60%, signaling long-term commitment to decarbonized glass supply. As freight makes up roughly 35% of delivered glass-package emissions, each 10% weight reduction can trim shipping emissions by nearly 3%, a compelling trade-off for premium wineries that must now publish Scope 3 footprints.
Booming Canned-Wine Sales in Off-Premise Channels
Aluminum's 100% recyclability, low mass, and venue acceptance have lifted the format from novelty to mainstream. Ball shipped 48 billion aluminum beverage containers across North America in 2024, crossing the 30% penetration mark for the first time. Consumer trials show younger drinkers value portability over tradition, and venues from stadiums to beaches prefer non-breakable packages. Quality hurdles linked to hydrogen-sulfide formation are being mitigated by improved liners that vary by manufacturer. Brands such as Bogle's Element[AL] have launched 90 g aluminum bottles that ship at one-fifth the mass of glass while retailing at premium price points.
Volatile Natural-Gas Costs Inflating Domestic Glass Production
Energy expenses account for roughly 20% of glass plant overhead, and spikes in natural-gas prices have prompted closures such as Ardagh's Houston facility, which idled 220 workers in 2024. O-I disclosed a 4.5% drop in 2024 sales volume as buyers shifted toward cheaper or lighter alternatives. While companies are retrofitting furnaces with oxy-fuel or electric systems, capital requirements slow fleet turnover, keeping price volatility in play for the near term.
Other drivers and restraints analyzed in the detailed report include:
- DtC Shipping Liberalisation Across 47 States
- Bottle-Deposit Laws Increasing Recycled-Content Requirements
- Premium-Segment Scepticism Toward PET Quality Perception
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Glass accounted for 66.65% of the United States wine packaging market share in 2025, equal to about USD 706.5 million within the United States wine packaging market size. Metal, led by aluminum, is projected to post an 8.31% CAGR through 2031 as brands prioritize lighter weights and closed-loop recycling credentials. Glass suppliers are countering with 390 g eco-bottle launches and higher cullet ratios that lower furnace energy use while preserving premium shelf presence. Paper composites and refillable-glass systems remain niche but signal the next wave of low-carbon formats that could erode glass share if supply chains scale.
Aluminum's ascent hinges on reduced freight cost, 100% recyclability, and venue acceptance where breakage is a concern, while glass retains an authenticity advantage for premium cues. Ball's plan to reach 85% recycled content by 2030 exemplifies the aggressive sustainability targets that drive material substitution. Glass makers are investing in electric furnaces and oxy-fuel burners to shield margins from natural-gas volatility, yet capital intensity slows fleet turnover. Ultimately, wineries are weighing carbon disclosures against brand heritage, prompting a gradual mix shift rather than an abrupt material handoff.
Glass bottles captured 56.12% of the 2025 value, but cans are expanding at a 7.74% CAGR as portability, recyclability, and event-venue policies favor unbreakable formats. Hydrogen-sulfide risks linked to can liner chemistry are being mitigated through improved internal coatings, opening the door for broader varietal adoption. Bag-in-box remains entrenched for bulk and value wines because vineyard labor shortages push producers toward formats that minimize handling. Plastic bottles and pouches serve price-sensitive or single-serve occasions but face premium-image headwinds.
Canned presentations align with younger demographics that prioritize environmental responsibility over tradition, evidenced by Bogle's 90 g aluminum bottle introduction at USD 16.99 retail. Bottlers are also experimenting with resealable ends and secondary paper wraps to upgrade shelf visibility. For glass, lightweighting and emboss-free silhouettes are helping retain relevance by trimming freight emissions without compromising perceived quality. The result is a diversified product mix that lets wineries match pack type to channel, price tier, and consumption occasion.
Complete Report Scope:
- By Material Type
- Glass
- Plastic
- Metal
- Paper
- By Product Type
- Glass Bottles
- Plastic Bottles
- Bag-in-Box
- Cans
- Pouches
- By Closure Type
- Natural Cork
- Technical/Synthetic Cork
- Screw Caps
- Crown Caps
- Other Closure Types (T-stoppers, Vino-Lok)
- By Wine Type
- Still Wine
- Sparkling Wine
- Fortified and Dessert Wine
- Low and No-Alcohol Wine
- By Capacity
- Less than 375 mL
- 375-750 mL
- 750-1,500 mL
- More than 1,500 mL
- By Distribution Channel
- Direct Sales
- Indirect Sales
List of Companies Covered in this Report:
- Owens-Illinois Inc.
- Ardagh Group S.A.
- Gallo Glass Company
- Verallia North America
- Ball Corporation
- Amcor plc
- Crown Holdings Inc.
- Silgan Holdings Inc.
- Scholle IPN
- Tetra Laval International S.A.
- Plastipak Holdings Inc.
- CCL Industries Inc.
- Avery Dennison Corp.
- Berlin Packaging LLC
- TricorBraun Inc.
- Saxco International LLC
- Encore Glass Inc.
- Saverglass
- Guala Closure Group
- Smurfit Westrock
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for lightweight eco-glass
- 4.2.2 Booming canned-wine sales in off-premise channels
- 4.2.3 DtC shipping liberalisation across 47 states spurring e-commerce-ready packs
- 4.2.4 Bottle-deposit laws (OR, MI) increasing recycled-content requirements
- 4.2.5 Vineyard labour shortages shifting bulk formats toward bag-in-box
- 4.2.6 Private-label retailers scaling cost-efficient PET/BIB volumes
- 4.3 Market Restraints
- 4.3.1 Volatile natural-gas costs inflating domestic glass production
- 4.3.2 Community resistance to new glass plants on emissions grounds
- 4.3.3 Premium-segment scepticism toward PET quality perception
- 4.3.4 Plateauing food-grade RPET supply bottlenecks
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Consumers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Major Innovations in Wine Packaging
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Glass
- 5.1.2 Plastic
- 5.1.3 Metal
- 5.1.4 Paper
- 5.2 By Product Type
- 5.2.1 Glass Bottles
- 5.2.2 Plastic Bottles
- 5.2.3 Bag-in-Box
- 5.2.4 Cans
- 5.2.5 Pouches
- 5.3 By Closure Type
- 5.3.1 Natural Cork
- 5.3.2 Technical/Synthetic Cork
- 5.3.3 Screw Caps
- 5.3.4 Crown Caps
- 5.3.5 Other Closure Types (T-stoppers, Vino-Lok)
- 5.4 By Wine Type
- 5.4.1 Still Wine
- 5.4.2 Sparkling Wine
- 5.4.3 Fortified and Dessert Wine
- 5.4.4 Low and No-Alcohol Wine
- 5.5 By Capacity
- 5.5.1 Less than 375 mL
- 5.5.2 375-750 mL
- 5.5.3 750-1,500 mL
- 5.5.4 More than 1,500 mL
- 5.6 By Distribution Channel
- 5.6.1 Direct Sales
- 5.6.2 Indirect Sales
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Owens-Illinois Inc.
- 6.4.2 Ardagh Group S.A.
- 6.4.3 Gallo Glass Company
- 6.4.4 Verallia North America
- 6.4.5 Ball Corporation
- 6.4.6 Amcor plc
- 6.4.7 Crown Holdings Inc.
- 6.4.8 Silgan Holdings Inc.
- 6.4.9 Scholle IPN
- 6.4.10 Tetra Laval International S.A.
- 6.4.11 Plastipak Holdings Inc.
- 6.4.12 CCL Industries Inc.
- 6.4.13 Avery Dennison Corp.
- 6.4.14 Berlin Packaging LLC
- 6.4.15 TricorBraun Inc.
- 6.4.16 Saxco International LLC
- 6.4.17 Encore Glass Inc.
- 6.4.18 Saverglass
- 6.4.19 Guala Closure Group
- 6.4.20 Smurfit Westrock
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 葡萄酒包裝:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 葡萄酒桶市場規模、佔有率和成長分析:按材質、產能、烘焙程度、最終用戶和地區分類-2026-2033年產業預測
 瓦楞紙運輸箱市場規模、佔有率、成長和行業分析:按類型、產品類型、最終用途、地區分類,並預測至2034年
 葡萄酒包裝袋市場 - 全球產業規模、佔有率、趨勢、機會、預測:按類型、應用、分銷管道、地區和競爭格局分類,2021-2031年
 可重複使用桶市場:按材料類型、烘焙類型、最終用途行業和地區分類。葡萄酒包裝盒市場:按類型、分銷管道和地區分類
 葡萄酒及汽水配件市場:商機、成長要素、產業趨勢分析及2026-2035年預測
 葡萄酒包裝市場規模、佔有率、趨勢和預測:按材料、包裝類型和地區分類,2026-2034年
 葡萄酒包裝市場:依包裝類型、瓶蓋類型和瓶身尺寸分類-2026-2032年全球預測
 2026年全球葡萄酒桶市場報告