


 |
市場調查報告書
商品編碼
2115063
施工機械附件:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Construction Machinery Attachment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
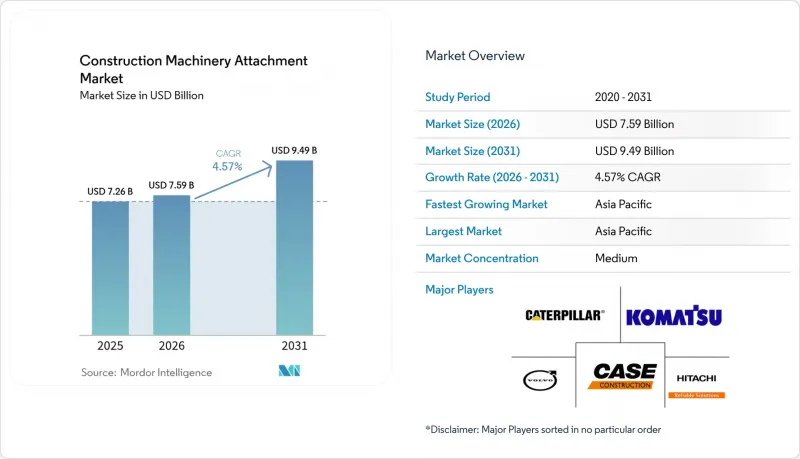
根據 Mordor Intelligence 預測,施工機械附件市場將從 2025 年的 72.6 億美元成長到 2026 年的 75.9 億美元,然後在 2031 年達到 94.9 億美元,2026 年至 2031 年的複合年成長率為 4.57%。
本報告按設備類型(鏟鬥、抓斗等)、設備等級(挖土機附件、滑移裝載機附件等)、連接系統(銷式、專用快換接頭等)、應用領域(建築、林業等)、銷售管道(OEM、售後市場等)和地區進行細分。市場預測以美元計價。
全球施工機械附件市場趨勢及洞察
加速對新興市場的基礎建設投資
印度的「國家基礎設施管道」計畫和其他項目正在推動對堅固耐用、易於維護的附件的需求,這些屬具適用於惡劣的工作環境以及維護設施有限的場所。在農村道路、地鐵項目和住宅建設計畫等項目的推動下,印度施工機械產業的目標是到2030年從85億美元成長到250億美元。中國原始設備製造商(OEM)正積極響應這一需求,推出採用價值工程技術的附件,這些屬具配備簡化的液壓系統和本地採購的鋼材,並由區域工廠提供支持,從而縮短前置作業時間並降低關稅風險。隨著OEM尋求接近性高成長市場,這一趨勢正在重塑價值鏈,並展現出更深層的在地化。
對高效附件的需求日益成長
隨著利潤率的下降,建築公司正優先考慮產能和降低燃料成本,加速採用高流量液壓系統和精密工具。傾斜旋轉器正是此轉變的象徵,由於其360°旋轉功能、降低定位難度和減輕操作員疲勞,其複合年成長率高達5.86%。能源回收錘與傳統型號相比,可降低高達15%的燃料消耗,而內建感測器可將資料傳輸到現場分析平台,以便及早發現維護需求。生態系統思維促成了整合工作流程的創建,該流程整合了快速連接器、自動化控制和遠端資訊處理技術,從而實現了高效的進度安排和更短的專案週期。
熟練的附件操作員短缺
產業研究表明,到2030年,需要新增73,500名技術人員來操作先進的附件,但人才培養體系卻未能跟上需求。操作複雜的傾斜旋轉器和智慧連接器需要掌握液壓、電子和診斷的知識。高達40%的停機時間是由於操作員失誤造成的,這推高了專案成本。原始設備製造商(OEM)贊助的培訓機構、微證書專案和模擬器平台旨在彌補這一缺口,但人才獲取仍然是短期部署計劃中的一個瓶頸。
細分市場分析
由於鏟鬥用途廣泛,可用於挖掘、物料輸送附件施工機械施工機械附件即可快速更換以減少停機時間,預計其複合年成長率將達到5.05%。
成長趨勢凸顯了模組化設計的趨勢。製造商擴大採用LIN總線感測器和RFID標籤來即時追蹤運作週期和維護需求。油壓破碎機在城市維修和拆除項目中需求不斷成長,而抓斗在林業和廢棄物處理領域的應用也日益廣泛。螺旋鑽在通訊溝槽和電線杆安裝方面保持著穩定的訂單。隨著回收法規的日益嚴格,專用剪切機和破碎機的需求也不斷成長。該領域未來的發展取決於競爭激烈的附件品牌以及能夠使用單一連接器連接且不影響性能的互通性標準。
到2025年,挖土機附件將佔施工機械附件市場佔有率的47.20%,這反映了挖土機作為主要土方作業平台的地位。隨著大型機械在人口密集城區使用受到限制,緊湊型履帶裝載機附件的成長速度最快,複合年成長率達7.01%。隨著租賃公司增加與90馬力級載具相容的挖溝機、刨床和冷銑床頭的庫存,預計與緊湊型裝載機相關的施工機械附件市場規模將快速成長。
由於成本績效,滑移裝載機附件在小規模承包商中持續受到歡迎,而後鏟式裝載機附件則被廣泛應用於市政公共工程項目中。輪式裝載機叉和裝載鏟鬥仍然是散裝物料搬運的主要工具。小型挖土機附件受益於住宅掩埋的建設,傾斜式平地鏟鬥的市場佔有率也不斷擴大。加長型堆高機平台在夾層樓板施工和工業貨架安裝方面的需求正在逐步成長。供應商們正競相開發雲端連接控制系統,以自動將液壓流量微調至每個附件的最佳設定。
區域分析
預計到2025年,亞太地區將以46.10%的市佔率引領施工機械附件市場,並在2031年之前維持5.18%的複合年成長率。中國的脫碳藍圖正在加速電動運輸工具的普及,三一重工和徐工集團等國內整車製造商正向市場推出符合當地排放氣體法規的專用破碎錘、抓斗和挖溝機。在政府基礎主導措施的推動下,印度2024會計年度的施工機械銷售量成長了26%,達到135,650台。東南亞國家正將「一帶一路」計劃的投資重點轉向收費公路和港口建設,從而增加了對挖泥鏟鬥和長臂拆除附件的需求。
北美仍然是第二大市場,5,500億美元的基礎設施投資和就業項目推動了橋樑維修、鐵路升級和供水系統維修。儘管2024年運輸工具銷售下降,但對附件的需求轉向了能夠提高現場運轉率的高價值工具。在加拿大,由於人手不足迫使承包商採用能夠減少操作員工作時間的技術,傾斜旋轉器的應用正在增加。在加州和紐約州,隨著各州政策收緊排放氣體法規,電動附件已開始迅速普及。
在歐洲,由於都市區嚴格的法規,低噪音和低振動系統備受重視。沃爾沃的目標是到2030年實現全系列純電動輕量化設備,為此,製造商們正在改進全電動小型挖土機的附件。在德國,精密操縱桿控制的連接器的研發正引領著歷史建築的維修。在英國和法國,政府利用維修補貼來支持節能建築維修,這增加了對能夠減少手部振動的破碎錘和帶有抑塵功能的剪切機的需求。在東歐市場,價格是關鍵因素,隨著高速公路擴建工程的加速推進,翻新附件和本地翻新車間更受青睞,以最大限度地利用預算。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 加速對新興市場的基礎建設投資
- 對高效附件的需求日益成長
- 租賃車輛的擴張需要多功能工具
- 電氣化轉型正在推動低振動工具的廣泛應用。
- 相容於 BIM 的 Smart-ID附件可實現預測性維護。
- 採用輕質複合材料設計,以滿足碳排放配額要求
- 市場限制因素
- 熟練的附件操作員短缺
- 特殊鋼供應鏈的可變性
- 先進液壓工具的初始成本較高
- 關於物聯網附件中資料所有權的擔憂
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
- 永續性和循環經濟分析
第5章 市場規模與成長預測
- 依設備類型
- 桶
- 抓鉤
- 油壓破碎機
- 螺旋鑽
- 快速接頭
- 開膛手
- 破碎機
- 剪切機
- 碎枝機
- 其他
- 依設備類型
- 挖土機附件
- 滑移裝載機附件
- 小型履帶裝載機附件
- 後鏟式裝載機附件
- 輪式裝載機附件
- 小型挖土機的附件
- 加長型堆高機附件
- 其他
- 耦合系統
- 別針式
- 專用快速接頭
- 通用快速接頭
- 傾斜旋轉器
- 自動液壓耦合器
- 透過使用
- 建造
- 拆除和退役
- 採礦和採石
- 林業
- 農業和園林綠化
- 廢棄物和回收
- 除雪和道路維護
- 其他
- 按銷售管道
- OEM
- 售後市場
- 租賃
- 按地區
- 北美洲
- 美國
- 加拿大
- 其他北美國家
- 南美洲
- 巴西
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 澳洲和紐西蘭
- 其他亞太國家
- 中東和非洲
- 土耳其
- 南非
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Caterpillar Inc.
- Komatsu Ltd.
- Volvo Construction Equipment
- Hitachi Construction Machinery
- Hyundai Construction Equipment
- Case Construction Equipment
- JCB
- Liebherr Group
- Sany Group
- Develon(Doosan Infracore)
- Kubota Corporation
- Takeuchi Manufacturing
- Wacker Neuson
- Epiroc AB
- Manitou Group
第7章 市場機會與未來展望
According to Mordor Intelligence, the construction machinery attachment market size is expected to grow from USD 7.26 billion in 2025 to USD 7.59 billion in 2026 and is forecast to reach USD 9.49 billion by 2031 at 4.57% CAGR over 2026-2031.
This report is Segmented by Equipment Type (Buckets, Grapplers, and More), Equipment Class (Excavator Attachments, Skid-Steer Loader Attachments, and More), Coupling System (Pin-On, Dedicated Quick Coupler, and More), Application (Construction, Forestry, and More), Sales Channel (OEM, Aftermarket, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Construction Machinery Attachment Market Trends and Insights
Accelerated Infrastructure Spend in Emerging Markets
Programs such as India's National Infrastructure Pipeline elevate demand for robust, easy-service attachments suitable for rugged sites and limited workshop access. India's construction equipment sector targets USD 25 billion by 2030, up from USD 8.5 billion, on the back of rural roads, metro projects, and housing missions. Chinese OEMs respond with value-engineered tools that use simplified hydraulics and local steel grades, backed by regional plants that cut lead times and tariff exposure. These moves recalibrate supply chains and signal deeper localization as OEMs chase proximity to high-growth markets.
Rising Demand for High-Efficiency Attachments
Contractors prioritize throughput and fuel savings as margins tighten, driving widespread adoption of high-flow hydraulics and precision tooling. Tiltrotators illustrate the shift, recording a 5.86% CAGR on the ability to rotate 360°, reduce repositioning, and ease operator fatigue . Energy-recapture hammers now cut fuel use by up to 15% over conventional units, while integrated sensors feed job-site analytics platforms that flag maintenance needs early. Ecosystem thinking links quick couplers, automated controls, and telematics into a unified workflow that supports lean scheduling and shorter project cycles.
Scarcity of Skilled Attachment Operators
Industry surveys indicate 73,500 new technicians are needed by 2030 to support advanced tooling, yet training pipelines lag. Complex tiltrotators and smart couplers demand hydraulic, electronic, and diagnostic literacy. Up to 40% of downtime links to operator error, inflating project costs. OEM-sponsored academies, micro-credential programs, and simulator platforms aim to fill gaps, but talent availability remains a chokepoint in near-term deployment plans.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Rental Fleets Requiring Multi-Purpose Tools
- Electrification Retrofits Boosting Low-Vibration Tools
- Specialty-Steel Supply-Chain Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Buckets accounted for 43.12% of the construction machinery attachment market in 2025, owing to their universal applicability across excavation, material handling, and quarrying. The construction machinery attachment market size for buckets is projected to climb steadily as infrastructure renewal sustains baseline demand. Quick couplers, while holding a smaller slice, are set for a 5.05% CAGR as fleet managers value rapid, tool-free swaps that minimize idle time.
Growth patterns underline a pivot to modular design. Manufacturers increasingly embed LIN-bus sensors and RFID tags that track cycle counts and maintenance needs in real time. Hydraulic hammers ride renovation and teardown work in urban cores, whereas grapples gain in forestry and waste transfer. Augers maintain steady orders from telecom trenching and utility pole installation. Specialty shears and pulverizers find traction as recycling mandates tighten. The segment's future hinges on interoperability standards that let one coupler mate with competing attachment brands without performance loss.
Excavator attachments represented 47.20% construction machinery attachment market share in 2025, reflecting excavators' role as the primary earthmoving platform. Compact track loader tools grow fastest at 7.01% CAGR as jurisdictions restrict full-size machines in dense downtown corridors. The construction machinery attachment market size tied to compact loaders is forecast to climb sharply as rental depots expand inventories of trenchers, planers, and cold-milling heads sized for 90 hp carriers.
Skid-steer loader tools remain popular among small contractors for cost-effectiveness, whereas backhoe loader add-ons serve municipal utility jobs. Wheel loader forks and rehandling buckets continue as bulk-material workhorses. Mini-excavator attachments benefit from residential infill construction, with tilting grading buckets gaining share. Telehandler platforms see incremental demand in mezzanine builds and industrial racking installs. Suppliers race to develop cloud-linked control systems that automatically fine-tune hydraulic flows to each attachment's optimum setting.
Complete Report Scope:
- By Equipment Type
- Buckets
- Grapples
- Hydraulic Hammers
- Augers
- Quick Couplers
- Rippers
- Pulverizers
- Shears
- Mulchers
- Others
- By Equipment Class
- Excavator Attachments
- Skid-Steer Loader Attachments
- Compact Track Loader Attachments
- Backhoe Loader Attachments
- Wheel Loader Attachments
- Mini-Excavator Attachments
- Telehandler Attachments
- Others
- By Coupling System
- Pin-On
- Dedicated Quick Coupler
- Universal Quick Coupler
- Tiltrotator
- Automatic Hydraulic Coupler
- By Application
- Construction
- Demolition and Decommissioning
- Mining and Quarrying
- Forestry
- Agriculture and Landscaping
- Waste and Recycling
- Snow Removal and Road Maintenance
- Others
- By Sales Channel
- OEM
- Aftermarket
- Rental
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Turkey
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific led the construction machinery attachment market with a 46.10% footing in 2025 and is predicted to log a 5.18% CAGR through 2031. China's decarbonization roadmap accelerates electric carrier deployment, prompting indigenous OEMs such as Sany and XCMG to roll out purpose-built hammers, grapples, and trenchers that match local emissions targets. In FY2024, bolstered by the government's infrastructure-driven initiatives, India witnessed a 26% surge in construction equipment sales, totaling 135,650 units. Southeast Asian nations channel Belt and Road investments into toll roads and ports, elevating demand for dredging buckets and long-reach demolition attachments.
North America remains the second-largest region, anchored by the USD 550 billion Infrastructure Investment and Jobs Act pipeline that spurs bridge repair, rail upgrades, and water-system overhauls. While carrier sales dipped in 2024, attachment demand shifted to high-value tools that lift job-site utilization. Adoption of tiltrotators rises in Canada, where labor scarcity pushes contractors toward technology that saves operator time. Electric-ready attachments gain early traction in California and New York as state policies tighten emissions caps.
Europe prioritizes low-noise, low-vibration systems, catalyzed by dense urban regulations. Manufacturers refine attachments for all-electric compact excavators as Volvo targets fully electric light equipment portfolios by 2030 . Germany spearheads precision joystick-controlled couplers for historical building renovations. The United Kingdom and France funnel renovation subsidies into energy-efficient building retrofits, boosting demand for hand-arm-vibration-reduced breakers and dust-suppression shears. Eastern European markets emphasize affordability, favoring refurbished attachments and local rebuild shops to stretch budgets while ramping up highway expansions.
- Caterpillar Inc.
- Komatsu Ltd.
- Volvo Construction Equipment
- Hitachi Construction Machinery
- Hyundai Construction Equipment
- Case Construction Equipment
- JCB
- Liebherr Group
- Sany Group
- Develon (Doosan Infracore)
- Kubota Corporation
- Takeuchi Manufacturing
- Wacker Neuson
- Epiroc AB
- Manitou Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerated Infrastructure Spend in Emerging Markets
- 4.2.2 Rising Demand for High-Efficiency Attachments
- 4.2.3 Expansion of Rental Fleets Requiring Multi-Purpose Tools
- 4.2.4 Electrification Retrofits Boosting Low-Vibration Tools
- 4.2.5 BIM-Ready Smart-ID Attachments Enable Predictive Maintenance
- 4.2.6 Lightweight Composite Designs to Meet Carbon Quotas
- 4.3 Market Restraints
- 4.3.1 Scarcity of Skilled Attachment Operators
- 4.3.2 Specialty-Steel Supply-Chain Volatility
- 4.3.3 High Upfront Cost of Advanced Hydraulic Tools
- 4.3.4 Data-ownership concerns in IoT-enabled attachments
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Sustainability and Circular Economy Analysis
5 Market Size and Growth Forecasts (Value, USD)
- 5.1 By Equipment Type
- 5.1.1 Buckets
- 5.1.2 Grapples
- 5.1.3 Hydraulic Hammers
- 5.1.4 Augers
- 5.1.5 Quick Couplers
- 5.1.6 Rippers
- 5.1.7 Pulverizers
- 5.1.8 Shears
- 5.1.9 Mulchers
- 5.1.10 Others
- 5.2 By Equipment Class
- 5.2.1 Excavator Attachments
- 5.2.2 Skid-Steer Loader Attachments
- 5.2.3 Compact Track Loader Attachments
- 5.2.4 Backhoe Loader Attachments
- 5.2.5 Wheel Loader Attachments
- 5.2.6 Mini-Excavator Attachments
- 5.2.7 Telehandler Attachments
- 5.2.8 Others
- 5.3 By Coupling System
- 5.3.1 Pin-On
- 5.3.2 Dedicated Quick Coupler
- 5.3.3 Universal Quick Coupler
- 5.3.4 Tiltrotator
- 5.3.5 Automatic Hydraulic Coupler
- 5.4 By Application
- 5.4.1 Construction
- 5.4.2 Demolition and Decommissioning
- 5.4.3 Mining and Quarrying
- 5.4.4 Forestry
- 5.4.5 Agriculture and Landscaping
- 5.4.6 Waste and Recycling
- 5.4.7 Snow Removal and Road Maintenance
- 5.4.8 Others
- 5.5 By Sales Channel
- 5.5.1 OEM
- 5.5.2 Aftermarket
- 5.5.3 Rental
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Rest of North America
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 India
- 5.6.4.3 Japan
- 5.6.4.4 South Korea
- 5.6.4.5 Australia and New Zealand
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Turkey
- 5.6.5.2 South Africa
- 5.6.5.3 Rest of Middle East and Africa
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Caterpillar Inc.
- 6.4.2 Komatsu Ltd.
- 6.4.3 Volvo Construction Equipment
- 6.4.4 Hitachi Construction Machinery
- 6.4.5 Hyundai Construction Equipment
- 6.4.6 Case Construction Equipment
- 6.4.7 JCB
- 6.4.8 Liebherr Group
- 6.4.9 Sany Group
- 6.4.10 Develon (Doosan Infracore)
- 6.4.11 Kubota Corporation
- 6.4.12 Takeuchi Manufacturing
- 6.4.13 Wacker Neuson
- 6.4.14 Epiroc AB
- 6.4.15 Manitou Group
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

 全球施工機械附件市場規模、佔有率、趨勢及成長分析報告(2026-2034)
 施工機械附件市場規模、佔有率和趨勢分析報告:按設備類型、設備等級、銷售管道、應用、地區和細分市場預測(2026-2033 年)
 堆高機橫樑市場:依產品類型、材料、應用和最終用戶分類,全球預測,2026-2032年卡車連桿總成市場(依設備類型、產品類型、最終用戶和通路分類),全球預測(2026-2032)青貯卸料鏟鬥市場按產品類型、驅動類型、容量、應用和最終用戶分類,全球預測(2026-2032)
 2026年全球施工機械附件市場報告
 施工機械附件市場-全球產業規模、佔有率、趨勢、機會及預測(依設備類型、銷售管道、地區及競爭格局分類,2021-2031年)
 全球施工機械附件市場