


 |
市場調查報告書
商品編碼
2114921
泡棉膠帶:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Foam Tape - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
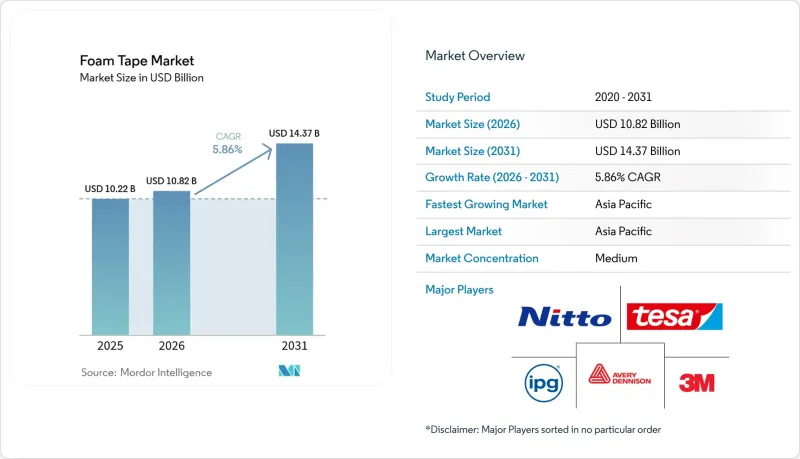
據 Mordor Intelligence 稱,2025 年泡棉膠帶市場價值為 102.2 億美元,預計到 2031 年將達到 143.7 億美元,而 2026 年為 108.2 億美元,預測期(2026-2031 年)的複合年成長率為 5.86%。
本報告按泡沫類型(聚乙烯、聚氨酯、氯丁橡膠、丙烯酸等)、膠帶類型(單面泡棉膠帶、雙面泡棉膠帶)、樹脂類型(橡膠、矽膠、丙烯酸、EVA等)、技術(溶劑型、水性等)、終端用戶產業(汽車、建築、電氣和電子等)以及地區(亞太地區分類、北美地區等)對產業分類。
全球泡沫膠帶市場趨勢及洞察
對維修工程的需求迅速成長
維修計畫旨在20年內將美國建築物的排放量減少73%,而泡棉膠帶有助於阻隔熱橋,且不會增加結構負荷。 《通貨膨脹控制法案》撥款90億美元用於低收入族群的維修項目,從而將基本客群擴展到商業領域之外。 2024年修訂的《國際建築規範》(IBC)要求外牆材料必須符合更嚴格的火焰傳播指數標準,這將增加對防火泡棉膠帶的需求。歐盟的《包裝和包裝廢棄物法規》也反映了類似的趨勢,該法規建議使用可回收的隔熱系統,以便在拆除過程中進行清潔分類。這些政策推動因素共同作用,使維修成為一個快速成長的產業,將能源效率、安全性和循環經濟完美融合。
電子商務包裝領域迅速轉向使用泡棉膠帶。
在高速運作的自動化履約中心,黏合解決方案比機械封口方式更具優勢。預計到2024年,全球密封和捆紮膠帶市場規模將達到253.6億美元,其中發泡膠帶憑藉降低小包裹網路中的破損率而不斷擴大市場佔有率。 Aalstrom的可回收基材符合零售商對「可作為生活垃圾回收的包裝」的要求。與充氣緩衝材料相比,其卓越的緩衝性能確保即使在溫度波動的情況下也能可靠地保護貨物。在物流中斷導致服務水準違規處罰力度不斷增加的當下,這一點至關重要。隨著品牌越來越重視包裝可靠性以應對供應鏈的不確定性,這種轉變正在加速,從而推動了高品質泡棉膠帶的穩定普及。
異氰酸酯和石油基原料價格的波動
2024年初,MDI和TDI成本飆升,推高了聚氨酯樹脂價格,擠壓了依賴現貨採購的膠帶加工商的利潤空間。同期,汽車產業需求下降25%,加上原物料成本上漲和銷售量減少,進一步加劇了利潤壓力。沒有長期供應合約的中小型加工商面臨現金流緊張的局面,導致大型企業為了實現規模經濟而掀起了一波收購浪潮。儘管與原料供應商的合作以及非異氰酸酯聚氨酯的研發工作正在進行中,但這些解決方案需要數年的檢驗,因此價格波動只是短期問題。
細分市場分析
聚乙烯憑藉其成熟的供應鏈能夠滿足建築和包裝需求以及低成本優勢,成為該細分市場的主要驅動力,預計到2025年將佔據38.72%的市場佔有率。聚乙烯發泡膠帶的市場規模預計到2025年將達到39.6億美元,但隨著法規促使用戶轉向更環保的化學品,其成長速度正在放緩。其他發泡膠帶,包括生物基和特種配方,正以6.83%的複合年成長率成長,是整個細分市場中成長最快的。聚氨酯產品正面臨歐盟二異氰酸酯法規帶來的不利影響,該法規正促使市場需求轉向本質上危害性較低的丙烯酸和矽酮產品。
源自玉米和蓖麻油的生物基聚氨酯可減少30-50%的碳足跡,萬華的聚醚多元醇現已符合汽車產業的壓縮永久變形和剪切強度標準。弗勞恩霍夫研究所的FOIM技術透過在貼合加工中對薄聚氨酯薄膜進行發泡,避免了生產過程中接觸異氰酸酯,並降低了運輸成本。明尼蘇達州的學術實驗室正在大規模生產源自腰果殼的三嵌段共聚物,該共聚物可在溫和的堆肥條件下分解,同時保持相當的黏合強度。儘管這些發泡進展預示著不久的將來將發生變革,但從規模化生產的經濟性角度來看,傳統聚乙烯在對成本敏感的應用領域仍然具有優勢。
單面膠帶憑藉其在墊圈、縫隙填充和密封條等領域的廣泛應用,預計到2025年將佔總銷售額的61.68%。單面發泡膠帶的市佔率依然強勁,這主要得益於建築公司和原始設備製造商(OEM)對熟悉的施工方法和眾多供應商的青睞。儘管規模較小,但雙面膠帶預計到2031年將保持7.02%的複合年成長率,這得益於其雙面粘合的優勢,可簡化電動汽車電池模組、幕牆面板和電子產品邊框粘合等領域的組裝流程。
艾利丹尼森已將EVB膠帶定位為鉚釘的替代品,用於固定結構部件,其設計應用使每件產品的成本增加了5到10美元。 Tesa的「按需剝離」系列產品允許使用低溫工具進行拆卸,從而實現設備維修,符合家用電子電器的循環設計準則。雖然通用單面膠帶市場仍然受價格主導,但OEM認證週期為高階雙面膠帶產品線提供了穩定性,以更高的利潤率抵消了絕對銷量的下降。
區域分析
預計到2025年,亞太地區將主導市場,佔全球銷售額的41.63%,並將以6.72%的複合年成長率保持領先地位至2031年。中國作為電動車和家用電器生產基地,佔最大市場佔有率;而印度在生產連結獎勵計畫計畫(PLI)的支持下,電子產業正經歷兩位數成長。韓國和日本則在半導體和先進材料領域推動高階需求。中國針對汽車內裝的VOC排放法規正在加速超低排放膠帶的普及,隨著這些標準擴展到出口市場,全球供應商被迫先獲得符合中國標準的認證。
在北美,受《通膨控制法案》相關90億美元維修資金的支持,市場呈現穩定成長態勢。發泡膠帶適用於窗戶防水、外牆接縫和暖通空調管道維修,無需重型機械即可實現快速施工週期。索諾科公司已投資3,000萬美元擴建其位於奧蘭多的黏合劑包裝產能,這反映了其對該地區市場需求的信心。近岸外包技術的進步使墨西哥成為全球第四大聚氨酯消費國,從而能夠向美國汽車工廠提供短距離供應。在北美,擁有UL和NFPA認證的供應商更受青睞,因為這些認證可以加快市政許可的批准流程。
在歐洲,嚴格的環保法規與材料創新之間需要取得平衡。 2023年實施的二異氰酸酯法規正促使用戶轉向丙烯酸和矽酮基體系。聖戈班以10.25億美元收購福斯羅克,便是旨在強化其建築產品系列的行業重組的一個例證。德國汽車製造商(OEM)指定在輕量化車身面板中使用阻燃黏合劑,而法國航太業則要求客艙內裝使用FST認證的發泡材。歐盟循環經濟政策強制要求可回收利用,促進了單一材料結構的研究與發展。將這些永續解決方案出口到其他大洲,有助於歐洲總部多元化收入。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 維修工程需求激增
- 電子商務包裝材料正迅速轉向泡棉膠帶。
- 電動車電池組組裝中的輕量化努力
- 高速自動模切機的介紹
- 根據《建築標準法》提高外牆的耐火性能
- 市場限制因素
- 異氰酸酯和石油基原料價格波動劇烈
- 溶劑生產線的VOC排放有嚴格的規定。
- 難以回收的多層發泡複合材料
- 價值鏈分析
- 波特五力模型
第5章 市場規模與成長預測
- 依表單類型
- 聚乙烯(PE)
- 聚氨酯(PU)
- 丙烯酸纖維
- 氯丁橡膠
- 其他類型的泡沫(例如生物基泡沫)
- 磁帶類型
- 一邊
- 雙面
- 依樹脂類型
- 丙烯酸纖維
- 橡皮
- 矽酮
- 乙烯-醋酸乙烯酯共聚物(EVA)
- 其他樹脂類型(環氧樹脂、生物基樹脂等)
- 透過技術
- 溶劑型
- 水溶液
- 熱熔膠
- 按最終用戶行業分類
- 建造
- 車
- 電氣和電子設備
- 航太
- 包裝
- 其他終端用戶產業(食品飲料等)
- 按地區
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 東南亞國協
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 北歐國家
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- 3F GmbH Klebe-& Kaschiertechnik.
- 3M
- AVERY DENNISON CORPORATION
- Berry Global Inc.
- CCL Design
- HALCO
- IPG(Intertape Polymer Group)
- LAMATEK, Inc.
- LINTEC Corporation.
- Lohmann
- Lynvale Ltd
- Nitto Denko Corporation.
- Rogers Corporation
- RPM International Inc
- Saint-Gobain
- Shurtape Technologies, LLC
- Teraoka Seisakusho co.,Ltd.
- tesa Tapes(India)Private Limited
- Wuxi Canaan Adhesive Technology Co., Ltd
第7章 市場機會與未來展望
According to Mordor Intelligence, the foam tape market size was valued at USD 10.22 billion in 2025 and estimated to grow from USD 10.82 billion in 2026 to reach USD 14.37 billion by 2031, at a CAGR of 5.86% during the forecast period (2026-2031).
This report Segments the Industry Into Foam Type (Polyethylene, Polyurethane, Neoprene, Acrylic, and More), Tape Type (Single Sided Foam Tape, Double Sided Foam Tape), Resin Type (Rubber, Silicone, Acrylic, EVA, and More), Technology (Solvent-Based, Water-Based, and More), End-User Industry (Automotive, Construction, Electrical and Electronics, and More), and Geography (Asia-Pacific, North America, and More).
Global Foam Tape Market Trends and Insights
Booming Retrofit Construction Demand
Retrofit programs aim for a 73% emission cut in US buildings over twenty years, and foam tapes help close thermal bridges without adding structural load. The Inflation Reduction Act allocates USD 9 billion to low-income retrofit projects, broadening the customer base beyond commercial segments. Updated 2024 International Building Code provisions require facade materials to meet tougher flame-spread indices, lifting demand for fire-rated foam tapes. Similar direction in the EU Packaging and Packaging Waste Regulation promotes recyclable insulation systems that enable clean separation during deconstruction. The combined policy push positions retrofit as a fast-growing avenue where energy savings, safety, and circularity converge.
Rapid E-commerce Packaging Shift to Foam Tape
Automated fulfillment centers run at high line speeds that reward adhesive solutions over mechanical closures. The global sealing and strapping tapes market reached USD 25.36 billion in 2024, and foam tapes capture share by lowering damage rates in parcel networks. Ahlstrom's recyclable backings answer retailer mandates for curb-side-recyclable packaging. Superior cushioning versus air-filled dunnage keeps goods secure across temperature swings, a decisive factor while logistics disruptions elevate service-level penalties. The shift is amplified as brands adopt packaging reliability as a hedge against supply chain unpredictability, driving steady uptake of premium foam tapes.
Volatile Isocyanate & Petro-feedstock Prices
MDI and TDI costs spiked in early 2024, pushing polyurethane resin prices higher and eroding margins for tape converters reliant on spot purchasing. Automotive demand dropped 25% the same quarter, magnifying margin strain as raw material surcharges met falling volumes. Smaller converters without long-term supply contracts faced cash-flow stress, triggering acquisitions by larger players seeking scale economies. Alliances with feedstock suppliers and R&D into non-isocyanate polyurethanes are under way, but these solutions need multi-year validation, keeping volatility a near-term concern.
Other drivers and restraints analyzed in the detailed report include:
- Lightweighting Push in EV Battery Pack Assembly
- High-speed Automated Die-cutting Adoption
- Stringent VOC Emissions Limits on Solvent Lines
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyethylene led the segment with 38.72% share in 2025 thanks to mature supply chains and low cost that satisfy construction and packaging demand. The foam tapes market size for polyethylene equates to USD 3.96 billion in 2025, but growth moderates as regulations drive users toward greener chemistries. Other foam types that include bio-based and specialty formulations expand at a 6.83% CAGR, the highest in the segment mix. Polyurethane variants face headwinds from EU diisocyanate training rules, and this constraint diverts volume into acrylic and silicone options that offer inherently lower hazard profiles.
Bio-based polyurethane derived from corn and castor oil delivers 30-50% lower carbon footprints, and Wanhua's polyether polyols now meet automotive standards for compression set and shear. Fraunhofer's FOIM technology, where thin polyurethane foil puffs into foam during lamination, removes isocyanate exposure during production while cutting shipping volume. Academic labs in Minnesota are scaling cashew-shell triblock copolymers that match adhesion strength yet degrade under mild composting conditions. These breakthroughs signal an impending shift, although scale-up economics still favor conventional PE in cost-sensitive jobs.
Single-sided tapes commanded 61.68% revenue in 2025 relying on their versatility for gasketing, gap filling, and weather stripping. The foam tapes market share for single-sided stands resilient as contractors and OEMs value familiar installation and broad supplier choice. Double-sided tapes, while smaller, post 7.02% CAGR through 2031 on the strength of EV battery modules, facade panels, and electronic bezel bonding where two-way adhesion cuts assembly steps.
Avery Dennison has positioned its EVB tapes to replace rivets in structural attachments, winning design-ins that add USD 5-10 per vehicle. tesa's Debonding on Demand series allows device repair by releasing with low-heat tools, meeting circular-design guidelines in consumer electronics. Commodity single-sided products remain a price-driven arena, but OEM qualification cycles provide stickiness for premium double-sided lines, offsetting lower absolute volumes with healthier contribution margins.
Complete Report Scope:
- By Foam Type
- Polyethylene (PE)
- Polyurethane (PU)
- Acrylic
- Neoprene
- Other Foam Types (Bio-based, etc.)
- By Tape Type
- Single-Sided
- Double-Sided
- By Resin Type
- Acrylic
- Rubber
- Silicone
- Ethyl Vinyl Acetate (EVA)
- Other Resin Types (Epoxy, Bio-based, etc,)
- By Technology
- Solvent-Based
- Water-Based
- Hot-Melt
- By End-User Industry
- Construction
- Automotive
- Electrical and Electronics
- Aerospace
- Packaging
- Other End-user Industries (Food and Beverage, etc.)
- By Geography
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific dominated with 41.63% revenue share in 2025 and leads at a 6.72% CAGR to 2031. China accounts for the largest slice through its EV and consumer electronics production hubs, while India supplies double-digit electronics growth supported by the Production Linked Incentive scheme. South Korea and Japan push premium demand in semiconductors and advanced materials. VOC rules in Chinese car interiors accelerated adoption of ultra-low-emission tapes, and these standards ripple into export markets, compelling global suppliers to certify to Chinese thresholds first.
North America shows steady growth underpinned by USD 9 billion in retrofit funding tied to the Inflation Reduction Act. Foam tapes fit window flashing, facade joints, and HVAC ducting upgrades, enabling fast project cycles without heavy gear. Sonoco invests USD 30 million to scale adhesive packaging capacity in Orlando, signaling confidence in regional demand. Near-shoring pushes Mexico to become the fourth-largest polyurethane consumer, offering short-haul supply for US automotive plants. The continent rewards suppliers with UL and NFPA approvals that speed municipal permitting.
Europe balances strict environmental compliance with materials innovation. The diisocyanate training regulation effective in 2023 nudged users toward acrylic and silicone systems. Saint-Gobain's USD 1.025 billion FOSROC acquisition illustrates consolidation aimed at strengthening construction chemistry portfolios. Germany's OEMs specify flame-retardant adhesives in lightweight body panels, while France's aerospace sector demands FST-rated foams for cabin interiors. EU circularity policies enforce recyclability, prompting R&D into mono-material architectures. Export of these sustainable solutions to other continents supports revenue diversification for European headquarters.
- 3F GmbH Klebe- & Kaschiertechnik.
- 3M
- AVERY DENNISON CORPORATION
- Berry Global Inc.
- CCL Design
- HALCO
- IPG (Intertape Polymer Group)
- LAMATEK, Inc.
- LINTEC Corporation.
- Lohmann
- Lynvale Ltd
- Nitto Denko Corporation.
- Rogers Corporation
- RPM International Inc
- Saint-Gobain
- Shurtape Technologies, LLC
- Teraoka Seisakusho co.,Ltd.
- tesa Tapes (India) Private Limited
- Wuxi Canaan Adhesive Technology Co., Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Booming retrofit construction demand
- 4.2.2 Rapid e-commerce packaging shift to foam tape
- 4.2.3 Lightweighting push in EV battery pack assembly
- 4.2.4 High-speed automated die-cutting adoption
- 4.2.5 Building-code fire-safety upgrades for facades
- 4.3 Market Restraints
- 4.3.1 Volatile isocyanate & petro-feedstock prices
- 4.3.2 Stringent VOC emissions limits on solvent lines
- 4.3.3 Recycling-unfriendly multi-layer foam composites
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size & Growth Forecasts (Value)
- 5.1 By Foam Type
- 5.1.1 Polyethylene (PE)
- 5.1.2 Polyurethane (PU)
- 5.1.3 Acrylic
- 5.1.4 Neoprene
- 5.1.5 Other Foam Types (Bio-based, etc.)
- 5.2 By Tape Type
- 5.2.1 Single-Sided
- 5.2.2 Double-Sided
- 5.3 By Resin Type
- 5.3.1 Acrylic
- 5.3.2 Rubber
- 5.3.3 Silicone
- 5.3.4 Ethyl Vinyl Acetate (EVA)
- 5.3.5 Other Resin Types (Epoxy, Bio-based, etc,)
- 5.4 By Technology
- 5.4.1 Solvent-Based
- 5.4.2 Water-Based
- 5.4.3 Hot-Melt
- 5.5 By End-User Industry
- 5.5.1 Construction
- 5.5.2 Automotive
- 5.5.3 Electrical and Electronics
- 5.5.4 Aerospace
- 5.5.5 Packaging
- 5.5.6 Other End-user Industries (Food and Beverage, etc.)
- 5.6 By Geography
- 5.6.1 Asia-Pacific
- 5.6.1.1 China
- 5.6.1.2 Japan
- 5.6.1.3 India
- 5.6.1.4 South Korea
- 5.6.1.5 ASEAN Countries
- 5.6.1.6 Rest of Asia-Pacific
- 5.6.2 North America
- 5.6.2.1 United States
- 5.6.2.2 Canada
- 5.6.2.3 Mexico
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 NORDIC Countries
- 5.6.3.8 Rest of Europe
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Argentina
- 5.6.4.3 Rest of South America
- 5.6.5 Middle East and Africa
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 South Africa
- 5.6.5.3 Rest of Middle East and Africa
- 5.6.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.4.1 3F GmbH Klebe- & Kaschiertechnik.
- 6.4.2 3M
- 6.4.3 AVERY DENNISON CORPORATION
- 6.4.4 Berry Global Inc.
- 6.4.5 CCL Design
- 6.4.6 HALCO
- 6.4.7 IPG (Intertape Polymer Group)
- 6.4.8 LAMATEK, Inc.
- 6.4.9 LINTEC Corporation.
- 6.4.10 Lohmann
- 6.4.11 Lynvale Ltd
- 6.4.12 Nitto Denko Corporation.
- 6.4.13 Rogers Corporation
- 6.4.14 RPM International Inc
- 6.4.15 Saint-Gobain
- 6.4.16 Shurtape Technologies, LLC
- 6.4.17 Teraoka Seisakusho co.,Ltd.
- 6.4.18 tesa Tapes (India) Private Limited
- 6.4.19 Wuxi Canaan Adhesive Technology Co., Ltd
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

 雙面泡棉膠帶市場報告:趨勢、預測及競爭分析(至2035年)
 矽酮泡棉密封條市場:全球市場預測,2026-2032年
 耐火聚氨酯泡棉市場規模、佔有率和成長分析:按產品類型、配方類型、應用、最終用途產業、分銷管道和地區分類-2026-2033年產業預測雙面發泡膠帶市場:按材料類型、黏合劑類型、厚度、應用、終端用戶產業和分銷管道分類-2026-2032年全球預測
 2026年全球雙面泡棉膠帶市場報告2026年全球泡棉膠帶市場報告
 泡棉膠帶市場-全球產業規模、佔有率、趨勢、機會、預測:依樹脂類型、技術、泡棉類型、終端用戶產業、地區和競爭格局分類,2021-2031年
 泡沫膠帶市場規模、佔有率、成長分析,按泡沫類型、類型、樹脂、技術、應用、地區 - 按行業預測,2024-2031 年