


 |
市場調查報告書
商品編碼
2113946
中東和非洲輸送機市場:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)Middle East And Africa Conveyors - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,中東和非洲的輸送機市場規模預計將從 2025 年的 10.8 億美元成長到 2026 年的 11.2 億美元,然後從 2026 年到 2031 年以 3.28% 的複合年成長率成長,到 2031 億美元達到 13.1 億美元。
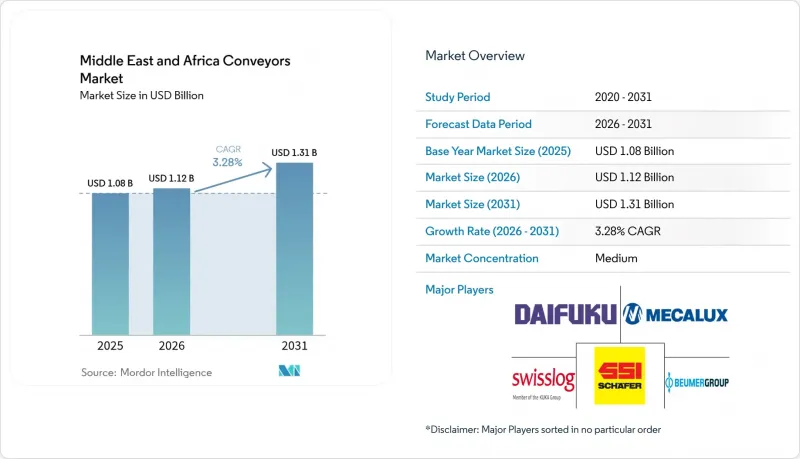
本報告按產品類型(皮帶輸送機、滾筒輸送機、托盤輸送機等)、終端用戶行業(機場、零售/電商、汽車、一般製造業等)、輸送機方向(水平、傾斜、垂直)、安裝位置(落地式、天花板式)和國家/地區進行細分。市場預測以美元計價。
中東和非洲輸送機市場趨勢及洞察。
電子商務的快速成長
預計到2024年,阿拉伯聯合大公國和沙烏地阿拉伯的線上零售滲透率將達到總銷售額的15%,這將進一步擴大消費者需求與履約能力之間的差距。亞馬遜位於利雅德的10萬平方公尺物流中心和Noon位於杜拜的20萬平方公尺擴建項目均採用模組化皮帶輸送機、滾筒輸送機和「貨到人」輸送機,高峰時段每小時可處理超過5000份訂單。經由傑貝阿里港的跨境小包裹數量年增40%,迫使第三方物流公司部署高速匯聚輸送機和自動化海關分類系統。配備RFID讀取器和視覺引導分類裝置的輸送機分類準確率高達99.9%,確保當日送達的承諾得以兌現。隨著履約業者實施多層夾層系統,每平方公尺的傳送帶密度不斷增加,進一步推動了對感測器豐富的模組化平台的需求,這些平台可以按季度而不是按年擴展。
海灣合作理事會地區基礎設施大型企劃的興起
沙烏地阿拉伯耗資5000億美元的「NEOM」計畫和耗資350億美元的「薩勒曼國王國際機場」計畫需要總長超過50公里的骨材和建築材料輸送機,這些輸送機的設計能夠承受50攝氏度的環境溫度和沙漠沙塵暴的侵襲。杜拜南部和卡達旅遊走廊類似的大型開發案也要求採用ISO 50001能源管理標準,這推動了變頻驅動器和再生煞車技術的應用。原始設備製造商(OEM)正在開發太陽能動力傳動系統,並提供混合動力氣動驅動系統,以實現高達40%的碳減排目標。由於競標週期將持續到2030年,因此供應商需要具備靈活的本地組裝能力,以應對外匯波動和進口關稅的大幅上漲。雖然這些項目鞏固了對輸送機的長期需求,但訂單夥伴關係的波動性有利於擁有強大區域合作夥伴關係的供應商。
高初始資本投入
對於標準皮帶和滾筒輸送系統,輸送機的安裝成本通常為每公尺 800 至 2,500 美元,但對於架空電力輸送線路,成本則高達每公尺 8,000 美元。由於進口關稅和貨幣貶值,非洲企業還面臨 15% 至 25% 的額外成本,導致EBITDA獲利率低於 10% 的公司投資回收期超過五年。當地銀行提供的設備租賃選擇有限,這意味著資金籌措缺口仍然存在,迫使中小企業 (SME) 只能選擇低成本的重力滾筒或人工運輸。提供供應商融資和計量收費模式的原始設備製造商 (OEM) 開始開拓“缺少的中間市場”,該市場佔未開發需求的近三分之一。
細分市場分析
到2025年,皮帶輸送機將佔中東和非洲輸送機市場總量的48.12%,並在採礦、機場行李處理和食品加工等應用領域佔據穩固地位,這些應用領域對每米的載重限制為500公斤。滾筒輸送機在一般製造業中主導運輸紙板和托盤,而托盤輸送機則用於運輸重量超過1000公斤的汽車零件。儘管架空輸送系統在絕對規模上較小,但預計到2031年,其複合年成長率將達到5.18%,因為製藥業和多層汽車工廠的無塵室需要無污染的運輸路線和最佳化的占地面積。
Interroll的模組化輸送平台於2024年在阿拉伯聯合大公國和沙烏地阿拉伯的多個履約部署,凸顯了「即插即用」組件的轉變,維護團隊可在四小時內完成重新配置,從而將總生命週期成本降低高達25%。架空式無動力輸送線計劃部署在Lucid Motors的電動車工廠和Sia的沙烏地阿拉伯組裝廠。在這些工廠中,車身面板必須在不阻礙地面交通的情況下通過噴漆、焊接和組裝區域。該領域的一個顯著趨勢是向配備感測器和物聯網功能的平台過渡。這不僅能夠透過預測性維護和軟體主導的吞吐量最佳化來實現狀態監測,還能滿足區域監管要求,例如ISO 50001合規性。
預計到2025年,機場營運商將佔中東和非洲地區輸送帶需求的34.85%,反映了樞紐機場長期以來對行李基礎設施的投資。然而,隨著線上使用量的持續成長,以及當日送達服務的需求從海灣合作理事會國家擴展到埃及和肯亞,零售和電子商務履約中心預計將成為成長最快的領域,到2031年,其複合年成長率將達到6.33%。
食品飲料製造商,例如Al Malaya和雀巢,正在將其輸送機維修為不銹鋼材質,以確保衛生並符合HACCP規範,這導致每個工廠的平均支出增加了40%。同時,製藥業的無塵室需要符合FDA 21 CFR Part 11可追溯性要求的架空式免維護輸送系統,每公尺成本高達1萬美元,但能顯著降低污染風險。電商業者採用醫藥級目視檢測來防止產品損耗,飲料廠也開始部署電商風格的周轉箱輸送機來組裝混合SKU套裝,這些都反映了產業間界線的日益模糊。擁有跨產業實施案例的供應商,正憑藉這一加速融合的趨勢,獲得競爭優勢。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 電子商務的快速成長
- 海灣合作理事會地區基礎設施大型企劃的興起
- 第三方物流公司對倉庫自動化的投資正在加速。
- 機場行李處理系統升級改造正在快速增加。
- 非洲採礦業現代化
- 新建電動車組裝廠
- 市場限制因素
- 高初始資本投入
- 熟練維修人員短缺
- 原物料價格波動
- 非洲OEM和售後服務網路的去中心化
- 產業價值/價值鏈分析
- 監理情勢
- 技術展望
- 宏觀經濟因素對市場的影響
- 波特五力分析
第5章 市場規模與成長預測
- 依產品類型
- 皮帶輸送機
- 滾筒輸送機
- 托盤輸送機
- 高架輸送機
- 螺旋輸送機
- 鍊式輸送機
- 按最終用戶行業分類
- 飛機場
- 零售與電子商務
- 車
- 一般製造業
- 食品/飲料
- 製藥
- 採礦和礦產
- 傳送帶方向
- 橫版
- 斜體字
- 垂直
- 按下輸送機安裝位置
- 落地式
- 吸頂式
- 國家
- 中東
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 卡達
- 阿曼
- 科威特
- 巴林
- 土耳其
- 以色列
- 其他中東國家
- 非洲
- 南非
- 埃及
- 奈及利亞
- 肯亞
- 摩洛哥
- 其他非洲國家
- 中東
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Daifuku Co. Ltd.
- SSI Schaefer AG
- Swisslog Holding AG
- BEUMER Group GmbH and Co. KG
- Mecalux SA
- KNAPP AG
- Kardex Holding AG
- Interroll Holding AG
- CITCOnveyors SRL
- Melco Conveyor Equipment(Pty)Ltd.
- Fives Intralogistics SAS
- Vanderlande Industries BV
- Bastian Solutions LLC
- Dematic Corp.
- FlexLink AB
- Siemens Logistics GmbH
- Dorner Manufacturing Corp.
- Continental AG
- Hytrol Conveyor Company Inc.
- TGW Logistics Group GmbH
- Honeywell Intelligrated
第7章 市場機會與未來展望
According to Mordor Intelligence, the middle east and Africa conveyors market size is expected to grow from USD 1.08 billion in 2025 to USD 1.12 billion in 2026 and is forecast to reach USD 1.31 billion by 2031 at 3.28% CAGR over 2026-2031.
This report is Segmented by Product Type (Belt Conveyors, Roller Conveyors, Pallet Conveyors, and More), End-User Industry (Airport, Retail and E-Commerce, Automotive, General Manufacturing, and More), Conveyor Orientation (Horizontal, Inclined, and Vertical), Conveyor Location (Floor-Mounted, and Overhead-Mounted), and Country. The Market Forecasts are Provided in Terms of Value (USD).
Middle East And Africa Conveyors Market Trends and Insights
Rapid Growth Of E-Commerce
Online retail penetration in the UAE and Saudi Arabia rose to 15% of total sales in 2024, magnifying the gap between consumer demand and fulfillment capacity. Amazon's 100,000-square-meter Riyadh facility and Noon's 200,000-square-meter Dubai expansion both rely on modular belt, roller, and goods-to-person conveyors capable of processing more than 5,000 orders per hour in peak periods. Cross-border parcel inflows via Jebel Ali climbed 40% year over year, forcing 3PLs to deploy high-speed merge conveyors and automated customs sortation. Conveyors equipped with RFID readers and vision-guided diverters deliver 99.9% sort accuracy, ensuring compliance with same-day delivery promises. As fulfillment operators adopt multi-level mezzanines, conveyor intensity per square meter is rising, further amplifying demand for sensor-rich modular platforms that can be re-scaled quarterly rather than annually.
Rise Of Infrastructure Megaprojects Across GCC
Saudi Arabia's USD 500 billion NEOM and USD 35 billion King Salman International Airport projects require more than 50 kilometers of aggregate, baggage, and construction conveyors engineered for 50 °C ambient temperatures and desert sandstorms. Similar large-scale developments in Dubai South and Qatar's tourism corridors specify ISO 50001 energy management, catalyzing uptake of variable-frequency drives and regenerative braking. OEMs are building solar-ready power trains and offering hybrid electric-pneumatic drives to meet embodied-carbon reduction targets of up to 40%. Tender cycles that run through 2030 necessitate flexible local assembly capacity so suppliers avoid foreign-exchange swings and import-duty spikes. These projects cement long-term conveyor demand yet create lumpy order patterns that favor vendors with robust regional partnerships.
High Initial Capital Expenditure
Typical conveyor installations cost USD 800-2,500 per linear meter for standard belt and roller systems, escalating to USD 8,000 per meter for overhead power-and-free lines. African operators incur an extra 15-25% because of import duties and currency depreciation, stretching payback periods beyond five years for companies running on sub-10% EBITDA margins. Financing gaps persist as local banks offer limited equipment-leasing products, nudging SMEs toward low-cost gravity rollers or manual handling. OEMs that provide vendor financing and pay-per-use models are beginning to unlock the "missing-middle" segment representing nearly one-third of untapped demand.
Other drivers and restraints analyzed in the detailed report include:
- Accelerating Warehouse Automation Investments By 3PLs
- Surge In Airport Baggage-Handling System Upgrades
- Limited Skilled Maintenance Workforce
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Belt conveyors represented 48.12% of the Middle East and Africa conveyors market in 2025, entrenched in mining, airport baggage, and food processing applications where load limits reach 500 kg per meter. Roller conveyors dominate carton and pallet flows in general manufacturing, while pallet conveyors serve heavy automotive sub-assemblies exceeding 1,000 kg. Overhead systems, although smaller in absolute terms, will post a 5.18% CAGR through 2031 as pharmaceutical clean rooms and multi-level automotive plants target contamination-free routing and floor-space optimization.
Interroll's modular conveyor platform, installed across multiple UAE and Saudi fulfillment hubs in 2024, underscores the pivot toward plug-and-play sections that maintenance teams can reconfigure within four-hour windows, cutting total lifecycle costs by up to 25% . Overhead power-and-free lines are slated for Lucid Motors' EV plant and Ceer's Saudi assembly campus, where body panels must traverse painting, welding, and final-assembly zones without obstructing floor traffic. The embedded trend is a migration to sensor-enabled, IoT-ready platforms that allow predictive health monitoring and software-driven throughput optimization, aligning with regional mandates for ISO 50001 compliance.
Airport operators accounted for 34.85% of 2025 demand in the Middle East and Africa conveyors market, reflecting historic investment in hub-airport baggage infrastructure. Yet retail and e-commerce fulfillment centers will record the fastest 6.33% CAGR through 2031 as online penetration climbs and same-day delivery expectations spread from the GCC to Egypt and Kenya.
Food and beverage producers led by Almarai and Nestle are retrofitting stainless-steel hygienic conveyors to satisfy HACCP protocols, raising average spend per facility by 40%. Meanwhile, pharmaceutical clean rooms demand overhead power-and-free systems engineered for FDA 21 CFR Part 11 traceability, driving per-meter costs to USD 10,000 but radically reducing contamination risk. The blurring of segment boundaries is evident as e-commerce operators adopt pharmaceutical-grade vision inspection for shrinkage control, while beverage plants install e-commerce-style tote conveyors for mixed-SKU kitting. Suppliers with cross-sector case studies hold a competitive edge as convergence accelerates.
Complete Report Scope:
- By Product Type
- Belt Conveyors
- Roller Conveyors
- Pallet Conveyors
- Overhead Conveyors
- Screw Conveyors
- Chain Conveyors
- By End-User Industry
- Airport
- Retail and E-Commerce
- Automotive
- General Manufacturing
- Food and Beverage
- Pharmaceuticals
- Mining and Minerals
- By Conveyor Orientation
- Horizontal
- Inclined
- Vertical
- By Conveyor Location
- Floor-Mounted
- Overhead-Mounted
- By Country
- Middle East
- United Arab Emirates
- Saudi Arabia
- Qatar
- Oman
- Kuwait
- Bahrain
- Turkey
- Israel
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Kenya
- Morocco
- Rest of Africa
- Middle East
List of Companies Covered in this Report:
- Daifuku Co. Ltd.
- SSI Schaefer AG
- Swisslog Holding AG
- BEUMER Group GmbH and Co. KG
- Mecalux SA
- KNAPP AG
- Kardex Holding AG
- Interroll Holding AG
- CITCOnveyors SRL
- Melco Conveyor Equipment (Pty) Ltd.
- Fives Intralogistics SAS
- Vanderlande Industries B.V.
- Bastian Solutions LLC
- Dematic Corp.
- FlexLink AB
- Siemens Logistics GmbH
- Dorner Manufacturing Corp.
- Continental AG
- Hytrol Conveyor Company Inc.
- TGW Logistics Group GmbH
- Honeywell Intelligrated
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Growth of E-Commerce
- 4.2.2 Rise of Infrastructure Megaprojects Across GCC
- 4.2.3 Accelerating Warehouse Automation Investments by 3PLs
- 4.2.4 Surge in Airport Baggage Handling System Upgrades
- 4.2.5 Mining Sector Modernization in Africa
- 4.2.6 Greenfield Electric-Vehicle Assembly Plants
- 4.3 Market Restraints
- 4.3.1 High Initial Capital Expenditure
- 4.3.2 Limited Skilled Maintenance Workforce
- 4.3.3 Volatile Raw Material Prices
- 4.3.4 Fragmented OEM and After-Sales Network in Africa
- 4.4 Industry Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Intensity of Competitive Rivalry
- 4.8.5 Threat of Substitutes
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Belt Conveyors
- 5.1.2 Roller Conveyors
- 5.1.3 Pallet Conveyors
- 5.1.4 Overhead Conveyors
- 5.1.5 Screw Conveyors
- 5.1.6 Chain Conveyors
- 5.2 By End-User Industry
- 5.2.1 Airport
- 5.2.2 Retail and E-Commerce
- 5.2.3 Automotive
- 5.2.4 General Manufacturing
- 5.2.5 Food and Beverage
- 5.2.6 Pharmaceuticals
- 5.2.7 Mining and Minerals
- 5.3 By Conveyor Orientation
- 5.3.1 Horizontal
- 5.3.2 Inclined
- 5.3.3 Vertical
- 5.4 By Conveyor Location
- 5.4.1 Floor-Mounted
- 5.4.2 Overhead-Mounted
- 5.5 By Country
- 5.5.1 Middle East
- 5.5.1.1 United Arab Emirates
- 5.5.1.2 Saudi Arabia
- 5.5.1.3 Qatar
- 5.5.1.4 Oman
- 5.5.1.5 Kuwait
- 5.5.1.6 Bahrain
- 5.5.1.7 Turkey
- 5.5.1.8 Israel
- 5.5.1.9 Rest of Middle East
- 5.5.2 Africa
- 5.5.2.1 South Africa
- 5.5.2.2 Egypt
- 5.5.2.3 Nigeria
- 5.5.2.4 Kenya
- 5.5.2.5 Morocco
- 5.5.2.6 Rest of Africa
- 5.5.1 Middle East
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Daifuku Co. Ltd.
- 6.4.2 SSI Schaefer AG
- 6.4.3 Swisslog Holding AG
- 6.4.4 BEUMER Group GmbH and Co. KG
- 6.4.5 Mecalux SA
- 6.4.6 KNAPP AG
- 6.4.7 Kardex Holding AG
- 6.4.8 Interroll Holding AG
- 6.4.9 CITCOnveyors SRL
- 6.4.10 Melco Conveyor Equipment (Pty) Ltd.
- 6.4.11 Fives Intralogistics SAS
- 6.4.12 Vanderlande Industries B.V.
- 6.4.13 Bastian Solutions LLC
- 6.4.14 Dematic Corp.
- 6.4.15 FlexLink AB
- 6.4.16 Siemens Logistics GmbH
- 6.4.17 Dorner Manufacturing Corp.
- 6.4.18 Continental AG
- 6.4.19 Hytrol Conveyor Company Inc.
- 6.4.20 TGW Logistics Group GmbH
- 6.4.21 Honeywell Intelligrated
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 螺旋輸送機市場規模、佔有率和成長分析:按輸送機類型、螺旋類型、應用、最終用戶產業、營運方式和地區分類-2026-2033年產業預測
 冷凍食品輸送機系統市場規模、佔有率和成長分析:按輸送機類型、應用、食品類型、最終用戶和地區分類-2026-2033年產業預測
 升降輸送機市場規模、佔有率和成長分析:按輸送機類型、應用、最終用戶、驅動系統和地區分類-2026-2033年產業預測
 滅菌輸送機市場規模、佔有率和成長分析:按輸送機類型、滅菌技術、應用、最終用戶、自動化程度和地區分類-2026-2033年產業預測
 智慧輸送機自動化市場預測至2034年-按輸送機類型、組件、自動化程度、應用、最終用戶和地區分類的全球分析
 輸送系統市場規模、佔有率、成長、全球產業分析、區域趨勢及2026-2034年預測。
 亞太地區輸送機:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)歐洲輸送機:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)輸送機:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)
 振動輸送機市場-2026-2032年全球市場預測