


 |
市場調查報告書
商品編碼
2113787
英國太陽能發電:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)United Kingdom Solar Power - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,英國太陽能發電市場(以裝置容量計算)預計將從 2026 年的 20.85 吉瓦成長到 2031 年的 32.5 吉瓦,在預測期(2026-2031 年)內複合年成長率為 9.28%。
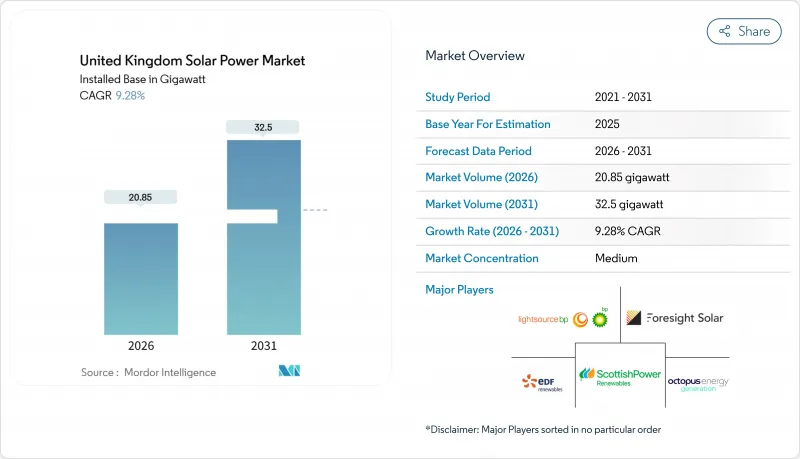
本報告按技術(光伏和聚光型太陽光電)、併網類型(併網和離網)以及最終用戶(大型發電、工商業和住宅)進行細分。市場規模和預測以裝置容量(GW)表示。
英國太陽能市場趨勢與洞察
延長可再生能源強制令(ROE)證書將促進企業購電協議(PPA)的簽訂。
可再生能源授權證書 (ROC) 計畫有效期至 2027 年 3 月,支援 10 至 15 年的購電協議 (PPA),使製造商和資料中心能夠在滿足資訊揭露要求的同時,對沖批發價格波動帶來的風險。集中在蘇格蘭和英格蘭的工業需求吸收了中午時段的發電量,從而降低了發電限制的風險。 ROC 較低的價格上限緩解了初期現金流風險,並促進了中型開發商獲得銀行融資,儘管預計在計劃結束前會出現專案運作高峰。如果 2027 年以後沒有大規模的差價合約 (CFD)競標,相關活動可能會放緩。
在公用事業規模的專案中實現市電平價將加速商業太陽能的發展。
到2024年,隨著平準化發電成本降至每千瓦時0.045英鎊以下,英格蘭南部地區的項目將能夠依靠批發電力收入、嵌入式效益和輔助服務收入。面式組件和單軸追蹤器正在提升發電效率,GRIDSERVE位於約克的電站已證明,整合27兆瓦的儲能系統可確保多種價值來源。商業太陽能專案的可行性研究正在將專案集中在陽光充足的地區,吸引機構投資者資金並降低政策風險。
土地利用規劃的限制正日益成為一個嚴峻的挑戰。
由於被劃為農業用地,在1-3a級土壤上進行太陽能發電受到阻礙,核准流程可能需要18-24個月。薩默塞特郡和北約克郡的項目可能會被拒絕,除非它們能夠證明其用途為雙重用途或棕地位置。垃圾掩埋場土壤修復成本的掩埋進一步擠壓了利潤空間,迫使開發商將目光轉向威爾斯和蘇格蘭。
細分市場分析
預計到2025年,光伏技術將佔據英國太陽能市場100%的佔有率,並在2031年之前以9.3%的複合年成長率成長,這表明英國太陽能市場將繼續主導。北約克郡的現場測試表明,雙面組件的基準值單面組件高出15-17%,這支持了雙面組件的快速普及。半電池和多匯流排設計進一步提高了在低光源條件下的發電量,非常適合英國的漫射太陽輻射特性。
組件創新與逆變器發展趨勢密切相關。串列型逆變器因其成本效益高,在公用事業規模的太陽能電站中佔據主導地位;而微型逆變器則因其能夠減輕煙囪和樹木遮擋的影響,在屋頂光伏電站中日益普及。追蹤系統目前仍屬於小眾市場,但南安普敦大學的測試預計在2026年至2028年間量化雙軸追蹤系統在高緯度地區的價值。這些技術的進步將進一步鞏固其在英國整體太陽能市場中的地位。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 可再生能源強制令(ROC)的延長促進了公司間購電協議(PPA)的簽訂。
- 大型專案實現市電平價正在加速私人太陽能發電的普及。
- 國家電網的電力系統最佳化改革正在促進分散式太陽能發電的進入。
- 英國農業部門脫碳,對農業光電發電的需求日益成長。
- Ofgem 靈活的連接配置提高了電池儲能和太陽能發電的經濟效益。
- 基於英國淨零排放策略的本地化OEM供應鏈獎勵
- 市場限制因素
- 英格蘭「國家規劃政策架構」中的土地利用規劃限制
- 新疆矽模組供應鏈帶來的進口依賴風險
- 英格蘭北部電網堵塞,連接等待時間過長
- 波動性極大的差價合約執行價格限制了小規模專案的資金籌措可能性。
- 供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
- PESTLE分析
第5章 市場規模與成長預測
- 透過技術
- 太陽能發電(PV)
- 聚光型太陽熱能發電(CSP)
- 按網格類型
- 併網
- 離網
- 最終用戶
- 公用事業規模
- 商業和工業(C&I)
- 住宅
- 按成分(定性分析)
- 太陽能模組/面板
- 逆變器(組串式、集中式、微型)
- 安裝和追蹤系統
- 系統平衡和電氣設備
- 儲能和混合整合
第6章 競爭情勢
- 市場集中度
- 策略趨勢(併購、聯盟、購電協議)
- 市場佔有率分析(主要公司的市場排名和佔有率)
- 公司簡介
- Lightsource bp Renewable Energy Investments Ltd
- EDF Renewables UK(Electricite de France SA)
- Octopus Energy Generation
- Foresight Solar Fund Ltd
- ScottishPower Renewables(Iberdrola SA)
- SSE Renewables
- Statkraft UK
- Vattenfall AB
- BayWa re UK Ltd
- First Solar Inc.
- JinkoSolar Holding Co. Ltd
- Canadian Solar Inc.
- Trina Solar Co. Ltd
- Anesco Ltd
- Hive Energy Ltd
- Renewable Energy Systems Ltd
- Ecotricity Group Ltd
- Ameresco Inc.
- NextEnergy Capital Group
- Good Energy Group PLC
第7章 市場機會與未來展望
According to Mordor Intelligence, the United Kingdom solar power market size in terms of installed base is expected to grow from 20.85 gigawatt in 2026 to 32.5 gigawatt by 2031, at a CAGR of 9.28% during the forecast period (2026-2031).
This report is Segmented by Technology (Solar Photovoltaic and Concentrated Solar Power), Grid Type (On-Grid and Off-Grid), and End-User (Utility-Scale, Commercial and Industrial, and Residential). The Market Sizes and Forecasts are Provided in Terms of Installed Capacity (GW).
United Kingdom Solar Power Market Trends and Insights
Renewable Energy Obligation Certificates Extension Spurs Corporate PPAs
The ROC window through March 2027 underpins 10-15-year corporate PPAs, letting manufacturers and data centers hedge volatile wholesale prices while meeting disclosure mandates. Industrial demand clusters in Scotland and England absorb midday generation, lowering curtailment risks. The ROC floor de-risks early cash flows, unlocking bank finance for mid-scale developers, yet a commissioning rush is expected before the mechanism sunsets. Without larger CFD rounds, post-2027 activity could soften.
Grid-Parity Achievement in Utility-Scale Projects Accelerates Merchant Solar
Levelized costs below GBP 0.045 per kWh in 2024 let southern English projects rely on wholesale, embedded-benefit, and ancillary-service revenues. Bifacial modules and single-axis trackers enhance yields, demonstrated by GRIDSERVE's York site, which integrates 27 MW storage to capture multiple value streams. Merchant viability concentrates pipelines in high-irradiance counties, attracting institutional capital and reducing policy risk.
Land-Use Planning Constraints Challenge Expansion
Agricultural land classifications hinder solar on Grade 1-3a soils, extending approvals to 18-24 months. Projects in Somerset and North Yorkshire face rejection unless dual-use or brownfield siting is proven. Elevated remediation costs on landfills further squeeze margins, shifting developers toward Wales and Scotland.
Other drivers and restraints analyzed in the detailed report include:
- National Grid ESO Reform Favors Distributed Participation
- Battery-Coupled Solar Economics Enhanced by Flexible Connection Code
- Import Dependency Risk from Xinjiang Silicon
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solar photovoltaic technology captured 100% of the UK solar power market share in 2025 and is set to grow at a 9.3% CAGR through 2031, keeping the UK solar power market entirely PV-driven. Field tests in North Yorkshire show bifacial modules generating 15-17% more energy than monofacial references, validating rapid bifacial uptake. Half-cell and multi-busbar designs further boost low-light yields, aligning with the nation's diffuse-irradiance profile.
Module innovations dovetail with inverter trends: string inverters dominate utility arrays for cost efficiency, whereas microinverters prosper on rooftops by mitigating chimney and tree shading. Tracking remains niche, yet University of Southampton trials could quantify dual-axis value at high latitudes over 2026-2028. Collectively, these advancements reinforce the technology's lock-in across the UK solar power market.
Complete Report Scope:
- By Technology
- Solar Photovoltaic (PV)
- Concentrated Solar Power (CSP)
- By Grid Type
- On-Grid
- Off-Grid
- By End User
- Utility-Scale
- Commercial and Industrial (C&I)
- Residential
- By Component (Qualitative Analysis)
- Solar Modules/Panels
- Inverters (String, Central, Micro)
- Mounting and Tracking Systems
- Balance-of-System and Electricals
- Energy Storage and Hybrid Integration
List of Companies Covered in this Report:
- Lightsource bp Renewable Energy Investments Ltd
- EDF Renewables UK (Electricite de France SA)
- Octopus Energy Generation
- Foresight Solar Fund Ltd
- ScottishPower Renewables (Iberdrola SA)
- SSE Renewables
- Statkraft UK
- Vattenfall AB
- BayWa r.e. UK Ltd
- First Solar Inc.
- JinkoSolar Holding Co. Ltd
- Canadian Solar Inc.
- Trina Solar Co. Ltd
- Anesco Ltd
- Hive Energy Ltd
- Renewable Energy Systems Ltd
- Ecotricity Group Ltd
- Ameresco Inc.
- NextEnergy Capital Group
- Good Energy Group PLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Renewable Energy Obligation Certificates (ROCs) Extension Spurs Corporate PPAs
- 4.2.2 Grid-Parity Achievement in Utility-scale Projects Accelerating Merchant Solar
- 4.2.3 National Grid's ESO Reform Favouring Distributed Solar Participation
- 4.2.4 Rising Demand for Agri-PV to Decarbonise UK Farming Sector
- 4.2.5 Battery-Coupled Solar Economics Enhanced by Ofgem's Flexible Connection Code
- 4.2.6 OEM Supply-Chain Localisation Incentives Under UK Net-Zero Strategy
- 4.3 Market Restraints
- 4.3.1 Land-Use Planning Constraints in England's National Planning Policy Framework
- 4.3.2 Import Dependency Risk from Xinjiang Silicon Module Supply Chain
- 4.3.3 Grid Congestion & Long Queue Times for Connections in Northern England
- 4.3.4 Volatile CFD Strike Prices Limiting Small-scale Project Bankability
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 PESTLE Analysis
5 Market Size & Growth Forecasts
- 5.1 By Technology
- 5.1.1 Solar Photovoltaic (PV)
- 5.1.2 Concentrated Solar Power (CSP)
- 5.2 By Grid Type
- 5.2.1 On-Grid
- 5.2.2 Off-Grid
- 5.3 By End User
- 5.3.1 Utility-Scale
- 5.3.2 Commercial and Industrial (C&I)
- 5.3.3 Residential
- 5.4 By Component (Qualitative Analysis)
- 5.4.1 Solar Modules/Panels
- 5.4.2 Inverters (String, Central, Micro)
- 5.4.3 Mounting and Tracking Systems
- 5.4.4 Balance-of-System and Electricals
- 5.4.5 Energy Storage and Hybrid Integration
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Lightsource bp Renewable Energy Investments Ltd
- 6.4.2 EDF Renewables UK (Electricite de France SA)
- 6.4.3 Octopus Energy Generation
- 6.4.4 Foresight Solar Fund Ltd
- 6.4.5 ScottishPower Renewables (Iberdrola SA)
- 6.4.6 SSE Renewables
- 6.4.7 Statkraft UK
- 6.4.8 Vattenfall AB
- 6.4.9 BayWa r.e. UK Ltd
- 6.4.10 First Solar Inc.
- 6.4.11 JinkoSolar Holding Co. Ltd
- 6.4.12 Canadian Solar Inc.
- 6.4.13 Trina Solar Co. Ltd
- 6.4.14 Anesco Ltd
- 6.4.15 Hive Energy Ltd
- 6.4.16 Renewable Energy Systems Ltd
- 6.4.17 Ecotricity Group Ltd
- 6.4.18 Ameresco Inc.
- 6.4.19 NextEnergy Capital Group
- 6.4.20 Good Energy Group PLC
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

 2034年太陽能市場預測—全球技術、組件、安裝類型、併網類型、容量、應用、最終用戶、連接類型、所有權類型和區域分析
 中東太陽能市場:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 太陽能電錶市場 - 全球產業規模、佔有率、趨勢、機會、預測:按類型、測量方法、最終用戶、外形規格、地區和競爭格局分類,2021-2031年
 太陽能市場規模、佔有率和成長分析:按技術、應用、最終用戶和地區分類-2026-2033年產業預測
 2026年全球太陽能電能表市場報告
 日本太陽能發電設備市場規模、佔有率、趨勢和預測:按設備類型、應用和地區分類,2026-2034年2026年超高效能太陽能發電全球市場報告
 太陽能即時預測市場:2026-2032年全球預測(依最終用戶、技術、部署類型、預測類型和服務產品分類)
 太陽能光電設備市場規模、佔有率及成長分析(按產品類型、來源、最終用途和地區分類)-產業預測,2026-2033年全球光電市場:預測至2032年-按組件、部署方式、技術、最終用戶和地區分類的分析