


 |
市場調查報告書
商品編碼
2113594
高階摩托車安全帽:市佔率分析、產業趨勢與統計及成長預測(2026-2031)Premium Motorcycle Helmets - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
預計高階摩托車安全帽市場將從 2025 年的 9.7 億美元成長到 2026 年的 10.2 億美元,到 2031 年將達到 13.3 億美元,2026 年至 2031 年的複合年成長率為 5.45%。
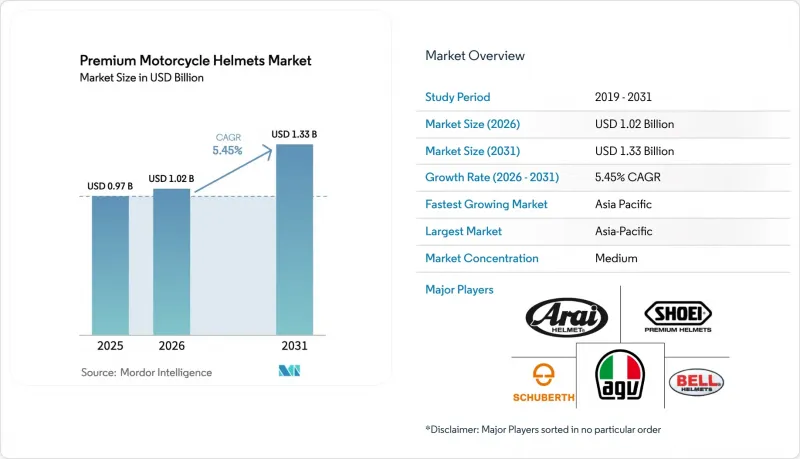
本報告按類型(全罩式安全帽、半罩式安全帽等)、材料(聚碳酸酯、玻璃纖維、碳纖維等)、應用(街道騎乘等)、銷售管道(線下和線上)、最終用戶(通勤者和賽車手)以及地區(北美、南美等)進行細分。市場預測以價值(美元)和銷售(件)為單位呈現。
全球高階摩托車安全帽市場趨勢與洞察
全球安全法規日益收緊
基於ECE 22.06的新測試標準要求進行更高速度的斜向碰撞測試,並將衝擊點數量增加一倍,這使得傳統模具無法使用,並迫使跨區域的測試實驗室加快研發步伐。將於2026年1月生效的賽道賽車認證標準(FRHPhe-02)設定了旋轉加速度的上限,迫使品牌為賽道和公路使用設計不同的安全帽外殼。印度熱帶氣候下的通風法規進一步推動了頭盔形狀設計的本土化,而Snell M2025R標準則將頭盔尺寸標準與職業美式足球中使用的腦震盪閾值保持一致。這些要求雖然累積,增加了認證成本,但也設定了強大的進入門檻,有利於現有製造商。
技術整合(藍牙、HUD)
藍牙對講機和抬頭顯示器已經從笨重的售後套件發展成為重量增加不到50克的完全整合模組。舒伯特C5(Schubert C5)將於2025年投產,它將Cardo的SC-EDGE單元整合到外殼中,降低了4分貝的風噪,並消除了先前令高階買家望而卻步的外露支架。組件的商品化降低了與連接功能相關的溢價,使得大眾市場品牌能夠標準化基本的通訊功能,而超高階品牌則保持了其獨特的市場定位。雖然早期用戶會帶來“光環效應”,但電子設備廣泛普及的關鍵在於確保其抗衝擊性能不受影響。
新興市場零售價格高企
在許多低收入地區,符合ECE標準的正品頭盔零售價在80至150美元之間,而未經認證的仿冒品售價卻不到15美元。稅收政策,例如對大排氣量摩托車配件徵收28%的商品及服務稅,進一步拉大了價格差距。國內製造商正在拓展其中端產品線,以平衡安全性和成本,但由於貨幣貶值和進口關稅的影響,消費者的購買趨勢仍然嚴重偏向聚碳酸酯外殼的頭盔。
細分市場分析
預計到2025年,全罩式安全帽將佔摩托車安全帽總銷量的46.98%,鞏固其在高階摩托車頭盔市場的主導地位,尤其是在運動旅行和賽道騎行領域。然而,隨著越野旅行和長途騎行的日益普及,探險和雙用途頭盔的設計預計將以7.83%的複合年成長率快速成長。 2025年的新款頭盔將配備帽簷、相容護目鏡和可拆卸下巴護罩,在提升通風性能的同時,兼顧高速行駛時的空氣動力學性能。旅行騎士通常更傾向於選擇模組化翻蓋式頭盔,因為其佩戴方便,但許多人也會因為傳統鉸鏈帶來的額外重量而選擇更輕的碳纖維材質頭盔。
不同地區的偏好差異進一步增加了產品線的複雜性。在北美,全罩式安全帽佔據絕對主導地位;在歐洲,半罩式安全帽和全罩式安全帽都比較受歡迎;而在亞太地區的相當一部分地區,半罩式安全帽仍然是通勤的首選。為了應對這種複雜性,各大品牌正在創新,開發出既符合街道騎乘標準又符合賽道標準的多功能頭盔。例如,Shark 的「Aeron」安全帽同時符合 ECE 22.06 和 FIM 8859-2015 標準。這使得零售商只需儲備一個 SKU,即可同時滿足賽車愛好者和日常通勤者的需求,從而提高庫存管理效率並提升客戶價值。
在高階摩托車安全帽市場,玻璃纖維材質佔據主導地位,預計2025年銷售量將佔比將達34.72%。然而,碳纖維頭盔預計到2031年將以5.98%的複合年成長率成長。自動化纖維鋪放和混合層壓等技術進步,使得製造商能夠生產重量低於1200克的頭盔外殼,同時滿足ECE和FIM嚴格的雙重衝擊測試標準。 HJC的2024款F100 Carbon頭盔,定價策略性地低於700歐元(約760美元),使其能夠在與旗艦型號競爭的同時,透過降低人事費用來維持健康的利潤率。雖然熱塑性塑膠和ABS材質的頭盔外殼在入門級價位段佔據主導地位,但在印度和印度尼西亞,受12個月分期付款計劃的普及推動,消費者對複合材料的需求正在顯著成長。
材料選擇已不再僅出於安全考慮,而是成為品牌定位的關鍵要素。例如,高階品牌強調手工精製的碳纖維編織工藝,以證明其超過 800 美元的定價合理。相較之下,中端品牌則巧妙地將玻璃纖維和碳纖維結合使用,在不犧牲性能聲譽的前提下,降低產品價格。內襯技術也取得了進步。一種用於碰撞區域的聚合物材料,能夠吸收約 30% 的斜向衝擊能量,價格也因此增加了 150 美元。然而,由於價格較高,這種材料的應用僅限於探險頭盔,而且消費者通常更願意投資購買能夠增強多次衝擊防護性能的產品。
區域分析
預計到2025年,亞太地區將佔全球摩托車市場價值的38.81%,複合年成長率(CAGR)為6.49%。印度和印尼工資水準的提高正推動消費者從踏板車轉向排氣量超過150cc的摩托車。這種轉變增加了對符合DOT和ECE標準的頭盔的需求。儘管中國是全球最大的摩托車生產國,但其高階安全帽的普及率卻低於全球平均。造成這種差距的主要原因是頭盔佩戴法規執行不力,尤其是在農村地區。像印尼的IMHAX這樣的展會吸引了大量人群,但大多數摩托車的售價卻低於150美元。這凸顯了價格敏感度帶來的挑戰,而高階品牌可以透過提供融資方案和本地組裝來應對這一挑戰。
預計到2031年,北美市場將以3.02%的複合年成長率成長。這項成長主要得益於Liberty Media對MotoGP的策略性投入以及MotoAmerica賽事參與人數的增加。這些因素正在培養賽道騎乘文化,並提升對雙重認證安全帽的需求。儘管全球銷量有所下滑,但Shoei在北美的銷量在2024會計年度仍成長了34.7%,凸顯了市場對該公司精湛工藝的高度認可。此外,加拿大在2024年批准了ECE 22.06標準(除DOT標準外),這拓寬了歐洲製造商的品牌選擇範圍,並降低了其合規成本。
歐洲市場預計將以3.49%的複合年成長率成長。 ECE 22.06標準的採用正在創造一個更公平的競爭環境,尤其是在旋轉衝擊測試方面,縮小高階品牌和中階品牌之間的性能差距。日本主要製造商巧妙地應對外匯波動,並透過漲價來彌補銷售下滑,展現了強大的品牌忠誠度。隨著環保政策的推進,預計這些政策將影響消費者的購買決策。隨著生產者延伸責任制(EPR)法規強調頭盔的可回收性,此趨勢尤其顯著。目前,現有的回收舉措只能處理每年數百萬個廢棄頭盔中的一小部分。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 全球安全法規日益收緊
- 技術整合(藍牙、HUD 等)
- 可支配所得增加和超級摩托車的普及
- 向輕質碳纖維複合材料過渡
- 與保險相關的遠端資訊處理折扣
- 高階安全帽近岸製造
- 市場限制因素
- 新興市場零售價格飆漲
- 一款高品質的仿冒頭盔
- 電子設備的過時以及電子廢棄物的風險
- 碳纖維供應鏈的波動性
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 按類型
- 全罩式安全帽
- 模組化頭盔
- 開放式頭盔
- 半盔
- 材料
- 聚碳酸酯
- 玻璃纖維
- 碳纖維
- 克維拉
- 塑膠/ABS
- 透過使用
- 街頭騎行
- 越野駕駛
- 場地賽
- 透過分銷管道
- 線下(零售店)
- 線上(電子商務)
- 最終用戶
- 通勤者
- 賽車手
- 按地區
- 北美洲
- 美國
- 加拿大
- 其他北美國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 英國
- 德國
- 西班牙
- 義大利
- 法國
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 印度
- 中國
- 日本
- 韓國
- 其他亞太國家
- 中東和非洲
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 土耳其
- 埃及
- 南非
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Shoei Co., Ltd
- Arai Helmet Ltd.
- Schuberth GmbH
- HJC Helmets
- Shark Helmets
- Bell Helmets
- Nolan Group
- Airoh Helmets
- LS2 Helmets
- MT Helmets
- Suomy Motorsport SRL
- Kabuto Helmets
- Scorpion Sports, Inc.(Scorpion EXO)
- Ruroc Ltd.
- MT Helmets
- Sena Technologies
- Forcite
- Alpinestars
第7章 市場機會與未來展望
According to Mordor Intelligence, the premium motorcycle helmets market size is expected to grow from USD 0.97 billion in 2025 to USD 1.02 billion in 2026 and is forecast to reach USD 1.33 billion by 2031 at a 5.45% CAGR over 2026-2031.
This report is Segmented by Type (Full-Face, Modular, and More), Material (Polycarbonate, Fiberglass, Carbon Fiber, and More), Application (Street Riding and More), Distribution Channel (Offline and Online), End-User (Commuters and Racers), and Geography (North America, South America, and More). Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Global Premium Motorcycle Helmets Market Trends and Insights
Stringent Global Safety Regulations
New test matrices under ECE 22.06 require oblique-impact trials at higher velocities and double the number of strike points, rendering legacy molds obsolete and forcing multi-region labs to front-load R&D. Circuit racing homologation (FRHPhe-02), effective January 2026, caps rotational acceleration, compelling brands to design separate shells for track and street. India's tropical-climate ventilation rules further regionalize geometry, while Snell M2025R aligns helmet metrics with concussion thresholds used in professional football. The cumulative requirements raise certification outlays but create durable entry barriers that favor incumbents.
Technological Integration (Bluetooth, HUD)
Bluetooth intercoms and heads-up displays have migrated from bulky aftermarket kits to fully embedded modules that add under 50 grams. A 2025 production run of Schuberth's C5 integrates Cardo's SC-EDGE unit within the shell, cutting wind noise by 4 dB and removing exposed brackets that previously deterred premium buyers. Component commoditization has compressed the connectivity premiums, allowing mass-market brands to standardize basic communication while ultra-premium labels maintain analog positioning. Early adopters create halo demand, but widespread uptake will hinge on warranty assurances that electronics will not compromise impact integrity.
High Retail Prices in Emerging Markets
In many lower-income regions, authentic ECE-compliant helmets retail at USD 80-150, while non-certified look-alikes can be had for under USD 15. Tax structures such as a 28% goods-and-services levy on high-capacity bike accessories widen the affordability gap. Domestic makers are scaling mid-price ranges to reconcile safety and cost, but currency depreciation and import tariffs continue to skew buying toward polycarbonate shells.
Other drivers and restraints analyzed in the detailed report include:
- Rising Disposable Incomes & Superbike Uptake
- Shift Toward Lightweight Carbon-Fiber Composites
- Counterfeit Premium-Look Helmets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, full-face models captured 46.98% of sales, solidifying their dominance in the premium motorcycle helmet market, especially for sport-touring and track uses. Yet, as off-road tourism and overlanding gain traction, adventure and dual-sport helmet designs are set to surge at a 7.83% CAGR. New models for 2025 feature peak visors, goggle compatibility, and removable chin bars, striking a balance between enhanced ventilation and freeway aerodynamics. While touring riders gravitate towards modular flip-ups for their convenience, many are opting for lighter carbon-fiber alternatives, driven by the added weight of traditional hinges.
Regional preferences add layers of complexity to product offerings. North America leans heavily towards full-face sport shells, Europe finds a middle ground with both modular and full-face options, and a significant portion of Asia-Pacific continues to prefer open-face helmets for commuting. To navigate this complexity, brands are innovating by creating versatile shells that cater to both street and track standards. Take Shark's Aeron, for instance: it's compliant with both ECE 22.06 and FIM 8859-2015 standards. This means dealers can stock a single SKU that seamlessly serves both racing enthusiasts and daily commuters, streamlining inventory management and enhancing perceived value.
Fiberglass dominated the premium motorcycle helmet market, accounting for 34.72% of 2025 revenue. However, carbon-fiber units are projected to grow at a 5.98% CAGR through 2031. Owing to advancements like automated fiber placement and hybrid lay-ups, manufacturers are producing shells under 1,200 grams that still meet stringent dual ECE and FIM impact tests. HJC's 2024 F100 carbon, priced below EUR 700 (USD 760), is strategically positioned to undercut rival flagship models while maintaining healthy margins due to reduced labor content. While thermoplastic and ABS shells dominate entry-level price points, consumers in India and Indonesia are making a notable shift to composites, facilitated by financing plans that spread payments over twelve months.
Material selection is evolving beyond mere safety considerations, becoming a pivotal tool for brand positioning. Premium brands, for instance, emphasize hand-finished carbon weaves to justify price tags exceeding USD 800. In contrast, mid-tier brands are ingeniously blending glass and carbon, allowing them to penetrate lower price brackets without compromising on perceived performance. Liner technology is also witnessing advancements: crumple-zone polymers, which absorb approximately 30% more oblique impact energy, come at an incremental cost of USD 150. This price point, however, limits their use to adventure helmets, where buyers are willing to invest more for enhanced multi-impact resilience.
Complete Report Scope:
- By Type
- Full-Face Helmets
- Modular Helmets
- Open-Face Helmets
- Half Helmets
- By Material
- Polycarbonate
- Fiberglass
- Carbon Fiber
- Kevlar
- Plastics / ABS
- By Application
- Street Riding
- Off-Road Riding
- Track Racing
- By Distribution Channel
- Offline (Retail Stores)
- Online (E-commerce)
- By End-User
- Commuters
- Racers
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- Spain
- Italy
- France
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- Egypt
- South Africa
- Rest of Middle-East and Africa
- North America
Geography Analysis
In 2025, the Asia-Pacific region accounted for 38.81% of the market's value and is projected to grow at a CAGR of 6.49%. As salaries rise in India and Indonesia, there's a noticeable shift from scooters to motorcycles exceeding 150 cc. This shift has led to an increased demand for helmets that comply with both DOT and ECE standards. While China holds the title of the world's largest motorcycle producer, the attachment rate of premium helmets lags behind the global average. This discrepancy is largely due to inconsistent enforcement of helmet laws in rural areas. Events like Indonesia's IMHAX draw significant crowds, yet sales predominantly fall below the USD 150 mark. This highlights a price sensitivity challenge that premium brands might address through financing options or local assembly.
North America is projected to grow at a CAGR of 3.02% until 2031. The growth is largely driven by Liberty Media's strategic moves with MotoGP and the increasing attendance at MotoAmerica events. These factors have cultivated a track-day culture with a heightened demand for dual-certified helmets. Despite a global downturn in unit sales, Shoei's North American revenue surged by 34.7% in fiscal 2024, underscoring the market's appreciation for perceived craftsmanship. Furthermore, Canada's 2024 endorsement of the ECE 22.06 standard, in addition to DOT, has expanded brand options and lowered compliance costs for European manufacturers.
Europe is anticipated to witness a growth rate of 3.49% CAGR. The adoption of the ECE 22.06 standard is leveling the playing field, especially in rotational-impact testing, bridging the performance divide between premium and mid-tier brands. Leading Japanese manufacturers have adeptly navigated currency fluctuations, countering volume declines with price hikes, a testament to the strength of brand loyalty. As environmental policies gain traction, they are poised to influence purchasing decisions. This is especially true as extended-producer-responsibility regulations emphasize helmet recyclability. Currently, existing take-back initiatives manage only a small fraction of the millions of discarded units each year.
- Shoei Co., Ltd
- Arai Helmet Ltd.
- Schuberth GmbH
- HJC Helmets
- Shark Helmets
- Bell Helmets
- Nolan Group
- Airoh Helmets
- LS2 Helmets
- MT Helmets
- Suomy Motorsport SRL
- Kabuto Helmets
- Scorpion Sports, Inc. (Scorpion EXO)
- Ruroc Ltd.
- MT Helmets
- Sena Technologies
- Forcite
- Alpinestars
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stringent Global Safety Regulations
- 4.2.2 Technological Integration (Bluetooth, HUD, etc.)
- 4.2.3 Rising Disposable Incomes & Superbike Adoption
- 4.2.4 Shift Toward Lightweight Carbon-Fiber Composites
- 4.2.5 Insurance-Linked Telematics Discounts
- 4.2.6 Near-Shoring of Premium-Helmet Manufacturing
- 4.3 Market Restraints
- 4.3.1 High Retail Prices in Emerging Markets
- 4.3.2 Counterfeit Premium-Look Helmets
- 4.3.3 Electronics Obsolescence & E-Waste Risk
- 4.3.4 Carbon-Fiber Supply-Chain Volatility
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value and Volume)
- 5.1 By Type
- 5.1.1 Full-Face Helmets
- 5.1.2 Modular Helmets
- 5.1.3 Open-Face Helmets
- 5.1.4 Half Helmets
- 5.2 By Material
- 5.2.1 Polycarbonate
- 5.2.2 Fiberglass
- 5.2.3 Carbon Fiber
- 5.2.4 Kevlar
- 5.2.5 Plastics / ABS
- 5.3 By Application
- 5.3.1 Street Riding
- 5.3.2 Off-Road Riding
- 5.3.3 Track Racing
- 5.4 By Distribution Channel
- 5.4.1 Offline (Retail Stores)
- 5.4.2 Online (E-commerce)
- 5.5 By End-User
- 5.5.1 Commuters
- 5.5.2 Racers
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Rest of North America
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 Spain
- 5.6.3.4 Italy
- 5.6.3.5 France
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 India
- 5.6.4.2 China
- 5.6.4.3 Japan
- 5.6.4.4 South Korea
- 5.6.4.5 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 Turkey
- 5.6.5.4 Egypt
- 5.6.5.5 South Africa
- 5.6.5.6 Rest of Middle-East and Africa
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Shoei Co., Ltd
- 6.4.2 Arai Helmet Ltd.
- 6.4.3 Schuberth GmbH
- 6.4.4 HJC Helmets
- 6.4.5 Shark Helmets
- 6.4.6 Bell Helmets
- 6.4.7 Nolan Group
- 6.4.8 Airoh Helmets
- 6.4.9 LS2 Helmets
- 6.4.10 MT Helmets
- 6.4.11 Suomy Motorsport SRL
- 6.4.12 Kabuto Helmets
- 6.4.13 Scorpion Sports, Inc. (Scorpion EXO)
- 6.4.14 Ruroc Ltd.
- 6.4.15 MT Helmets
- 6.4.16 Sena Technologies
- 6.4.17 Forcite
- 6.4.18 Alpinestars
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

 全球摩托車安全帽市場
 摩托車安全帽市場:商機、成長要素、產業趨勢分析及2026-2035年預測
 2026年全球輕型摩托車頭盔市場報告
 全球摩托車頭盔市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 高階摩托車頭盔市場規模、佔有率、趨勢及預測(按類型、材料類型、技術、最終用戶和地區分類),2026-2034年2026年全球摩托車安全帽市場報告
 摩托車頭盔市場 - 全球產業規模、佔有率、趨勢、機會、預測:按材料類型、分銷管道、最終用戶、地區和競爭格局分類,2021-2031年
 運動摩托車頭盔市場按類型、材料、認證標準、分銷管道和最終用戶分類,全球預測(2026-2032)
 高階摩托車安全帽市場規模、佔有率和成長分析(按材料類型、類型、安全標準、通路管道、最終用戶和地區分類)-2026-2033年產業預測
 摩托車安全帽市場規模、佔有率及成長分析(按類型、分銷通路、最終用戶和地區分類)-2026-2033年產業預測