


 |
市場調查報告書
商品編碼
2101650
摩托車安全帽市場:商機、成長要素、產業趨勢分析及2026-2035年預測Motorcycle Helmet Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球摩托車安全帽市場預計到 2025 年將價值 109 億美元,並將以 4.5% 的複合年成長率成長,到 2035 年達到 171 億美元。
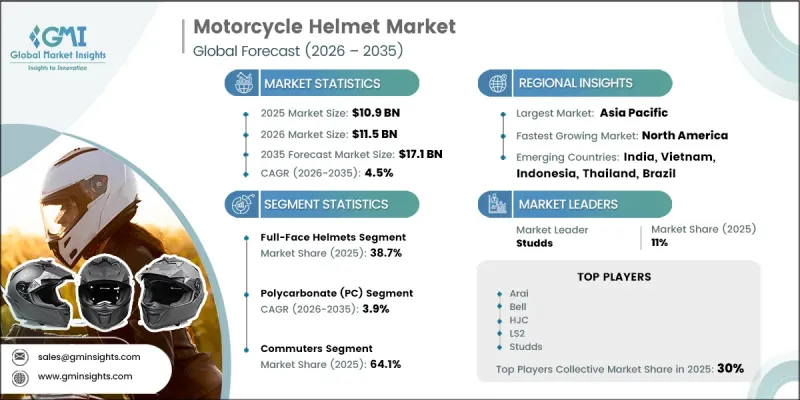
摩托車安全帽產業的成長得益於穩定的更換需求、對認證防護裝備的監管要求以及首次購車者購買量的增加。尤其是在摩托車仍然是實用交通工具的開發中國家,摩托車保有量的持續成長對市場產生了正面影響。同時,在成熟市場,消費者對技術先進、高階頭盔的日益青睞也推動了單價的提升。這種整體成長模式是發展中地區銷售成長和成熟市場產品價值提升共同作用的結果。都市化的加速、人們對摩托車作為日常交通工具的依賴增強以及摩托車出行的成本優勢,持續推動全球安全帽的銷售。摩托車登記數量的增加和安全標準的不斷完善也支撐著長期需求,再加上持續的產品創新和意識提升,全球摩托車安全帽市場的整體成長前景進一步增強。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 109億美元 |
| 預測金額 | 171億美元 |
| 複合年成長率 | 4.5% |
預計到2025年,全罩式安全帽市佔率將達到38.7%,並在2026年至2035年間維持5.2%的複合年成長率。全罩式安全帽因其能夠全面覆蓋騎士頭部和臉部的多個部位,提供更全面的保護,因此持續引領市場,成為注重安全的消費者的首選。消費者對更高防護性能的強烈需求以及對安全法規日益嚴格的遵守,持續推動全罩式安全帽在廣大摩托車用戶中的普及。此外,鼓勵使用符合更高防護標準的安全帽的監管要求也促進了全罩式安全帽市場的發展。
預計到2025年,聚碳酸酯(PC)市佔率將達到54%,並在2035年之前以3.9%的複合年成長率成長。其市場主導地位得益於其優異的性能,包括高效的生產製造、成本效益以及可靠的抗衝擊性,使其能夠符合認證的安全標準。這些特性使得聚碳酸酯成為入門級和中階摩托車頭盔製造中最常用的外殼材料之一,從而支援大規模生產和廣泛的消費市場。
預計到2025年,亞太地區摩托車頭盔市佔率將達到45.1%,並在2026年至2035年間以4.9%的複合年成長率成長。該地區摩托車用戶數量龐大,且多個開發中國家的摩托車交通量持續成長,這為其在亞太地區的市場主導地位提供了有力支撐。摩托車保有量的增加、城市人口的擴張以及騎乘者安全意識的提高,持續推動對認證摩托車頭盔的穩定需求,進一步鞏固了該地區在全球市場的主導地位。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 原物料供應商
- 零件供應商
- 製造商
- 服務供應商
- 分銷管道
- 最終用途
- 成本結構
- 利潤率
- 每個階段增加的價值
- 垂直整合趨勢
- 顛覆者
- 供應商情況
- 影響產業的因素
- 促進因素
- 全球摩托車和二輪車擁有量增加。
- 嚴格的安全帽安全規定
- 騎乘者安全意識不斷提高
- 智慧頭盔越來越受歡迎。
- 市場限制因素
- 豪華頭盔價格昂貴
- 假頭盔的流通狀況
- 市場機遇
- 電子商務銷售成長
- 新興國家摩托車市場的成長
- 探險騎行和摩托車運動日益普及
- 永續製造
- 促進因素
- 成長潛力分析
- 技術與創新展望
- 最新技術
- 新興技術
- 價格分析
- 對過去價格趨勢的分析
- 依球員類型分類的定價策略(高級球員、超值球員、成本加成球員)
- 監管指南
- 北美洲
- 美國國家公路交通安全管理局(NHTSA)
- 美國運輸部(DOT) FMVSS 218 頭盔標準
- 斯內爾紀念基金會認證
- 職業安全與健康管理局(OSHA)
- 加拿大機動車輛安全標準(CMVSS)
- 歐洲
- 聯合國歐洲經濟委員會第22號條例(ECE 22.06)
- CE標誌(個人防護設備法規)
- REACH(化學品註冊、評估、授權和限制)
- 通用產品安全法規 (GPSR)
- 國家型式認可要求
- 亞太地區
- 中國強制產品認證(CCC)
- 印度中央機動車輛法規(CMVR)
- 印度標準局 (BIS) - IS 4151
- 日本工業標準(JIS)
- 澳洲和紐西蘭標準(AS/NZS 1698)
- 拉丁美洲
- 巴西國家計量院(INMETRO)
- 巴西國家交通委員會(CONTRAN)
- 墨西哥官方標準(NOM)
- 區域進口和產品認證要求
- 中東和非洲
- 海灣合作理事會標準組織(GSO)
- 沙烏地阿拉伯標準、計量和品質組織(SASO)
- 阿拉伯聯合大公國計量與標準化局(ESMA)
- 南非國家標準監管機構(NRCS)
- 北美洲
- 貿易數據分析
- 進出口量及進口額趨勢
- 主要貿易路線及關稅的影響
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 生產能力和生產情況
- 設備產能:按地區和主要生產商分類
- 運轉率和擴張計劃
- 成本細分分析
- 專利分析
- 波特的分析
- PESTLE分析
- 消費者購買行為
- 智慧頭盔生態系統
- 認證和測試的現狀
- 永續性和環境方面
- 永續計劃
- 減少廢棄物策略
- 生產中的能源效率
- 具有環保意識的舉措
- 考慮碳足跡
- 預測假設和情境分析
- 基本案例-驅動複合年成長率的關鍵宏觀經濟與產業變量
- 樂觀情境-宏觀經濟與產業的順風
- 悲觀情景-宏觀經濟放緩或產業逆風
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 排名分類標準與遴選標準
- 按銷售額、地區和創新能力分類的層級定位矩陣。
第5章 市場估價與預測:依頭盔類型分類,2022-2035年
- 全罩式安全帽
- 半盔(3/4盔)
- 半盔
- 模組化/翻蓋式頭盔
- 越野/摩托車越野頭盔
- 雙用途/探險頭盔
第6章 市場估計與預測:依外殼材料分類,2022-2035年
- 聚碳酸酯(PC)
- 玻璃纖維複合材料
- 碳纖維
- 先進複合材料(多材料)
第7章 市場估計與預測:依價格區間分類,2022-2035年
- 經濟型(150 美元以下)
- 中價位(150-500美元)
- 高級版(500美元至1000美元)
- 超高級(1000 美元或以上)
第8章 市場估算與預測:依最終用途分類,2022-2035年
- 通勤者
- 專業/賽車手
- 旅行/探險騎手
第9章 市場估價與預測:依摩托車類型分類,2022-2035年
- 主要趨勢
- 巡航自行車
- 運動摩托車
- 旅行自行車
- 標準/裸車
- 探險/雙用途摩托車
- 越野/泥地摩托車
第10章 市場估價與預測:依通路分類,2022-2035年
- 主要趨勢
- 離線
- 專賣店
- 多品牌零售商
- 大賣場和超級市場
- OEM經銷商
- 線上
- 電子商務平台
- 品牌官方網站
第11章 市場估價與預測:按地區分類,2022-2035年
- 主要趨勢
- 北美洲
- 美國
- 加拿大
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 北歐的
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 東南亞
- 印尼
- 馬來西亞
- 新加坡
- 泰國
- 越南
- ANZ
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第12章:公司簡介
- 世界公司
- Arai
- Bell
- Caberg
- LS2
- Nolan
- Schuberth
- Shark
- Shoei
- ScorpionEXO
- 當地公司
- Airoh
- MT Helmets
- Nexx
- NZI
- OGK Kabuto
- Premier
- SMK
- Steelbird
- STUDDS
- Vega
- ZEUS
The Global Motorcycle Helmet Market was valued at USD 10.9 billion in 2025 and is estimated to grow at a CAGR of 4.5% to reach USD 17.1 billion by 2035.
Growth in the motorcycle helmet industry is supported by consistent replacement demand, regulatory requirements for certified protective equipment, and rising purchases from first-time motorcycle owners. The market continues to benefit from expanding motorcycle ownership, particularly in developing economies where two-wheel transportation remains a practical mobility solution. At the same time, mature markets are contributing higher revenue per unit as consumers increasingly prefer technologically advanced and premium helmet products. The overall growth pattern reflects the combination of rising sales volumes in developing regions and greater product value in established markets. Increasing urbanization, growing reliance on motorcycles for daily transportation, and the cost advantages of two-wheel mobility continue to encourage helmet purchases worldwide. Expanding motorcycle registrations and evolving safety standards are also supporting long-term demand, while ongoing product innovation and improved consumer awareness regarding rider protection continue to strengthen growth prospects across the global motorcycle helmet market.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $10.9 Billion |
| Forecast Value | $17.1 Billion |
| CAGR | 4.5% |
The full-face helmet segment accounted for 38.7% share in 2025 and is anticipated to register a CAGR of 5.2% during 2026-2035. The segment continues to lead the market because it offers extensive protection by covering multiple areas of the rider's head and face, making it a preferred choice among safety-focused consumers. Strong demand for enhanced rider protection and increasing compliance with safety regulations continue to support the adoption of full-face helmets across a wide range of motorcycle users. The segment also benefits from regulatory requirements that encourage the use of helmets offering higher protection standards.
The polycarbonate (PC) segment held 54% share in 2025 and is projected to grow at a CAGR of 3.9% through 2035. Its market leadership is supported by a favorable balance of manufacturing efficiency, cost-effectiveness, and reliable impact resistance that enables compliance with recognized safety standards. These characteristics make polycarbonate one of the most widely used shell materials for producing entry-level and mid-range motorcycle helmets while supporting large-scale manufacturing and broad consumer accessibility.
Asia Pacific Motorcycle Helmet Market held 45.1% share in 2025 and is forecast to grow at a CAGR of 4.9% during 2026-2035. Regional market leadership is supported by the large population of motorcycle users and the continued growth of two-wheel transportation across several developing economies. Rising motorcycle ownership, expanding urban populations, and increasing awareness of rider safety continue to generate consistent demand for certified motorcycle helmets, reinforcing the region's dominant position in the global market.
Major companies operating in the global motorcycle helmet market include Studds, Arai, HJC, LS2, Bell, Nolangroup, Shoei, Caberg, Schuberth, and Shark. Companies operating in the motorcycle helmet market are strengthening their market position by investing in product innovation, expanding premium product portfolios, and improving manufacturing capabilities. Many manufacturers continue to focus on lightweight materials, enhanced impact protection, improved ventilation systems, and advanced comfort features to meet evolving consumer preferences. Businesses are also increasing investments in research and development to enhance product performance while complying with changing safety regulations. Expanding distribution networks, strengthening online and offline sales channels, and improving brand visibility remain important strategies for reaching broader customer segments.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation
- 1.7 Forecast
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Helmet
- 2.2.3 Shell Material
- 2.2.4 Price Range
- 2.2.5 End Use
- 2.2.6 Motorcycle
- 2.2.7 Distribution Channel
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.1.1 Raw material suppliers
- 3.1.1.2 Component suppliers
- 3.1.1.3 Manufacturers
- 3.1.1.4 Service providers
- 3.1.1.5 Distribution channel
- 3.1.1.6 End Use
- 3.1.2 Cost structure
- 3.1.3 Profit margin
- 3.1.4 Value addition at each stage
- 3.1.5 Vertical integration trends
- 3.1.6 Disruptors
- 3.1.1 Supplier landscape
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising global motorcycle and two-wheeler ownership
- 3.2.1.2 Stringent helmet safety regulations
- 3.2.1.3 Growing rider safety awareness
- 3.2.1.4 Increasing adoption of smart helmets
- 3.2.2 Market Restraints
- 3.2.2.1 High cost of premium helmets
- 3.2.2.2 Availability of counterfeit helmets
- 3.2.3 Market Opportunities
- 3.2.3.1 Expansion of e-commerce sales
- 3.2.3.2 Growing two-wheeler markets in emerging economies
- 3.2.3.3 Rising adventure riding and motorsports
- 3.2.3.4 Sustainable helmet manufacturing
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Technology and Innovation landscape
- 3.4.1 Current technologies
- 3.4.2 Emerging technologies
- 3.5 Pricing Analysis (Driven by Primary Research)
- 3.5.1 Historical Price Trend Analysis
- 3.5.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
- 3.6 Regulatory guideline
- 3.6.1 North America
- 3.6.1.1 National Highway Traffic Safety Administration (NHTSA)
- 3.6.1.2 U.S. Department of Transportation (DOT) FMVSS No. 218 Helmet Standard
- 3.6.1.3 Snell Memorial Foundation Certification
- 3.6.1.4 Occupational Safety and Health Administration (OSHA)
- 3.6.1.5 Canadian Motor Vehicle Safety Standards (CMVSS)
- 3.6.2 Europe
- 3.6.2.1 UNECE Regulation No. 22 (ECE 22.06)
- 3.6.2.2 CE Marking (Personal Protective Equipment Regulation)
- 3.6.2.3 REACH (Registration, Evaluation, Authorisation and Restriction of Chemicals)
- 3.6.2.4 General Product Safety Regulation (GPSR)
- 3.6.2.5 National Type Approval Requirements
- 3.6.3 Asia Pacific
- 3.6.3.1 China Compulsory Certification (CCC)
- 3.6.3.2 Indian Central Motor Vehicles Rules (CMVR)
- 3.6.3.3 Bureau of Indian Standards (BIS) – IS 4151
- 3.6.3.4 Japanese Industrial Standards (JIS)
- 3.6.3.5 Australian/New Zealand Standard (AS/NZS 1698)
- 3.6.4 Latin America
- 3.6.4.1 Brazilian National Institute of Metrology (INMETRO)
- 3.6.4.2 Brazilian National Traffic Council (CONTRAN)
- 3.6.4.3 Mexican Official Standard (NOM)
- 3.6.4.4 Regional Import and Product Certification Requirements
- 3.6.5 MEA
- 3.6.5.1 GCC Standardization Organization (GSO)
- 3.6.5.2 Saudi Standards, Metrology and Quality Organization (SASO)
- 3.6.5.3 Emirates Authority for Standardization and Metrology (ESMA)
- 3.6.5.4 South African National Regulator for Compulsory Specifications (NRCS)
- 3.6.1 North America
- 3.7 Trade data analysis (Driven by Paid Research)
- 3.7.1 Import/export volume & value trends
- 3.7.2 Key trade corridors & tariff impact
- 3.8 Impact of AI & generative AI on the market
- 3.8.1 AI-driven disruption of existing business models
- 3.8.2 GenAI use cases & adoption roadmap by segment
- 3.8.3 Risks, limitations & regulatory considerations
- 3.9 Capacity & production landscape (Driven by Primary Research)
- 3.9.1 Installed capacity by region & key producer
- 3.9.2 Capacity utilization rates & expansion pipelines
- 3.10 Cost breakdown analysis
- 3.11 Patent analysis (Driven by Primary Research)
- 3.12 Porter’s analysis
- 3.13 PESTEL analysis
- 3.14 Consumer Buying Behavior
- 3.15 Smart Helmet Ecosystem
- 3.16 Certification & Testing Landscape
- 3.17 Sustainability and environmental aspects
- 3.17.1 Sustainable practices
- 3.17.2 Waste reduction strategies
- 3.17.3 Energy efficiency in production
- 3.17.4 Eco-friendly Initiatives
- 3.17.5 Carbon footprint considerations
- 3.18 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.18.1 Base Case — key macro & industry variables driving CAGR
- 3.18.2 Optimistic Scenarios — Favorable macro and industry tailwinds
- 3.18.3 Pessimistic Scenario — Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia-Pacific
- 4.2.4 Latin America
- 4.2.5 Middle East & Africa
- 4.3 Competitive positioning matrix
- 4.4 Key developments
- 4.4.1 Mergers & acquisitions
- 4.4.2 Partnerships & collaborations
- 4.4.3 New product launches
- 4.4.4 Expansion plans and funding
- 4.5 Company tier benchmarking
- 4.5.1 Tier classification criteria & qualifying thresholds
- 4.5.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates & Forecast, By Helmet, 2022 - 2035 ($Mn, Units)
- 5.1 Key trends
- 5.2 Full Face Helmets
- 5.3 Open Face (3/4) Helmets
- 5.4 Half Helmets
- 5.5 Modular/Flip-Up Helmets
- 5.6 Off-Road/Motocross Helmets
- 5.7 Dual-Sport/Adventure Helmets
Chapter 6 Market Estimates & Forecast, By Shell Material, 2022 - 2035 ($Mn, Units)
- 6.1 Key trends
- 6.2 Polycarbonate (PC)
- 6.3 Fiberglass Composite
- 6.4 Carbon Fiber
- 6.5 Advanced Composite (Multi-Material)
Chapter 7 Market Estimates & Forecast, By Price Range, 2022 - 2035 ($Mn, Units)
- 7.1 Key trends
- 7.2 Economy (Below USD 150)
- 7.3 Mid-Range (USD 150–USD 500)
- 7.4 Premium (USD 500–USD 1,000)
- 7.5 Ultra-Premium (Above USD 1,000)
Chapter 8 Market Estimates & Forecast, By End Use, 2022 - 2035 ($Mn, Units)
- 8.1 Key trends
- 8.2 Commuters
- 8.3 Professional/Racing Riders
- 8.4 Touring/Adventure Riders
Chapter 9 Market Estimates & Forecast, By Motorcycle, 2022 - 2035 ($Mn, Units)
- 9.1 Key Trends
- 9.2 Cruiser motorcycles
- 9.3 Sport motorcycles
- 9.4 Touring motorcycles
- 9.5 Standard/naked motorcycles
- 9.6 Adventure/dual-sport motorcycles
- 9.7 Off-road/dirt motorcycles
Chapter 10 Market Estimates & Forecast, By Distribution Channel, 2022 - 2035 ($Mn, Units)
- 10.1 Key Trends
- 10.2 Offline
- 10.2.1 Specialty Stores
- 10.2.2 Multi-Brand Retail Stores
- 10.2.3 Hypermarkets & Supermarkets
- 10.2.4 OEM Dealerships
- 10.3 Online
- 10.3.1 E-commerce Platforms
- 10.3.2 Brand Websites
Chapter 11 Market Estimates & Forecast, By Region, 2022 - 2035 ($Mn, Units)
- 11.1 Key Trends
- 11.2 North America
- 11.2.1 US
- 11.2.2 Canada
- 11.3 Europe
- 11.3.1 UK
- 11.3.2 Germany
- 11.3.3 France
- 11.3.4 Italy
- 11.3.5 Spain
- 11.3.6 Russia
- 11.3.7 Nordics
- 11.4 Asia Pacific
- 11.4.1 China
- 11.4.2 India
- 11.4.3 Japan
- 11.4.4 South Korea
- 11.4.5 Southeast Asia
- 11.4.5.1 Indonesia
- 11.4.5.2 Malaysia
- 11.4.5.3 Singapore
- 11.4.5.4 Thailand
- 11.4.5.5 Vietnam
- 11.4.6 ANZ
- 11.5 Latin America
- 11.5.1 Brazil
- 11.5.2 Mexico
- 11.5.3 Argentina
- 11.6 MEA
- 11.6.1 South Africa
- 11.6.2 Saudi Arabia
- 11.6.3 UAE
Chapter 12 Company Profiles
- 12.1 Global Players
- 12.1.1 Arai
- 12.1.2 Bell
- 12.1.3 Caberg
- 12.1.4 LS2
- 12.1.5 Nolan
- 12.1.6 Schuberth
- 12.1.7 Shark
- 12.1.8 Shoei
- 12.1.9 ScorpionEXO
- 12.2 Regional Players
- 12.2.1 Airoh
- 12.2.2 MT Helmets
- 12.2.3 Nexx
- 12.2.4 NZI
- 12.2.5 OGK Kabuto
- 12.2.6 Premier
- 12.2.7 SMK
- 12.2.8 Steelbird
- 12.2.9 STUDDS
- 12.2.10 Vega
- 12.2.11 ZEUS

 全球摩托車安全帽市場
 高階摩托車安全帽:市佔率分析、產業趨勢與統計及成長預測(2026-2031)
 2026年全球輕型摩托車頭盔市場報告
 全球摩托車頭盔市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 高階摩托車頭盔市場規模、佔有率、趨勢及預測(按類型、材料類型、技術、最終用戶和地區分類),2026-2034年2026年全球摩托車安全帽市場報告
 摩托車頭盔市場 - 全球產業規模、佔有率、趨勢、機會、預測:按材料類型、分銷管道、最終用戶、地區和競爭格局分類,2021-2031年
 運動摩托車頭盔市場按類型、材料、認證標準、分銷管道和最終用戶分類,全球預測(2026-2032)
 高階摩托車安全帽市場規模、佔有率和成長分析(按材料類型、類型、安全標準、通路管道、最終用戶和地區分類)-2026-2033年產業預測
 摩托車安全帽市場規模、佔有率及成長分析(按類型、分銷通路、最終用戶和地區分類)-2026-2033年產業預測