


 |
市場調查報告書
商品編碼
2113453
超音波感測器:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Ultrasonic Sensors - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
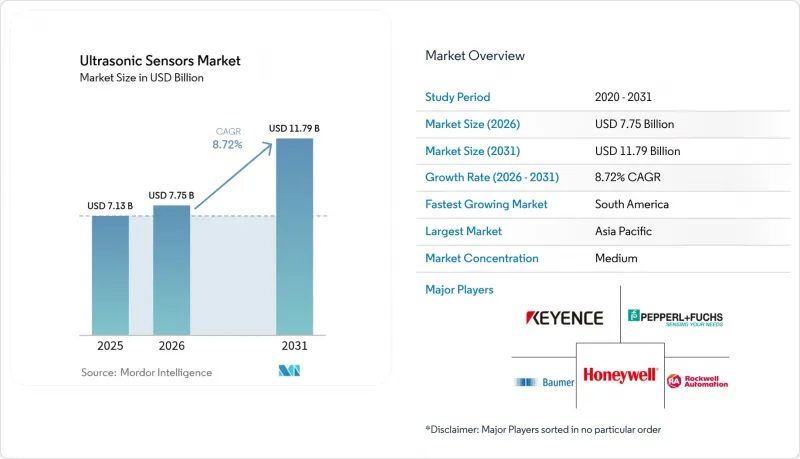
據 Mordor Intelligence 稱,2025 年超音波感測器市值為 71.3 億美元,預計到 2031 年將達到 117.9 億美元,而 2026 年為 77.5 億美元,預測期(2026-2031 年)的複合年成長率為 8.72%。
本報告按技術(例如,體壓電換能器)、產品類型(例如,接近感測器感測器和距離感測器)、偵測範圍(短程、中程和遠端)、安裝方式(例如,直插式/螺紋式)、運作頻率(例如,70 kHz 及以上)、使用者產業(例如,汽車和出行領域)以及地區進行分類。市場預測以美元(USD)計價。
全球超音波感測器市場趨勢及洞察
工業4.0生產單元中高精度超音波感測器的應用日益廣泛
工業4.0生產單元如今需要亞毫米級的精度,這迫使供應商採用電容式被測裝置(MUT),與傳統的陶瓷感測器相比,電容式被測裝置的頻寬拓寬了40%,頻率超過400 kHz。支援IO-Link的設備可將資料傳輸到機器學習模型,並透過基於狀態的警報將意外停機時間減少30%。全球製造商正在將生產能力本地化,以縮短客製化探頭的前置作業時間。例如,OMRON投資920萬美元擴建了其在南卡羅來納州的生產能力。
中國和歐盟的乘用車安全法規強制要求安裝前後障礙物偵測系統。
歐盟GSR2及其對應的中國法規要求所有新型輕型車輛必須配備基於近距離超音波感測的自動緊急煞車和車道維持輔助功能。相關產品的出貨量已從2009年的300萬台激增至2023年的2億台。博世透過將超音波、雷達和攝影機訊號與人工智慧融合演算法結合,來區分行人和靜止物體,從而滿足弱勢道路使用者的需求。
多感測器ADAS叢集在超過10公尺的距離上的訊號衰減
隨著車輛感測器密度的增加,超音波串擾現象會加劇,導致11公尺以外的探測精度下降。目前汽車設計中每輛車配備12至16個感測器,增加了干擾風險。研究證實,大氣變化會進一步放大這些影響,因此雷達和LiDAR的聯合使用至關重要。 Sonair的聲學測距和偵測平台透過將視場角擴展至180度,減少了感測器的數量。
細分市場分析
2025年,得益於經濟高效的大規模生產,用於汽車停車系統的體型壓電換能器將佔據超音波感測器市場64.30%的佔有率。該領域的規模經濟效應使其單位成本保持在較低水準。相較之下,由於醫療成像和精密機器人領域對小型化高頻性能的需求,多單元超音波感測器(MUT)陣列正以12.64%的複合年成長率成長。隨著PMUT在空氣耦合檢測領域表現優異,CMUT在液體耦合成像領域佔據主導地位,與MUT技術相關的超音波感測器市場規模預計將快速擴張。
這種技術轉變反映了陶瓷板在小型化過程中存在的物理限制。基於鈮酸鉀鈉的光電倍增管在10公分的距離上實現了105.5 dB/V的靈敏度,優於同類氮化鋁基產品。與CMOS電子電路的整合簡化了片上波束成形,並降低了智慧型設備的總組件成本。
預計到2025年,接近和距離測量模型將佔銷售額的39.40%,並廣泛應用於汽車保險桿和機器人安全簾等領域。同時,得益於智慧基礎設施項目,液位和深度感測器的複合年成長率預計將達到11.58%。持續監測液位可以降低水處理、化學和食品相關設施的維護頻率。
無線遙測技術將偵測範圍擴展至遠端儲罐,從而實現預測性維護計劃並減少服務車輛的出車次數。超音波探頭能夠檢測清澈液體並穿透罐壁,相比光學和浮球式檢測方法更具優勢,鞏固了其在嚴苛工業環境中的市場領先地位。
區域分析
到2025年,亞洲將佔全球銷售額的37.60%,這主要得益於中國汽車電子產業的快速成長以及日本精密製造的傳統優勢。政府法規正推動超音波近距離感測技術成為新型乘用車的標準配置,而半導體叢集的存在也使得超音波換能器(MUT)的在地化生產成為可能。韓國為感測器提供專用積體電路(ASIC),而印度經濟實惠的汽車市場則促進了成本最佳化設計的應用。政策主導的智慧城市建設支出進一步鞏固了超音波感測器市場在區域基礎設施建設中的地位。
北美正專注於高階細分市場。在美國,用於門診診斷的高頻探頭正在研發中;而在航太領域,耐環境因素影響的探頭則被用於結構完整性監測(SHM)。加拿大的冬季環境也催生了對溫度補償型探頭的需求。 FDA的指導意見簡化了核准流程,使得新型探頭能夠比以往的監管週期更快地部署到醫院和家庭環境中。
歐洲正將監管領導力與產業優勢結合。歐盟的全球戰略參考框架2(GSR2)正在推動汽車產業的需求同步,而德國的機器人叢集則是支援IO-Link的探頭領域的先驅,這些探頭能夠實現即時過程回饋。北歐的公共產業正在尋求能夠承受低至-40 度C低溫的加熱感測器組件,這推動了材料工程領域的突破。同時,南美洲的複合年成長率(CAGR)高達9.76%,位居榜首。隨著礦業公司實現偏遠地區自動化以及各國政府推動供水管網現代化,對穩健的非接觸式測量技術的需求日益成長。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 工業4.0生產單元中高精度超音波感測器的應用日益廣泛
- 根據中國和歐盟乘用車安全法規,乘用車必須安裝前後障礙物偵測系統。
- 非接觸式水位監測技術正在海灣合作理事會國家的智慧供水和污水處理計畫中迅速普及。
- 在醫療即時成像系統中應用高頻(200 kHz 或更高)MUT 陣列。
- 將耐腐蝕PVDF探針引入離岸風力發電。
- 市場限制因素
- 多感測器ADAS叢集在超過10公尺的距離上的訊號衰減
- 北歐-40 度C工作條件下壓電堆的性能漂移
- 穿戴式消費性電子產品超音波暴露限值的監管障礙。
- PMUT晶片與傳統塊狀陶瓷設計之間的價格差異
- 產業價值鏈分析
- 技術展望(小型化PMUT/CMUT晶圓,整合到ASIC中)
- 監管趨勢(ISO 19365、UNECE R159、FDA關於診斷超音波的指南)
- 波特五力分析
- 主要宏觀經濟趨勢評估
第5章 市場規模與成長預測
- 透過技術
- 體壓電換能器
- 微加工超音波換能器(MUT)
- PMUT(壓電式 MUT)
- 電容式被動鏡 (CMUT)
- 依產品類型
- 接近/距離感測器
- 液位/深度測量感測器
- 流量測量感測器
- 超音波成像模組
- 按範圍
- 短距離(小於2公尺)
- 中距離(2-10公尺)
- 遠距離(超過10公尺)
- 按安裝類型
- 直列式/螺紋式
- 街區/側視圖
- 拼接/夾緊式
- 按運作頻率
- 低於 70 kHz
- 71~200 kHz
- 超過 200 千赫茲
- 按最終用戶行業分類
- 工業製造
- 汽車與出行
- 家用電子電器和家用電器
- 醫療保健
- 農業和智慧農業
- 其他(石油及天然氣、船舶等)
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 北歐的
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 其他亞太國家
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 埃及
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Keyence Corporation
- Pepperl+Fuchs AG
- Sick AG
- Honeywell International Inc.
- Omron Corporation
- Rockwell Automation Inc.
- Baumer Ltd
- Murata Manufacturing Co. Ltd
- Banner Engineering Corp.
- Balluff Inc.
- Robert Bosch GmbH
- Qualcomm Incorporated
- TDK Corporation
- Sensata Technologies
- TE Connectivity
- MaxBotix Inc.
- Siemens AG
- Texas Instruments Incorporated
- Hyde Park Electronics LLC
- Denso Corporation
第7章 市場機會與未來展望
According to Mordor Intelligence, the ultrasonic sensors market size was valued at USD 7.13 billion in 2025 and estimated to grow from USD 7.75 billion in 2026 to reach USD 11.79 billion by 2031, at a CAGR of 8.72% during the forecast period (2026-2031).
This report is Segmented by Technology (Bulk Piezoelectric Transducer, and More), Product Type (Proximity and Distance Sensors, and More), Range (Short-Range, Medium-Range, Long-Range), Mounting Type (In-Line/Threaded, and More), Operating Frequency (>= 70 KHz, and More), End-User Vertical (Automotive and Mobility, and More), Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Ultrasonic Sensors Market Trends and Insights
Rising Installation of High-Precision Ultrasonic Sensors in Industry 4.0 Production Cells
Industry 4.0 cells now demand sub-millimeter accuracy, pushing suppliers to adopt capacitive MUTs that achieve > 400 kHz and 40% broader bandwidth than legacy ceramics. IO-Link enabled devices feed machine-learning models that cut unplanned downtime by 30% through condition-based alerts. Global manufacturers localize capacity, exemplified by Omron's USD 9.2 million expansion in South Carolina, to shorten lead times for customized probes
Mandatory Front-Rear Obstacle-Detection Mandates in Chinese and EU Passenger-Car Safety Regulations
EU GSR2 and synchronized Chinese rules compel every new light vehicle to incorporate autonomous emergency braking and lane-keeping functions that rely on close-range ultrasonic sensing. Shipments leapt from 3 million units in 2009 to 200 million in 2023. Bosch couples ultrasonic, radar, and camera signals with AI fusion algorithms that distinguish pedestrians from static objects, meeting vulnerable road user requirements
Signal Attenuation in Multi-Sensor ADAS Clusters Beyond 10 m Ranges
High vehicle sensor density breeds ultrasonic cross-talk that lowers detection accuracy past 11 meters. Automotive designs now integrate 12-16 devices per car, widening interference risks. Research confirms that atmospheric variations magnify these effects, making radar or LiDAR pairing essential Sonair's acoustic ranging and detection platform reduces sensor count by widening field-of-view to 180
Other drivers and restraints analyzed in the detailed report include:
- Rapid Adoption of Non-Contact Level Monitoring in Smart Water and Wastewater Utilities Across GCC Countries
- Deployment of Corrosion-Resistant PVDF Probes in Offshore Wind O&M Robots
- Performance Drift of Piezoelectric Stacks Under -40°C Nordic Operating Conditions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Bulk piezoelectric transducers retained a 64.30% ultrasonic sensors market share in 2025, anchored by economical mass production for automotive parking systems. The segment's scale advantage keeps unit costs low. In contrast, MUT arrays are growing at 12.64% CAGR as medical imaging and precision robotics demand miniaturized high-frequency performance. The ultrasonic sensors market size tied to MUT technology is expected to swell sharply as PMUTs excel in air-coupled detection while CMUTs dominate liquid-coupled imaging.
The technology transition reflects physical limits in ceramic plates when shrinking form factors. Potassium sodium niobate PMUTs recorded 105.5 dB/V at 10 cm, outclassing aluminum nitride competitors . Integration with CMOS electronics simplifies on-chip beamforming that lowers total bill of materials for smart devices.
Proximity and distance models captured 39.40% of 2025 revenue, favored for automotive bumpers and robot safety curtains. Level and depth sensors, however, are registering a 11.58% CAGR thanks to smart infrastructure projects. Continuous fluid-level insight curbs maintenance in water, chemical, and food facilities.
Wireless telemetry extends coverage to remote tanks, enabling predictive scheduling that trims service truck rolls. Transparent-liquid detection and through-wall sensing give ultrasonic probes an advantage over optical or float approaches, cementing market leadership across harsh industrial settings
Complete Report Scope:
- By Technology
- Bulk Piezoelectric Transducers
- Micromachined Ultrasound Transducers (MUT)
- PMUT (Piezo-MUT)
- CMUT (Capacitive-MUT)
- By Product Type
- Proximity and Distance Sensors
- Level/Depth Measurement Sensors
- Flow-measurement Sensors
- Ultrasonic Imaging Modules
- By Range
- Short-range ( >2 m)
- Medium-range (2 - 10 m)
- Long-range (> 10 m)
- By Mounting Type
- In-line / Threaded
- Block / Side-Looking
- Splice / Clamp-on
- By Operating Frequency
- <70 kHz
- 71 - 200 kHz
- > 200 kHz
- By End-user Vertical
- Industrial Manufacturing
- Automotive and Mobility
- Consumer Electronics and Appliances
- Medical and Healthcare
- Agriculture and Smart Farming
- Others (Oil and Gas, Marine, etc.)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Nordics
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- North America
Geography Analysis
Asia secured 37.60% of 2025 revenue on the back of China's vehicle electronics boom and Japan's precision manufacturing heritage. Government mandates make ultrasonic proximity detection standard in new passenger cars, while semiconductor clusters enable native MUT fabrication. South Korea supplies sensor ASICs, and India's affordable vehicle market increases penetration of cost-optimized designs. Policy-driven smart-city spending further embeds the ultrasonic sensors market in regional infrastructure rollouts.
North America concentrates on premium niches. The United States advances high-frequency probes for ambulatory diagnostics, while the aerospace sector exploits ruggedized units for structural health monitoring. Canada's winter environment shapes demand for temperature-compensated stacks. FDA guidance streamlines approvals, bringing new platforms to bedside and home settings faster than in earlier regulatory cycles.
Europe blends regulatory leadership and industrial prowess. EU GSR2 triggers synchronized automotive demand, and Germany's robotics clusters pioneer IO-Link enabled probes for real-time process feedback. Nordic utilities request heated sensor packages that withstand -40 °C, spurring material engineering breakthroughs. Meanwhile, South America posts the fastest 9.76% CAGR as mining firms automate remote sites and governments modernize water networks, enhancing need for resilient non-contact measurement.
- Keyence Corporation
- Pepperl+Fuchs AG
- Sick AG
- Honeywell International Inc.
- Omron Corporation
- Rockwell Automation Inc.
- Baumer Ltd
- Murata Manufacturing Co. Ltd
- Banner Engineering Corp.
- Balluff Inc.
- Robert Bosch GmbH
- Qualcomm Incorporated
- TDK Corporation
- Sensata Technologies
- TE Connectivity
- MaxBotix Inc.
- Siemens AG
- Texas Instruments Incorporated
- Hyde Park Electronics LLC
- Denso Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising installation of high-precision ultrasonic sensors in Industry 4.0 production cells
- 4.2.2 Mandatory fron trear obstacle-detection mandates in Chinese and EU passenger-car safety regulations
- 4.2.3 Rapid adoption of non-contact level monitoring in smart water and wastewater utilities across GCC countries
- 4.2.4 Use of high-frequency ( > 200 kHz) MUT arrays in medical point-of-care imaging devices
- 4.2.5 Deployment of corrosion-resistant PVDF-based probes in offshore wind O&M robots
- 4.3 Market Restraints
- 4.3.1 Signal attenuation in multi-sensor ADAS clusters beyond 10 m ranges
- 4.3.2 Performance drift of piezoelectric stacks under -40°C Nordic operating conditions
- 4.3.3 Regulatory hurdles around ultrasound exposure limits in wearable consumer electronics
- 4.3.4 Price premiums of PMUT wafers versus legacy bulk ceramic designs
- 4.4 Industry Value Chain Analysis
- 4.5 Technological Outlook (Miniaturized PMUT/CMUT wafers, ASIC integration)
- 4.6 Regulatory Outlook (ISO 19365, UNECE R159, FDA guidance for diagnostic ultrasound)
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assessment of Key Macroeconomic Trends
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Technology
- 5.1.1 Bulk Piezoelectric Transducers
- 5.1.2 Micromachined Ultrasound Transducers (MUT)
- 5.1.2.1 PMUT (Piezo-MUT)
- 5.1.2.2 CMUT (Capacitive-MUT)
- 5.2 By Product Type
- 5.2.1 Proximity and Distance Sensors
- 5.2.2 Level/Depth Measurement Sensors
- 5.2.3 Flow-measurement Sensors
- 5.2.4 Ultrasonic Imaging Modules
- 5.3 By Range
- 5.3.1 Short-range ( < 2 m)
- 5.3.2 Medium-range (2 - 10 m)
- 5.3.3 Long-range ( > 10 m)
- 5.4 By Mounting Type
- 5.4.1 In-line / Threaded
- 5.4.2 Block / Side-Looking
- 5.4.3 Splice / Clamp-on
- 5.5 By Operating Frequency
- 5.5.1 <70 kHz
- 5.5.2 71 - 200 kHz
- 5.5.3 > 200 kHz
- 5.6 By End-user Vertical
- 5.6.1 Industrial Manufacturing
- 5.6.2 Automotive and Mobility
- 5.6.3 Consumer Electronics and Appliances
- 5.6.4 Medical and Healthcare
- 5.6.5 Agriculture and Smart Farming
- 5.6.6 Others (Oil and Gas, Marine, etc.)
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 South America
- 5.7.2.1 Brazil
- 5.7.2.2 Argentina
- 5.7.2.3 Rest of South America
- 5.7.3 Europe
- 5.7.3.1 United Kingdom
- 5.7.3.2 Germany
- 5.7.3.3 France
- 5.7.3.4 Italy
- 5.7.3.5 Spain
- 5.7.3.6 Nordics
- 5.7.3.7 Rest of Europe
- 5.7.4 Asia Pacific
- 5.7.4.1 China
- 5.7.4.2 Japan
- 5.7.4.3 India
- 5.7.4.4 South Korea
- 5.7.4.5 Rest of Asia Pacific
- 5.7.5 Middle East
- 5.7.5.1 Saudi Arabia
- 5.7.5.2 United Arab Emirates
- 5.7.5.3 Turkey
- 5.7.5.4 Rest of Middle East
- 5.7.6 Africa
- 5.7.6.1 South Africa
- 5.7.6.2 Egypt
- 5.7.6.3 Rest of Africa
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Keyence Corporation
- 6.4.2 Pepperl+Fuchs AG
- 6.4.3 Sick AG
- 6.4.4 Honeywell International Inc.
- 6.4.5 Omron Corporation
- 6.4.6 Rockwell Automation Inc.
- 6.4.7 Baumer Ltd
- 6.4.8 Murata Manufacturing Co. Ltd
- 6.4.9 Banner Engineering Corp.
- 6.4.10 Balluff Inc.
- 6.4.11 Robert Bosch GmbH
- 6.4.12 Qualcomm Incorporated
- 6.4.13 TDK Corporation
- 6.4.14 Sensata Technologies
- 6.4.15 TE Connectivity
- 6.4.16 MaxBotix Inc.
- 6.4.17 Siemens AG
- 6.4.18 Texas Instruments Incorporated
- 6.4.19 Hyde Park Electronics LLC
- 6.4.20 Denso Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 超音波感測器市場:按類型、輸出類型、工作範圍、技術和應用分類-2026-2032年全球市場預測
 超音波感測器市場報告:按技術、類型、最終用戶和地區分類(2026-2034 年)
 超音波感測器全球市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 超音波感測器市場:按技術、終端用戶產業和地區分類
 全球超音波設備市場:市場規模、佔有率和趨勢分析(2026-2032 年)
 超音波感測器市場分析及預測(至2035年):按類型、產品類型、技術、組件、應用、形狀、材質、最終用戶和功能分類
 2026年全球超音波感測器市場報告全球超音波感測器市場:市場規模、佔有率、成長率、產業分析、依類型、應用和地區劃分的分析及預測(2026-2034)
 超音波感測器市場 - 全球產業規模、佔有率、趨勢、競爭格局、機會及預測(按類型、應用、產業垂直領域、地區和競爭格局分類,2021-2031年)
 超音波感測器市場機會、成長要素、產業趨勢分析及2026年至2035年預測