


 |
市場調查報告書
商品編碼
2062342
油田阻垢劑:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)Oilfield Scale Inhibitor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
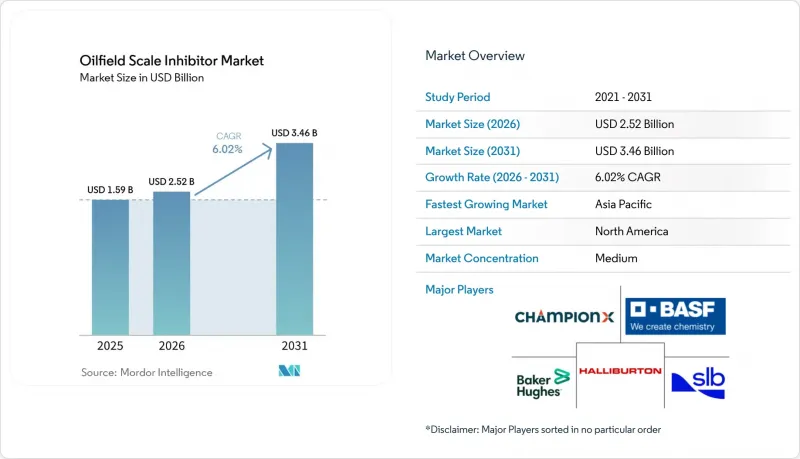
預計油田阻垢劑市場規模將從 2025 年的 15.9 億美元成長到 2026 年的 25.2 億美元,到 2031 年將達到 34.6 億美元,2026 年至 2031 年的複合年成長率為 6.02%。
本報告按類型(磷酸酯、羧酸鹽/丙烯酸酯、聚合物、生物分解材料、有機有機磷酸鹽)、應用(地下防腐、管道保護、表面處理、管道控制、注水、生產水回注)和地區(亞太地區、北美地區、歐洲地區、南美地區、中東和非洲)進行細分。市場預測以美元計價。
全球油田阻垢劑市場趨勢及洞察
成熟油田對結垢控制的需求日益成長
隨著全球成熟油田含水量的增加,營運商在管理日益成長的鹽水方面面臨越來越嚴峻的挑戰,因為鹽水極易結垢。在二疊紀盆地,業者每天都會產生大量的生產水,水油比高達3:1至12:1。這些水的回注和循環利用會無意中濃縮碳酸根離子和硫酸根離子,導致業者更加依賴複雜的擠注方案。亞太地區正面臨持續的產量下降,推動了油田維修和提高採收率(EOR)活動的增加,而挪威北海新開發的油田則採用雙管齊下的策略,將18-24個月的擠注週期與線上殘留物分析相結合,以減少浮體式設施的停機時間。在此背景下,油田阻垢劑市場正在興起,成為一種經濟有效的保障措施,可以避免因結垢導致的停產而造成的每天數百萬美元的潛在損失。
擴大海洋探勘和管道活動
到2025年,巴西鹽層下油田的日產量將飆升至數百萬桶。新型FPSO(浮體式生產儲貨運設施)配備了專為富含二氧化碳流體設計的阻垢劑組件,覆蓋長達18公里的回接管線。中海油已擴大產量,達到每日數百萬桶油當量。儘管該公司採用了海水注入技術,但這種策略增加了海底管匯中硫酸鈣結垢的風險。在西非地區,深海油田系統也面臨類似的挑戰,並依賴長效擠壓劑。預計這將推動2026年至2031年預測期內油田阻垢劑市場的收入成長。
原油價格波動正在抑制化工預算。
預計布蘭特原油價格將在2026年第二季達到峰值,並在隔年開始回落。歷史上,如此大幅的下跌往往會導致非必需化學品支出的減少。因此,北美獨立石油公司已經推遲了非緊急的壓裂作業,這給油田除垢劑市場的優質供應商帶來了壓力。
細分市場分析
至2025年,具有優異耐熱性和抗鈣性能(濃度超過1000 mg/L)的磷酸酯類產品將佔據油田阻垢劑市場45.82%的主導佔有率,並在2026年至2031年間以6.83%的複合年成長率成長。中東地區正在進行的海水注入計畫中,對亞ppm級氨基亞甲基混合物的需求日益成長,這將進一步推動這一成長。儘管由於美國環保署(EPA)和REACH法規要求減少磷排放,羧酸鹽和丙烯酸類產品正逐漸受到關注,但這些替代品通常需要兩位數ppm的劑量。這項要求限制了它們在巴西深海地區的應用,因為化學品物流成本會顯著影響總成本。在生產水回注網路中,除了控制水垢離子外,控制懸浮固態也至關重要,因此聚合物基和含磷混合產品正日益普及。尤其值得注意的是,馬來西亞國家石油公司(PETRONAS)在其龐大的管道網路中採用了多功能分散劑。雖然可生物分解配方目前仍屬於小眾市場,但其成長率卻最高。北海油氣業者正在投資符合OSPAR「黃C」標準的環保產品,凸顯了市場對環境議題日益成長的關注。
對於面臨硫化氫和鐵共生等挑戰的油井,當傳統的單一化學方法不足以應對時,有機磷酸鹽和協同混合物可提供解決方案。供應商正在測試示踪標記分子以提高效率。這些分子可透過光纖檢測,使作業者能夠準確了解其在油井中的分佈情況,從而減少過度處理,這有望提高這些專用解決方案的市場佔有率。市場格局複雜。儘管全球主要公司正在提交 REACH 註冊文件,但區域性製劑生產商正利用監管寬鬆的現狀來推廣傳統的磷酸酯。隨著環境法規的日益嚴格和運作溫度的升高,對各種化學品的需求將會增加,從而在 2026 年至 2031 年的預測期內形成一個平衡的市場,涵蓋成熟和新興的抑制劑系列。
區域分析
2025年,北美佔油田阻垢劑市佔率的36.11%。這主要歸功於頁岩油氣產區、墨西哥灣和瓦卡穆爾塔地區的集中開採活動。在二疊紀盆地,持續注入阻垢劑是處理生產水的關鍵。阿巴拉契亞頁岩油氣產區的業者面臨價格壓力和儲量長期壓縮的困境,導致全部區域的發展趨勢各不相同。在2026年至2031年的預測期內,北美油田阻垢劑市場保持穩定成長,儘管原油價格波動為短期預算帶來了挑戰。在加拿大,由於需要使用阻垢劑來處理高溫瀝青,油砂開採作業的單位銷售量呈現穩定但適度的成長。
亞太地區是成長最快的地區,在2026年至2031年的預測期內,複合年成長率(CAGR)達到6.79%。中國海上油氣開發的擴張、印尼的聚合物注入以及馬來西亞快速成長的管道網路推動了化學品使用量的成長。儘管東協油田年產量下降需要維修改造,並增加了鹽水pH值升高和結垢的風險,但油田阻垢劑市場的前景依然樂觀。中國海洋石油總公司(中海油)在2025年基準年的增產以及渤海灣的海水注入提振了需求。此外,印度石油天然氣公司(ONGC)與信實工業(Reliance)在印度克里希納-戈達瓦里盆地的合作確保了產量,從而需要高耐鹽化學品。馬來西亞國家石油公司(Petronas)將PM3計畫延長20年,凸顯了東南亞對化學品的持續需求。
在歐洲,成長依然溫和,但消費保持穩定。以2025年為基準年,挪威七個新開發的油田對高性能阻垢劑的需求有所成長,尤其是用於海底電氣化系統的阻垢劑。在英國,與油田退役相關的油井維護化學品的間歇性需求抵消了產量逐漸下降的影響。俄羅斯市場雖然規模龐大,但由於制裁的影響,其前景仍然不明朗,並且主要依賴國內磷酸酯的生產。中東地區的成長率並非最高,但預計其絕對銷量增幅最大。沙烏地阿美、阿布達比國家石油公司和科威特石油公司等行業領導者在註水和提高採收率(EOR)基礎設施方面投入巨資。在南美洲,巴西,尤其是阿根廷以外的地區,成為焦點。巴西石油公司利用其在2025年基準年的產量,推出了專為富含二氧化碳的鹽層下下層流體設計的耐酸阻垢劑。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 成熟油田對結垢控制的需求日益成長
- 海洋探勘和管道業務的擴展
- 採用提高採收率(EOR)技術會增加化學品的消耗量。
- 傳統型石油資源的成長
- 即時數位抑制劑的管理和監控
- 在缺水地區過渡到採出水回注
- 市場限制因素
- 原油價格波動給化學工業的預算帶來了壓力。
- 加強磷和重金屬排放法規
- 透過全電動海底系統減少化學品注入點。
- 膦酸中間體供應鏈持續面臨風險
- 價值鏈分析
- 波特五力模型
第5章 市場規模與成長預測
- 按類型
- 磷酸酯
- 羧酸鹽/丙烯酸酯
- 聚合物/磷標記聚合物
- 可生物分解且環境友善的抑制劑
- 有機磷化合物和協同混合物
- 透過使用
- 礦井結垢預防(擠壓)
- 管材和套管的保護
- 表面處理
- 管道和輸油管的縮放控制
- 注水系統
- 生產水的回注和處置
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 東南亞國協
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 北歐國家
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- Afton Chemical
- Arkema
- Ashland
- Baker Hughes Company
- BASF
- ChampionX
- Clariant
- Dow
- Halliburton
- Huntsman
- Innospec
- Italmatch Oil & Gas
- Kemira
- LANXESS
- SLB(Schlumberger)
- SNDB
- SNF
- Solenis
- Solvay
- Stepan Company
- Thermax Limited
第7章 市場機會與未來展望
According to Mordor Intelligence, the oilfield scale inhibitor market size is expected to increase from USD 1.59 billion in 2025 to USD 2.52 billion in 2026 and reach USD 3.46 billion by 2031, growing at a CAGR of 6.02% over 2026-2031.
This report is Segmented by Type (Phosphonates, Carboxylates/Acrylics, Polymeric, Biodegradable, and Organophosphates), Application (Downhole Prevention, Tubing Protection, Surface Treatment, Pipeline Control, Water Injection, and Produced-Water Reinjection), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). Market Forecasts are Provided in Value (USD).
Global Oilfield Scale Inhibitor Market Trends and Insights
Growing Demand for Scale Control in Mature Fields
Operators face increasing challenges in managing the growing volumes of brine, which have a high potential for scaling, as mature reservoirs worldwide experience rising water cuts. In the Permian Basin, operators generate significant volumes of produced water daily, with water-to-oil ratios ranging from 3:1 to 12:1. As they reinject and recycle this water, they inadvertently concentrate carbonate and sulfate ions, leading to a heightened reliance on advanced squeeze programs. While the Asia-Pacific region has grappled with a sustained production decline, intensifying workover and Enhanced Oil Recovery (EOR) activities, Norway's newly tapped North Sea fields have adopted a dual approach - pairing 18-24 month squeeze cycles with online residual analyzers to curtail downtime on floating facilities. Given these dynamics, the oilfield scale inhibitor market has emerged as a cost-effective safeguard, protecting against potential million-dollar daily losses stemming from scale-induced outages.
Expansion of Offshore Exploration and Pipeline Activities
By 2025, Brazil's pre-salt output surged, reaching millions of barrels per day. Each new FPSO now features inhibitor packages specifically designed for CO2-rich fluids, spanning 18-kilometer tiebacks. CNOOC increased its production, achieving millions of barrels of oil equivalent per day. The company adopted seawater injection, a strategy that increases the risk of calcium-sulfate scaling in subsea manifolds. In the West-African region, deepwater systems face similar challenges, relying on long-residence squeeze chemistries that are expected to enhance revenue in the oilfield scale inhibitor market during the forecast period of 2026-2031.
Volatile Crude Prices Curbing Chemical Budgets
Brent prices are projected to peak in Q2 2026 before declining in the following year. This significant drop has historically led to a reduction in discretionary chemical spending. In response, North American independents are already postponing non-critical squeezes, putting pressure on premium suppliers in the oilfield scale inhibitor market.
Other drivers and restraints analyzed in the detailed report include:
- Adoption of EOR Techniques Elevating Chemical Consumption
- Growth in Unconventional Oil Resources
- Tightening Discharge Regulations on Phosphorus and Heavy Metals
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, phosphonates, with a robust thermal endurance and a calcium tolerance exceeding 1,000 mg/L, captured a dominant 45.82% share of the oilfield scale inhibitor market, growing at an annual rate of 6.83% CAGR from 2026 to 2031. By 2026, ongoing seawater-injection projects in the Middle-East, increasingly favoring aminomethylene blends at sub-ppm treatment rates, will support this growth. While carboxylates and acrylics are gaining traction - driven by EPA and REACH pressures to curtail phosphorus discharge - these alternatives often require double-digit ppm dosages. This necessity has limited their adoption in deepwater Brazil, where chemical logistics heavily impact total costs. In produced-water reinjection networks, where managing suspended solids alongside scaling ions is vital, polymeric and phosphorus-tagged hybrids are becoming more popular. Notably, PETRONAS utilizes multifunctional dispersants throughout its extensive pipeline network. Although biodegradable formulations occupy a niche segment, they are witnessing the fastest growth rate in percentage terms. Operators in the North Sea are investing in products classified under OSPAR's "Yellow C" designation, highlighting the market's environmental focus.
For wells facing challenges like hydrogen sulfide or iron co-production, organophosphates and synergistic blends provide solutions where traditional single-chemistry methods falter. Suppliers are trialing tracer-tagged molecules to enhance efficiency. Detectable via fiber optics, these molecules allow operators to accurately map downhole distribution and reduce overtreatment, potentially boosting the market share for these specialized solutions. The landscape is intricate: while global giants register REACH dossiers, regional formulators champion classic phosphonates, benefiting from lighter oversight. As environmental regulations tighten and operational temperatures rise, the demand for diverse chemistries ensures a balanced market, accommodating both established and emerging inhibitor families during the forecast period of 2026-2031.
Geography Analysis
In 2025, North America commanded a 36.11% share of the oilfield scale inhibitor market, driven by activities converging in shale regions, the offshore Gulf, and Vaca Muerta. Continuous chemical dosing was essential for the produced-water stream in the Permian Basin. Operators in the Appalachian shale, facing price pressures and extended squeeze intervals, are resulting in mixed dynamics across the region. While North America's oilfield scale inhibitor market was on a steady growth trajectory during the forecast period 2026-2031, fluctuations in crude prices posed challenges to short-term budgets. In Canada, oil sands operations, requiring inhibitors compatible with hot bitumen, experienced consistent but slower unit growth.
Asia-Pacific led as the fastest-growing region, registering a 6.79% CAGR during the forecast period 2026-2031. China's offshore expansions, Indonesia's polymer floods, and Malaysia's burgeoning pipeline network spurred heightened chemical usage. Despite annual declines in ASEAN fields prompting workovers and increased brine pH and scaling risks, the oilfield scale inhibitor market's outlook remained optimistic. CNOOC's production boost in the base year 2025, alongside seawater injections in Bohai Bay, amplified demand. Furthermore, the collaboration between ONGC and Reliance in India's KG basin unlocked volumes necessitating high-salinity-tolerant chemicals. PETRONAS's two-decade extension of the PM3 project underscored the enduring chemical demand in Southeast Asia.
Europe experienced modest growth yet sustained stable consumption. In the base year 2025, Norway's seven newly tapped fields favored high-performance inhibitors, particularly those adept against electrified subsea systems. The United Kingdom's decommissioning activities spurred sporadic demand for well-preservation chemicals, offsetting the nation's gradual production declines. Russia's market, while sizable, remained opaque due to sanctions and leaned predominantly on domestic phosphonate production. The Middle-East, though not leading in percentage growth, was poised for the most substantial absolute volume increase. Industry giants such as Saudi Aramco, ADNOC, and Kuwait Oil Company made significant investments in injection and enhanced oil recovery (EOR) infrastructure. In South America, Brazil emerged as a focal point, particularly in regions outside Argentina. Petrobras, capitalizing on its production in the base year 2025, deployed acid-stable inhibitors specifically designed for CO2-rich pre-salt fluids.
- Afton Chemical
- Arkema
- Ashland
- Baker Hughes Company
- BASF
- ChampionX
- Clariant
- Dow
- Halliburton
- Huntsman
- Innospec
- Italmatch Oil & Gas
- Kemira
- LANXESS
- SLB (Schlumberger)
- SNDB
- SNF
- Solenis
- Solvay
- Stepan Company
- Thermax Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing demand for scale control in mature fields
- 4.2.2 Expansion of offshore exploration and pipeline activities
- 4.2.3 Adoption of EOR techniques elevating chemical consumption
- 4.2.4 Growth in unconventional oil resources
- 4.2.5 Real-time digital inhibitor dosing and monitoring
- 4.2.6 Shift toward produced-water reinjection in water-scarce regions
- 4.3 Market Restraints
- 4.3.1 Volatile crude prices curbing chemical budgets
- 4.3.2 Tightening discharge regulations on phosphorus and heavy metals
- 4.3.3 All-electric subsea systems reducing chemical injection points
- 4.3.4 Persistent supply-chain risk for phosphonate intermediates
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Phosphonates
- 5.1.2 Carboxylates/Acrylics
- 5.1.3 Polymeric/Phosphorus-tagged Polymers
- 5.1.4 Biodegradable and Green Inhibitors
- 5.1.5 Organophosphates and Synergistic Blends
- 5.2 By Application
- 5.2.1 Downhole Scale Prevention (Squeeze)
- 5.2.2 Tubing and Casing Protection
- 5.2.3 Surface Facility Treatment
- 5.2.4 Pipeline and Flowline Scale Control
- 5.2.5 Water-Injection Systems
- 5.2.6 Produced-Water Reinjection and Disposal
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Spain
- 5.3.3.6 Russia
- 5.3.3.7 Nordic Countries
- 5.3.3.8 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)}
- 6.4.1 Afton Chemical
- 6.4.2 Arkema
- 6.4.3 Ashland
- 6.4.4 Baker Hughes Company
- 6.4.5 BASF
- 6.4.6 ChampionX
- 6.4.7 Clariant
- 6.4.8 Dow
- 6.4.9 Halliburton
- 6.4.10 Huntsman
- 6.4.11 Innospec
- 6.4.12 Italmatch Oil & Gas
- 6.4.13 Kemira
- 6.4.14 LANXESS
- 6.4.15 SLB (Schlumberger)
- 6.4.16 SNDB
- 6.4.17 SNF
- 6.4.18 Solenis
- 6.4.19 Solvay
- 6.4.20 Stepan Company
- 6.4.21 Thermax Limited
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment
- 7.2 Smart inhibitors with embedded fibre-optic sensing

 聚磷酸鹽基阻垢劑市場:全球市場預測(2026-2032年)高效率灰水阻垢劑市場:全球市場預測,2026-2032年
 除垢劑:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)
 阻垢劑和除垢劑市場規模、佔有率和趨勢分析報告:按產品、應用、最終用途、地區和細分市場預測(2026-2033 年)
 除垢閥市場規模、佔有率和成長分析:按閥門類型、材料、壓力等級、最終用途產業、操作方式、分銷管道和地區分類-2026-2033年產業預測
 阻垢劑市場:依類型、製程、應用、技術、形態、國家及地區分類-全球產業分析、市場規模、市場佔有率及2026年至2033年預測
 阻垢劑和分散劑市場規模、佔有率和成長分析:按產品化學、製劑形式、目標系統、最終用途產業和地區分類-2026-2033年產業預測
 阻垢劑和防污劑市場規模、佔有率和成長分析:按化學分類、系統運作、最終用途產業和地區分類-2026-2033年產業預測
 全球阻垢劑市場規模、佔有率、趨勢和成長分析報告(2026-2034年)水垢去除劑市場規模、佔有率和趨勢分析報告:按產品、形式、應用、最終用途、地區和細分市場分類(2026-2033 年)