


 |
市場調查報告書
商品編碼
2121654
生物分解包裝解決方案:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)Biodegradable Packaging Solutions - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,生物分解包裝解決方案的市場規模預計將在 2026 年達到 1,177.4 億美元,並在 2031 年達到 1,599.7 億美元。
這表明從 2026 年到 2031 年,複合年成長率將達到 6.32%,支持該行業的穩定成長趨勢。
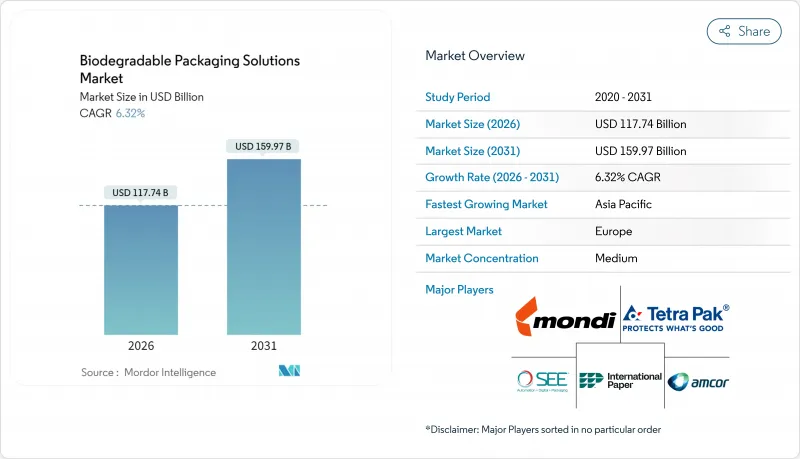
本報告按材料類型(生質塑膠、紙張、模塑紙漿纖維、植物來源複合材料)、包裝形式(硬質、軟質)、終端用戶產業(食品、飲料、醫療保健、個人護理、電子商務等)、分銷管道(直接、間接)和地區(北美、南美等)進行細分。市場預測以美元計價。
全球可生物分解包裝解決方案市場趨勢與洞察
消費者對循環利用和零浪費包裝的需求日益成長
2025年的一項消費者調查顯示,歐洲和北美67%的消費者在做出購買決定時會考慮產品生命週期結束後如何處理,高於2023年的52%。尤其是千禧世代和Z世代消費者,如果覺得品牌的永續性聲明不夠充分,他們往往會更換品牌。為此,一些快餐店已在部分城市啟動試點項目,提供可堆肥刀叉餐具和翻蓋式容器,以減少15%至20%的塑膠廢棄物。加工商正在加強其技術支援團隊,以幫助品牌適應認證流程和包裝上的處理方法標籤。零售商正利用自有品牌作為新材料的低風險試驗場,加速商業性示範週期。這種行為轉變支撐了穩定的溢價,抵消了生物聚合物成本的上漲,並推動了對可生物分解包裝解決方案市場的長期需求。
都市區堆肥基礎設施的擴建
歐盟已從其凝聚基金中撥款23億歐元(約26億美元),用於在2024-2025年期間在東歐各地建造厭氧消化和風乾堆肥設施,目標是到2030年實現50%的有機廢棄物回收率。在舊金山和多倫多等北美城市,挨家挨戶收集居民有機廢棄物是強制性的,這確保了堆肥企業穩定的原料供應,並驗證了包裝材料在實際環境中的表現。中國住宅及城鄉建設部正在46個城市試行推行廢棄物分類項目,而印度的「智慧城市計畫」則將市政補貼與堆肥績效掛鉤。基礎設施密度的提高降低了品牌所有者的聲譽風險,而位於堆肥場附近的加工企業則透過閉合迴路收集方案獲得了物流優勢。
生物聚合物所需農業原料供應的波動
2024年至2025年間,玉米和甘蔗價格波動幅度達18%至24%,一場嚴重的乾旱導致美國玉米減產12%。巴西生產商將甘蔗種植面積轉向大豆,導致甘蔗產量下降7%,PLA生產商的供應也因此趨緊。缺乏避險能力的中小型加工商難以應對這些價格波動,有時甚至會減緩品牌發展速度,或將市佔率拱手讓給像道達爾科比昂(Total Corbion)這樣規模更大、垂直整合程度更高的競爭對手。如果可堆肥包裝的成本超過品牌所有者的成本上限,原料價格的波動可能會減緩替代速度,並抑制可生物分解包裝解決方案市場的短期成長。
細分市場分析
到2025年,生質塑膠在可生物分解包裝解決方案市場中仍將佔據48.21%的佔有率。這主要歸功於PLA與現有擠出和熱成型設備的兼容性,從而最大限度地降低了轉型期間的資本支出。澱粉基聚合物佔據了性能較低的細分市場,例如散裝填充材和農業覆蓋物,而纖維素衍生物則因其透明度和可印刷性而受到高階個人護理品牌的青睞。 PHA因其海洋生物分解性而享有溢價,並受到沿海酒店業和海鮮連鎖店的青睞。 PBS級產品具有優異的耐熱性,可用於開發保存期限長的醬料和調理食品。
預計到2031年,蘑菇菌絲體、海藻薄膜和甘蔗渣纖維等植物來源複合材料的複合年成長率將達到7.42%,成為所有材料中成長最快的,因為高階電子產品和化妝品製造商對具有質感和故事性的基材的需求日益成長。 Ecovative Design的菌絲體緩衝材料正受到尋求無塑膠保護性包裝的電子品牌的青睞。水溶性海藻衍生小袋為調味品包裝帶來了全新的用戶體驗,而甘蔗渣托盤則獲得了快餐店的支持,這些快餐店希望減少發泡聚苯乙烯的使用。這種多樣性凸顯了可生物分解包裝解決方案市場如何從功能性能和引人注目的行銷策略的結合中獲益。
到2025年,軟包裝將佔據56.32%的市場。這反映了其低品質與產品比例和高運輸效率,這對電商物流包裝和快餐包裝至關重要。生物阻隔塗層提高了氧氣滲透性,促使寵物食品和咖啡包裝袋廣泛使用。同時,在飲料和乳製品生產商試點使用模塑紙漿瓶和罐作為PET替代品的推動下,預計到2031年,硬質容器將以7.89%的複合年成長率保持強勁成長。
斯特拉勒恩索的木纖維複合瓶透過將纖維瓶身與薄生物內襯相結合,展現出良好的應用前景。儘管生物聚合物在瓶罐應用中仍面臨熔體強度的挑戰,但目前正積極進行研發工作以克服這些挑戰。軟包裝的優點與硬包裝的快速普及並存,反映出在可生物分解包裝解決方案市場中,材料效率與使用後易於分類之間存在著權衡取捨。
區域分析
到2025年,歐洲將佔據可生物分解包裝解決方案市場40.21%的佔有率。這主要得益於德國、法國和荷蘭已建立的堆肥網路,以及《包裝和包裝廢棄物法規》強制要求在2030年實現可回收或可堆肥。德國的《包裝方法》進一步提高了再生材料含量的標準,而法國則透過將一次性塑膠禁令擴大到包括生鮮食品包裝(2025年生效),加快了材料替代的步伐。英國在脫歐後調整了其“塑膠包裝稅”,以保持與歐洲大陸監管的一致性。
亞太地區正處於成長最快的階段,預計到2031年將維持8.85%的複合年成長率。中國2024年的指導方針旨在到2030年將一次性塑膠的使用量減少40%,這將刺激對聚乳酸(PLA)和聚羥基脂肪酸酯(PHA)生產能力的投資。印度修訂後的《塑膠廢棄物管理條例》鼓勵使用可堆肥替代品,但各邦的實施情況有所不同。日本的《綠色採購法》正在推動公共採購的需求,而澳洲2025年的包裝目標也鼓勵國內品牌轉向可堆肥包裝。中產階級的壯大和電子商務的快速發展為消費提供了順風,進一步增加了該地區對可生物分解包裝解決方案的需求。
在北美,加州、奧勒岡州、科羅拉多和緬因州推行的擴大生產者責任制(EPR)正在推動可堆肥產品的普及,但由於缺乏聯邦層面的統一標準,各地區的合規水平存在差異。加拿大將於2024年推出的聯邦EPR框架將彌合各省之間的差距,並提高可堆肥產品的普及率。墨西哥正利用與位置,努力將自身打造成為加工商的近岸外包中心。南美市場仍在發展中,巴西和阿根廷的堆肥基礎設施不均衡以及價格敏感度構成了發展障礙。在中東和非洲,可堆肥產品的普及零星出現。特別是阿拉伯聯合大公國和南非,這兩個旅遊業和出口導向產業正將永續性放在首位,亟需改善基礎設施以促進更廣泛的市場發展。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 消費者對循環利用、零浪費包裝的需求日益成長
- 都市區堆肥基礎設施的擴建
- 各國強制性生產者延伸責任制
- 阻隔性生物基塗料的進步正在開闢新的應用領域。
- 亞太地區PLA和PHA產能快速擴張
- 零售商自有品牌的永續性目標正在加速其普及。
- 市場限制因素
- 生物聚合物所需農業原料供應的波動
- 區域遴選和認證標準有缺陷
- 與傳統塑膠相比,其在防潮和阻隔性存在差異。
- 「綠色清洗」訴訟的風險正在推高合規成本。
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 宏觀經濟因素對市場的影響
- 波特五力分析
第5章 市場規模及成長預測(以金額為準)
- 依材料類型
- 生質塑膠
- 澱粉基塑膠
- 纖維素基塑膠
- 聚乳酸(PLA)
- 聚羥基烷酯(PHA)
- 聚丁二酸丁二醇酯(PBS)
- 其他可堆肥聚合物
- 紙
- 模壓紙漿纖維
- 植物來源複合材料(蘑菇、海藻、甘蔗渣)
- 生質塑膠
- 按包裝類型
- 硬包裝
- 瓶子和罐子
- 托盤和翻蓋
- 盒子和紙箱
- 其他硬質包裝
- 軟包裝
- 薄膜和包裝
- 小袋和袋子
- 其他軟包裝
- 硬包裝
- 按最終用戶行業分類
- 食物
- 飲料
- 醫療和藥品
- 個人護理化妝品
- 電子商務與零售
- 其他終端用戶產業
- 透過分銷管道
- 直銷
- 間接銷售
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 埃及
- 奈及利亞
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Amcor plc
- Mondi Group
- Smurfit WestRock
- Tetra Pak International SA
- Sealed Air Corporation
- International Paper Company
- Ranpak Holding Corporation
- Huhtamaki Oyj
- Stora Enso Oyj
- NatureWorks LLC
- BASF SE
- Novamont SpA
- Total Corbion PLA
- Elevate Packaging Inc.
- BioPak Pty Ltd(Duni Group)
- Kruger Inc.
- Greenpack Limited
- Berkley International Packaging Ltd.
第7章 市場機會與未來展望
According to Mordor Intelligence, the biodegradable packaging solutions market size reached USD 117.74 billion in 2026 and is projected to advance to USD 159.97 billion by 2031, reflecting a CAGR of 6.32% over 2026-2031 and confirming the sector's steady upward trajectory.
This report is Segmented by Material Type (Bioplastics, Paper, Molded Pulp Fiber, and Plant-Based Composites), Packaging Format (Rigid, and Flexible), End-User Industry (Food, Beverage, Healthcare, Personal Care, E-Commerce, and More), Distribution Channel (Direct, and Indirect), and Geography (North America, South America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Biodegradable Packaging Solutions Market Trends and Insights
Growing Consumer Demand for Circular, Zero-Waste Packaging
Consumer surveys conducted in 2025 indicate that 67% of shoppers in Europe and North America now consider end-of-life disposal when making purchasing decisions, up from 52% in 2023. Millennials and Gen Z buyers, in particular, switch brands when sustainability claims appear weak, prompting quick-service restaurants to pilot compostable cutlery and clamshells that trimmed plastic waste by 15-20% in trial cities. Converters are responding by bolstering their technical-support teams, which help brands navigate certification processes and on-pack disposal messaging. Retailers use private-label lines as low-risk test beds for new materials, accelerating commercial validation cycles. This behavioral shift underpins stable price premiums that offset higher biopolymer costs and reinforces long-run demand for the biodegradable packaging solutions market.
Expansion of Composting Infrastructure in Urban Centers
The European Union allocated EUR 2.3 billion (USD 2.60 billion) from the 2024-2025 cohesion funds to build anaerobic digestion and windrow facilities across Eastern Europe, targeting a 50% organic waste diversion rate by 2030. North American cities, such as San Francisco and Toronto, mandate curbside organics collection, ensuring a steady feedstock for compost operators and validating packaging performance under real-world conditions. China's Ministry of Housing and Urban-Rural Development is piloting food-waste separation programs in 46 cities, while India's Smart Cities Mission ties municipal grants to composting performance. Greater infrastructure density lowers reputational risk for brand owners and grants converters near composting hubs a logistics advantage through closed-loop take-back schemes.
Volatile Availability of Agricultural Feedstocks for Biopolymers
Corn and sugarcane prices fluctuated 18-24% during 2024-2025, with U.S. corn yields down 12% after severe droughts. Brazilian growers diverted acreage from sugarcane to soybeans, cutting cane output by 7% and tightening supply for PLA producers. Smaller converters lacking hedging capacity struggle to absorb these swings, sometimes delaying brand rollouts or ceding share to larger, vertically integrated rivals such as Total Corbion. Feedstock price instability can dampen substitution momentum if compostable formats exceed brand owners' cost ceilings, potentially moderating near-term expansion of the biodegradable packaging solutions market.
Other drivers and restraints analyzed in the detailed report include:
- Mandatory Extended Producer Responsibility Schemes Globally
- Advances in High-Barrier Bio-Based Coatings Unlocking New Applications
- Inadequate Sorting and Certification Standards Across Regions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Bioplastics retained a 48.21% share of the biodegradable packaging solutions market size in 2025, largely due to PLA's compatibility with existing extrusion and thermoforming assets, which minimizes capital outlay during the transition. Starch-based polymers occupy low-performance niches such as loose-fill and agricultural mulch, while cellulose derivatives satisfy premium personal-care labels that demand transparency and printability. PHA fetches a price premium for marine biodegradability, appealing to coastal hospitality and seafood chains. PBS grades offer superior heat resistance, unlocking shelf-stable sauces and ready meals.
Plant-based composites, such as mushroom mycelium, seaweed films, and bagasse fibers, are forecast to grow at a 7.42% CAGR through 2031, the fastest among materials, as luxury electronics and cosmetics adopters seek texture-rich, story-driven substrates. Ecovative Design's mycelium cushioning wins with electronics brands seeking plastic-free protective formats. Seaweed-based sachets that dissolve in water offer a novel user experience for condiment packets, while bagasse trays are gaining favor with quick-service restaurants seeking to eliminate expanded polystyrene. This diversity underscores how the biodegradable packaging solutions market benefits when functional performance and narrative marketing intersect.
Flexible formats commanded a 56.32% share in 2025, reflecting their lower mass-to-product ratio and transport efficiency, which are crucial for e-commerce mailers and quick-service wraps. Pouches for pet food and coffee gained traction as bio-barrier coatings narrowed oxygen-permeation gaps. Conversely, rigid formats are projected to track a robust 7.89% CAGR to 2031, driven by molded-pulp bottles and jars that beverage and dairy players are piloting to replace PET.
Stora Enso's wood-fiber composite bottle demonstrates progress, pairing a fiber body with a thin bio-liner. Bottles and jars still face melt-strength hurdles with biopolymers, but active R&D is aimed at closing these gaps. The coexistence of flexible leadership and rigid acceleration reflects trade-offs between material efficiency and post-use sorting clarity within the biodegradable packaging solutions market.
Complete Report Scope:
- By Material Type
- Bioplastics
- Starch-Based Plastics
- Cellulose-Based Plastics
- Polylactic Acid (PLA)
- Polyhydroxyalkanoates (PHA)
- Polybutylene Succinate (PBS)
- Other Compostable Polymers
- Paper
- Molded Pulp Fiber
- Plant-Based Composites (Mushroom, Seaweed, Bagasse)
- Bioplastics
- By Packaging Format
- Rigid Packaging
- Bottles and Jars
- Trays and Clamshells
- Boxes and Cartons
- Other Rigid Packagings
- Flexible Packaging
- Films and Wraps
- Pouches and Bags
- Other Flexible Packagings
- Rigid Packaging
- By End-User Industry
- Food
- Beverage
- Healthcare and Pharmaceuticals
- Personal Care and Cosmetics
- E-Commerce and Retail
- Other End-user Industries
- By Distribution Channel
- Direct Sales
- Indirect Sales
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Europe contributed 40.21% of the biodegradable packaging solutions market share in 2025, driven by the Packaging and Packaging Waste Regulation, which mandates recyclability or compostability by 2030, and by well-established composting networks in Germany, France, and the Netherlands. Germany's Verpackungsgesetz further tightened recycled-content thresholds, while France extended its ban on single-use plastics to fresh produce packaging in 2025, accelerating material substitution. The United Kingdom aligned its Plastic Packaging Tax post-Brexit, maintaining regulatory coherence with continental Europe.
Asia-Pacific is on track for the fastest 8.85% CAGR through 2031. China's 2024 guidelines aim for a 40% reduction in single-use plastics by 2030 and spur investments in PLA and PHA capacity. India's amended Plastic Waste Management Rules encourage the use of compostable alternatives, although enforcement varies by state. Japan's Green Purchasing Law boosts demand in public procurement, and Australia's 2025 packaging targets push national brands toward compostable formats. An expanding middle class and rapid e-commerce growth add consumption tailwinds, amplifying regional pull for the biodegradable packaging solutions market.
North America benefits from EPR rollouts in California, Oregon, Colorado, and Maine, yet lacks federal harmonization, creating patchwork compliance terrain. Canada's 2024 federal EPR framework simplifies provincial divergence and elevates compostable adoption rates. Mexico's proximity to U.S. brands positions it as a near-shoring hub for converters. South America remains nascent, with Brazil and Argentina hindered by uneven compost infrastructure and price sensitivity. The Middle East and Africa show sporadic adoption most notably in the United Arab Emirates and South Africa, where tourism and export-oriented sectors value sustainability credentials, though broader market development awaits infrastructure build-out.
- Amcor plc
- Mondi Group
- Smurfit WestRock
- Tetra Pak International SA
- Sealed Air Corporation
- International Paper Company
- Ranpak Holding Corporation
- Huhtamaki Oyj
- Stora Enso Oyj
- NatureWorks LLC
- BASF SE
- Novamont SpA
- Total Corbion PLA
- Elevate Packaging Inc.
- BioPak Pty Ltd (Duni Group)
- Kruger Inc.
- Greenpack Limited
- Berkley International Packaging Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Consumer Demand for Circular, Zero-Waste Packaging
- 4.2.2 Expansion of Composting Infrastructure in Urban Centers
- 4.2.3 Mandatory Extended Producer Responsibility Schemes Globally
- 4.2.4 Advances in High-Barrier Bio-Based Coatings Unlocking New Applications
- 4.2.5 Rapid Capacity Additions for PLA and PHA in Asia-Pacific
- 4.2.6 Retailers' Private-Label Sustainability Targets Accelerating Adoption
- 4.3 Market Restraints
- 4.3.1 Volatile Availability of Agricultural Feedstocks for Biopolymers
- 4.3.2 Inadequate Sorting and Certification Standards Across Regions
- 4.3.3 Performance Gaps in Moisture and Oxygen Barrier vs Conventional Plastics
- 4.3.4 Risk of Greenwashing Litigations Increasing Compliance Costs
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS ( VALUE)
- 5.1 By Material Type
- 5.1.1 Bioplastics
- 5.1.1.1 Starch-Based Plastics
- 5.1.1.2 Cellulose-Based Plastics
- 5.1.1.3 Polylactic Acid (PLA)
- 5.1.1.4 Polyhydroxyalkanoates (PHA)
- 5.1.1.5 Polybutylene Succinate (PBS)
- 5.1.1.6 Other Compostable Polymers
- 5.1.2 Paper
- 5.1.3 Molded Pulp Fiber
- 5.1.4 Plant-Based Composites (Mushroom, Seaweed, Bagasse)
- 5.1.1 Bioplastics
- 5.2 By Packaging Format
- 5.2.1 Rigid Packaging
- 5.2.1.1 Bottles and Jars
- 5.2.1.2 Trays and Clamshells
- 5.2.1.3 Boxes and Cartons
- 5.2.1.4 Other Rigid Packagings
- 5.2.2 Flexible Packaging
- 5.2.2.1 Films and Wraps
- 5.2.2.2 Pouches and Bags
- 5.2.2.3 Other Flexible Packagings
- 5.2.1 Rigid Packaging
- 5.3 By End-User Industry
- 5.3.1 Food
- 5.3.2 Beverage
- 5.3.3 Healthcare and Pharmaceuticals
- 5.3.4 Personal Care and Cosmetics
- 5.3.5 E-Commerce and Retail
- 5.3.6 Other End-user Industries
- 5.4 By Distribution Channel
- 5.4.1 Direct Sales
- 5.4.2 Indirect Sales
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Egypt
- 5.5.5.2.3 Nigeria
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 Mondi Group
- 6.4.3 Smurfit WestRock
- 6.4.4 Tetra Pak International SA
- 6.4.5 Sealed Air Corporation
- 6.4.6 International Paper Company
- 6.4.7 Ranpak Holding Corporation
- 6.4.8 Huhtamaki Oyj
- 6.4.9 Stora Enso Oyj
- 6.4.10 NatureWorks LLC
- 6.4.11 BASF SE
- 6.4.12 Novamont SpA
- 6.4.13 Total Corbion PLA
- 6.4.14 Elevate Packaging Inc.
- 6.4.15 BioPak Pty Ltd (Duni Group)
- 6.4.16 Kruger Inc.
- 6.4.17 Greenpack Limited
- 6.4.18 Berkley International Packaging Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 Skep瓶市場規模、佔有率和成長分析:按材料、產能、應用、最終用戶、分銷管道和地區分類-2026-2033年產業預測
 零廢棄包裝解決方案市場分析及預測至 2035 年:按類型、產品類型、服務、技術、應用、材料類型、製程、最終用戶和解決方案分類。
 永續食品包裝市場預測至2034年—按材料類型、包裝形式、永續性屬性、應用、最終用戶和地區分類的全球分析
 拋棄式包裝市場規模、佔有率、成長和行業分析:按材料類型、產品類型、最終用途和地區分類,並預測至2034年2034年可生物分解化妝品包裝市場預測-全球分析(依材料類型、包裝類型、化妝品類別、功能、最終使用者和地區分類)海藻衍生永永續包裝市場預測至2034年—按產品類型、材料成分、包裝功能、最終用戶、分銷管道和地區分類的全球分析生物基包裝市場預測至2034年-按材料、包裝形式、產品類型、最終用途產業和地區分類的全球分析可再生塑膠包裝市場預測至2034年—按材料、包裝類型、回收流程、應用、最終用戶和地區分類的全球分析可溶性包裝市場預測至2034年-按材料、產品類型、溶解度、阻隔性、技術、最終用戶和地區分類的全球分析紙包裝市場:預測(至2034年)-按包裝類型、紙張類型、包裝形式、功能、印刷技術、最終用戶和地區分類的全球分析