


 |
市場調查報告書
商品編碼
2174820
智慧水錶市場:按技術、水錶類型、組件、應用和地區分類-全球預測至2031年Smart Water Meter Market by Technology, Meter Type, Component, Application, and Region - Global Forecast to 2031 |
||||||

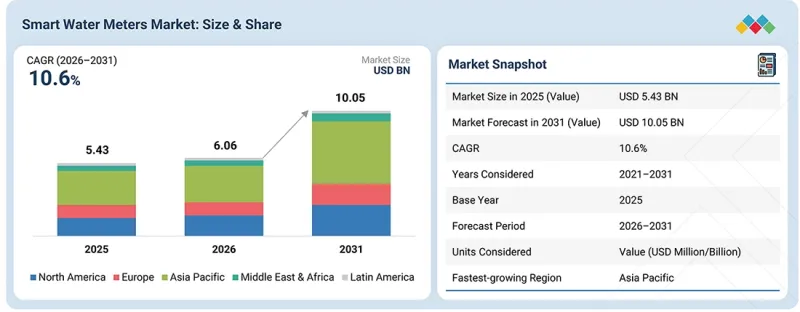
智慧水錶市場預計將從 2026 年的 60.6 億美元成長到 2031 年的 100.5 億美元,預測期內複合年成長率為 10.6%。
受節水需求不斷成長、未計費水量減少以及老舊供水系統現代化改造等因素的推動,智慧水錶市場預計在預測期內將實現顯著成長。供水事業和市政當局正逐步採用智慧水錶,以實現準確及時的用水量計量、及早發現漏水、簡化計費流程以及遠端監控用水情況。
| 調查範圍 | |
|---|---|
| 調查期 | 2021-2031 |
| 基準年 | 2025 |
| 預測期 | 2026-2031 |
| 計算單位 | 金額(百萬/十億美元) |
| 部分 | 技術、儀表類型、應用 |
| 目標區域 | 北美洲、南美洲、歐洲、亞太地區、中東和非洲 |
此外,提高營運效率、加強水資源管理以及實施自動水錶讀數和高級計量基礎設施 (AMI) 的需求預計將進一步增加對物聯網技術和解決方案的需求,包括超音波、電磁水錶和智慧機械水錶。
“從技術角度來看,超音波水錶有望在整個預測期內保持領先地位。”
由於超音波水錶具有測量精度高、無移動部件以及能夠持續遠端監測用水量等優點,預計仍將是智慧水錶市場的領先技術。超音波水錶利用聲音訊號測量水流量,因此無論水流量如何波動,都能提供精確的測量結果,並最大限度地減少設備磨損和損壞。隨著自動抄表 (AMR) 和高級計量基礎設施 (AMI) 通訊技術的普及,超音波水表現在可以將記錄的用水資料遠端傳輸給市政部門。隨著水資源管理的擴展、無收益未計費水量的減少以及老舊基礎設施的更新換代,對超音波智慧水錶的需求必將不斷成長,尤其是在住宅、商業和市政應用領域。
“從用水類型來看,預計在整個預測期內,供水事業將保持領先地位。”
隨著城市和供水事業日益重視提高供水效率、減少未計費水量收益水和加強用水管理,智慧水錶預計將在供水事業產業中快速普及。供水事業業者依靠精準的監測來實現計費準確、用水量監控、洩漏檢測以及配水管網的用水管理。配備自動抄表 (AMR) 和高級計量基礎設施 (AMI) 技術的智慧水錶使供水事業能夠遠端抄表、追蹤異常用水情況並有效監控水錶數量。此外,老舊供水系統現代化改造、節水措施實施以及營運效率提升的整體需求也推動了智慧水錶的積極應用。數據分析支援的互聯水網數量的增加以及遠端監控的普及預計將進一步提升供水事業產業對智慧水錶的需求。
初步調查結果分析
為了收集和檢驗重要的定性和定量信息,並評估未來市場前景,我們對主要行業相關人員、特定領域專家、主要市場參與者的高管和董事以及其他相關領域的專業人士進行了詳細訪談。初步調查的訪談安排如下:
按公司類型分類:一級供應商 - 65%,二級供應商 - 24%,三級供應商 - 11%
按職位:首席級別主管 -30%,總監 -25%,其他 -45%
區域細分:北美 -20%,歐洲 -25%,亞太地區 -30%,中東和非洲 -10%,南美和中美洲 -15%。
註:「其他」包括銷售經理、工程師、區域經理等。
一級公司:2025 年企業收入超過 50 億美元;二級公司:企業收入在 10 億美元至 50 億美元之間;三級公司:企業收入低於 10 億美元。
智慧水錶市場主要由成熟的計量技術公司和智慧水錶製造商主導。各公司全面的計量產品系列、技術實力、產品創新、通訊解決方案,以及對智慧水錶系統的持續投資和在該地區不斷擴大的生產能力,持續塑造著市場競爭格局。
調查範圍
本報告全面定義、描述並預測了智慧水錶市場,涵蓋技術(自動抄表[AMR]和自動抄表基礎設施[AMI])、水錶類型(超音波水錶、電磁水錶、智慧機械水錶)、組件(水錶及配件、IT解決方案、通訊)、應用(供水事業和工業企業)以及地區(北美、歐洲、亞太、以及中東和中東地區)。該報告對市場促進因素、挑戰和限制因素進行了定性和定量分析,並納入了競爭格局評估、市場規模估算和預測、技術趨勢、生態系統分析、商業應用案例、企業標竿分析以及最新發展動態,從而對智慧水錶市場進行了全面的展望。
購買本報告的主要好處
本報告旨在幫助原始設備製造商 (OEM)、安裝商、供水事業、政策制定者、投資者和其他相關人員了解不斷發展的智慧水錶市場。報告提供涵蓋所有主要細分市場和地區的可靠市場預測,並深入分析技術應用、競爭格局和未來成長機會。透過詳盡的市場資訊和策略分析,本報告助力相關人員做出明智的商業決策。
- 關鍵市場動態分析:本分析涵蓋了各種關鍵成長要素(重視節水、減少水浪費、更換過時的水錶、實施智慧城市計畫、供水事業數位化)、阻礙因素成本、互通性問題、網路安全挑戰、升級現有水務基礎設施)、機遇(基於物聯網的測量、實施進階計量基礎設施 (AMI) 和自動抄表(AMR)、遠端監控洩漏檢測、整合數位水資源管理系統)以及挑戰(資料隱私、通訊網路的可靠性、與現有系統的整合、對技術專長的需求)。
- 技術和產品創新:我們將研究超音波和電磁計量、智慧機械表、自動抄表 (AMR) 和高級計量基礎設施 (AMI) 通訊、物聯網 (IoT) 連接、遠端抄表、洩漏檢驗、消耗分析和雲端資料管理方面的進展,並說明這些如何有助於確保準確測量、自動資料收集和增強用水監測。
- 市場發展:本報告重點介紹了水利基礎設施現代化、水資源短缺加劇、都市化、政府主導的節水措施、對高效供水的需求不斷成長以及向數位化公用事業管理的轉變,這些因素正在推動供水事業和工業應用領域採用智慧水計量系統。
- 市場多元化:我們正在評估智慧水錶的應用,從傳統的供水事業到工業設施和其他需要精確用水量測量、自動計費、洩漏監測和高效水資源管理的商業用戶。
- 競爭格局評估:Badger Meter, Inc.(美國)、Kamstrup(丹麥)、Diehl Stiftung &Co. KG(德國)、Landis+Gyr(瑞士)、Aclara Technologies(美國)、Xylem(美國)、Itron, Inc.(美國)、Bmeters Srl(義大利)、Honeywell International Inc.(以色列)、Honey)、Honey)、Honeywell International(以色列)、Honeywell International 以色列) &Co. KG(德國)、Neptune Technology Group Inc.(美國)、Iskraemeco Group(斯洛維尼亞)、Sagemcom(法國)、Wasion Group(中國)、Baylan Water Meters(土耳其)、Wegot Utility Solutions(中國)、Apator SA(波蘭)、美國)、Hizzronics STMNV(瑞士)、Aliservation) Labs, Inc.(美國)和Integra Holding。本報告重點關注AG(瑞士),涵蓋其產品系列、策略舉措、技術能力和競爭地位。
目錄
第1章:引言
第2章執行摘要
第3章重要考察
- 智慧水錶市場為企業帶來極具吸引力的機會
- 智慧水錶市場:按水錶類型和地區分類
- 智慧水錶市場:以水錶類型分類
- 智慧水錶市場:按組件分類
- 智慧水錶市場:依技術分類
- 智慧水錶市場:按應用領域分類
- 智慧水錶市場:按國家/地區分類
第4章 市場概覽
- 市場動態
- 促進因素
- 抑制因子
- 機會
- 任務
- 未滿足的需求和未開發的領域
- 相互關聯的市場與跨產業機遇
- 一級/二級/三級主要公司的策略性舉措
第5章 產業趨勢
- 波特五力分析
- 競爭公司之間的競爭
- 新進入者的威脅
- 供應商的議價能力
- 買方的議價能力
- 替代品的威脅
- 宏觀經濟展望
- GDP趨勢與預測
- 全球供水事業產業趨勢
- 全球產業部門的發展趨勢
- 價值鏈分析
- 生態系分析
- 價格分析
- 智慧水錶平均售價趨勢(以水錶類型分類,2023-2025 年)
- 各地區智慧水錶平均售價趨勢(2023-2025 年)
- 貿易分析
- 進口場景(HS編碼9028)
- 出口情境(HS編碼9028)
- 重大會議和活動(2026-2027)
- 影響客戶業務的趨勢/顛覆性因素
- 投資和資金籌措場景
- 案例研究分析
- 透過引入智慧水錶減少非營利用水。
- 透過大規模基礎設施(AMI)實現家用燃氣表系統的現代化
- 利用先進計量基礎設施(AMI)實現義大利電網現代化
- 美國定價體系對智慧水錶市場的影響
- 主要收費系統
- 價格影響分析
- 對該地區的影響
- 對應用程式的影響
第6章:技術進步、人工智慧的影響、專利、創新與未來應用
- 主要技術
- 進階計量基礎設施(AMI)
- 物聯網 (IoT)
- 互補技術
- 智慧電網基礎設施
- 計量資料管理系統(MDMS)
- 技術和產品藍圖
- 專利分析
- 未來應用
- 人工智慧/生成式人工智慧對智慧水錶市場的影響
- 主要應用場景和市場潛力
- 智慧水錶市場中原始設備製造商 (OEM) 實施的最佳實踐
- 人工智慧/生成式人工智慧在智慧水錶市場引入的案例研究
- 相互關聯的生態系統及其對市場參與者的影響
- 客戶對引入整合人工智慧/GEN AI的智慧水錶的準備情況。
- 成功案例和實際應用範例
- BADGER METER INC.:聯網水錶和洩漏偵測。
- SENSUS(XYLEM):相容AMI的智慧水網管理
- 迪爾計量:人工智慧驅動的水損管理和互聯測量
第7章 監理情勢
- 區域法規和合規性
- 監管機構、政府機構和其他組織
- 業界標準
第8章:顧客趨勢與購買行為
- 決策流程
- 採購過程中的關鍵相關人員及其評估標準
- 採購過程中涉及的關鍵相關人員
- 購買標準
- 實施障礙和內部挑戰
- 市場盈利
- 獲利潛力
- 成本趨勢
第9章:智慧水錶市場:依技術分類
- 自動抄表(AMR)
- 先進計量基礎設施(AMI)
第10章:智慧水錶市場:依應用分類
- 供水事業
- 產業
第11章 智慧水錶:依水錶類型分類
- 電磁
- 超音波型
- 智慧機械
第12章 智慧水錶:依組件分類
- 水錶及配件
- IT解決方案
- 溝通
第13章:智慧水錶市場:按地區分類
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 馬來西亞
- 亞太其他地區
- 歐洲
- 英國
- 法國
- 德國
- 丹麥
- 荷蘭
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 烏拉圭
- 南美洲其他地區
- 中東和非洲
- GCC
- 以色列
- 埃及
- 南非
- 其他中東和非洲地區
第14章 競爭格局
- 概述
- 主要參與企業的策略/優勢,2023年1月至2026年9月
- 2025年市佔率分析
- 2021-2025年收入分析
- 品牌對比
- BADGER METER, INC. (US)
- SENSUS (XYLEM) (US)
- DIEHL STIFTUNG & CO. KG (GERMANY)
- ITRON INC. (US)
- LANDIS+GYR (SWITZERLAND)
- 企業估值矩陣:主要公司,2025 年
- 星星
- 新興領導者
- 玩家種類繁多
- 參與企業
- 企業企業發展:主要公司,2025 年
- 公司估值矩陣:新創企業/中小企業,2025 年
- 先進公司
- 應對力的公司
- 充滿活力的公司
- 起始點
- 競爭標竿分析:新創企業/中小企業,2025 年
- 企業估值和財務指標
- 競爭格局
- 產品發布
- 交易
- 業務拓展
第15章:公司簡介
- 大公司
- BADGER METER, INC.
- LANDIS+GYR
- ITRON INC.
- DIEHL STIFTUNG &CO. KG
- SENSUS(XYLEM)
- HONEYWELL INTERNATIONAL INC.
- WASION HOLDINGS INTERNATIONAL
- KAMSTRUP
- ACLARA(HUBBELL)
- B METERS SRL
- ARAD GROUP
- ZENNER INTERNATIONAL GMBH &CO. KG
- NEPTUNE TECHNOLOGY GROUP INC.
- ISKRAEMECO GROUP
- SAGEMCOM
- 其他主要公司
- BAYLAN WATER METERS
- WEGOT UTILITY SOLUTIONS PVT LTD.
- APATOR SA
- STMICROELECTRONICS
- AXIOMA METERING
- DRIZZLEX
- CONSERVATION LABS, INC.
- INTEGRA
- PHYN LLC
- BOVE TECHNOLOGY
第16章調查方法
第17章附錄
The smart water meter market is projected to grow from USD 6.06 billion in 2026 to USD 10.05 billion by 2031, at a CAGR of 10.6% during the forecast period. The market for smart water meters is predicted to experience significant growth during the projected period as the demand for water conservation, reduction of non-revenue water, and modernization of the increasingly aging water distribution system is growing. Water utilities and municipalities are progressively using smart meters to retrieve precise and on-time measurements of consumption, spot leaks, facilitate billing process, and monitor water usage remotely.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2021-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million/Billion) |
| Segments | Technology, Meter Type, Application |
| Regions covered | North America, South America, Europe, Asia Pacific, Middle East & Africa |
Moreover, the necessity to enhance operational efficiency, reinforce water resources management, and implement automatic reading of meters and advanced metering infrastructure will further enhance the demand for IoT-enabled technologies and solutions, including ultrasonic, electromagnetic, and smart mechanical meters.
"Ultrasonic meters, by technology, are expected to maintain their leading position throughout the forecast period."
It is anticipated that ultrasonic meters will continue to be a leading technology in the smart water meter market due to their excellent accuracy in measurement, lack of moving parts, and ability to continuously and remotely monitor water usage. Ultrasonic meters use acoustic signals to measure water flow based on which it can measure accurately irrespective of the fluctuation in water flow and minimize wear and tear on the equipment. The widespread adoption of AMR and AMI communication technologies allows ultrasonic meters to send cities the recorded usage remotely. The growth in water management, reduced non-revenue water use, and upgrading of very old infrastructure will ensure increased demand of ultrasonic smart water meters in particular for residential, commercial, and municipal applications.
"Water utilities, by application, are expected to maintain their leading position throughout the forecast period."
Water utilities are predicted to see the rapid adoption of smart water meters as urban and utility operators are placing more emphasis on the efficiency of water delivery, reducing non-revenue water and enhancing water consumption management. Water utilities rely on accurate monitoring for billing accuracy, consumption monitoring, detection of leakages, and management of water usage in the distribution network. Smart water meters with AMR and AMI technologies allow utilities to read their meters remotely, track unusual water usage, and monitor the number of meters efficiently. Furthermore, the active introduction of smart water meters is being supported by the overall need to modernize the outdated water supply system, implement water saving schemes, and improve efficiency in operations. Increasing number of connected water networks and remote monitoring supported by data analytics is expected to further boost the demand for smart water meters in the utilities applications.
Breakdown of Primaries
In-depth interviews with key industry participants, subject-matter experts, C-level executives of key market players, and directors, among other experts, were conducted to obtain and verify critical qualitative and quantitative information, as well as to assess future market prospects. The primary interviews were distributed as follows:
By Company Type: Tier 1- 65%, Tier 2 - 24%, and Tier 3 - 11%
By Designation: C-Level Executives - 30%, Directors - 25%, Others - 45%
By Region: North America - 20%, Europe - 25%, Asia Pacific - 30%, Middle East & Africa - 10%, South and Central America - 15%.
Note: Others include sales managers, engineers, and regional managers.
Tier 1 company: revenue > USD 5 billion; tier 2 company: revenue between USD 1 and USD 5 billion; and tier 3 company: revenue < USD 1 billion in 2025
Well-established metering technology companies and smart water meter manufacturers predominantly govern the smart water meter market. Key players profiled in the report include Badger Meter, Inc. (US), Kamstrup (Denmark), Diehl Stiftung & Co. KG (Germany), Landis+Gyr (Switzerland), Aclara Technologies (US), Xylem (US), Itron, Inc. (US), Bmeters Srl (Italy), Honeywell International Inc. (US), MOM Co. Ltd. (South Korea), WaterTech (Arad Group) (Israel), Zenner International GmbH & Co. KG (Germany), Neptune Technology Group Inc. (US), Iskraemeco Group (Slovenia), Sagemcom (France), Wasion Group (China), Baylan Water Meters (Turkey), Wegot Utility Solutions (China), Apator S.A. (Poland), STMicroelectronics N.V. (Switzerland), Axioma Metering (Poland), Drizzlex (US), PHYN LLC (US), Conservation Labs, Inc. (US), and Integra Holding AG (Switzerland). Their strong metering portfolios, technological capabilities, product innovations, communication solutions, and continued investments in smart water metering systems and regional capacity expansion continue to shape the competitive landscape.
Research Coverage
The report provides a comprehensive definition, description, and forecast of the smart water meter market across technology (automated meter reading [AMR] and automated metering infrastructure [AMI]), meter type (ultrasonic meter, electromagnetic meter, and smart mechanical meter), component (meter & accessories, IT solutions, and communications), application (water utilities and industries), and region (North America, Europe, Asia Pacific, South America, and the Middle East & Africa). It delivers qualitative and quantitative analysis of market drivers, restraints, opportunities, and challenges. The study also includes competitive landscape assessment, market sizing and forecasts, technology trends, ecosystem analysis, commercial use cases, company benchmarking, and recent developments to provide a comprehensive view of the smart water meter market.
Key Benefits of Buying the Report
The report is designed to support OEMs, installers, utilities, policymakers, investors, and other stakeholders in understanding the evolving Smart Water Meter market. It provides reliable market forecasts across all major segments and regions while delivering insights into technology adoption, competitive positioning, and future growth opportunities. The report enables stakeholders to make informed business decisions through detailed market intelligence and strategic analysis.
- Analysis of key market dynamics: Covers various key growth factors (emphasis on water conservation; reduction of water wastage; replacing old water meters; adoption of smart city initiatives and digitization of water utilities), restraints (cost of smart meter deployment, issues of interoperability, cybersecurity issues, and the problem of upgrading existing water infrastructure), opportunities (metering through IoT as well as deployment of AMI and AMR, remote monitoring of leak detection, and integration of digital water management systems), and challenges (privacy of data, reliability of communication networks, integration with existing systems, and need for technical expertise).
- Technology and Product Innovation: Examines advancements into progress made in ultrasonic as well as electromagnetic metering, smart mechanical meters, automatic meter reading (AMR) as well as advanced metering infrastructure (AMI) communication, Internet of Things (IoT) connectivity, remote reading of meters, leak detection, consumption analysis, and cloud data management that help guarantee precise measurements, automatic data collection, and enhanced water-use monitoring.
- Market Development: Highlights how water infrastructure modernization, increasing water scarcity, urbanization, government-led water conservation initiatives, growing demand for efficient water distribution, and the transition toward digital utility management spur the implementation of smart water metering systems across water utilities and industrial applications.
- Market Diversification: Evaluates smart water meter applications extending from traditional municipal water utilities to industrial facilities and other commercial users requiring accurate consumption measurement, automated billing, leakage monitoring, and efficient water resource management.
- Competitive Assessment: Provides detailed analysis of leading companies including Badger Meter, Inc. (US), Kamstrup (Denmark), Diehl Stiftung & Co. KG (Germany), Landis+Gyr (Switzerland), Aclara Technologies (US), Xylem (US), Itron, Inc. (US), Bmeters Srl (Italy), Honeywell International Inc. (US), MOM Co. Ltd. (South Korea), WaterTech (Arad Group) (Israel), Zenner International GmbH & Co. KG (Germany), Neptune Technology Group Inc. (US), Iskraemeco Group (Slovenia), Sagemcom (France), Wasion Group (China), Baylan Water Meters (Turkey), Wegot Utility Solutions (China), Apator S.A. (Poland), STMicroelectronics N.V. (Switzerland), Axioma Metering (Poland), Drizzlex (US), PHYN LLC (US), Conservation Labs, Inc. (US), and Integra Holding AG (Switzerland), covering their product portfolios, strategic initiatives, technological capabilities, and competitive positioning.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKETS COVERED AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 LIMITATIONS
- 1.6 STAKEHOLDERS
- 1.7 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN SMART WATER METER MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN SMART WATER METER MARKET
- 3.2 SMART WATER METER MARKET, BY METER TYPE AND REGION
- 3.3 SMART WATER METER MARKET, BY METER TYPE
- 3.4 SMART WATER METER MARKET, BY COMPONENT
- 3.5 SMART WATER METER MARKET, BY TECHNOLOGY
- 3.6 SMART WATER METER MARKET, BY APPLICATION
- 3.7 SMART WATER METER MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Growing emphasis on reducing water losses across distribution networks
- 4.2.1.2 Increasing advanced metering infrastructure projects
- 4.2.2 RESTRAINTS
- 4.2.2.1 Limited government support and inadequate funding
- 4.2.2.2 Short battery lifespan
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Strong focus on aging water infrastructure modernization
- 4.2.3.2 Rising installation of municipal water metering systems
- 4.2.3.3 Expansion of sewage treatment infrastructure
- 4.2.4 CHALLENGES
- 4.2.4.1 Issues in ensuring maintenance, cybersecurity, and data integrity
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 INTENSITY OF COMPETITIVE RIVALRY
- 5.1.2 THREAT OF NEW ENTRANTS
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 THREAT OF SUBSTITUTES
- 5.2 MACROECONOMIC OUTLOOK
- 5.2.1 INTRODUCTION
- 5.2.1.1 Increasing investment in water infrastructure and urbanization
- 5.2.1.2 Growing concerns over water scarcity and conservation
- 5.2.1.3 Growing demand for digital water management
- 5.2.2 GDP TRENDS AND FORECAST
- 5.2.3 TRENDS IN GLOBAL WATER UTILITY SECTOR
- 5.2.4 TRENDS IN GLOBAL INDUSTRIAL SECTOR
- 5.2.1 INTRODUCTION
- 5.3 VALUE CHAIN ANALYSIS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 AVERAGE SELLING PRICE TREND OF SMART WATER METERS, BY METER TYPE, 2023-2025
- 5.5.2 AVERAGE SELLING PRICE TREND OF SMART WATER METERS, BY REGION, 2023-2025
- 5.6 TRADE ANALYSIS
- 5.6.1 IMPORT SCENARIO (HS CODE 9028)
- 5.6.2 EXPORT SCENARIO (HS CODE 9028)
- 5.7 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.9 INVESTMENT AND FUNDING SCENARIO
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 REDUCING NON-REVENUE WATER THROUGH SMART WATER METER DEPLOYMENT
- 5.10.2 MODERNIZING NATIONAL GAS METERING THROUGH LARGE-SCALE AMI DEPLOYMENT
- 5.10.3 MODERNIZING ITALY'S ELECTRICITY GRID THROUGH ADVANCED METERING INFRASTRUCTURE
- 5.11 IMPACT OF US TARIFFS - SMART WATER METER MARKET
- 5.11.1 INTRODUCTION
- 5.11.2 KEY TARIFF RATES
- 5.11.3 PRICE IMPACT ANALYSIS
- 5.11.4 IMPACT ON REGIONS
- 5.11.4.1 North America
- 5.11.4.2 Europe
- 5.11.4.3 Asia Pacific
- 5.11.4.4 South America
- 5.11.4.5 Middle East & Africa
- 5.11.5 IMPACT ON APPLICATIONS
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY TECHNOLOGIES
- 6.1.1 ADVANCED METERING INFRASTRUCTURE (AMI)
- 6.1.2 INTERNET OF THINGS (IOT)
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 SMART GRID INFRASTRUCTURE
- 6.2.2 METER DATA MANAGEMENT SYSTEM (MDMS)
- 6.3 TECHNOLOGY/PRODUCT ROADMAP
- 6.4 PATENT ANALYSIS
- 6.5 FUTURE APPLICATIONS
- 6.6 IMPACT OF AI/GEN AI ON SMART WATER METER MARKET
- 6.6.1 TOP USE CASES AND MARKET POTENTIAL
- 6.6.2 BEST PRACTICES FOLLOWED BY OEMS IN SMART WATER METER MARKET
- 6.6.3 CASE STUDIES RELATED TO AI/GEN AI IMPLEMENTATION IN SMART WATER METER MARKET
- 6.6.4 INTERCONNECTED ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.6.5 CLIENTS' READINESS TO ADOPT AI/GEN AI-INTEGRATED SMART WATER METERS
- 6.7 SUCCESS STORIES AND REAL-WORLD APPLICATIONS
- 6.7.1 BADGER METER INC.: CONNECTED WATER METERING AND LEAK DETECTION
- 6.7.2 SENSUS (XYLEM): AMI-ENABLED SMART WATER NETWORK MANAGEMENT
- 6.7.3 DIEHL METERING: AI-ENABLED WATER LOSS MANAGEMENT AND CONNECTED METERING
7 REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.4 MARKET PROFITABILITY
- 8.4.1 REVENUE POTENTIAL
- 8.4.2 COST DYNAMICS
9 SMART WATER METER MARKET, BY TECHNOLOGY
- 9.1 INTRODUCTION
- 9.2 AUTOMATIC METER READING (AMR)
- 9.2.1 REDUCED MANUAL INTERVENTION FOR DATA COLLECTION TO BOOST SEGMENTAL GROWTH
- 9.3 ADVANCED METERING INFRASTRUCTURE (AMI)
- 9.3.1 HIGH RELIABILITY OF AMI COMMUNICATION INFRASTRUCTURE TO DRIVE MARKET
10 SMART WATER METER MARKET, BY APPLICATION
- 10.1 INTRODUCTION
- 10.2 WATER UTILITIES
- 10.2.1 INVESTMENT IN TRADITIONAL WATER NETWORK UPGRADES TO FUEL SEGMENTAL GROWTH
- 10.3 INDUSTRIES
- 10.3.1 INCREASED FOCUS ON WATER LOSS REDUCTION TO AUGMENT SEGMENTAL GROWTH
11 SMART WATER METER, BY METER TYPE
- 11.1 INTRODUCTION
- 11.2 ELECTROMAGNETIC
- 11.2.1 ENHANCED ACCURACY LEVEL IN WATER TRACKING TO BOOST SEGMENTAL GROWTH
- 11.3 ULTRASONIC
- 11.3.1 EFFECTIVE DETECTION OF LEAKS, BURSTS, AND REVERSE FLOW TO FACILITATE SEGMENTAL GROWTH
- 11.4 SMART MECHANICAL
- 11.4.1 LOW COST TO CREATE LUCRATIVE MARKET GROWTH OPPORTUNITIES IN DEVELOPING COUNTRIES
12 SMART WATER METER, BY COMPONENT
- 12.1 INTRODUCTION
- 12.2 METERS & ACCESSORIES
- 12.2.1 TECHNOLOGICAL INNOVATIONS IN METERING DEVICES TO PROPEL MARKET
- 12.3 IT SOLUTIONS
- 12.3.1 INCREASING DEMAND FOR DATA MANAGEMENT SOFTWARE TO BOLSTER SEGMENTAL GROWTH
- 12.4 COMMUNICATIONS
- 12.4.1 RISING DEVELOPMENT OF LOW-POWER COMMUNICATION TECHNOLOGIES TO BOLSTER SEGMENTAL GROWTH
13 SMART WATER METER MARKET, BY REGION
- 13.1 INTRODUCTION
- 13.2 NORTH AMERICA
- 13.2.1 US
- 13.2.1.1 Increasing investment in water infrastructure modernization and digital utility management to boost market growth
- 13.2.2 CANADA
- 13.2.2.1 1.4.5.2.1 Strong focus on modernizing aging water infrastructure to contribute to market growth
- 13.2.3 MEXICO
- 13.2.3.1 Increasing pressure to reduce distribution losses and manage limited water resources to fuel market growth
- 13.2.1 US
- 13.3 ASIA PACIFIC
- 13.3.1 CHINA
- 13.3.1.1 Rapid urbanization, smart-city development, and continued modernization of municipal water infrastructure to drive market
- 13.3.2 INDIA
- 13.3.2.1 Rapid revolutionization of urban water management and sustainability to boost market growth
- 13.3.3 JAPAN
- 13.3.3.1 Rising need to maintain reliable water services and improve efficiency of utility operations to expedite market growth
- 13.3.4 AUSTRALIA
- 13.3.4.1 Growing concern about drought and need to improve water-use efficiency across urban and regional communities to drive market
- 13.3.5 MALAYSIA
- 13.3.5.1 Increasing need to reduce water loss to contribute to market growth
- 13.3.6 REST OF ASIA PACIFIC
- 13.3.1 CHINA
- 13.4 EUROPE
- 13.4.1 UK
- 13.4.1.1 Water scarcity and government initiatives to boost market growth
- 13.4.2 FRANCE
- 13.4.2.1 Municipal infrastructure modernization and emphasis on reducing water losses to augment market growth
- 13.4.3 GERMANY
- 13.4.3.1 Modernization of municipal water infrastructure and digitalization of utility operations to expedite market growth
- 13.4.4 DENMARK
- 13.4.4.1 Global collaborations for smart water innovation to drive market
- 13.4.5 NETHERLANDS
- 13.4.5.1 Rising need to improve water accountability and network resilience through connected metering solutions to foster market growth
- 13.4.6 REST OF EUROPE
- 13.4.1 UK
- 13.5 SOUTH AMERICA
- 13.5.1 BRAZIL
- 13.5.1.1 Strong focus on reducing water losses and improving utility efficiency to accelerate market growth
- 13.5.2 ARGENTINA
- 13.5.2.1 Growing emphasis on improving water distribution monitoring and reducing non-revenue water to fuel market growth
- 13.5.3 URUGUAY
- 13.5.3.1 Rising need to strengthen water conservation and consumption visibility to contribute to market growth
- 13.5.4 REST OF SOUTH AMERICA
- 13.5.1 BRAZIL
- 13.6 MIDDLE EAST & AFRICA
- 13.6.1 GCC
- 13.6.1.1 Saudi Arabia
- 13.6.1.1.1 Growing focus on groundwater monitoring and conservation to boost market growth
- 13.6.1.2 UAE
- 13.6.1.2.1 Water security strategy 2036 to expedite market growth
- 13.6.1.1 Saudi Arabia
- 13.6.2 ISRAEL
- 13.6.2.1 Expansion of smart water metering for consumption monitoring and water-loss reduction to support market growth
- 13.6.3 EGYPT
- 13.6.3.1 Desalination mega-projects to provide market growth opportunities
- 13.6.4 SOUTH AFRICA
- 13.6.4.1 Modernization of water infrastructure to contribute to market growth
- 13.6.5 REST OF MIDDLE EAST & AFRICA
- 13.6.1 GCC
14 COMPETITIVE LANDSCAPE
- 14.1 OVERVIEW
- 14.2 KEY PLAYER COMPETITIVE STRATEGIES/RIGHT TO WIN, JANUARY 2023- SEPTEMBER 2026
- 14.3 MARKET SHARE ANALYSIS, 2025
- 14.4 REVENUE ANALYSIS, 2021-2025
- 14.5 BRAND COMPARISON
- 14.5.1 BADGER METER, INC. (US)
- 14.5.2 SENSUS (XYLEM) (US)
- 14.5.3 DIEHL STIFTUNG & CO. KG (GERMANY)
- 14.5.4 ITRON INC. (US)
- 14.5.5 LANDIS+GYR (SWITZERLAND)
- 14.6 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 14.6.1 STARS
- 14.6.2 EMERGING LEADERS
- 14.6.3 PERVASIVE PLAYERS
- 14.6.4 PARTICIPANTS
- 14.6.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 14.6.5.1 Company footprint
- 14.6.5.2 Region footprint
- 14.6.5.3 Component footprint
- 14.6.5.4 Meter type footprint
- 14.6.5.5 Application footprint
- 14.7 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 14.7.1 PROGRESSIVE COMPANIES
- 14.7.2 RESPONSIVE COMPANIES
- 14.7.3 DYNAMIC COMPANIES
- 14.7.4 STARTING BLOCKS
- 14.7.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 14.7.5.1 Detailed list of key startups/SMEs
- 14.7.5.2 Competitive benchmarking of key startups/SMEs
- 14.8 COMPANY VALUATION AND FINANCIAL METRICS
- 14.9 COMPETITIVE SCENARIO
- 14.9.1 PRODUCT LAUNCHES
- 14.9.2 DEALS
- 14.9.3 EXPANSIONS
15 COMPANY PROFILES
- 15.1 KEY PLAYERS
- 15.1.1 BADGER METER, INC.
- 15.1.1.1 Business overview
- 15.1.1.2 Products/Solutions/Services offered
- 15.1.1.3 Recent developments
- 15.1.1.3.1 Product launches
- 15.1.1.3.2 Deals
- 15.1.1.3.3 Expansions
- 15.1.1.4 MnM view
- 15.1.1.4.1 Key strengths/Right to win
- 15.1.1.4.2 Strategic choices
- 15.1.1.4.3 Weaknesses/Competitive threats
- 15.1.2 LANDIS+GYR
- 15.1.2.1 Business overview
- 15.1.2.2 Products/Solutions/Services offered
- 15.1.2.3 Recent developments
- 15.1.2.3.1 Product Launches
- 15.1.2.3.2 Deals
- 15.1.2.3.3 Expansions
- 15.1.2.4 MnM view
- 15.1.2.4.1 Key strengths/Right to win
- 15.1.2.4.2 Strategic choices
- 15.1.2.4.3 Weaknesses/Competitive threats
- 15.1.3 ITRON INC.
- 15.1.3.1 Business overview
- 15.1.3.2 Products/Solutions/Services offered
- 15.1.3.3 Recent developments
- 15.1.3.3.1 Product Launches
- 15.1.3.3.2 Deals
- 15.1.3.3.3 Expansions
- 15.1.3.4 MnM view
- 15.1.3.4.1 Key strengths/Right to win
- 15.1.3.4.2 Strategic choices
- 15.1.3.4.3 Weaknesses/Competitive threats
- 15.1.4 DIEHL STIFTUNG & CO. KG
- 15.1.4.1 Business overview
- 15.1.4.2 Products/Solutions/Services offered
- 15.1.4.3 Recent developments
- 15.1.4.3.1 Product Launches
- 15.1.4.3.2 Deals
- 15.1.4.3.3 Expansions
- 15.1.4.4 MnM view
- 15.1.4.4.1 Key strengths/Right to win
- 15.1.4.4.2 Strategic choices
- 15.1.4.4.3 Weaknesses/Competitive threats
- 15.1.5 SENSUS (XYLEM)
- 15.1.5.1 Business overview
- 15.1.5.2 Products/Solutions/Services offered
- 15.1.5.3 Recent developments
- 15.1.5.3.1 Deals
- 15.1.5.3.2 Expansions
- 15.1.5.4 MnM view
- 15.1.5.4.1 Key strengths/Right to win
- 15.1.5.4.2 Strategic choices
- 15.1.5.4.3 Weaknesses/Competitive threats
- 15.1.6 HONEYWELL INTERNATIONAL INC.
- 15.1.6.1 Business overview
- 15.1.6.2 Products/Solutions/Services offered
- 15.1.6.3 Recent developments
- 15.1.6.3.1 Product Launches
- 15.1.6.3.2 Deals
- 15.1.6.3.3 Expansions
- 15.1.7 WASION HOLDINGS INTERNATIONAL
- 15.1.7.1 Business overview
- 15.1.7.2 Products/Solutions/Services offered
- 15.1.7.3 Recent developments
- 15.1.7.3.1 Expansions
- 15.1.7.3.2 Other developments
- 15.1.8 KAMSTRUP
- 15.1.8.1 Business overview
- 15.1.8.2 Products/Solutions/Services offered
- 15.1.8.3 Recent developments
- 15.1.8.3.1 Product Launches
- 15.1.8.3.2 Deals
- 15.1.8.3.3 Expansions
- 15.1.9 ACLARA (HUBBELL)
- 15.1.9.1 Business overview
- 15.1.9.2 Products/Solutions/Services offered
- 15.1.9.3 Recent developments
- 15.1.9.3.1 Deals
- 15.1.9.3.2 Expansions
- 15.1.10 B METERS SRL
- 15.1.10.1 Business overview
- 15.1.10.2 Products/Solutions/Services offered
- 15.1.10.3 Recent developments
- 15.1.10.3.1 Product Launches
- 15.1.10.3.2 Deals
- 15.1.10.3.3 Expansions
- 15.1.11 ARAD GROUP
- 15.1.11.1 Business overview
- 15.1.11.2 Products/Solutions/Services offered
- 15.1.11.3 Recent developments
- 15.1.11.3.1 Product Launches
- 15.1.11.3.2 Expansions
- 15.1.12 ZENNER INTERNATIONAL GMBH & CO. KG
- 15.1.12.1 Business overview
- 15.1.12.2 Products/Solutions/Services offered
- 15.1.12.3 Recent developments
- 15.1.12.3.1 Deals
- 15.1.12.3.2 Expansions
- 15.1.13 NEPTUNE TECHNOLOGY GROUP INC.
- 15.1.13.1 Business overview
- 15.1.13.2 Products/Solutions/Services offered
- 15.1.13.3 Recent developments
- 15.1.13.3.1 Expansions
- 15.1.14 ISKRAEMECO GROUP
- 15.1.14.1 Business overview
- 15.1.14.2 Products/Solutions/Services offered
- 15.1.14.3 Recent developments
- 15.1.14.3.1 Expansions
- 15.1.15 SAGEMCOM
- 15.1.15.1 Business overview
- 15.1.15.2 Products/Solutions/Services offered
- 15.1.1 BADGER METER, INC.
- 15.2 OTHER PLAYERS
- 15.2.1 BAYLAN WATER METERS
- 15.2.2 WEGOT UTILITY SOLUTIONS PVT LTD.
- 15.2.3 APATOR S.A.
- 15.2.4 STMICROELECTRONICS
- 15.2.5 AXIOMA METERING
- 15.2.6 DRIZZLEX
- 15.2.7 CONSERVATION LABS, INC.
- 15.2.8 INTEGRA
- 15.2.9 PHYN LLC
- 15.2.10 BOVE TECHNOLOGY
16 RESEARCH METHODOLOGY
- 16.1 RESEARCH DATA
- 16.1.1 SECONDARY DATA
- 16.1.1.1 List of major secondary sources
- 16.1.1.2 Key data from secondary sources
- 16.1.2 PRIMARY DATA
- 16.1.2.1 List of primary interview participants
- 16.1.2.2 Key industry insights
- 16.1.2.3 Breakdown of primaries
- 16.1.2.4 Key data from primary sources
- 16.1.1 SECONDARY DATA
- 16.2 DATA TRIANGULATION
- 16.3 MARKET SIZE ESTIMATION
- 16.3.1 BOTTOM-UP APPROACH
- 16.3.2 TOP-DOWN APPROACH
- 16.4 DEMAND-SIDE ANALYSIS
- 16.4.1 ASSUMPTIONS FOR DEMAND-SIDE ANALYSIS
- 16.4.2 CALCULATIONS FOR DEMAND-SIDE ANALYSIS
- 16.5 SUPPLY-SIDE ANALYSIS
- 16.5.1 ASSUMPTIONS FOR SUPPLY-SIDE ANALYSIS
- 16.5.2 CALCULATIONS FOR SUPPLY-SIDE ANALYSIS
- 16.6 GROWTH FORECAST ASSUMPTIONS
- 16.7 RESEARCH LIMITATIONS
- 16.8 RISK ASSESSMENT
17 APPENDIX
- 17.1 DISCUSSION GUIDE
- 17.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 17.3 CUSTOMIZATION OPTIONS
- 17.4 RELATED REPORTS
- 17.5 AUTHOR DETAILS
List of Tables
- TABLE 1 SEWAGE TREATMENT PROJECTS IN INDIA
- TABLE 2 INTERCONNECTED MARKETS
- TABLE 3 KEY MOVES AND STRATEGIC FOCUS OF TIER-1/2/3 PLAYERS
- TABLE 4 IMPACT OF PORTER'S FIVE FORCES
- TABLE 5 GDP PERCENTAGE CHANGE, BY KEY COUNTRY, 2021-2029
- TABLE 6 ROLE OF COMPANIES IN SMART WATER METER ECOSYSTEM
- TABLE 7 AVERAGE SELLING PRICE TREND OF SMART WATER METERS, BY METER TYPE, 2023-2025 (USD/UNIT)
- TABLE 8 AVERAGE SELLING PRICE TREND OF SMART WATER METERS, BY REGION, 2023-2025 (USD/UNIT)
- TABLE 9 IMPORT DATA FOR HS CODE 9028-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 10 EXPORT DATA FOR HS CODE 9028-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 11 LIST OF KEY CONFERENCES AND EVENTS, 2026-2027
- TABLE 12 AMI-ENABLED WATER NETWORK MODERNIZATION BY KAMSTRUP
- TABLE 13 LARGE-SCALE SMART GAS METER DEPLOYMENT BY GRDF
- TABLE 14 LARGE-SCALE AMI DEPLOYMENT BY ENEL IN ITALY
- TABLE 15 US-ADJUSTED RECIPROCAL TARIFF RATES
- TABLE 16 EXPECTED CHANGE IN PRICES AND POTENTIAL IMPACT ON MARKET PLAYERS DUE TO TARIFFS
- TABLE 17 LIST OF KEY PATENTS, 2025
- TABLE 18 SMART CITIES & URBAN WATER MANAGEMENT
- TABLE 19 REAL-TIME LEAK DETECTION & WATER LOSS MANAGEMENT
- TABLE 20 IOT-ENABLED & CONNECTED WATER METERING
- TABLE 21 AI-BASED CONSUMPTION ANALYTICS & DEMAND FORECASTING
- TABLE 22 INDUSTRIAL WATER EFFICIENCY, SMART IRRIGATION & SUSTAINABLE WATER MANAGEMENT
- TABLE 23 USE CASES AND MARKET POTENTIAL
- TABLE 24 BEST PRACTICES: USE CASES OF SMART WATER METERS, BY COMPANY
- TABLE 25 CASE STUDIES RELATED TO AI/GEN AI IMPLEMENTATION
- TABLE 26 INTERCONNECTED ECOSYSTEM AND IMPACT ON SMART WATER METER MARKET PLAYERS
- TABLE 27 NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 28 EUROPE: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 29 ASIA PACIFIC: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 30 ROW: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 31 GLOBAL: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 32 GLOBAL INDUSTRY STANDARDS
- TABLE 33 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY APPLICATION (%)
- TABLE 34 BUYING CRITERIA, BY APPLICATION
- TABLE 35 SMART WATER METER MARKET, BY TECHNOLOGY, 2022-2025 (USD MILLION)
- TABLE 36 SMART WATER METER MARKET, BY TECHNOLOGY, 2026-2031 (USD MILLION)
- TABLE 37 AUTOMATIC METER READING (AMR): SMART WATER METER MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 38 AUTOMATIC METER READING (AMR): SMART WATER METER MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 39 ADVANCED METERING INFRASTRUCTURE (AMI): SMART WATER METER MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 40 ADVANCED METERING INFRASTRUCTURE (AMI): SMART WATER METER MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 41 SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 42 SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 43 WATER UTILITIES: SMART WATER METER MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 44 WATER UTILITIES: SMART WATER METER MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 45 INDUSTRIES: SMART WATER METER MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 46 INDUSTRIES: SMART WATER METER MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 47 SMART WATER METER MARKET, BY METER TYPE, 2022-2025 (USD MILLION)
- TABLE 48 SMART WATER METER MARKET, BY METER TYPE, 2026-2031 (USD MILLION)
- TABLE 49 ELECTROMAGNETIC: SMART WATER METER MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 50 ELECTROMAGNETIC: SMART WATER METER MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 51 ULTRASONIC: SMART WATER METER MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 52 ULTRASONIC: SMART WATER METER MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 53 SMART MECHANICAL: SMART WATER METER MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 54 SMART MECHANICAL: SMART WATER METER MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 55 SMART WATER METER MARKET, BY COMPONENT, 2022-2025 (USD MILLION)
- TABLE 56 SMART WATER METER MARKET, BY COMPONENT, 2026-2031 (USD MILLION)
- TABLE 57 METERS & ACCESSORIES: SMART WATER METER MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 58 METERS & ACCESSORIES: SMART WATER METER MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 59 IT SOLUTIONS: SMART WATER METER MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 60 IT SOLUTIONS: SMART WATER METER MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 61 COMMUNICATIONS: SMART WATER METER MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 62 COMMUNICATIONS: SMART WATER METER MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 63 SMART WATER METER MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 64 SMART WATER METER MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 65 SMART WATER METER MARKET, BY REGION, 2022-2025 (MILLION UNITS)
- TABLE 66 SMART WATER METER MARKET, BY REGION, 2026-2031 (MILLION UNITS)
- TABLE 67 NORTH AMERICA: SMART WATER METER MARKET, BY METER TYPE, 2022-2025 (USD MILLION)
- TABLE 68 NORTH AMERICA: SMART WATER METER MARKET, BY METER TYPE, 2026-2031 (USD MILLION)
- TABLE 69 NORTH AMERICA: SMART WATER METER MARKET, BY TECHNOLOGY, 2022-2025 (USD MILLION)
- TABLE 70 NORTH AMERICA: SMART WATER METER MARKET, BY TECHNOLOGY, 2026-2031 (USD MILLION)
- TABLE 71 NORTH AMERICA: SMART WATER METER MARKET, BY COMPONENT, 2022-2025 (USD MILLION)
- TABLE 72 NORTH AMERICA: SMART WATER METER MARKET, BY COMPONENT, 2026-2031 (USD MILLION)
- TABLE 73 NORTH AMERICA: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 74 NORTH AMERICA: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 75 NORTH AMERICA: SMART WATER METER MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 76 NORTH AMERICA: SMART WATER METER MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 77 US: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 78 US: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 79 CANADA: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 80 CANADA: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 81 MEXICO: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 82 MEXICO: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 83 ASIA PACIFIC: SMART WATER METER MARKET, BY METER TYPE, 2022-2025 (USD MILLION)
- TABLE 84 ASIA PACIFIC: SMART WATER METER MARKET, BY METER TYPE, 2026-2031 (USD MILLION)
- TABLE 85 ASIA PACIFIC: SMART WATER METER MARKET, BY TECHNOLOGY, 2022-2025 (USD MILLION)
- TABLE 86 ASIA PACIFIC: SMART WATER METER MARKET, BY TECHNOLOGY, 2026-2031 (USD MILLION)
- TABLE 87 ASIA PACIFIC: SMART WATER METER MARKET, BY COMPONENT, 2022-2025 (USD MILLION)
- TABLE 88 ASIA PACIFIC: SMART WATER METER MARKET, BY COMPONENT, 2026-2031 (USD MILLION)
- TABLE 89 ASIA PACIFIC: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 90 ASIA PACIFIC: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 91 ASIA PACIFIC: SMART WATER METER MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 92 ASIA PACIFIC: SMART WATER METER MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 93 CHINA: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 94 CHINA: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 95 INDIA: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 96 INDIA: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 97 JAPAN: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 98 JAPAN: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 99 AUSTRALIA: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 100 AUSTRALIA: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 101 MALAYSIA: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 102 MALAYSIA: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 103 REST OF ASIA PACIFIC: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 104 REST OF ASIA PACIFIC: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 105 EUROPE: SMART WATER METER MARKET, BY METER TYPE, 2022-2025 (USD MILLION)
- TABLE 106 EUROPE: SMART WATER METER MARKET, BY METER TYPE, 2026-2031 (USD MILLION)
- TABLE 107 EUROPE: SMART WATER METER MARKET, BY TECHNOLOGY, 2022-2025 (USD MILLION)
- TABLE 108 EUROPE: SMART WATER METER MARKET, BY TECHNOLOGY, 2026-2031 (USD MILLION)
- TABLE 109 EUROPE: SMART WATER METER MARKET, BY COMPONENT, 2022-2025 (USD MILLION)
- TABLE 110 EUROPE: SMART WATER METER MARKET, BY COMPONENT, 2026-2031 (USD MILLION)
- TABLE 111 EUROPE: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 112 EUROPE: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 113 EUROPE: SMART WATER METER MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 114 EUROPE: SMART WATER METER MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 115 UK: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 116 UK: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 117 FRANCE: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 118 FRANCE: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 119 GERMANY: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 120 GERMANY: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 121 DENMARK: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 122 DENMARK: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 123 NETHERLANDS: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 124 NETHERLANDS: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 125 REST OF EUROPE: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 126 REST OF EUROPE: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 127 SOUTH AMERICA: SMART WATER METER MARKET, BY METER TYPE, 2022-2025 (USD MILLION)
- TABLE 128 SOUTH AMERICA: SMART WATER METER MARKET, BY METER TYPE, 2026-2031 (USD MILLION)
- TABLE 129 SOUTH AMERICA: SMART WATER METER MARKET, BY TECHNOLOGY, 2022-2025 (USD MILLION)
- TABLE 130 SOUTH AMERICA: SMART WATER METER MARKET, BY TECHNOLOGY, 2026-2031 (USD MILLION)
- TABLE 131 SOUTH AMERICA: SMART WATER METER MARKET, BY COMPONENT, 2022-2025 (USD MILLION)
- TABLE 132 SOUTH AMERICA: SMART WATER METER MARKET, BY COMPONENT, 2026-2031 (USD MILLION)
- TABLE 133 SOUTH AMERICA: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 134 SOUTH AMERICA: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 135 SOUTH AMERICA: SMART WATER METER MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 136 SOUTH AMERICA: SMART WATER METER MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 137 BRAZIL: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 138 BRAZIL: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 139 ARGENTINA: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 140 ARGENTINA: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 141 URUGUAY: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 142 URUGUAY: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 143 REST OF SOUTH AMERICA: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 144 REST OF SOUTH AMERICA: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 145 MIDDLE EAST & AFRICA: SMART WATER METER MARKET, BY METER TYPE, 2022-2025 (USD MILLION)
- TABLE 146 MIDDLE EAST & AFRICA: SMART WATER METER MARKET, BY METER TYPE, 2026-2031 (USD MILLION)
- TABLE 147 MIDDLE EAST & AFRICA: SMART WATER METER MARKET, BY TECHNOLOGY, 2022-2025 (USD MILLION)
- TABLE 148 MIDDLE EAST & AFRICA: SMART WATER METER MARKET, BY TECHNOLOGY, 2026-2031 (USD MILLION)
- TABLE 149 MIDDLE EAST & AFRICA: SMART WATER METER MARKET, BY COMPONENT, 2022-2025 (USD MILLION)
- TABLE 150 MIDDLE EAST & AFRICA: SMART WATER METER MARKET, BY COMPONENT, 2026-2031 (USD MILLION)
- TABLE 151 MIDDLE EAST & AFRICA: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 152 MIDDLE EAST & AFRICA: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 153 MIDDLE EAST & AFRICA: SMART WATER METER MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 154 MIDDLE EAST & AFRICA: SMART WATER METER MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 155 GCC: SMART WATER METER MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 156 GCC: SMART WATER METER MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 157 SAUDI ARABIA: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 158 SAUDI ARABIA: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 159 UAE: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 160 UAE: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 161 ISRAEL: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 162 ISRAEL: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 163 EGYPT: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 164 EGYPT: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 165 SOUTH AFRICA: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 166 SOUTH AFRICA: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 167 REST OF MIDDLE EAST & AFRICA: SMART WATER METER MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 168 REST OF MIDDLE EAST & AFRICA: SMART WATER METER MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 169 SMART WATER METER MARKET: OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS, JANUARY 2023-SEPTEMBER 2026
- TABLE 170 SMART WATER METER MARKET: DEGREE OF COMPETITION, 2025
- TABLE 171 SMART WATER METER MARKET: REGION FOOTPRINT
- TABLE 172 SMART WATER METER MARKET: COMPONENT FOOTPRINT
- TABLE 173 SMART WATER METER MARKET: METER TYPE FOOTPRINT
- TABLE 174 SMART WATER METER MARKET: APPLICATION FOOTPRINT
- TABLE 175 SMART WATER METER MARKET: DETAILED LIST OF KEY STARTUPS/SMES
- TABLE 176 SMART WATER METER MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
- TABLE 177 SMART WATER METER MARKET: PRODUCT LAUNCHES, JANUARY 2023-SEPTEMBER 2026
- TABLE 178 SMART WATER METER MARKET: DEALS, JANUARY 2023-SEPTEMBER 2026
- TABLE 179 SMART WATER METER MARKET: EXPANSIONS, JANUARY 2023-SEPTEMBER 2026
- TABLE 180 BADGER METER, INC.: COMPANY OVERVIEW
- TABLE 181 BADGER METER, INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 182 BADGER METER, INC.: PRODUCT LAUNCHES
- TABLE 183 BADGER METER, INC.: DEALS
- TABLE 184 BADGER METER, INC.: EXPANSIONS
- TABLE 185 LANDIS+GYR: COMPANY OVERVIEW
- TABLE 186 LANDIS+GYR: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 187 LANDIS+GYR: PRODUCT LAUNCHES
- TABLE 188 LANDIS+GYR: DEALS
- TABLE 189 LANDIS+GYR: EXPANSIONS
- TABLE 190 ITRON INC.: COMPANY OVERVIEW
- TABLE 191 ITRON INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 192 ITRON INC.: PRODUCT LAUNCHES
- TABLE 193 ITRON INC.: DEALS
- TABLE 194 ITRON INC.: EXPANSIONS
- TABLE 195 DIEHL STIFTUNG & CO. KG: COMPANY OVERVIEW
- TABLE 196 DIEHL STIFTUNG & CO. KG: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 197 DIEHL STIFTUNG & CO. KG: PRODUCT LAUNCHES
- TABLE 198 DIEHL STIFTUNG & CO. KG: DEALS
- TABLE 199 DIEHL STIFTUNG & CO. KG: EXPANSIONS
- TABLE 200 SENSUS (XYLEM): COMPANY OVERVIEW
- TABLE 201 SENSUS (XYLEM): PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 202 SENSUS (XYLEM): DEALS
- TABLE 203 SENSUS (XYLEM): EXPANSIONS
- TABLE 204 HONEYWELL INTERNATIONAL INC.: COMPANY OVERVIEW
- TABLE 205 HONEYWELL INTERNATIONAL INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 206 HONEYWELL INTERNATIONAL INC.: PRODUCT LAUNCHES
- TABLE 207 HONEYWELL INTERNATIONAL INC.: DEALS
- TABLE 208 HONEYWELL INTERNATIONAL INC.: EXPANSIONS
- TABLE 209 WASION HOLDINGS INTERNATIONAL: COMPANY OVERVIEW
- TABLE 210 WASION HOLDINGS INTERNATIONAL: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 211 WASION HOLDINGS INTERNATIONAL: EXPANSIONS
- TABLE 212 WASION HOLDINGS INTERNATIONAL: OTHER DEVELOPMENTS
- TABLE 213 KAMSTRUP: COMPANY OVERVIEW
- TABLE 214 KAMSTRUP: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 215 KAMSTRUP: PRODUCT LAUNCHES
- TABLE 216 KAMSTRUP: DEALS
- TABLE 217 KAMSTRUP: EXPANSIONS
- TABLE 218 ACLARA (HUBBELL): COMPANY OVERVIEW
- TABLE 219 ACLARA (HUBBELL): PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 220 ACLARA (HUBBELL): DEALS
- TABLE 221 ACLARA (HUBBELL): EXPANSIONS
- TABLE 222 B METERS SRL: COMPANY OVERVIEW
- TABLE 223 B METERS SRL: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 224 B METERS SRL: PRODUCT LAUNCHES
- TABLE 225 B METERS SRL: DEALS
- TABLE 226 B METERS SRL: EXPANSIONS
- TABLE 227 ARAD GROUP: COMPANY OVERVIEW
- TABLE 228 ARAD GROUP: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 229 ARAD GROUP: PRODUCT LAUNCHES
- TABLE 230 ARAD GROUP: EXPANSIONS
- TABLE 231 ZENNER INTERNATIONAL GMBH & CO. KG: COMPANY OVERVIEW
- TABLE 232 ZENNER INTERNATIONAL GMBH & CO. KG: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 233 ZENNER INTERNATIONAL GMBH & CO. KG: DEALS
- TABLE 234 ZENNER INTERNATIONAL GMBH & CO. KG: EXPANSIONS
- TABLE 235 NEPTUNE TECHNOLOGY GROUP INC.: COMPANY OVERVIEW
- TABLE 236 NEPTUNE TECHNOLOGY GROUP INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 237 NEPTUNE TECHNOLOGY GROUP INC.: EXPANSIONS
- TABLE 238 ISKRAEMECO GROUP: COMPANY OVERVIEW
- TABLE 239 ISKRAEMECO GROUP: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 240 ISKRAEMECO GROUP: EXPANSIONS
- TABLE 241 SAGEMCOM: COMPANY OVERVIEW
- TABLE 242 SAGEMCOM: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 243 BAYLAN WATER METERS: COMPANY OVERVIEW
- TABLE 244 WEGOT UTILITY SOLUTIONS PVT LTD.: COMPANY OVERVIEW
- TABLE 245 APATOR S.A.: COMPANY OVERVIEW
- TABLE 246 STMICROELECTRONICS: COMPANY OVERVIEW
- TABLE 247 AXIOMA METERING: COMPANY OVERVIEW
- TABLE 248 DRIZZLEX: COMPANY OVERVIEW
- TABLE 249 CONSERVATION LABS, INC.: COMPANY OVERVIEW
- TABLE 250 INTEGRA: COMPANY OVERVIEW
- TABLE 251 PHYN LLC: COMPANY OVERVIEW
- TABLE 252 BOVE TECHNOLOGY: COMPANY OVERVIEW
List of Figures
- FIGURE 1 SMART WATER METER MARKET SEGMENTATION AND REGIONAL SCOPE
- FIGURE 2 SMART WATER METER MARKET SCENARIO
- FIGURE 3 GLOBAL SMART WATER METER MARKET SIZE, 2022-2031
- FIGURE 4 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN SMART WATER METER MARKET, 2023-2026
- FIGURE 5 DISRUPTIONS INFLUENCING GROWTH OF SMART WATER METER MARKET
- FIGURE 6 HIGH-GROWTH SEGMENTS IN SMART WATER METER MARKET, 2026-2031
- FIGURE 7 ASIA PACIFIC TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 8 INCREASING INVESTMENT IN MUNICIPAL WATER NETWORKS AND SMART CITIES TO DRIVE MARKET
- FIGURE 9 ULTRASONIC SEGMENT AND NORTH AMERICA ACCOUNTED FOR LARGEST MARKET SHARES IN 2025
- FIGURE 10 ULTRASONIC SEGMENT TO REGISTER HIGHEST GROWTH RATE FROM 2026 TO 2031
- FIGURE 11 IT SOLUTIONS SEGMENT TO EXHIBIT HIGHEST CAGR BETWEEN 2026 AND 2031
- FIGURE 12 AUTOMATED METER READING (AMR) SEGMENT TO BE FASTEST-GROWING BETWEEN 2026 AND 2031
- FIGURE 13 INDUSTRIES SEGMENT TO EXHIBIT HIGHER GROWTH RATE FROM 2026 TO 2031
- FIGURE 14 CHINA TO REGISTER HIGHEST CAGR IN GLOBAL SMART WATER METER MARKET DURING FORECAST PERIOD
- FIGURE 15 DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 16 SMART WATER METER INSTALLATIONS IN ASHEVILLE, US
- FIGURE 17 PORTER'S FIVE FORCES ANALYSIS
- FIGURE 18 SMART WATER METER VALUE CHAIN ANALYSIS
- FIGURE 19 SMART WATER METER ECOSYSTEM
- FIGURE 20 ASP TREND OF SMART WATER METERS, BY METER TYPE, 2023-2025
- FIGURE 21 ASP TREND OF SMART WATER METERS, BY REGION, 2023-2025
- FIGURE 22 IMPORT DATA FOR HS CODE 9028-COMPLIANT PRODUCTS FOR TOP FIVE COUNTRIES, 2021-2025
- FIGURE 23 EXPORT DATA FOR HS CODE 9028-COMPLIANT PRODUCTS FOR TOP FIVE COUNTRIES, 2021-2025
- FIGURE 24 TRENDS/DISRUPTIONS INFLUENCING CUSTOMER BUSINESS
- FIGURE 25 INVESTMENT AND FUNDING SCENARIO
- FIGURE 26 PATENTS APPLIED AND GRANTED, 2016-2025
- FIGURE 27 FUTURE APPLICATIONS OF SMART WATER METER
- FIGURE 28 REAL-WORLD APPLICATIONS
- FIGURE 29 DECISION-MAKING FACTORS IN SMART WATER METER MARKET
- FIGURE 30 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY APPLICATION
- FIGURE 31 KEY BUYING CRITERIA, BY APPLICATION
- FIGURE 32 SMART WATER METER ADOPTION BARRIERS AND INTERNAL CHALLENGES
- FIGURE 33 ADVANCED METERING INFRASTRUCTURE (AMI) SEGMENT HELD LARGER MARKET SHARE IN 2025
- FIGURE 34 WATER UTILITIES SEGMENT CAPTURED MAJORITY OF MARKET SHARE IN 2025
- FIGURE 35 ULTRASONIC SEGMENT ACCOUNTED FOR LARGEST MARKET SHARE IN 2025
- FIGURE 36 METERS & ACCESSORIES SEGMENT ACCOUNTED FOR MAJORITY OF MARKET SHARE IN 2025
- FIGURE 37 CHINA TO REGISTER HIGHEST CAGR IN GLOBAL SMART WATER METER MARKET FROM 2026 TO 2031
- FIGURE 38 NORTH AMERICA HELD LARGEST MARKET SHARE IN 2025
- FIGURE 39 NORTH AMERICA: SMART WATER METER MARKET SNAPSHOT
- FIGURE 40 ASIA PACIFIC: SMART WATER METER MARKET SNAPSHOT
- FIGURE 41 MARKET SHARE ANALYSIS OF COMPANIES PROVIDING SMART WATER METERS, 2025
- FIGURE 42 SMART WATER METER MARKET: REVENUE ANALYSIS OF TOP PLAYERS, 2021-2025
- FIGURE 43 BRAND COMPARATIVE ANALYSIS
- FIGURE 44 SMART WATER METER MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- FIGURE 45 SMART WATER METER MARKET: COMPANY FOOTPRINT
- FIGURE 46 SMART WATER METER MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
- FIGURE 47 COMPANY VALUATION
- FIGURE 48 FINANCIAL METRICS (EV/EBITDA)
- FIGURE 49 BADGER METER, INC.: COMPANY SNAPSHOT
- FIGURE 50 LANDIS+GYR: COMPANY SNAPSHOT
- FIGURE 51 ITRON INC.: COMPANY SNAPSHOT
- FIGURE 52 HONEYWELL INTERNATIONAL INC.: COMPANY SNAPSHOT
- FIGURE 53 WASION HOLDINGS INTERNATIONAL: COMPANY SNAPSHOT
- FIGURE 54 SMART WATER METER MARKET: RESEARCH DESIGN
- FIGURE 55 SMART WATER METER MARKET: DATA TRIANGULATION
- FIGURE 56 SMART WATER METER MARKET: BOTTOM-UP APPROACH
- FIGURE 57 SMART WATER METER MARKET: TOP-DOWN APPROACH
- FIGURE 58 SMART WATER METER MARKET: DEMAND-SIDE ANALYSIS
- FIGURE 59 METRICS CONSIDERED FOR ANALYZING DEMAND FOR SMART WATER METERS
- FIGURE 60 KEY METRICS CONSIDERED FOR ASSESSING SUPPLY OF SMART WATER METER PROVIDERS
- FIGURE 61 SMART WATER METER MARKET: SUPPLY-SIDE ANALYSIS
- FIGURE 62 MARKET SHARE ANALYSIS OF SMART WATER METER MARKET, 2025

 智慧水錶市場:全球市場預測,2026-2032年485 遠程水錶市場:全球市場預測,2026-2032 年遠端傳輸預付水錶市場:全球市場預測,2026-2032年
 智慧水錶市場規模、佔有率、成長、全球產業分析、區域趨勢及2026年至2034年預測。電子遠程水錶市場:全球市場預測,2026-2032年
 智慧水錶市場機會、成長要素、產業趨勢分析及2026-2035年預測。
 水網遙測市場規模、佔有率和成長分析:按組件、技術、應用、最終用戶、部署類型和地區分類-2026-2033年產業預測
 智慧水錶:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)智慧水錶市場:按組件、通訊方式、測量技術、通訊架構、安裝類型、電源、應用和最終用戶分類-2026-2032年全球市場預測
 美國供水事業應對資料中心擴張的策略:機會、趨勢與展望