


 |
市場調查報告書
商品編碼
2164995
低全球暖化潛勢冷媒市場:按類型、應用和地區分類-全球預測至2031年Low GWP Refrigerants Market by Type (Inorganics, Fluorocarbons, Hydrocarbons), Application (Industrial, Commercial, Domestic Refrigeration, Stationary Air Conditioning, Mobile Air Conditioning, Others), and Region - Global Forecast To 2031 |
||||||

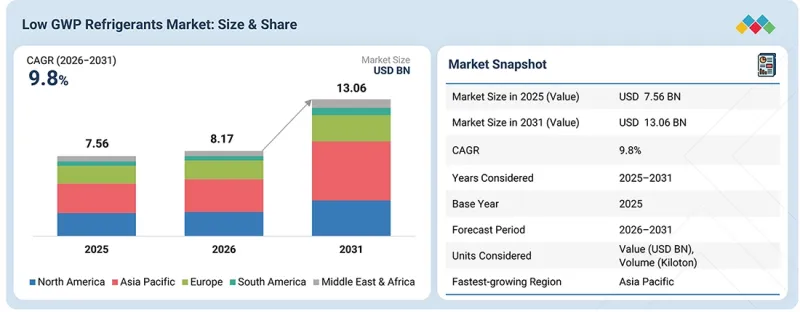
預計到 2031 年,低全球暖化潛勢冷媒市場規模將達到 135 億美元,而 2026 年為 84 億美元,預測期內複合年成長率為 10.0%。
| 調查範圍 | |
|---|---|
| 調查期 | 2023-2031 |
| 基準年 | 2025 |
| 預測期 | 2026-2031 |
| 計算單位 | 金額(百萬/十億美元) 數量(千噸) |
| 部分 | 類型、應用和區域 |
| 目標區域 | 北美洲、亞太地區、歐洲、中東和非洲、南美洲 |
未來,低全球暖化潛勢(GWP)冷媒市場預計將加速成長,這主要得益於各行各業(包括工業、商業、住宅、汽車和冷鏈應用)對環保、高效、可靠且永續的製冷和空調系統的需求不斷成長。日益嚴格的環境法規推動了這一市場擴張,加速了高GWP冷媒的淘汰,並促使人們對現代化冷凍和冷卻基礎設施的投資激增。此外,低GWP冷媒在工業冷凍、商業冷卻、家用電器、汽車空調和熱泵系統等領域的應用也進一步推高了對這些冷媒的需求。如今,冷凍和空調系統的運作已無法忽視其環境影響。食品加工廠、冷庫、醫療機構、商業建築和車輛都需要有效率、可靠且符合環境法規的冷凍空調系統。對環境目標和能源效率日益成長的需求也進一步推動了市場發展。需求正在各個領域蔓延,低全球暖化潛值冷媒的使用量正在增加。
“在預測期內,含氟冷媒預計將成為低全球暖化潛值冷媒市場中最大的細分市場。”
在低全球暖化潛勢(GWP)冷媒市場中,含氟冷媒預計將佔據最大的市場佔有率。這主要歸功於其在製冷和暖通空調(HVAC)設備領域豐富的應用經驗、卓越的製冷性能、優異的能耗特性以及與大多數現代和現有設備的兼容性。此外,低GWP氟碳化合物技術,例如氫氟烯烴(HFO)和低GWP氫氟碳化合物(HFC)混合物,也被廣泛用作高GWP冷媒的替代品。這些冷媒廣泛應用於商業冷凍、工業製冷、固定式空調、汽車空調、熱泵以及其他冷凍和特殊冷凍應用。對節能製冷、監管要求、高GWP冷媒替代品以及可靠系統性能的需求不斷成長,正在推動含氟冷媒市場的發展。
“在預測期內,商用製冷預計將成為低全球暖化潛值冷媒市場中最大的應用領域。”
在預測期內,受節能製冷系統需求成長、高全球暖化潛值(GWP)冷媒的替代以及超級市場、零售、餐飲服務和商業冷凍基礎設施擴張等因素的推動,商用冷凍應用領域預計將佔據低全球暖化潛值冷媒市場的最大佔有率。低全球暖化潛值冷媒主要用於商用冷凍應用,例如展示櫃、冷藏室、中央冷凍系統、食品儲存以及其他需要溫度控制的應用。對提高能源效率、減少溫室氣體排放、遵守環境法規以及實現更佳溫度控制的日益成長的需求,將推動商用製冷領域對低全球暖化潛值冷媒解決方案的需求。
“在預測期內,亞太地區有望成為低全球暖化潛值冷媒市場最大的地區。”
預計到2031年,亞太地區低全球暖化潛值(GWP)冷媒市場將實現顯著的營收成長。這主要得益於快速的都市化和工業化進程、製造地的持續擴張以及對冷鏈、暖通空調(HVAC)、製冷和其他工業冷卻系統投資的增加。快速發展的商業冷凍、工業冷凍、食品加工和製造業預計也將推動亞太地區對低GWP冷媒的需求。商業製冷、工業製冷、固定式暖通空調、移動式暖通空調、冷鏈應用和熱泵的興起,以及對高性能、高可靠性冷卻、安全性和合規性的需求,以及對專業冷鏈基礎設施、食品飲料製造和暖通空調系統投資的增加,預計將在預測期內略微推動亞太地區低GWP冷媒市場的穩定成長。此外,高GWP冷媒的逐步減少以及天然冷媒和其他新型低GWP混合冷媒的日益普及,也為市場的長期穩定成長提供了支撐。
依公司類型分類:一級供應商:40%,二級供應商:30%,三級供應商:30%
按職位:董事:30%,經理:20%,其他:50%
按地區分類:北美:20%,歐洲:10%,亞太地區:40%,南美:10%,中東和非洲:20%
註:其他職位包括銷售經理、市場經理和產品經理。
第一級:超過10億美元;第二級:5億美元至10億美元;第三級:低於5億美元。
本研究對低全球暖化潛勢冷媒市場的主要參與者進行了詳細的競爭分析,包括公司簡介、近期發展和主要市場策略。
調查範圍
本研究報告根據「類型」(無機、氟化、碳氫化合物)和「應用」(工業製冷、商業製冷、家用冷凍、固定式空調、汽車空調及其他應用)對低全球暖化潛值(GWP)冷媒市場進行細分。報告詳細闡述了影響低GWP冷媒市場成長的促進因素、阻礙因素、挑戰和機會。該報告還對主要行業參與者進行了深入分析,包括其業務概況、產品組合以及與低GWP冷媒市場相關的關鍵策略,例如併購、產品發布、合作和業務擴張。此外,該報告還對低GWP冷媒市場生態系統中的新興企業進行了競爭考察。
購買本報告的理由
本報告為市場領導和新參與企業提供低全球暖化潛勢(GWP)冷媒市場及其各細分市場最準確的銷售數據估算。它幫助相關人員了解競爭格局,獲得更深入的洞察以更好地定位自身業務,並制定合適的打入市場策略。此外,報告還提供有關市場趨勢、關鍵市場促進因素和挑戰的資訊。
本報告深入分析了以下幾點:
- 分析可分為關鍵促進因素(嚴格的法規和高全球暖化潛勢冷媒的分階段減少、對節能製冷和暖通空調系統的需求不斷成長,以及冷鏈、食品加工和冷藏保管基礎設施的擴張)、阻礙因素(低全球暖化潛值冷媒系統的初始成本高,以及與現有製冷設備的有限相容性)、機遇(二氧化碳、氨和碳氫化合物等天然冷媒的採用率提高、新興市場對低全球暖化潛勢冷媒的需求不斷成長,以及熱泵和下一代暖通空調系統的部署增加)和挑戰(某些低全球暖化潛值冷媒的易燃性和毒性風險,以及缺乏技術專長和冷媒回收基礎設施)。
- 產品開發/創新:深入了解低全球暖化潛值冷媒市場的未來技術、研發活動以及產品/服務發布。
- 市場發展:盈利市場的全面資訊-本報告分析了各個地區的低全球暖化潛值冷媒市場。
- 市場多元化:有關低全球暖化潛值冷媒市場的新產品和服務、未開發地區、近期趨勢和投資的全面資訊。
- 競爭評估:我們對主要公司的市場佔有率、成長策略和服務產品進行詳細評估。
目錄
第1章:引言
第2章執行摘要
第3章重要考察
- 低全球暖化潛勢冷媒市場參與者面臨極具吸引力的商機。
- 低全球暖化潛勢冷媒市場(按類型)
- 低全球暖化潛勢冷媒市場:按應用領域分類
- 低全球暖化潛勢冷媒市場:按國家/地區分類
第4章 市場概覽
- 市場動態
- 促進因素
- 抑制因子
- 機會
- 任務
- 未滿足的需求和未開發的領域
- 低全球暖化潛勢冷媒市場尚未滿足的需求
- 未開發市場中的機遇
- 相互關聯的市場與跨產業機遇
- 相互關聯的市場
- 跨產業機遇
- 新的經營模式與生態系轉型
- 新經營模式
- 生態系的轉變
- 1/2/3級玩家的策略舉措
- 主要進展和戰略重點
第5章 產業趨勢
- 波特五力分析
- 替代品的威脅
- 供應商的議價能力
- 新進入者的威脅
- 買方的議價能力
- 競爭公司之間的競爭
- 宏觀經濟展望
- 全球GDP趨勢
- 價值鏈分析
- 生態系分析
- 定價分析
- 各地區平均售價趨勢
- 產品平均售價趨勢
- 貿易分析
- 進口方案(HS編碼281410)
- 出口方案(HS編碼281410)
- 進口方案(HS編碼382768)
- 出口方案(HS編碼382768)
- 重要會議和活動
- 影響客戶業務的趨勢與變革
- 投資和資金籌措場景
- 案例研究分析
- 用於食品和飲料行業的低全球暖化潛值冷媒
- 用於冷鏈應用的低全球暖化潛值冷媒
- 2025年美國關稅對低全球暖化潛勢冷媒市場的影響
- 主要關稅稅率
- 價格影響分析
- 對該地區的影響
- 對終端用戶產業的影響
第6章:技術進步、人工智慧的影響、專利與創新
- 主要新興技術
- 新一代超低全球暖化潛值冷媒
- 先進的低全球暖化潛值冷媒混合物
- 高效率製冷系統,填充量低
- 互補技術
- 冷媒回收、回收和再生技術
- 先進的洩漏檢測和冷媒管理系統
- 相關技術
- 熱泵和下一代暖通空調系統
- 人工智慧驅動的冷凍系統監控與最佳化
- 技術和產品藍圖
- 短期(2026-2027 年)| 最佳化和效能提升
- 中期計劃(2027-2030 年)| 擴張與標準化
- 長期規劃(2030-2035年及以後)| 先進的功能與永續創新
- 專利分析
- 專利的法律狀況
- 管轄權分析
- 未來應用
- 先進的低全球暖化潛值冷媒和高效冷卻技術
- 自動冷凍控制和先進的系統技術
- 智慧型冷凍性能監測系統
- 數位化製造和製冷系統的整合平台
- 先進的冷凍技術和高性能冷卻技術
- 人工智慧/生成式人工智慧對低全球暖化潛值冷媒市場的影響
- 主要應用場景和市場潛力
- 低全球暖化潛勢冷媒市場的最佳實踐
- 人工智慧在低全球暖化潛勢冷媒市場的應用案例研究
- 相互關聯的相鄰生態系及其對市場參與者的影響
- 客戶對低全球暖化潛值冷媒市場引進人工智慧技術的準備情況
第7章:監理情勢與永續發展舉措
- 區域法規和合規性
- 監管機構、政府機構和其他組織
- 業界標準
- 監理政策舉措
- 安全協定
- 永續
- 標準化
- 循環經濟
- 永續發展計劃
- 與熱性能、環境和安全相關的舉措
- 關於永續性影響和監管政策的舉措
- 認證、標籤和環境標準
第8章:顧客趨勢與購買行為
- 決策流程
- 主要相關人員和採購標準
- 採購過程中的關鍵相關人員
- 購買標準
- 實施障礙和內部挑戰
- 各終端用戶產業未滿足的需求
- 市場盈利
- 獲利潛力
- 成本趨勢
- 提高關鍵終端用戶產業利潤率的機會
第9章:低全球暖化潛勢冷媒市場:按類型分類
- 無機化合物
- 氟碳化合物
- 碳氫化合物
第10章 低全球暖化潛勢冷媒市場:依應用領域分類
- 工業製冷
- 商業冷凍
- 家用冰櫃和冰箱
- 固定式空調
- 攜帶式空調
- 其他用途
第11章 低全球暖化潛值冷媒市場:依地區分類
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 法國
- 英國
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 亞太其他地區
- 中東和非洲
- 海灣合作理事會國家
- 南非
- 其他中東和非洲地區
- 南美洲
- 巴西
- 阿根廷
- 南美洲其他地區
第12章 競爭格局
- 主要參與企業的策略/優勢
- 收入分析(2021-2025)
- 市佔率分析(2025 年)
- 產品對比
- 企業估值矩陣:主要公司,2025 年
- 明星公司
- 新興領導者
- 玩家種類繁多
- 參與企業
- 企業企業發展:主要公司,2025 年
- 公司估值矩陣:新創企業/中小企業,2025 年
- 先進公司
- 應對力的公司
- 充滿活力的公司
- 起始點
- 競爭標竿分析:新創企業/中小企業,2025 年
- 企業估值和財務指標
- 財務指標
- 企業估值
- 企業估值
- 競爭格局
- 新產品發布
- 交易
- 業務拓展
第13章:公司簡介
- 大公司
- SOLSTICE ADVANCED MATERIALS, INC.
- THE CHEMOURS COMPANY
- DAIKIN INDUSTRIES, LTD.
- ARKEMA
- ORBIA
- LINDE PLC
- AGC INC.
- DONGYUE GROUP
- SINOCHEM HOLDINGS CORPORATION LTD.
- ZHEJIANG JUHUA CO., LTD.
- 其他主要公司
- A-GAS INTERNATIONAL LIMITED
- AIR LIQUIDE
- ENGAS PTY LTD
- GTS SPA
- GUJARAT FLUOROCHEMICALS LIMITED
- HARP INTERNATIONAL LTD.
- HYCHILL AUSTRALIA PTY LTD.
- JIANGSU MEILAN CHEMICAL CO. LTD.
- NAVIN FLUORINE INTERNATIONAL LIMITED.
- ZHEJIANG SANMEI CHEMICAL INDUSTRY CO., LTD.
- PUYANG ZHONGWEI FINE CHEMICAL CO., LTD.
- SHANDONG YUE'AN NEW MATERIAL CO., LTD.
- SRF LIMITED
- TAZZETTI SPA
- ZHEJIANG YONGHE REFRIGERANT CO., LTD.
第14章調查方法
第15章附錄
The low GWP refrigerants market is expected to reach USD 13.50 billion by 2031 from USD 8.40 billion in 2026, at a CAGR of 10.0% during the forecast period.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2023-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million/Billion) Volume (Kiloton) |
| Segments | Type, Application, and Region |
| Regions covered | North America, Asia Pacific, Europe, Middle East & Africa, and South America |
The low GWP refrigerants market is expected to grow at a faster pace in the future as the demand for refrigeration and air conditioning systems that are environmentally clean, efficient, reliable, and sustainable is increasing in different sectors of the economy such as industrial, commercial, domestic, automotive, and cold chain. Expansion of the market is being supported by strict environmental regulations, which result in the phase-out of high-GWP refrigerants and the upsurge of investments in modern refrigeration and cooling infrastructure. Apart from that, using low-GWP refrigerants in areas like industrial refrigeration, commercial cooling, home appliances, automotive air-conditioning, and heat pump systems has also led to the requirement of Low GWP refrigerants. Basically, these days one cannot run refrigeration and air-conditioning systems without considering the effect of the same on the environment. Food processing plants, cold storage units, healthcare centers, commercial buildings, and vehicles need their refrigeration or air-conditioning systems to be environmentally compliant, yet efficient and reliable. And rising environmental targets and energy-efficiency demands are driving the market further. The demand is spreading to different sectors, and the usage of low-GWP refrigerants is rising.
"Fluorocarbons are projected to be the largest type segment in the low-GWP refrigerants market during the forecast period."
In the low-GWP refrigerants market, fluorocarbons in the type segment are expected to hold the largest share, because of their ubiquitous use in refrigeration and air-conditioning equipment, good cooling qualities, attractive energy consumption characteristics, and compatibility with a large proportion of modern and existing equipment. Besides this, lower GWP fluorocarbon technologies such as hydrofluoroolefins (HFOs) and low-GWP hydrofluorocarbon (HFC) blends are also being widely used as replacements for high-GWP refrigerants. These types of refrigerants have wide applications in commercial refrigeration, industrial refrigeration, stationary air conditioning, mobile air conditioning, heat pumps, and other cooling and specialty cooling applications. Increasing demand for energy-efficient cooling, rules and regulations, replacement of high GWP refrigerants, and dependable system performance are among the reasons behind the growth of the fluorocarbon segment.
"Commercial refrigeration is projected to be the largest application segment in the low-GWP refrigerants market during the forecast period."
During the forecast period, commercial refrigeration in the application segment is projected to hold the largest share in low GWP refrigerants because of the growing demand for energy-efficient cooling systems, replacement of high-GWP refrigerants, and the expansion of the supermarket, retail, food-service, and commercial refrigeration infrastructure. Low GWP refrigerants are first and foremost used in commercial refrigeration in applications such as display cases, cold rooms, centralized refrigeration, food storage, and temperature- controlled applications. The requirement of higher energy efficiency, greenhouse gas reduction, compliance with environmental regulations, and better temperature control is going to drive the demand for low-GWP refrigerant solutions in commercial refrigeration.
"Asia Pacific is projected to be the largest region in the low-GWP refrigerants market during the forecast period."
The Low GWP refrigerants market in Asia Pacific is expected to experience a considerable rise in revenue by 2031. This is largely due to rapid urbanization and industrialization, conventional expansion in the manufacturing base, and increasing investments in cold-chain, air conditioning, refrigerating, and other industrial cooling systems. The fast-burgeoning commercial refrigeration, industrial refrigeration, food processing, and manufacturing sectors are also anticipated to drive the demand for low GWP refrigerants in Asia Pacific. The ascending trends in commercial refrigeration, industrial refrigeration, stationary air conditioning, mobile air conditioning, cold chain applications and heat pumps, demand for high-performance and reliable cooling, safety and regulatory compliance, and the rising investments in professional cold-chain infrastructure, food and beverage manufacturing, and air-conditioning systems are expected to marginally aid in the consistent growth of the Asia Pacific low-GWP refrigerants market during the forecast period. The developments, the phase-down of high-GWP refrigerants, and increasing penetration of natural and other new low-GWP blends support the consistent long-term growth.
By Company Type: Tier 1: 40%, Tier 2: 30%, and Tier 3: 30%
By Designation: Directors: 30%, Managers: 20%, and Others: 50%
By Region: North America: 20%, Europe: 10%, Asia Pacific: 40%, South America: 10%, and Middle East & Africa 20%
Notes: Others include sales, marketing, and product managers.
Tier 1: >USD 1 Billion; Tier 2: USD 500 million-1 Billion; and Tier 3: <USD 500 million
Companies Covered: Solstice Advanced Materials (US), The Chemours Company (US), Daikin Industries, Ltd. (Japan), Arkema (France), Orbia (Mexico), Linde PLC (UK), AGC Inc. (Japan), Dongyue Group (China), Sinochem Holdings (China), and Zhejiang Juhua Co., Ltd. (China) are covered in the report.
The study includes an in-depth competitive analysis of these key players in the Low GWP refrigerants market, with their company profiles, recent developments, and key market strategies.
Research Coverage
This research report categorizes the Low GWP refrigerants market based on Type (Inorganics, Fluorocarbons, Hydrocarbons) and Application (Industrial Refrigeration, Commercial Refrigeration, Domestic Refrigeration, Stationary Air Conditioning, Mobile Air Conditioning, Other Applications). The report's scope covers detailed information regarding drivers, restraints, challenges, and opportunities influencing the growth of the Low GWP refrigerants market. A detailed analysis of the key industry players has been conducted to provide insights into their business overview, products offered, and key strategies, such as mergers, acquisitions, product launches, partnerships, and expansions, associated with the low GWP refrigerants market. This report covers a competitive analysis of upcoming startups in the low GWP refrigerants market ecosystem.
Reasons to Buy the Report
The report will offer market leaders/new entrants with information on the closest approximations of the revenue numbers for the overall low GWP refrigerants market and the subsegments. This report will help stakeholders understand the competitive landscape, gain more insights into positioning their businesses better, and plan suitable go-to-market strategies. The report will help stakeholders understand the pulse of the market and provide them with information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following points:
- Analysis of key drivers (Stringent regulations and phase-down of high-GWP refrigerants, Growing demand for energy-efficient refrigeration and air-conditioning systems, and Expansion of cold-chain, food processing, and refrigerated storage infrastructure), restraints (High initial cost of low-GWP refrigerant systems and Compatibility limitations with existing refrigeration equipment), opportunities (Rising adoption of natural refrigerants such as CO2, ammonia, and hydrocarbons, Growing demand for low-GWP refrigerants in emerging markets, and Increasing adoption of heat pumps and next-generation HVAC systems), and challenges (Flammability and toxicity risks associated with certain low-GWP refrigerants and Limited technician expertise and refrigerant recovery and recycling infrastructure).
- Product Development/Innovation: Detailed insights into upcoming technologies, research & development activities, and product & service launches in the Low GWP refrigerants market.
- Market Development: Comprehensive information about profitable markets - the report analyzes the Low GWP refrigerants market across varied regions.
- Market Diversification: Exhaustive information about new products & services, untapped geographies, recent developments, and investments in the low GWP refrigerants market.
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and service offerings of leading players such as Solstice Advanced Materials (US), The Chemours Company (US), Daikin Industries, Ltd. (Japan), Arkema (France), Orbia (Mexico), Linde PLC (UK), AGC Inc. (Japan), Dongyue Group (China), Sinochem Holdings (China), and Zhejiang Juhua Co., Ltd. (China).
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKET SEGMENTATION & REGIONAL SCOPE
- 1.3.2 INCLUSIONS & EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.3.4 UNITS CONSIDERED
- 1.3.4.1 Currency/Value unit
- 1.3.4.2 Volume unit
- 1.4 STAKEHOLDERS
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING LOW GWP REFRIGERANTS MARKET
- 2.4 HIGH GROWTH SEGMENTS
- 2.5 SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR LOW GWP REFRIGERANTS MARKET PLAYERS
- 3.2 LOW GWP REFRIGERANTS MARKET, BY TYPE
- 3.3 LOW GWP REFRIGERANTS MARKET, BY APPLICATION
- 3.4 LOW GWP REFRIGERANTS MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Stringent regulations and phase-down of high GWP refrigerants
- 4.2.1.2 Growing demand for energy-efficient refrigeration and air-conditioning systems
- 4.2.1.3 Expansion of cold-chain, food processing, and refrigerated storage infrastructure
- 4.2.2 RESTRAINTS
- 4.2.2.1 High initial cost of low-GWP refrigerant systems
- 4.2.2.2 Compatibility limitations with existing refrigeration equipment
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Rising adoption of natural refrigerants such as CO2, ammonia, and hydrocarbons
- 4.2.3.2 Growing demand for low-GWP refrigerants in emerging markets
- 4.2.3.3 Increasing adoption of heat pumps and next-generation HVAC systems
- 4.2.4 CHALLENGES
- 4.2.4.1 Flammability and toxicity risks associated with certain low-GWP refrigerants
- 4.2.4.2 Limited technician expertise and refrigerant recovery and recycling infrastructure
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN LOW GWP REFRIGERANTS MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 EMERGING BUSINESS MODELS AND ECOSYSTEM SHIFTS
- 4.5.1 EMERGING BUSINESS MODELS
- 4.5.2 ECOSYSTEM SHIFTS
- 4.6 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- 4.6.1 KEY MOVES AND STRATEGIC FOCUS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT FROM SUBSTITUTES
- 5.1.2 BARGAINING POWER OF SUPPLIERS
- 5.1.3 THREAT FROM NEW ENTRANTS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC OUTLOOK
- 5.2.1 GLOBAL GDP TRENDS
- 5.3 VALUE CHAIN ANALYSIS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 AVERAGE SELLING PRICE TREND, BY REGION
- 5.5.2 AVERAGE SELLING PRICE TREND, BY PRODUCT
- 5.6 TRADE ANALYSIS
- 5.6.1 IMPORT SCENARIO (HS CODE 281410)
- 5.6.2 EXPORT SCENARIO (HS CODE 281410)
- 5.6.3 IMPORT SCENARIO (HS CODE 382768)
- 5.6.4 EXPORT SCENARIO (HS CODE 382768)
- 5.7 KEY CONFERENCES AND EVENTS
- 5.8 TRENDS AND DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.9 INVESTMENT AND FUNDING SCENARIO
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 LOW GWP REFRIGERANTS IN FOOD & BEVERAGE APPLICATIONS
- 5.10.2 LOW GWP REFRIGERANTS IN COLD-CHAIN APPLICATIONS
- 5.11 IMPACT OF 2025 US TARIFF - LOW GWP REFRIGERANTS MARKET
- 5.11.1 INTRODUCTION
- 5.11.2 KEY TARIFF RATES
- 5.11.3 PRICE IMPACT ANALYSIS
- 5.11.4 IMPACT ON REGIONS
- 5.11.4.1 North America
- 5.11.4.2 Europe
- 5.11.4.3 Asia Pacific
- 5.11.5 IMPACT ON END-USE INDUSTRIES
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, AND INNOVATIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 NEXT-GENERATION ULTRA-LOW GWP REFRIGERANTS
- 6.1.2 ADVANCED LOW-GWP REFRIGERANT BLENDS
- 6.1.3 LOW-CHARGE AND HIGH-EFFICIENCY REFRIGERATION SYSTEMS
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 REFRIGERANT RECOVERY, RECYCLING, AND RECLAMATION TECHNOLOGIES
- 6.2.2 ADVANCED LEAK DETECTION AND REFRIGERANT MANAGEMENT SYSTEMS
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 HEAT PUMP AND NEXT-GENERATION HVAC SYSTEMS
- 6.3.2 AI-ASSISTED REFRIGERATION SYSTEM MONITORING AND OPTIMIZATION
- 6.4 TECHNOLOGY/PRODUCT ROADMAP
- 6.4.1 SHORT-TERM (2026-2027) |OPTIMIZATION & PERFORMANCE ENHANCEMENT
- 6.4.2 MID-TERM (2027-2030) | EXPANSION & STANDARDIZATION
- 6.4.3 LONG-TERM (2030-2035+) | ADVANCED FUNCTIONALITY & SUSTAINABLE INNOVATION
- 6.5 PATENT ANALYSIS
- 6.5.1 LEGAL STATUS OF PATENTS
- 6.5.2 JURISDICTION ANALYSIS
- 6.6 FUTURE APPLICATIONS
- 6.6.1 ADVANCE LOW GWP REFRIGERANTS & HIGH-EFFICIENCY COOLING TECHNOLOGIES
- 6.6.2 AUTOMATED REFRIGERATION CONTROL & ADVANCED SYSTEM TECHNOLOGIES
- 6.6.3 SMART REFRIGERATION PERFORMANCE MONITORING SYSTEMS
- 6.6.4 DIGITAL MANUFACTURING & REFRIGERATION SYSTEM INTEGRATION PLATFORMS
- 6.6.5 ADVANCED REFRIGERATION & HIGH-PERFORMANCE COOLING TECHNOLOGIES
- 6.7 IMPACT OF AI/GEN AI ON LOW GWP REFRIGERANTS MARKET
- 6.7.1 TOP USE CASES AND MARKET POTENTIAL
- 6.7.2 BEST PRACTICES IN LOW GWP REFRIGERANTS MARKET
- 6.7.3 CASE STUDIES OF AI IMPLEMENTATION IN LOW GWP REFRIGERANTS MARKET
- 6.7.4 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.7.5 CLIENTS' READINESS TO ADOPT GENERATIVE AI LOW GWP REFRIGERANTS MARKET
7 REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.2 REGULATORY POLICY INITIATIVES
- 7.2.1 SAFETY PROTOCOLS
- 7.2.2 SUSTAINABLE DEVELOPMENT
- 7.2.3 STANDARDIZATION
- 7.2.4 CIRCULAR ECONOMY
- 7.3 SUSTAINABILITY INITIATIVES
- 7.3.1 THERMAL PERFORMANCE, ENVIRONMENTAL, AND SAFETY INITIATIVES
- 7.3.1.1 Low-carbon materials and sustainable product strategies
- 7.3.1.2 Green buildings & eco applications
- 7.3.1 THERMAL PERFORMANCE, ENVIRONMENTAL, AND SAFETY INITIATIVES
- 7.4 SUSTAINABILITY IMPACT & REGULATORY POLICY INITIATIVES
- 7.5 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS AND BUYING CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS IN VARIOUS END-USE INDUSTRIES
- 8.5 MARKET PROFITABILITY
- 8.5.1 REVENUE POTENTIAL
- 8.5.2 COST DYNAMICS
- 8.5.3 MARGIN OPPORTUNITIES IN KEY END-USE INDUSTRIES
9 LOW GWP REFRIGERANTS MARKET, BY TYPE
- 9.1 INTRODUCTION
- 9.2 INORGANICS
- 9.2.1 AMMONIA
- 9.2.1.1 Increasing Adoption of Ammonia-Based Refrigeration Systems to Drive Market
- 9.2.2 CARBON DIOXIDE
- 9.2.2.1 Growing Demand for Natural Refrigerants to Drive Growth
- 9.2.3 OTHER INORGANICS
- 9.2.3.1 Increasing Adoption of Low-GWP Inorganic Refrigerants to Support Market Growth
- 9.2.1 AMMONIA
- 9.3 FLUOROCARBONS
- 9.3.1 HFOS (PURE)
- 9.3.1.1 Increasing Adoption of Low-GWP HFO Refrigerants to Drive Market
- 9.3.2 HCFOS
- 9.3.2.1 Growing Demand for Low-GWP Refrigerants in Chillers to Support Market Growth
- 9.3.3 HFCS (PURE)
- 9.3.3.1 Increasing Demand for Lower-GWP HFCs to Drive Market
- 9.3.4 HFO/HFC BLENDS
- 9.3.4.1 Increasing Adoption of Low-GWP Refrigerant Blends to Drive the Growth
- 9.3.5 OTHER FLUORINATED BLENDS
- 9.3.5.1 Growing Adoption of Alternative Low-GWP Blends to Support Market Growth
- 9.3.1 HFOS (PURE)
- 9.4 HYDROCARBONS
- 9.4.1 PROPANE
- 9.4.1.1 Increasing Adoption of R-290-Based Systems to Drive Market
- 9.4.2 BUTANE
- 9.4.2.1 Growing Use of R-600 in Refrigeration Applications to Support Market Growth
- 9.4.3 ISOBUTANE
- 9.4.3.1 Increasing Adoption of R-600a in Domestic Refrigeration to Drive the Growth
- 9.4.4 OTHER HYDROCARBONS
- 9.4.4.1 Growing Adoption of R-1270 in Specialized Cooling Applications to Support Market Growth
- 9.4.1 PROPANE
10 LOW GWP REFRIGERANTS MARKET, BY APPLICATION
- 10.1 INTRODUCTION
- 10.2 INDUSTRIAL REFRIGERATION
- 10.3 COMMERCIAL REFRIGERATION
- 10.4 DOMESTIC REFRIGERATION
- 10.5 STATIONARY AIR CONDITIONING
- 10.6 MOBILE AIR CONDITIONING
- 10.7 OTHER APPLICATIONS
11 LOW GWP REFRIGERANTS MARKET, BY REGION
- 11.1 INTRODUCTION
- 11.2 NORTH AMERICA
- 11.2.1 US
- 11.2.1.1 Strong cooling demand and stringent HFC regulations to drive market growth
- 11.2.2 CANADA
- 11.2.2.1 Increasing infrastructure investment and HFC phase-down to drive market growth
- 11.2.3 MEXICO
- 11.2.3.1 Increasing HFC phase-down and expansion of commercial refrigeration to drive market growth
- 11.2.1 US
- 11.3 EUROPE
- 11.3.1 GERMANY
- 11.3.1.1 Stringent F-gas regulations and increasing adoption of low GWP refrigerants to drive market
- 11.3.2 FRANCE
- 11.3.2.1 Increasing electrification and adoption of energy-efficient cooling systems to drive market
- 11.3.3 UK
- 11.3.3.1 Commercial refrigeration and cold-chain expansion to drive market
- 11.3.4 REST OF EUROPE
- 11.3.1 GERMANY
- 11.4 ASIA PACIFIC
- 11.4.1 CHINA
- 11.4.1.1 Growing demand for sustainable refrigeration and air conditioning to drive market
- 11.4.2 INDIA
- 11.4.2.1 Expansion of cold-chain and commercial refrigeration infrastructure to drive market growth
- 11.4.3 JAPAN
- 11.4.3.1 Growing adoption of natural refrigerants in cold-chain applications to drive market growth
- 11.4.4 SOUTH KOREA
- 11.4.4.1 HFC management and transition toward lower-GWP refrigerants to drive market growth
- 11.4.5 REST OF ASIA PACIFIC
- 11.4.1 CHINA
- 11.5 MIDDLE EAST & AFRICA
- 11.5.1 GCC COUNTRIES
- 11.5.1.1 Saudi Arabia
- 11.5.1.1.1 Food manufacturing, tourism, and refrigeration infrastructure expansion to drive market growth
- 11.5.1.2 Rest of GCC
- 11.5.1.1 Saudi Arabia
- 11.5.2 SOUTH AFRICA
- 11.5.2.1 Cold-chain expansion and food-processing growth to drive market
- 11.5.3 REST OF MIDDLE EAST & AFRICA
- 11.5.1 GCC COUNTRIES
- 11.6 SOUTH AMERICA
- 11.6.1 BRAZIL
- 11.6.1.1 HFC reduction and energy-efficient refrigeration transition to drive market growth
- 11.6.2 ARGENTINA
- 11.6.2.1 Food processing and oil & gas expansion to drive market growth
- 11.6.3 REST OF SOUTH AMERICA
- 11.6.1 BRAZIL
12 COMPETITIVE LANDSCAPE
- 12.1 INTRODUCTION
- 12.2 KEY PLAYER STRATEGIES/RIGHT TO WIN
- 12.3 REVENUE ANALYSIS, 2021-2025
- 12.4 MARKET SHARE ANALYSIS, 2025
- 12.5 PRODUCT COMPARISON
- 12.6 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 12.6.1 STARS
- 12.6.2 EMERGING LEADERS
- 12.6.3 PERVASIVE PLAYERS
- 12.6.4 PARTICIPANTS
- 12.6.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 12.6.5.1 Company footprint
- 12.6.5.2 Region footprint
- 12.6.5.3 Type footprint
- 12.6.5.4 Application footprint
- 12.7 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 12.7.1 PROGRESSIVE COMPANIES
- 12.7.2 RESPONSIVE COMPANIES
- 12.7.3 DYNAMIC COMPANIES
- 12.7.4 STARTING BLOCKS
- 12.7.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 12.7.5.1 Detailed list of key startups/SMEs
- 12.7.5.2 Competitive benchmarking of key startups/SMEs
- 12.8 COMPANY VALUATION & FINANCIAL METRICS
- 12.8.1 FINANCIAL METRICS
- 12.8.2 COMPANY VALUATION
- 12.8.3 ENTERPRISE VALUATION
- 12.9 COMPETITIVE SCENARIO
- 12.9.1 PRODUCT LAUNCHES
- 12.9.2 DEALS
- 12.9.3 EXPANSIONS
13 COMPANY PROFILES
- 13.1 KEY PLAYERS
- 13.1.1 SOLSTICE ADVANCED MATERIALS, INC.
- 13.1.1.1 Business overview
- 13.1.1.2 Products/Solutions/Services offered
- 13.1.1.3 Recent developments
- 13.1.1.3.1 Product launches
- 13.1.1.4 Deals
- 13.1.1.5 MnM view
- 13.1.1.5.1 Right to win
- 13.1.1.5.2 Strategic choices
- 13.1.1.5.3 Weaknesses & competitive threats
- 13.1.2 THE CHEMOURS COMPANY
- 13.1.2.1 Business overview
- 13.1.2.2 Products/Solutions/Services offered
- 13.1.2.3 Recent developments
- 13.1.2.3.1 Product launches
- 13.1.2.4 MnM view
- 13.1.2.4.1 Right to win
- 13.1.2.4.2 Strategic choices
- 13.1.2.4.3 Weaknesses & competitive threats
- 13.1.3 DAIKIN INDUSTRIES, LTD.
- 13.1.3.1 Business overview
- 13.1.3.2 Products/Solutions/Services offered
- 13.1.3.3 Recent developments
- 13.1.3.3.1 Product launches
- 13.1.3.3.2 Deals
- 13.1.3.3.3 Expansions
- 13.1.3.4 MnM view
- 13.1.3.4.1 Right to win
- 13.1.3.4.2 Strategic choices
- 13.1.3.4.3 Weaknesses & competitive threats
- 13.1.4 ARKEMA
- 13.1.4.1 Business overview
- 13.1.4.2 Products/Solutions/Services offered
- 13.1.4.3 Recent developments
- 13.1.4.3.1 Deals
- 13.1.4.3.2 Expansions
- 13.1.4.4 MnM view
- 13.1.4.4.1 Right to win
- 13.1.4.4.2 Strategic choices
- 13.1.4.4.3 Weaknesses & competitive threats
- 13.1.5 ORBIA
- 13.1.5.1 Business overview
- 13.1.5.2 Products/Solutions/Services offered
- 13.1.5.3 Recent developments
- 13.1.5.3.1 Product launches
- 13.1.5.3.2 Deals
- 13.1.5.4 MnM view
- 13.1.5.4.1 Right to win
- 13.1.5.4.2 Strategic choices
- 13.1.5.4.3 Weaknesses & competitive threats
- 13.1.6 LINDE PLC
- 13.1.6.1 Business overview
- 13.1.6.2 Products/Solutions/Services offered
- 13.1.6.3 MnM view
- 13.1.7 AGC INC.
- 13.1.7.1 Business overview
- 13.1.7.2 Products/Solutions/Services offered
- 13.1.7.3 Recent developments
- 13.1.7.3.1 Product launches
- 13.1.7.4 MnM view
- 13.1.8 DONGYUE GROUP
- 13.1.8.1 Business overview
- 13.1.8.2 Products/Solutions/Services offered
- 13.1.8.3 Recent developments
- 13.1.8.3.1 Expansions
- 13.1.8.4 MnM view
- 13.1.9 SINOCHEM HOLDINGS CORPORATION LTD.
- 13.1.9.1 Business overview
- 13.1.9.2 Products/Solutions/Services offered
- 13.1.9.3 Recent developments
- 13.1.9.3.1 Deals
- 13.1.9.4 MnM view
- 13.1.10 ZHEJIANG JUHUA CO., LTD.
- 13.1.10.1 Business overview
- 13.1.10.2 Products/Solutions/Services offered
- 13.1.10.3 Recent developments
- 13.1.10.3.1 Product launch
- 13.1.10.3.2 Deals
- 13.1.10.4 MnM view
- 13.1.1 SOLSTICE ADVANCED MATERIALS, INC.
- 13.2 OTHER PLAYERS
- 13.2.1 A-GAS INTERNATIONAL LIMITED
- 13.2.2 AIR LIQUIDE
- 13.2.3 ENGAS PTY LTD
- 13.2.4 GTS SPA
- 13.2.5 GUJARAT FLUOROCHEMICALS LIMITED
- 13.2.6 HARP INTERNATIONAL LTD.
- 13.2.7 HYCHILL AUSTRALIA PTY LTD.
- 13.2.8 JIANGSU MEILAN CHEMICAL CO. LTD.
- 13.2.9 NAVIN FLUORINE INTERNATIONAL LIMITED.
- 13.2.10 ZHEJIANG SANMEI CHEMICAL INDUSTRY CO., LTD.
- 13.2.11 PUYANG ZHONGWEI FINE CHEMICAL CO., LTD.
- 13.2.12 SHANDONG YUE'AN NEW MATERIAL CO., LTD.
- 13.2.13 SRF LIMITED
- 13.2.14 TAZZETTI S.P.A.
- 13.2.15 ZHEJIANG YONGHE REFRIGERANT CO., LTD.
14 RESEARCH METHODOLOGY
- 14.1 RESEARCH DATA
- 14.1.1 SECONDARY DATA
- 14.1.1.1 Key data from secondary sources
- 14.1.2 PRIMARY DATA
- 14.1.2.1 Key data from primary sources
- 14.1.2.2 Key industry insights
- 14.1.2.3 Breakdown of primary interviews
- 14.1.1 SECONDARY DATA
- 14.2 MARKET SIZE ESTIMATION
- 14.2.1 BOTTOM-UP APPROACH
- 14.2.2 TOP-DOWN APPROACH
- 14.3 DATA TRIANGULATION
- 14.4 STUDY ASSUMPTIONS
- 14.5 RESEARCH LIMITATIONS
15 APPENDIX
- 15.1 DISCUSSION GUIDE
- 15.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 15.3 CUSTOMIZATION OPTIONS
- 15.4 RELATED REPORTS
- 15.5 AUTHOR DETAILS
List of Tables
- TABLE 1 LOW GWP REFRIGERANTS MARKET: INCLUSIONS & EXCLUSIONS
- TABLE 2 LOW GWP REFRIGERANTS MARKET: PORTER'S FIVE FORCES ANALYSIS
- TABLE 3 REAL GDP GROWTH (ANNUAL PERCENT CHANGE) OF KEY COUNTRIES, 2021-2030
- TABLE 4 ROLE OF COMPANIES IN ECOSYSTEM
- TABLE 5 AVERAGE SELLING PRICE TREND, BY REGION, 2023-2025 (USD/KG)
- TABLE 6 AVERAGE SELLING PRICE TREND, BY TYPE, 2023-2025 (USD/KG)
- TABLE 7 IMPORT DATA FOR HS CODE 281410-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 8 EXPORT DATA FOR HS CODE 281410-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 9 IMPORT DATA FOR HS CODE 382768-COMPLIANT PRODUCTS, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 10 EXPORT DATA FOR HS CODE 382768-COMPLIANT PRODUCTS, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 11 KEY CONFERENCES AND EVENTS, 2026-2027
- TABLE 12 US-ADJUSTED RECIPROCAL TARIFF RATES
- TABLE 13 TOP USE CASES AND MARKET POTENTIAL
- TABLE 14 BEST PRACTICES: NOTABLE INDUSTRY PRACTICES BY LEADING COMPANIES
- TABLE 15 LOW GWP REFRIGERANTS MARKET: CASE STUDIES RELATED TO AI IMPLEMENTATION
- TABLE 16 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- TABLE 17 NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 18 EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 19 ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 20 MIDDLE EAST & AFRICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 21 SOUTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 22 GLOBAL STANDARDS IN LOW GWP REFRIGERANTS MARKET
- TABLE 23 CERTIFICATIONS, LABELING, AND ECO-STANDARDS IN LOW GWP REFRIGERANTS MARKET
- TABLE 24 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY END-USE INDUSTRY (%)
- TABLE 25 KEY BUYING CRITERIA, BY END-USE INDUSTRY
- TABLE 26 LOW GWP REFRIGERANTS MARKET: UNMET NEEDS IN KEY END-USE INDUSTRIES
- TABLE 27 LOW GWP REFRIGERANTS MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 28 LOW GWP REFRIGERANTS MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 29 LOW GWP REFRIGERANTS MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 30 LOW GWP REFRIGERANTS MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 31 LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 32 LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 33 LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 34 LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 35 LOW GWP REFRIGERANTS MARKET, BY REGION, 2023-2025 (USD MILLION)
- TABLE 36 LOW GWP REFRIGERANTS MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 37 LOW GWP REFRIGERANTS MARKET, BY REGION, 2023-2025 (KILOTON)
- TABLE 38 LOW GWP REFRIGERANTS MARKET, BY REGION, 2026-2031 (KILOTON)
- TABLE 39 NORTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY COUNTRY, 2023-2025 (USD MILLION)
- TABLE 40 NORTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 41 NORTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY COUNTRY, 2023-2025 (KILOTON)
- TABLE 42 NORTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY COUNTRY, 2026-2031 (KILOTON)
- TABLE 43 NORTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 44 NORTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 45 NORTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 46 NORTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 47 NORTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 48 NORTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 49 NORTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 50 NORTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 51 US: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 52 US: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 53 US: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 54 US: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 55 CANADA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 56 CANADA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 57 CANADA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 58 CANADA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 59 MEXICO: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 60 MEXICO: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 61 MEXICO: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 62 MEXICO: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 63 EUROPE: LOW GWP REFRIGERANTS MARKET, BY COUNTRY, 2023-2025 (USD MILLION)
- TABLE 64 EUROPE: LOW GWP REFRIGERANTS MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 65 EUROPE: LOW GWP REFRIGERANTS MARKET, BY COUNTRY, 2023-2025 (KILOTON)
- TABLE 66 EUROPE: LOW GWP REFRIGERANTS MARKET, BY COUNTRY, 2026-2031 (KILOTON)
- TABLE 67 EUROPE: LOW GWP REFRIGERANTS MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 68 EUROPE: LOW GWP REFRIGERANTS MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 69 EUROPE: LOW GWP REFRIGERANTS MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 70 EUROPE: LOW GWP REFRIGERANTS MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 71 EUROPE: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 72 EUROPE: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 73 EUROPE: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 74 EUROPE: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 75 GERMANY: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 76 GERMANY: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 77 GERMANY: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 78 GERMANY: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 79 FRANCE: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 80 FRANCE: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 81 FRANCE: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 82 FRANCE: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 83 UK: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 84 UK: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 85 UK: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 86 UK: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 87 REST OF EUROPE: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 88 REST OF EUROPE: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 89 REST OF EUROPE: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 90 REST OF EUROPE: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 91 ASIA PACIFIC: LOW GWP REFRIGERANTS MARKET, BY COUNTRY, 2023-2025 (USD MILLION)
- TABLE 92 ASIA PACIFIC: LOW GWP REFRIGERANTS MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 93 ASIA PACIFIC: LOW GWP REFRIGERANTS MARKET, BY COUNTRY, 2023-2025 (KILOTON)
- TABLE 94 ASIA PACIFIC: LOW GWP REFRIGERANTS MARKET, BY COUNTRY, 2026-2031 (KILOTON)
- TABLE 95 ASIA PACIFIC: LOW GWP REFRIGERANTS MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 96 ASIA PACIFIC: LOW GWP REFRIGERANTS MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 97 ASIA PACIFIC: LOW GWP REFRIGERANTS MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 98 ASIA PACIFIC: LOW GWP REFRIGERANTS MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 99 ASIA PACIFIC: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 100 ASIA PACIFIC: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 101 ASIA PACIFIC: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 102 ASIA PACIFIC: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 103 CHINA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 104 CHINA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 105 CHINA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 106 CHINA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 107 INDIA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 108 INDIA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 109 INDIA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 110 INDIA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 111 JAPAN: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 112 JAPAN: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 113 JAPAN: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 114 JAPAN: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 115 SOUTH KOREA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 116 SOUTH KOREA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 117 SOUTH KOREA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 118 SOUTH KOREA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 119 REST OF ASIA PACIFIC: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 120 REST OF ASIA PACIFIC: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 121 REST OF ASIA PACIFIC: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 122 REST OF ASIA PACIFIC: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 123 MIDDLE EAST & AFRICA: LOW GWP REFRIGERANTS MARKET, BY COUNTRY, 2023-2025 (USD MILLION)
- TABLE 124 MIDDLE EAST & AFRICA: LOW GWP REFRIGERANTS MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 125 MIDDLE EAST & AFRICA: LOW GWP REFRIGERANTS MARKET, BY COUNTRY, 2023-2025 (KILOTON)
- TABLE 126 MIDDLE EAST & AFRICA: LOW GWP REFRIGERANTS MARKET, BY COUNTRY, 2026-2031 (KILOTON)
- TABLE 127 MIDDLE EAST & AFRICA: LOW GWP REFRIGERANTS MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 128 MIDDLE EAST & AFRICA: LOW GWP REFRIGERANTS MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 129 MIDDLE EAST & AFRICA: LOW GWP REFRIGERANTS MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 130 MIDDLE EAST & AFRICA: LOW GWP REFRIGERANTS MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 131 MIDDLE EAST & AFRICA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 132 MIDDLE EAST & AFRICA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 133 MIDDLE EAST & AFRICA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 134 MIDDLE EAST & AFRICA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 135 GCC COUNTRIES: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 136 GCC COUNTRIES: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 137 GCC COUNTRIES: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 138 GCC COUNTRIES: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 139 SAUDI ARABIA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 140 SAUDI ARABIA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 141 SAUDI ARABIA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 142 SAUDI ARABIA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 143 REST OF GCC: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 144 REST OF GCC: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 145 REST OF GCC: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 146 REST OF GCC: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 147 SOUTH AFRICA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 148 SOUTH AFRICA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 149 SOUTH AFRICA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 150 SOUTH AFRICA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 151 REST OF MIDDLE EAST & AFRICA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 152 REST OF MIDDLE EAST & AFRICA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 153 REST OF MIDDLE EAST & AFRICA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 154 REST OF MIDDLE EAST & AFRICA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 155 SOUTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY COUNTRY, 2023-2025 (USD MILLION)
- TABLE 156 SOUTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 157 SOUTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY COUNTRY, 2023-2025 (KILOTON)
- TABLE 158 SOUTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY COUNTRY, 2026-2031 (KILOTON)
- TABLE 159 SOUTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY TYPE, 2023-2025 (USD MILLION)
- TABLE 160 SOUTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 161 SOUTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY TYPE, 2023-2025 (KILOTON)
- TABLE 162 SOUTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 163 SOUTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 164 SOUTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 165 SOUTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 166 SOUTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 167 BRAZIL: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 168 BRAZIL: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 169 BRAZIL: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 170 BRAZIL: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 171 ARGENTINA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 172 ARGENTINA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 173 ARGENTINA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 174 ARGENTINA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 175 REST OF SOUTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (USD MILLION)
- TABLE 176 REST OF SOUTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 177 REST OF SOUTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2023-2025 (KILOTON)
- TABLE 178 REST OF SOUTH AMERICA: LOW GWP REFRIGERANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 179 KEY STRATEGIES ADOPTED BY MAJOR PLAYERS IN LOW GWP REFRIGERANTS MARKET
- TABLE 180 LOW GWP REFRIGERANTS MARKET: DEGREE OF COMPETITION, 2025
- TABLE 181 LOW GWP REFRIGERANTS MARKET: REGION FOOTPRINT
- TABLE 182 LOW GWP REFRIGERANTS MARKET: TYPE FOOTPRINT
- TABLE 183 LOW GWP REFRIGERANTS MARKET: APPLICATION FOOTPRINT
- TABLE 184 LOW GWP REFRIGERANTS MARKET: DETAILED LIST OF KEY STARTUPS/SME PLAYERS
- TABLE 185 LOW GWP REFRIGERANTS MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SME PLAYERS, BY TYPE, APPLICATION, AND REGION
- TABLE 186 LOW GWP REFRIGERANTS MARKET: PRODUCT LAUNCHES, J ANUARY 2020- SEPTEMBER 2026
- TABLE 187 LOW GWP REFRIGERANTS MARKET: DEALS, JANUARY 2020- SEPTEMBER 2026
- TABLE 188 LOW GWP REFRIGERANTS MARKET: EXPANSIONS, JANUARY 2023- SEPTEMBER 2026
- TABLE 189 SOLSTICE ADVANCED MATERIALS, INC.: COMPANY OVERVIEW
- TABLE 190 SOLSTICE ADVANCED MATERIALS, INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 191 SOLSTICE ADVANCED MATERIALS, INC.: PRODUCT LAUNCHES, JANUARY 2023-SEPTEMBER 2026
- TABLE 192 SOLSTICE ADVANCED MATERIALS, INC.: DEALS, JANUARY 2023- SEPTEMBER 2026
- TABLE 193 THE CHEMOURS COMPANY: COMPANY OVERVIEW
- TABLE 194 THE CHEMOURS COMPANY: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 195 THE CHEMOURS COMPANY: PRODUCT LAUNCHES, JANUARY 2023-SEPTEMBER 2026
- TABLE 196 DAIKIN INDUSTRIES, LTD.: COMPANY OVERVIEW
- TABLE 197 DAIKIN INDUSTRIES, LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 198 DAIKIN INDUSTRIES, LTD.: PRODUCT LAUNCHES, JANUARY 2023- SEPTEMBER 2026
- TABLE 199 DAIKIN INDUSTRIES, LTD.: DEALS, JANUARY 2023-SEPTEMBER 2026
- TABLE 200 DAIKIN INDUSTRIES, LTD.: EXPANSIONS, JANUARY 2023-SEPTEMBER 2026
- TABLE 201 ARKEMA: COMPANY OVERVIEW
- TABLE 202 ARKEMA: PRODUCTS/SOLUTIONS/SERVICES/TECHNOLOGY OFFERED
- TABLE 203 ARKEMA: DEALS, JANUARY 2023-SEPTEMBER 2026
- TABLE 204 ARKEMA: EXPANSIONS, JANUARY 2023-SEPTEMBER 2026
- TABLE 205 ORBIA: COMPANY OVERVIEW
- TABLE 206 ORBIA: PRODUCTS/SOLUTIONS/SERVICES/TECHNOLOGY OFFERED
- TABLE 207 ORBIA: PRODUCT LAUNCHES, JANUARY 2023-SEPTEMBER 2026
- TABLE 208 ORBIA: DEALS, JANUARY 2020-SEPTEMBER 2026
- TABLE 209 LINDE PLC: COMPANY OVERVIEW
- TABLE 210 LINDE PLC: PRODUCT/SOLUTIONS/SERVICES OFFERED
- TABLE 211 AGC INC.: COMPANY OVERVIEW
- TABLE 212 AGC INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 213 AGC INC.: PRODUCT LAUNCHES, JANUARY 2023-SEPTEMBER 2026
- TABLE 214 DONGYUE GROUP: COMPANY OVERVIEW
- TABLE 215 DONGYUE GROUP: PRODUCT/SOLUTIONS/SERVICES OFFERED
- TABLE 216 DONGYUE GROUP: EXPANSIONS, JANUARY 2023-SEPTEMBER 2026
- TABLE 217 SINOCHEM HOLDINGS CORPORATION LTD.: COMPANY OVERVIEW
- TABLE 218 SINOCHEM HOLDINGS CORPORATION LTD.: PRODUCT/SERVICES/ SOLUTIONS OFFERED
- TABLE 219 SINOCHEM HOLDINGS CORPORATION LTD.: DEALS, JANUARY 2023- SEPTEMBER 2026
- TABLE 220 ZHEJIANG JUHUA CO., LTD.: COMPANY OVERVIEW
- TABLE 221 ZHEJIANG JUHUA CO., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 222 ZHEJIANG JUHUA CO., LTD.: PRODUCT LAUNCHES, JANUARY 2023- SEPTEMBER 2026
- TABLE 223 ZHEJIANG JUHUA CO., LTD.: DEALS, JANUARY 2023-SEPTEMBER 2026
- TABLE 224 A-GAS INTERNATIONAL LIMITED: COMPANY OVERVIEW
- TABLE 225 AIR LIQUIDE: COMPANY OVERVIEW
- TABLE 226 ENGAS PTY LTD: COMPANY OVERVIEW
- TABLE 227 GTS SPA: COMPANY OVERVIEW
- TABLE 228 GUJARAT FLUOROCHEMICALS LIMITED: COMPANY OVERVIEW
- TABLE 229 HARP INTERNATIONAL LTD.: COMPANY OVERVIEW
- TABLE 230 HYCHILL AUSTRALIA PTY LTD.: COMPANY OVERVIEW
- TABLE 231 JIANGSU MEILAN CHEMICAL CO. LTD.: COMPANY OVERVIEW
- TABLE 232 NAVIN FLUORINE INTERNATIONAL LIMITED.: COMPANY OVERVIEW
- TABLE 233 ZHEJIANG SANMEI CHEMICAL INDUSTRY CO., LTD. : COMPANY OVERVIEW
- TABLE 234 PUYANG ZHONGWEI FINE CHEMICAL CO., LTD.: COMPANY OVERVIEW
- TABLE 235 SHANDONG YUE'AN NEW MATERIAL CO., LTD.: COMPANY OVERVIEW
- TABLE 236 SRF LIMITED: COMPANY OVERVIEW
- TABLE 237 TAZZETTI S.P.A.: COMPANY OVERVIEW
- TABLE 238 ZHEJIANG YONGHE REFRIGERANT CO., LTD.: COMPANY OVERVIEW
List of Figures
- FIGURE 1 LOW GWP REFRIGERANTS MARKET SEGMENTATION & REGIONAL SCOPE
- FIGURE 2 LOW GWP REFRIGERANTS MARKET: YEARS CONSIDERED
- FIGURE 3 KEY INSIGHTS AND MARKET HIGHLIGHTS
- FIGURE 4 LOW GWP REFRIGERANTS MARKET, 2023-2031 (USD MILLION)
- FIGURE 5 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN LOW GWP REFRIGERANTS MARKET, 2020-2025
- FIGURE 6 DISRUPTIVE TRENDS IMPACTING GROWTH OF LOW GWP REFRIGERANTS MARKET
- FIGURE 7 HIGH-GROWTH SEGMENTS IN LOW GWP REFRIGERANTS MARKET, 2026-2031
- FIGURE 8 ASIA PACIFIC TO REGISTER HIGHEST GROWTH RATE DURING FORECAST PERIOD
- FIGURE 9 ASIA PACIFIC TO OFFER LUCRATIVE OPPORTUNITIES IN LOW GWP REFRIGERANTS MARKET DURING FORECAST PERIOD
- FIGURE 10 HYDROCARBONS TO RECORD HIGHEST GROWTH DURING FORECAST PERIOD
- FIGURE 11 COMMERCIAL REFRIGERATION TO CAPTURE DOMINANT MARKET SHARE DURING FORECAST PERIOD
- FIGURE 12 INDIA TO BE MOST LUCRATIVE MARKET DURING FORECAST PERIOD
- FIGURE 13 LOW GWP REFRIGERANTS MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 14 PORTER'S FIVE FORCES ANALYSIS
- FIGURE 15 LOW GWP REFRIGERANTS MARKET: VALUE CHAIN ANALYSIS
- FIGURE 16 LOW GWP REFRIGERANTS MARKET: ECOSYSTEM ANALYSIS
- FIGURE 17 IMPORT DATA FOR HS CODE 281410-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD MILLION)
- FIGURE 18 EXPORT DATA FOR HS CODE 281410-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD MILLION)
- FIGURE 19 IMPORT DATA FOR HS CODE 382768-COMPLIANT PRODUCTS, BY COUNTRY, 2022-2025 (USD MILLION)
- FIGURE 20 EXPORT DATA FOR HS CODE 382768-COMPLIANT PRODUCTS, BY COUNTRY, 2022-2025 (USD MILLION)
- FIGURE 21 TRENDS AND DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- FIGURE 22 INVESTMENT AND FUNDING SCENARIO, 2021-2025 (USD MILLION)
- FIGURE 23 PATENTS APPLIED AND GRANTED, 2015-2025
- FIGURE 24 PATENT ANALYSIS, BY LEGAL STATUS
- FIGURE 25 TOP JURISDICTION, BY DOCUMENT
- FIGURE 26 LOW GWP REFRIGERANTS MARKET: DECISION-MAKING FACTORS
- FIGURE 27 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY END-USE INDUSTRY
- FIGURE 28 KEY BUYING CRITERIA, BY END-USE INDUSTRY
- FIGURE 29 ADOPTION BARRIERS & INTERNAL CHALLENGES
- FIGURE 30 FLUOROCARBONS TO ACCOUNT FOR LARGEST SHARE DURING FORECAST PERIOD
- FIGURE 31 COMMERCIAL REFRIGERATION TO DOMINATE MARKET DURING FORECAST PERIOD
- FIGURE 32 INDIA TO BE FASTEST-GROWING MARKET DURING FORECAST PERIOD
- FIGURE 33 NORTH AMERICA: LOW GWP REFRIGERANTS MARKET SNAPSHOT
- FIGURE 34 EUROPE: LOW GWP REFRIGERANTS MARKET SNAPSHOT
- FIGURE 35 ASIA PACIFIC: LOW GWP REFRIGERANTS MARKET SNAPSHOT
- FIGURE 36 REVENUE ANALYSIS OF KEY PLAYERS IN LOW GWP REFRIGERANTS MARKET, 2021-2025 (USD BILLION)
- FIGURE 37 LOW GWP REFRIGERANTS MARKET SHARE ANALYSIS, 2025
- FIGURE 38 LOW GWP REFRIGERANTS MARKET: PRODUCT COMPARATIVE ANALYSIS
- FIGURE 39 LOW GWP REFRIGERANTS MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- FIGURE 40 LOW GWP REFRIGERANTS MARKET: COMPANY FOOTPRINT
- FIGURE 41 LOW GWP REFRIGERANTS MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
- FIGURE 42 EV/EBITDA OF KEY MANUFACTURERS IN LOW GWP REFRIGERANTS MARKET
- FIGURE 43 YEAR-TO-DATE (YTD) PRICE TOTAL RETURN AND 5-YEAR STOCK BETA OF KEY MANUFACTURERS IN LOW GWP REFRIGERANTS MARKET
- FIGURE 44 ENTERPRISE VALUATION OF KEY PLAYERS IN LOW GWP REFRIGERANTS MARKET
- FIGURE 45 SOLSTICE ADVANCED MATERIALS, INC.: COMPANY SNAPSHOT
- FIGURE 46 THE CHEMOURS COMPANY: COMPANY SNAPSHOT
- FIGURE 47 DAIKIN INDUSTRIES, LTD.: COMPANY SNAPSHOT
- FIGURE 48 ARKEMA: COMPANY SNAPSHOT
- FIGURE 49 ORBIA: COMPANY SNAPSHOT
- FIGURE 50 LINDE PLC: COMPANY SNAPSHOT
- FIGURE 51 AGC INC.: COMPANY SNAPSHOT
- FIGURE 52 DONGYUE GROUP: COMPANY SNAPSHOT
- FIGURE 53 ZHEJIANG JUHUA CO., LTD.: COMPANY SNAPSHOT
- FIGURE 54 LOW GWP REFRIGERANTS MARKET: RESEARCH DESIGN
- FIGURE 55 KEY DATA FROM SECONDARY SOURCES IN LOW GWP REFRIGERANTS MARKET
- FIGURE 56 KEY DATA FROM PRIMARY SOURCES IN LOW GWP REFRIGERANTS MARKET
- FIGURE 57 KEY INSIGHTS FROM PRIMARY EXPERTS IN LOW GWP REFRIGERANTS MARKET
- FIGURE 58 BREAKDOWN OF PRIMARY INTERVIEWS, BY COMPANY TYPE, DESIGNATION, AND REGION
- FIGURE 59 LOW GWP REFRIGERANTS MARKET: BOTTOM-UP APPROACH
- FIGURE 60 LOW GWP REFRIGERANTS MARKET: TOP-DOWN APPROACH
- FIGURE 61 LOW GWP REFRIGERANTS MARKET: DATA TRIANGULATION
- FIGURE 62 LOW GWP REFRIGERANTS MARKET: STUDY ASSUMPTIONS
- FIGURE 63 LOW GWP REFRIGERANTS MARKET: RESEARCH LIMITATIONS

 全球低全球暖化潛勢冷媒市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 2026-2030年全球低全球暖化潛勢冷媒市場
 低全球暖化潛勢冷媒:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 低全球暖化潛勢冷媒市場規模、佔有率、趨勢和預測:按類型、應用和地區分類,2026-2034年
 HVAC冷媒回收系統市場規模、佔有率和趨勢分析報告:按類型、技術、最終用途、地區和細分市場分類(2026-2033年)
 低全球暖化潛勢冷媒市場:按產品類型、應用、最終用戶和分銷管道分類 - 2026-2032年全球預測低全球暖化潛勢(GWP)冷媒市場:按冷媒類型、應用、最終用途和分銷管道分類 - 全球預測(2026-2032年)