

 |
市場調查報告書
商品編碼
2130446
全球獸醫監測設備市場(至2031年):按類型(麻醉機、二氧化碳監測系統、心電圖和連續型心電圖監測、遙測、生命徵象監測儀)、技術(無線患者監護儀、有線監護系統)和最終用戶分類Veterinary Monitoring Equipment Market by Type (Anesthesia Machine, Capnography System, ECG & Holter Monitoring, Telemetry, Vital Signs Monitor), Technology (Wireless Patient Monitor, Wired Monitoring System), End User - Global Forecast to 2031 |
||||||


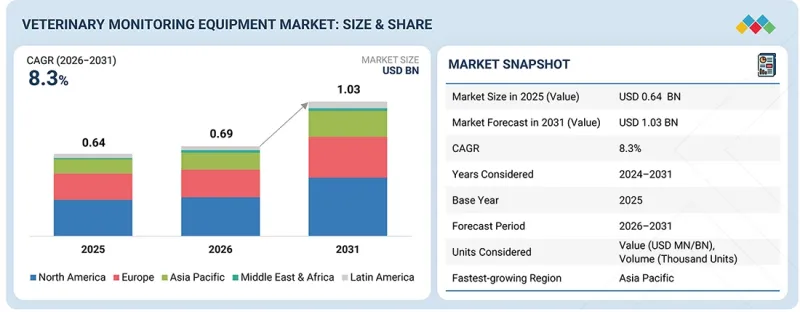
全球獸醫監測設備市場規模預計將從 2026 年的 6.9 億美元成長到 2031 年的 10.3 億美元,預計在預測期內將以 8.30% 的複合年成長率成長。
| 調查範圍 | |
|---|---|
| 調查期 | 2026-2031 |
| 基準年 | 2025 |
| 預測期 | 2026-2031 |
| 單元 | 金額(美元) |
| 部分 | 類型、目標區域、目標動物、技術、最終用戶、地區 |
| 目標區域 | 北美、歐洲、亞太地區、拉丁美洲、中東和非洲 |
市場成長的促進因素包括寵物數量的增加、寵物「擬人化」趨勢、老年犬貓慢性病和老齡化相關疾病(如心臟病和腎病)發病率的上升,以及需要持續生命徵象監測的外科手術數量的增加。然而,實施先進的多參數系統的高昂成本仍然是一個障礙,阻礙了小規模獨立獸醫診所採用這些系統。
“按技術細分來看,穿戴式監測細分市場預計在預測期內將呈現最高的複合年成長率。”
穿戴式非接觸感測器無需限制動物活動即可追蹤心率心率、呼吸頻率和體溫,從而減輕不願被觸碰的動物的壓力,並可在康復籠、收容所和移動診所中進行監測。此外,感測器的微型化和電池續航時間的延長,使得穿戴式裝置的應用範圍從手術室擴展到日常病例管理場景。
“按最終用戶細分市場來看,預計在預測期內,普通獸醫護理細分市場將佔據最大佔有率。”
綜合獸醫診所提供多種診療服務,包括常規健康檢查、牙科治療和小型外科手術,所有這些診療都需要在鎮靜或麻醉期間進行至少基本的生命徵象監測。綜合獸醫診所遍佈全球,數量持續成長,因此其設備安裝數量也高於專科診所和急診機構。
在預測期內,北美預計將佔據最大佔有率,而亞太地區預計將錄得最高的複合年成長率。
北美擁有龐大的寵物數量、完善的專科診所和轉診醫院網路,以及對獸用醫療設備的法規環境(無需在將監測設備引入動物醫院之前獲得正式的上市前批准),預計到2026年仍將佔據市場的大部分佔有率。同時,受寵物數量成長和醫院基礎設施擴建的推動,亞太地區預計將在2026年至2031年間以高於其他任何地區的複合年成長率成長,其中中國、印度和日本將引領這一成長。
本報告考察了全球獸醫監測設備市場,提供了市場概述、影響市場成長的各種因素分析、技術和專利趨勢、法律制度、案例研究、歷史和預測的市場規模、按細分市場/地區/主要國家/地區進行的詳細分析、競爭格局以及主要公司的概況。
目錄
第1章:引言
第2章執行摘要
第3章重要考察
第4章 市場概覽
- 市場動態
- 促進因素
- 抑制因子
- 機會
- 任務
- 未滿足的需求和閒置頻段
- 與相關市場和不同產業相關的跨領域機遇
- 一級/二級/三級公司的策略性舉措
第5章 產業趨勢
- 波特五力分析
- 總體經濟指標
- GDP趨勢與預測
- 全球醫療產業趨勢
- 全球醫療設備業趨勢
- 供應鏈分析
- 價值鏈分析
- 生態系分析
- 價格分析
- 貿易分析
- 救贖方案
- 2026-2027 年主要會議和活動
- 影響客戶業務的趨勢/顛覆性因素
- 投資和資金籌措場景
- 案例研究分析
- 2025年美國關稅對獸醫監測設備市場的影響
第6章:技術進步、人工智慧的影響、專利、創新與未來應用
- 技術分析
- 主要新興技術
- 互補技術
- 鄰近技術
- 技術/產品藍圖
- 短期(2025-2027)
- 中期計劃(2028-2030年)
- 長期(2030 年後)
- 專利分析
- 未來應用
- 人工智慧/生成式人工智慧對獸醫監測設備的影響
第7章:監理情勢與永續性舉措
- 監理情勢
- 對永續性的承諾
第8章:顧客趨勢與購買行為
- 決策流程
- 採購過程中的關鍵相關人員及其評估標準
- 實施障礙和內部挑戰
- 各個終端用戶產業尚未滿足的需求
- 市場盈利
第9章 獸醫監測設備市場:依類型分類
- 多參數獸用監測儀
- 定量分析
- 可攜式參數監視器
- 桌面多參數監視器
- 模組化多參數監視器
- 其他
- 二氧化碳圖與血氧飽和度監測系統
- 定量分析
- 二氧化碳監測系統
- 脈搏血氧計系統
- 麻醉儀器和耗材
- 定量分析
- 麻醉儀器
- 麻醉耗材
- 心電圖/動態心電圖監測系統
- 定量分析
- 靜態心電圖系統
- 連續心電圖系統
- 動態心電圖系統
- 遙測和中央監控系統
- 定量分析
- 中央監控系統
- 無線遙測系統
- 遠端患者監護系統
- 其他獸醫監測設備
- 定量分析
第10章 獸醫監測設備市場:依地區分類
- 心臟病
- 心電圖監控
- 血壓監測
- 心律監測
- 連續型心電圖監測
- 神經
- 腦電圖監測
- 神經肌肉監測
- 顱內壓監測
- 呼吸系統疾病
- 體重和體溫監測
- 體重監測
- 體溫監測
- 持續體溫監測
- 穿戴式體重和體溫監測
- 多參數監測
- 手術監測
- 重症監護監測
- 應急監測
- 恢復監測
- 其他
第11章 獸醫監測設備市場:依動物類型分類
- 伴侶動物
- 狗
- 貓
- 馬
- 其他
- 家畜
- 牛
- 豬
- 家禽
- 其他
第12章 獸醫監測設備市場:依技術分類
- 有線監控系統
- 無線監控系統
- 遠端患者監護
- 穿戴式監測技術
- 照護現場監測
第13章 獸醫監測設備市場:依最終使用者分類
- 一般獸醫治療
- 急診和重症監護
- 專業醫療中心
- 其他
第14章 獸醫監測設備市場:依地區分類
- 北美洲
- 宏觀經濟展望
- 定量分析
- 美國
- 加拿大
- 歐洲
- 宏觀經濟展望
- 定量分析
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 挪威
- 丹麥
- 其他
- 亞太地區
- 宏觀經濟展望
- 定量分析
- 中國
- 日本
- 印度
- 澳洲
- 韓國
- 其他
- 拉丁美洲
- 宏觀經濟展望
- 定量分析
- 巴西
- 墨西哥
- 其他
- 中東和非洲
- 宏觀經濟展望
- 定量分析
- 海灣合作理事會國家
- 其他
第15章 競爭格局
- 概述
- 主要參與企業的策略/優勢
- 收入分析
- 市佔率分析
- 品牌/產品對比
- 企業估值矩陣:主要公司
- 公司估值矩陣:新創企業/中小企業
- 企業估值和財務指標
- 競爭格局
第16章:公司簡介
- 大公司
- MIDMARK CORPORATION
- SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD.
- COVETRUS, INC.
- SUNTECH MEDICAL, INC.
- LEADING EDGE VETERINARY EQUIPMENT
- EICKEMEYER VETERINARY EQUIPMENT LTD.
- NONIN MEDICAL, INC.
- DIGICARE BIOMEDICAL
- BIONET CO., LTD.
- EDAN INSTRUMENTS, INC.
- SHENZHEN COMEN MEDICAL INSTRUMENTS CO., LTD.
- GUANGDONG BIOLIGHT MEDITECH CO., LTD.
- VETLAND MEDICAL SALES & SERVICES, LLC
- BURTONS MEDICAL EQUIPMENT LTD.
- AVANTE ANIMAL HEALTH
- 其他公司
- SINO-HERO
- DISPOMED LTD.
- BMV ANIMAL TECHNOLOGY CO., LTD.
- SHENZHEN MED-LINK ELECTRONICS TECH CO., LTD.
- VETSPECS, INC.
- CONTEC MEDICAL SYSTEMS CO., LTD.
- INFINIUM MEDICAL, INC.
- DEXTRONIX, INC.
- MASIMO CORPORATION
- MEDTRONIC
- ICU MEDICAL, INC.
第17章調查方法
第18章附錄
The global veterinary monitoring equipment market is projected to reach USD 1.03 billion by 2031 from USD 0.69 billion in 2026, growing at a CAGR of 8.30% during the forecast period.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD billion) |
| Segments | Type, Target Area, Animal type, Technology, End User, and Region |
| Regions covered | North America, Europe, Asia Pacific, Latin America, and Middle East & Africa |
Growth is driven by rising pet ownership and pet humanization, a rising incidence of chronic and age-related conditions such as cardiac and renal disease in aging dogs and cats, and increasing surgical case volumes that require continuous vital sign monitoring. The high capital cost of advanced multiparameter systems remains a barrier, limiting adoption among small and independent veterinary practices.
"Wearable monitoring technology segment is projected to register the highest CAGR in the veterinary monitoring equipment market during the forecast period."
By technology, the wearable monitoring segment is set to grow fastest between 2026 and 2031. Wearable and contactless sensors allow clinics to track heart rate, respiration and temperature without restraining the animal, reducing stress for patients that resist handling and extending monitoring into recovery cages, shelters and mobile practices. Smaller sensors and longer battery life are moving wearable formats beyond the surgical suite into everyday case management.
"Veterinary general practice segment is expected to account for the largest share of the veterinary monitoring equipment market during the forecast period."
By end user, veterinary general practice held the largest share of the market in 2025. General practices handle most routine wellness exams, dental work, and minor surgical procedures, and each case requires at least basic vital sign monitoring during sedation or anesthesia. The large and still-growing number of general practice clinics worldwide keeps this segment ahead of specialty and emergency facilities in equipment volume.
North America is expected to account for the largest share of the veterinary monitoring equipment market, while Asia Pacific is projected to register the highest CAGR during the forecast period.
North America held a major share of the market in 2026, supported by a large companion animal population, an established specialty and referral hospital network, and a veterinary device pathway that does not require formal premarket approval before a monitor reaches clinics. Asia Pacific is projected to grow at the highest CAGR from 2026 to 2031, the fastest of any region, led by China, India, and Japan as pet ownership rises and hospital infrastructure expands.
A breakdown of the primary participants referred to for this report is provided below:
- By Company Type: Tier 1-40%, Tier 2-35%, and Tier 3- 25%
- By Designation: Directors-23%, Managers-30%, and Others-47%
- By Region: North America-25%, Europe-35%, the Asia Pacific-20%, Latin America-13%, and the Middle East & Africa- 7%
Midmark Corporation (US); Shenzhen Mindray Bio-Medical Electronics (China); Covetrus (US); SunTech Medical (US); Nonin Medical (US); EDAN Instruments (China); Bionet (South Korea); Guangdong Biolight Meditech (China); Burtons Medical Equipment (UK); Eickemeyer Veterinary Equipment (UK); Masimo (US); ICU Medical (US); and Medtronic (Ireland) are some of the key players in the veterinary monitoring equipment market.
Research Coverage
This report studies the veterinary monitoring equipment market by type, target area, animal type, technology, end user, and region. It also covers the factors affecting market growth, analyzes the opportunities and challenges in the market, and provides details of the competitive landscape for market leaders. Furthermore, the report analyzes micromarkets with respect to their individual growth trends and forecasts the revenue of the market segments with respect to five main regions (and the respective countries in these regions).
Reasons to Buy the Report
The report will enable established firms as well as entrants and smaller firms to gauge the pulse of the market, which, in turn, would help them to garner a larger market share. Firms purchasing the report could use one or more of the strategies mentioned below to strengthen their market presence.
This report provides insights into the following pointers:
- Analysis of Key Drivers: Understand the drivers (pet humanization, chronic disease incidence, rising surgical volumes), restraints (high capital cost limiting adoption among small practices), opportunities (expanding veterinary infrastructure in emerging economies, technological advancements in monitoring equipment), and challenges (veterinary workforce shortage and limited technical expertise) shaping this market
- Market Development: Gain insight into the fastest-growing regions and segments, including Asia Pacific and wearable monitoring technology, to prioritize expansion plans
- Market Diversification: Explore new product types, target areas, and end user segments that present untapped revenue opportunities
- Competitive Assessment: Review the strategies of leading players including Midmark Corporation, Shenzhen Mindray Bio-Medical Electronics, Covetrus, SunTech Medical, and Masimo to benchmark competitive positioning
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 MARKET SCOPE
- 1.3.1 MARKET SEGMENTATION
- 1.4 INCLUSIONS AND EXCLUSIONS
- 1.4.1 YEARS CONSIDERED
- 1.4.2 CURRENCY CONSIDERED
- 1.5 STAKEHOLDERS
- 1.6 LIMITATIONS
- 1.7 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN VETERINARY MONITORING EQUIPMENT MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 VETERINARY MONITORING EQUIPMENT MARKET OVERVIEW
- 3.2 EUROPE: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER AND COUNTRY
- 3.3 VETERINARY MONITORING EQUIPMENT MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Growing pet ownership and pet humanization
- 4.2.1.2 Increasing incidence of chronic diseases and age-related conditions
- 4.2.1.3 Increasing veterinary surgical procedures
- 4.2.2 RESTRAINTS
- 4.2.2.1 High capital cost of advanced monitoring systems
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Expanding veterinary infrastructure and rising animal healthcare expenditure in emerging economies
- 4.2.3.2 Technological advancements in veterinary monitoring equipment
- 4.2.4 CHALLENGES
- 4.2.4.1 Veterinary workforce shortage and limited technical expertise in emerging economies
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN VETERINARY MONITORING EQUIPMENT MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
- 4.5.1 STRATEGIC MOVES IN VETERINARY MONITORING EQUIPMENT MARKET
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC INDICATORS
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST
- 5.2.3 TRENDS IN GLOBAL VETERINARY HEALTHCARE INDUSTRY
- 5.2.4 TRENDS IN GLOBAL MEDICAL DEVICE INDUSTRY
- 5.3 SUPPLY CHAIN ANALYSIS
- 5.4 VALUE CHAIN ANALYSIS
- 5.5 ECOSYSTEM ANALYSIS
- 5.5.1 MANUFACTURERS
- 5.5.2 END USERS
- 5.5.3 REGULATORY BODIES
- 5.6 PRICING ANALYSIS
- 5.7 TRADE ANALYSIS
- 5.7.1 IMPORT DATA (HS CODE 9018)
- 5.7.2 EXPORT DATA FOR (HS CODE 9018)
- 5.8 REIMBURSEMENT SCENARIO
- 5.9 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.10 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.11 INVESTMENT AND FUNDING SCENARIO
- 5.12 CASE STUDY ANALYSIS
- 5.13 IMPACT OF 2025 US TARIFF - VETERINARY MONITORING EQUIPMENT MARKET
- 5.13.1 INTRODUCTION
- 5.13.2 KEY TARIFF RATES
- 5.13.3 PRICE IMPACT ANALYSIS
- 5.13.4 IMPACT ON COUNTRIES/REGIONS
- 5.13.5 IMPACT ON END-USE SEGMENTS
- 5.13.5.1 Veterinary general practice
- 5.13.5.2 ER/urgent care
- 5.13.5.3 Veterinary specialty
- 5.13.5.4 Other end users
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 TECHNOLOGY ANALYSIS
- 6.1.1 KEY EMERGING TECHNOLOGIES
- 6.1.1.1 AI-enabled remote patient monitoring and wearable veterinary devices
- 6.1.1.2 Non-contact remote vital sign monitoring
- 6.1.2 COMPLEMENTARY TECHNOLOGIES
- 6.1.2.1 Connected telemetry and central monitoring platforms
- 6.1.2.2 Advanced capnography and multiparameter anesthesia monitoring
- 6.1.3 ADJACENT TECHNOLOGIES
- 6.1.3.1 Veterinary telemedicine and digital health platforms
- 6.1.1 KEY EMERGING TECHNOLOGIES
- 6.2 TECHNOLOGY/PRODUCT ROADMAP
- 6.2.1 NEAR-TERM (2025-2027)
- 6.2.2 MID-TERM (2028-2030)
- 6.2.3 LONG-TERM (2030+)
- 6.3 PATENT ANALYSIS
- 6.3.1 JURISDICTION AND TOP APPLICANT ANALYSIS
- 6.4 FUTURE APPLICATIONS
- 6.4.1 AI-ASSISTED CLINICAL DECISION SUPPORT
- 6.4.2 REMOTE & CONTINUOUS ANIMAL MONITORING
- 6.4.3 CONNECTED & PERSONALIZED VETERINARY CARE
- 6.5 IMPACT OF AI/GEN AI ON VETERINARY MONITORING EQUIPMENT
- 6.5.1 INTRODUCTION
- 6.5.2 MARKET POTENTIAL OF AI IN VETERINARY MONITORING EQUIPMENT
- 6.5.3 AI USE CASES
- 6.5.4 KEY COMPANIES IMPLEMENTING AI
7 REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
- 7.1 REGULATORY LANDSCAPE
- 7.1.1 REGULATORY FRAMEWORK
- 7.1.1.1 North America
- 7.1.1.2 Europe
- 7.1.1.3 Asia Pacific
- 7.1.1.4 Latin America
- 7.1.1.5 Middle East & Africa
- 7.1.2 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.3 INDUSTRY STANDARDS
- 7.1.1 REGULATORY FRAMEWORK
- 7.2 SUSTAINABILITY INITIATIVES
- 7.2.1 REDUCING MEDICAL WASTE & USE OF LOWER-IMPACT MATERIALS AND PACKAGING
- 7.2.2 WATER, ENERGY, & RESOURCE EFFICIENCY
- 7.2.3 CERTIFICATIONS, LABELING, & ECO-STANDARDS
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.4 UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES
- 8.5 MARKET PROFITABILITY
9 VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE
- 9.1 INTRODUCTION
- 9.2 MULTI-PARAMETER VETERINARY MONITORS
- 9.2.1 VOLUME ANALYSIS OF MULTI-PARAMETER VETERINARY MONITORS, 2024-2031
- 9.2.2 PORTABLE MULTI-PARAMETER MONITORS
- 9.2.2.1 Portability and cross-department deployment to support adoption
- 9.2.3 TABLETOP MULTI-PARAMETER MONITORS
- 9.2.3.1 Large displays and fixed workflow integration to sustain demand
- 9.2.4 MODULAR MULTI-PARAMETER MONITORS
- 9.2.4.1 Expandable parameter capability to increase use in referral and critical-care settings
- 9.2.5 OTHER MULTI-PARAMETER VETERINARY MONITORS
- 9.3 CAPNOGRAPHY & OXIMETRY SYSTEMS
- 9.3.1 VOLUME ANALYSIS OF CAPNOGRAPHY & OXIMETRY SYSTEMS, 2024-2031
- 9.3.2 CAPNOGRAPHY SYSTEMS
- 9.3.2.1 Greater emphasis on ventilation monitoring to accelerate capnography adoption
- 9.3.3 PULSE OXIMETRY SYSTEMS
- 9.3.3.1 Non-invasive oxygenation assessment and portable formats to sustain use
- 9.4 ANESTHESIA MACHINES & CONSUMABLES
- 9.4.1 VOLUME ANALYSIS OF ANESTHESIA MACHINES & CONSUMABLES, 2024-2031
- 9.4.2 ANESTHESIA MACHINES
- 9.4.2.1 Anesthesia machines without integrated ventilators
- 9.4.2.1.1 Lower capital requirements and established general-practice workflows to support demand
- 9.4.2.2 Advanced anesthesia machines with integrated ventilators
- 9.4.2.2.1 Integrated ventilation and connected safety functions to accelerate premium adoption
- 9.4.2.1 Anesthesia machines without integrated ventilators
- 9.4.3 ANESTHESIA CONSUMABLES
- 9.4.3.1 Sodasorb
- 9.4.3.1.1 Recurring replacement and carbon-dioxide absorption requirements to sustain demand
- 9.4.3.2 Vaporizers
- 9.4.3.2.1 Growing need for accurate anesthetic delivery and equipment replacement to maintain market growth
- 9.4.3.3 Scavengers
- 9.4.3.3.1 Increasing focus on workplace safety and operating room upgrades to drive adoption
- 9.4.3.1 Sodasorb
- 9.5 ECG & HOLTER MONITORING SYSTEMS
- 9.5.1 VOLUME ANALYSIS OF ECG & HOLTER MONITORING SYSTEMS, 2024-2031
- 9.5.2 RESTING ECG SYSTEMS
- 9.5.2.1 Increasing demand for rapid cardiac screening and diagnostic assessment to expand adoption
- 9.5.3 CONTINUOUS ECG SYSTEMS
- 9.5.3.1 Growing need for continuous cardiac surveillance in critical care to drive market growth
- 9.5.4 HOLTER ECG SYSTEMS
- 9.5.4.1 Increasing demand for long-term rhythm monitoring to improve market adoption
- 9.6 TELEMETRY & CENTRAL MONITORING SYSTEMS
- 9.6.1 VOLUME ANALYSIS OF TELEMETRY & CENTRAL MONITORING SYSTEMS, 2024-2031
- 9.6.2 CENTRAL MONITORING SYSTEMS
- 9.6.2.1 Growing need for multi-patient surveillance and workflow efficiency to support adoption
- 9.6.3 WIRELESS TELEMETRY SYSTEMS
- 9.6.3.1 Increasing demand for mobility-enabled inpatient monitoring to drive market growth
- 9.6.4 REMOTE PATIENT MONITORING SYSTEMS
- 9.6.4.1 Home-based data capture and chronic-care follow-up to accelerate market development
- 9.7 OTHER VETERINARY MONITORING EQUIPMENT
- 9.7.1 VOLUME ANALYSIS OF OTHER VETERINARY MONITORING EQUIPMENT, 2024-2031
10 VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA
- 10.1 INTRODUCTION
- 10.2 CARDIOLOGY
- 10.2.1 ECG MONITORING
- 10.2.1.1 Increasing adoption of cardiac screening and remote interpretation capabilities to support market growth
- 10.2.2 BLOOD PRESSURE MONITORING
- 10.2.2.1 Increasing demand for accurate cardiovascular assessment and veterinary-specific monitoring solutions to drive market growth
- 10.2.3 CARDIAC RHYTHM MONITORING
- 10.2.3.1 Increasing need for continuous cardiac surveillance and advanced arrhythmia detection to support market growth
- 10.2.4 HOLTER MONITORING
- 10.2.4.1 Increasing adoption of wearable cardiac monitoring and AI-assisted rhythm analysis to support market growth
- 10.2.1 ECG MONITORING
- 10.3 NEUROLOGY
- 10.3.1 EEG MONITORING
- 10.3.1.1 Increasing demand for objective neurological assessment and AI-enabled monitoring to support market growth
- 10.3.2 NEUROMUSCULAR MONITORING
- 10.3.2.1 Increasing focus on anesthesia safety and objective recovery assessment to support market growth
- 10.3.3 INTRACRANIAL PRESSURE MONITORING
- 10.3.3.1 Increasing demand for advanced neurological assessment and non-invasive monitoring approaches to support market growth
- 10.3.1 EEG MONITORING
- 10.4 RESPIRATORY DISORDERS
- 10.5 WEIGHT & TEMPERATURE MONITORING
- 10.5.1 BODY WEIGHT MONITORING
- 10.5.1.1 Increasing demand for accurate dosing and longitudinal health tracking to sustain market growth
- 10.5.2 BODY TEMPERATURE MONITORING
- 10.5.2.1 Increasing emphasis on perioperative safety and continuous physiological monitoring to support market growth
- 10.5.3 CONTINUOUS TEMPERATURE MONITORING
- 10.5.3.1 Increasing adoption of continuous trend monitoring and connected devices to expand market growth
- 10.5.4 WEARABLE WEIGHT & TEMPERATURE MONITORING
- 10.5.4.1 Increasing adoption of connected health monitoring and wearable technologies to support market growth
- 10.5.1 BODY WEIGHT MONITORING
- 10.6 MULTI-PARAMETER MONITORING
- 10.6.1 SURGICAL MONITORING
- 10.6.1.1 Increasing focus on anesthesia safety and integrated surgical monitoring to sustain market growth
- 10.6.2 CRITICAL CARE MONITORING
- 10.6.2.1 Increasing demand for advanced ICU monitoring and centralized patient surveillance to support market growth
- 10.6.3 EMERGENCY MONITORING
- 10.6.3.1 Increasing demand for rapid response monitoring and portable emergency-care solutions to drive market growth
- 10.6.4 RECOVERY MONITORING
- 10.6.4.1 Increasing focus on post-anesthetic safety and continuous recovery monitoring to support market growth
- 10.6.1 SURGICAL MONITORING
- 10.7 OTHER TARGET AREAS
11 VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE
- 11.1 INTRODUCTION
- 11.2 COMPANION ANIMALS
- 11.2.1 DOGS
- 11.2.1.1 Large dog population and expanding advanced-care applications to support market growth
- 11.2.2 CATS
- 11.2.2.1 Increasing feline ownership and specialized monitoring requirements to support market growth
- 11.2.3 HORSES
- 11.2.3.1 High-value equine procedures and specialized monitoring requirements to support market growth
- 11.2.4 OTHER COMPANION ANIMALS
- 11.2.1 DOGS
- 11.3 LIVESTOCK
- 11.3.1 CATTLE
- 11.3.1.1 Large cattle population and AI-enabled herd monitoring solutions to support market growth
- 11.3.2 PIGS
- 11.3.2.1 Increasing focus on herd health surveillance and automated disease detection to support market growth
- 11.3.3 POULTRY
- 11.3.3.1 Increasing adoption of automated flock monitoring and precision-production technologies to support market growth
- 11.3.4 OTHER LIVESTOCK ANIMALS
- 11.3.1 CATTLE
12 VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY
- 12.1 INTRODUCTION
- 12.2 WIRED MONITORING SYSTEMS
- 12.2.1 STABLE CONNECTIVITY AND ESTABLISHED CLINICAL WORKFLOWS TO SUSTAIN WIRED MONITORING ADOPTION
- 12.3 WIRELESS MONITORING SYSTEMS
- 12.3.1 INCREASING NEED FOR MOBILITY AND CONNECTED PATIENT SURVEILLANCE TO DRIVE WIRELESS MONITORING DEMAND
- 12.4 REMOTE PATIENT MONITORING
- 12.4.1 INCREASING ADOPTION OF CONNECTED HEALTH PLATFORMS AND LONGITUDINAL MONITORING TO SUPPORT MARKET GROWTH
- 12.5 WEARABLE MONITORING TECHNOLOGY
- 12.5.1 INCREASING ADOPTION OF CONTINUOUS BIOSENSING AND LESS RESTRICTIVE MONITORING SOLUTIONS TO SUPPORT MARKET GROWTH
- 12.6 POINT-OF-CARE MONITORING
- 12.6.1 INCREASING DEMAND FOR RAPID ASSESSMENT AND PORTABLE MONITORING SOLUTIONS TO SUPPORT MARKET GROWTH
13 VETERINARY MONITORING EQUIPMENT MARKET, BY END USER
- 13.1 INTRODUCTION
- 13.2 VETERINARY GENERAL PRACTICE
- 13.2.1 INCREASING PRACTICE MODERNIZATION AND ROUTINE CARE VOLUMES TO SUPPORT MARKET GROWTH
- 13.3 ER/URGENT CARE
- 13.3.1 INCREASING DEMAND FOR EMERGENCY RESPONSE CAPABILITIES AND CONTINUOUS CRITICAL MONITORING TO SUPPORT MARKET GROWTH
- 13.4 SPECIALTY CENTERS
- 13.4.1 INCREASING SPECIALTY-CARE DEMAND AND ADVANCED MONITORING ADOPTION TO SUPPORT MARKET GROWTH
- 13.5 OTHER END USERS
14 VETERINARY MONITORING EQUIPMENT MARKET, BY REGION
- 14.1 INTRODUCTION
- 14.2 NORTH AMERICA
- 14.2.1 MACROECONOMIC OUTLOOK FOR NORTH AMERICA
- 14.2.2 NORTH AMERICA: VOLUME ANALYSIS OF VETERINARY MONITORING EQUIPMENT, BY TYPE, 2024-2031
- 14.2.3 US
- 14.2.3.1 Large pet-owning base and advanced specialty infrastructure to sustain market leadership
- 14.2.4 CANADA
- 14.2.4.1 High pet ownership and need for accessible veterinary care to support adoption
- 14.3 EUROPE
- 14.3.1 MACROECONOMIC OUTLOOK FOR EUROPE
- 14.3.2 EUROPE: VOLUME ANALYSIS OF VETERINARY MONITORING EQUIPMENT, BY TYPE, 2024-2031
- 14.3.3 GERMANY
- 14.3.3.1 Large veterinary workforce and dual companion-animal and livestock demand to support market leadership
- 14.3.4 UK
- 14.3.4.1 Corporate practice expansion and strong referral networks to support market growth
- 14.3.5 FRANCE
- 14.3.5.1 Extensive veterinary network and specialty care development to drive market
- 14.3.6 ITALY
- 14.3.6.1 Expanding companion-animal care and livestock monitoring applications to support market growth
- 14.3.7 SPAIN
- 14.3.7.1 Strong livestock production and growing urban pet care to support market expansion
- 14.3.8 NORWAY
- 14.3.8.1 High companion-animal ownership and strong animal healthcare standards to support market growth
- 14.3.9 DENMARK
- 14.3.9.1 Strong livestock base and advanced veterinary standards to support market growth
- 14.3.10 REST OF EUROPE
- 14.4 ASIA PACIFIC
- 14.4.1 MACROECONOMIC OUTLOOK FOR ASIA PACIFIC
- 14.4.2 ASIA PACIFIC: VOLUME ANALYSIS OF VETERINARY MONITORING EQUIPMENT, BY TYPE, 2024-2031
- 14.4.3 CHINA
- 14.4.3.1 Domestic manufacturing, urban pet care, and livestock modernization to drive market
- 14.4.4 JAPAN
- 14.4.4.1 Aging pet population and high clinical standards to support market growth
- 14.4.5 INDIA
- 14.4.5.1 Expanding animal-health infrastructure and need for portable equipment to support market growth
- 14.4.6 AUSTRALIA
- 14.4.6.1 High pet ownership and demand for connected veterinary care to support market growth
- 14.4.7 SOUTH KOREA
- 14.4.7.1 Rising pet ownership and digital adoption to support market growth
- 14.4.8 REST OF ASIA PACIFIC
- 14.5 LATIN AMERICA
- 14.5.1 MACROECONOMIC OUTLOOK FOR LATIN AMERICA
- 14.5.2 LATIN AMERICA: VOLUME ANALYSIS OF VETERINARY MONITORING EQUIPMENT, BY TYPE, 2024-2031
- 14.5.3 BRAZIL
- 14.5.3.1 Large livestock base and expanding urban pet care to support market leadership
- 14.5.4 MEXICO
- 14.5.4.1 Veterinary-access expansion and livestock biosecurity to support market growth
- 14.5.5 REST OF LATIN AMERICA
- 14.6 MIDDLE EAST & AFRICA
- 14.6.1 MACROECONOMIC OUTLOOK FOR MIDDLE EAST & AFRICA
- 14.6.2 MIDDLE EAST & AFRICA: VOLUME ANALYSIS OF VETERINARY MONITORING EQUIPMENT, BY TYPE, 2024-2031
- 14.6.3 GCC COUNTRIES
- 14.6.3.1 Kingdom of Saudi Arabia
- 14.6.3.1.1 Food security investment and specialized animal care to support market growth
- 14.6.3.2 United Arab Emirates
- 14.6.3.2.1 Advanced veterinary infrastructure and premium animal care to drive market
- 14.6.3.3 Rest of GCC countries
- 14.6.3.1 Kingdom of Saudi Arabia
- 14.6.4 REST OF MIDDLE EAST & AFRICA
15 COMPETITIVE LANDSCAPE
- 15.1 OVERVIEW
- 15.2 KEY PLAYER STRATEGIES/RIGHT TO WIN, 2023-2026
- 15.2.1 OVERVIEW OF STRATEGIES ADOPTED BY KEY MARKET PLAYERS
- 15.3 REVENUE ANALYSIS, 2023-2025
- 15.4 MARKET SHARE ANALYSIS, 2025
- 15.4.1 GLOBAL: VETERINARY MONITORING EQUIPMENT MARKET SHARE ANALYSIS, 2025
- 15.4.1.1 US: Veterinary monitoring equipment market share analysis, 2025
- 15.4.1.2 Europe: Veterinary monitoring equipment market share analysis, 2025
- 15.4.1 GLOBAL: VETERINARY MONITORING EQUIPMENT MARKET SHARE ANALYSIS, 2025
- 15.5 BRAND/PRODUCT COMPARISON
- 15.6 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 15.6.1 STARS
- 15.6.2 EMERGING LEADERS
- 15.6.3 PERVASIVE PLAYERS
- 15.6.4 PARTICIPANTS
- 15.6.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 15.6.5.1 Company footprint
- 15.6.5.2 Region footprint
- 15.6.5.3 Type footprint
- 15.6.5.4 Target area footprint
- 15.6.5.5 Animal type footprint
- 15.6.5.6 Technology footprint
- 15.6.5.7 End user footprint
- 15.7 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 15.7.1 PROGRESSIVE COMPANIES
- 15.7.2 RESPONSIVE COMPANIES
- 15.7.3 DYNAMIC COMPANIES
- 15.7.4 STARTING BLOCKS
- 15.7.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 15.7.5.1 Detailed list of key startups/SMEs
- 15.7.5.2 Competitive benchmarking of key startups/SMEs
- 15.8 COMPANY VALUATION AND FINANCIAL METRICS
- 15.8.1 FINANCIAL METRICS
- 15.8.2 COMPANY VALUATION
- 15.9 COMPETITIVE SCENARIO
- 15.9.1 PRODUCT LAUNCHES
- 15.9.2 DEALS
- 15.9.3 EXPANSIONS
- 15.9.4 OTHER DEVELOPMENTS
16 COMPANY PROFILES
- 16.1 KEY PLAYERS
- 16.1.1 MIDMARK CORPORATION
- 16.1.1.1 Business overview
- 16.1.1.2 Products/Solutions/Services offered
- 16.1.1.3 Recent developments
- 16.1.1.3.1 Product launches
- 16.1.1.4 MnM view
- 16.1.1.4.1 Key strengths
- 16.1.1.4.2 Strategic choices
- 16.1.1.4.3 Weaknesses & competitive threats
- 16.1.2 SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD.
- 16.1.2.1 Business overview
- 16.1.2.2 Products/Solutions/Services offered
- 16.1.2.3 Recent developments
- 16.1.2.3.1 Product launches
- 16.1.2.3.2 Expansions
- 16.1.2.4 MnM view
- 16.1.2.4.1 Key Strengths
- 16.1.2.4.2 Strategic Choices
- 16.1.2.4.3 Weaknesses & Competitive Threats
- 16.1.3 COVETRUS, INC.
- 16.1.3.1 Business overview
- 16.1.3.2 Products/Solutions/Services offered
- 16.1.3.3 Recent developments
- 16.1.3.3.1 Deals
- 16.1.3.3.2 Expansions
- 16.1.3.4 MnM view
- 16.1.3.4.1 Key Strengths
- 16.1.3.4.2 Strategic Choices
- 16.1.3.4.3 Weaknesses & Competitive Threats
- 16.1.4 SUNTECH MEDICAL, INC.
- 16.1.4.1 Business overview
- 16.1.4.2 Products/Solutions/Services offered
- 16.1.4.3 Recent developments
- 16.1.4.3.1 Product launches
- 16.1.4.3.2 Expansions
- 16.1.4.4 MnM view
- 16.1.4.4.1 Key Strengths
- 16.1.4.4.2 Strategic Choices
- 16.1.4.4.3 Weaknesses & Competitive Threats
- 16.1.5 LEADING EDGE VETERINARY EQUIPMENT
- 16.1.5.1 Business overview
- 16.1.5.2 Products/Solutions/Services offered
- 16.1.5.3 MnM view
- 16.1.5.3.1 Key Strengths
- 16.1.5.3.2 Strategic Choices
- 16.1.5.3.3 Weaknesses & Competitive Threats
- 16.1.6 EICKEMEYER VETERINARY EQUIPMENT LTD.
- 16.1.6.1 Business overview
- 16.1.6.2 Products/Solutions/Services offered
- 16.1.7 NONIN MEDICAL, INC.
- 16.1.7.1 Business overview
- 16.1.7.2 Products/Solutions/Services offered
- 16.1.7.3 Recent developments
- 16.1.7.3.1 Deals
- 16.1.8 DIGICARE BIOMEDICAL
- 16.1.8.1 Business overview
- 16.1.8.2 Products/Solutions/Services offered
- 16.1.9 BIONET CO., LTD.
- 16.1.9.1 Business overview
- 16.1.9.2 Products/Solutions/Services offered
- 16.1.9.3 Recent developments
- 16.1.9.3.1 Other developments
- 16.1.10 EDAN INSTRUMENTS, INC.
- 16.1.10.1 Business overview
- 16.1.10.2 Products/Solutions/Services offered
- 16.1.10.3 Recent developments
- 16.1.10.3.1 Expansions
- 16.1.11 SHENZHEN COMEN MEDICAL INSTRUMENTS CO., LTD.
- 16.1.11.1 Business overview
- 16.1.11.2 Products/Solutions/Services offered
- 16.1.11.3 Recent developments
- 16.1.11.3.1 Expansions
- 16.1.12 GUANGDONG BIOLIGHT MEDITECH CO., LTD.
- 16.1.12.1 Business overview
- 16.1.12.2 Products/Solutions/Services offered
- 16.1.13 VETLAND MEDICAL SALES & SERVICES, LLC
- 16.1.13.1 Business overview
- 16.1.13.2 Products/Solutions/Services offered
- 16.1.14 BURTONS MEDICAL EQUIPMENT LTD.
- 16.1.14.1 Business overview
- 16.1.14.2 Products/Solutions/Services offered
- 16.1.14.3 Recent developments
- 16.1.14.3.1 Deals
- 16.1.15 AVANTE ANIMAL HEALTH
- 16.1.15.1 Business overview
- 16.1.15.2 Products/Solutions/Services offered
- 16.1.1 MIDMARK CORPORATION
- 16.2 OTHER PLAYERS
- 16.2.1 SINO-HERO
- 16.2.2 DISPOMED LTD.
- 16.2.3 BMV ANIMAL TECHNOLOGY CO., LTD.
- 16.2.4 SHENZHEN MED-LINK ELECTRONICS TECH CO., LTD.
- 16.2.5 VETSPECS, INC.
- 16.2.6 CONTEC MEDICAL SYSTEMS CO., LTD.
- 16.2.7 INFINIUM MEDICAL, INC.
- 16.2.8 DEXTRONIX, INC.
- 16.2.9 MASIMO CORPORATION
- 16.2.10 MEDTRONIC
- 16.2.11 ICU MEDICAL, INC.
17 RESEARCH METHODOLOGY
- 17.1 RESEARCH DATA
- 17.1.1 SECONDARY DATA
- 17.1.1.1 Key secondary sources
- 17.1.2 PRIMARY DATA
- 17.1.2.1 Primary sources
- 17.1.2.2 Key data from primary sources
- 17.1.2.3 Key industry insights
- 17.1.2.4 Breakdown of primaries
- 17.1.1 SECONDARY DATA
- 17.2 MARKET SIZE ESTIMATION
- 17.2.1 APPROACH 1: COMPANY REVENUE ANALYSIS APPROACH
- 17.2.2 APPROACH 2: CUSTOMER-BASED MARKET ESTIMATION
- 17.2.3 APPROACH 3: TOP-DOWN APPROACH
- 17.2.4 APPROACH 4: BOTTOM-UP APPROACH
- 17.2.5 APPROACH 4: PRIMARY INTERVIEWS
- 17.2.6 APPROACH 5: DEMAND-SIDE APPROACH
- 17.2.7 APPROACH 6: VOLUME DATA ANALYSIS
- 17.3 DATA TRIANGULATION AND MARKET BREAKDOWN
- 17.4 MARKET SHARE ASSESSMENT
- 17.5 RESEARCH ASSUMPTIONS
- 17.5.1 RESEARCH ASSUMPTIONS
- 17.5.2 GROWTH RATE ASSUMPTIONS
- 17.6 RISK ASSESSMENT
- 17.7 RESEARCH LIMITATIONS
18 APPENDIX
- 18.1 DISCUSSION GUIDE
- 18.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 18.3 CUSTOMIZATION OPTIONS
- 18.3.1 PRODUCT ANALYSIS
- 18.3.2 COMPANY INFORMATION
- 18.3.3 GEOGRAPHIC ANALYSIS
- 18.4 RELATED REPORTS
- 18.5 AUTHOR DETAILS
List of Tables
- TABLE 1 USD CONVERSION RATES
- TABLE 2 IMPACT OF PORTER'S FIVE FORCES ON VETERINARY MONITORING EQUIPMENT MARKET
- TABLE 3 GDP CHANGE, BY KEY COUNTRY, 2021-2030 (USD BILLION)
- TABLE 4 ROLE OF COMPANIES IN ECOSYSTEM
- TABLE 5 LIST OF KEY END USERS
- TABLE 6 LIST OF KEY REGULATORY BODIES
- TABLE 7 AVERAGE SELLING PRICE TREND OF KEY PLAYERS, BY PRODUCT, 2023-2025 (USD)
- TABLE 8 AVERAGE SELLING PRICE TREND, BY REGION, 2023-2025 (USD)
- TABLE 9 IMPORT DATA FOR HS CODE 9018-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 10 EXPORT DATA FOR HS CODE 9018-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 11 VETERINARY MONITORING EQUIPMENT MARKET: MAJOR CONFERENCES AND EVENTS, 2026-2027
- TABLE 12 MASIMO RADICAL-7 PULSE CO-OXIMETRY - EVALUATION IN ANAESTHETIZED HORSES
- TABLE 13 MINDRAY BENEHEART D3 / PATIENT MONITORING - ANESTHETIC MANAGEMENT OF DOG WITH CARDIAC DISEASE
- TABLE 14 NONIN PULSE OXIMETRY - OXYGENATION MONITORING IN IMMOBILIZED WHITE RHINOCEROSES
- TABLE 15 RECIPROCAL TARIFF RATES ADJUSTED BY US, 2025
- TABLE 16 KEY PRODUCT-RELATED TARIFF
- TABLE 17 NORTH AMERICA: IMPACT OF US TARIFF ON CANADA
- TABLE 18 ASIA PACIFIC: IMPACT OF US TARIFF ON CHINA, JAPAN, AND INDIA
- TABLE 19 EUROPE: IMPACT OF US TARIFF ON GERMANY AND UK
- TABLE 20 LATIN AMERICA: IMPACT OF US TARIFF ON MEXICO
- TABLE 21 VETERINARY MONITORING EQUIPMENT MARKET: KEY PATENTS, 2023-2025
- TABLE 22 COMPANIES IMPLEMENTING AI
- TABLE 23 NORTH AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 24 EUROPE: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 25 ASIA PACIFIC: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 26 LATIN AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 27 MIDDLE EAST & AFRICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 28 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR VETERINARY MONITORING EQUIPMENT, BY END USER
- TABLE 29 KEY BUYING CRITERIA FOR VETERINARY MONITORING EQUIPMENT, BY END USER
- TABLE 30 VETERINARY MONITORING EQUIPMENT MARKET: ADOPTION BARRIERS AND INTERNAL CHALLENGES
- TABLE 31 VETERINARY MONITORING EQUIPMENT MARKET: UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES
- TABLE 32 VETERINARY MONITORING EQUIPMENT MARKET: KEY PROFITABILITY DRIVERS
- TABLE 33 VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 34 MULTI-PARAMETER VETERINARY MONITORS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 35 MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 36 MULTI-PARAMETER VETERINARY MONITORS MARKET, BY REGION, 2024-2031 (THOUSAND UNITS)
- TABLE 37 KEY PLAYERS PROVIDING PORTABLE MULTI-PARAMETER MONITORS
- TABLE 38 PORTABLE MULTI-PARAMETER MONITORS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 39 KEY PLAYERS PROVIDING TABLETOP MULTI-PARAMETER MONITORS
- TABLE 40 TABLETOP MULTI-PARAMETER MONITORS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 41 KEY PLAYERS PROVIDING MODULAR MULTI-PARAMETER MONITORS
- TABLE 42 MODULAR MULTI-PARAMETER MONITORS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 43 KEY PLAYERS PROVIDING OTHER MULTI-PARAMETER VETERINARY MONITORS
- TABLE 44 OTHER MULTI-PARAMETER VETERINARY MONITORS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 45 CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 46 CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 47 CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY REGION, 2024-2031 (THOUSAND UNITS)
- TABLE 48 KEY PLAYERS PROVIDING CAPNOGRAPHY SYSTEMS
- TABLE 49 CAPNOGRAPHY SYSTEMS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 50 KEY PLAYERS PROVIDING PULSE OXIMETRY SYSTEMS
- TABLE 51 PULSE OXIMETRY SYSTEMS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 52 ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 53 ANESTHESIA MACHINES & CONSUMABLES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 54 ANESTHESIA MACHINES & CONSUMABLES MARKET, BY REGION, 2024-2031 (THOUSAND UNITS)
- TABLE 55 ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 56 ANESTHESIA MACHINES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 57 KEY PLAYERS PROVIDING ANESTHESIA MACHINES WITHOUT INTEGRATED VENTILATORS
- TABLE 58 ANESTHESIA MACHINES WITHOUT INTEGRATED VENTILATORS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 59 KEY PLAYERS PROVIDING ADVANCED ANESTHESIA MACHINES WITH INTEGRATED VENTILATORS
- TABLE 60 ADVANCED ANESTHESIA MACHINES WITH INTEGRATED VENTILATORS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 61 ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 62 ANESTHESIA CONSUMABLES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 63 KEY PLAYERS PROVIDING SODASORB
- TABLE 64 SODASORB MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 65 KEY PLAYERS PROVIDING VAPORIZERS
- TABLE 66 VAPORIZERS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 67 KEY PLAYERS PROVIDING SCAVENGERS
- TABLE 68 SCAVENGERS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 69 ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 70 ECG & HOLTER MONITORING SYSTEMS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 71 ECG & HOLTER MONITORING SYSTEMS MARKET, BY REGION, 2024-2031 (THOUSAND UNITS)
- TABLE 72 KEY PLAYERS PROVIDING RESTING ECG SYSTEMS
- TABLE 73 RESTING ECG SYSTEMS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 74 CONTINUOUS ECG SYSTEMS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 75 KEY PLAYERS PROVIDING HOLTER ECG SYSTEMS
- TABLE 76 HOLTER ECG SYSTEMS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 77 TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 78 TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 79 TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY REGION, 2024-2031 (THOUSAND UNITS)
- TABLE 80 KEY PLAYERS PROVIDING CENTRAL MONITORING SYSTEMS
- TABLE 81 CENTRAL MONITORING SYSTEMS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 82 KEY PLAYERS PROVIDING WIRELESS TELEMETRY SYSTEMS
- TABLE 83 WIRELESS TELEMETRY SYSTEMS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 84 REMOTE PATIENT MONITORING SYSTEMS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 85 KEY PLAYERS PROVIDING OTHER VETERINARY MONITORING EQUIPMENT
- TABLE 86 OTHER VETERINARY MONITORING EQUIPMENT MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 87 OTHER VETERINARY MONITORING EQUIPMENT MARKET, BY REGION, 2024-2031 (THOUSAND UNITS)
- TABLE 88 VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 89 CARDIOLOGY MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 90 CARDIOLOGY MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 91 ECG MONITORING MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 92 BLOOD PRESSURE MONITORING MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 93 CARDIAC RHYTHM MONITORING MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 94 HOLTER MONITORING MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 95 NEUROLOGY MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 96 NEUROLOGY MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 97 EEG MONITORING MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 98 NEUROMUSCULAR MONITORING MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 99 INTRACRANIAL PRESSURE MONITORING MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 100 RESPIRATORY DISORDERS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 101 WEIGHT & TEMPERATURE MONITORING MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 102 WEIGHT & TEMPERATURE MONITORING MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 103 BODY WEIGHT MONITORING MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 104 BODY TEMPERATURE MONITORING MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 105 CONTINUOUS TEMPERATURE MONITORING MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 106 WEARABLE WEIGHT & TEMPERATURE MONITORING MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 107 MULTI-PARAMETER MONITORING MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 108 MULTI-PARAMETER MONITORING MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 109 SURGICAL MONITORING MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 110 CRITICAL CARE MONITORING MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 111 EMERGENCY MONITORING MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 112 RECOVERY MONITORING MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 113 OTHER TARGET AREAS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 114 VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 115 COMPANION ANIMALS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 116 COMPANION ANIMALS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 117 DOGS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 118 CATS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 119 HORSES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 120 OTHER COMPANION ANIMALS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 121 LIVESTOCK MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 122 LIVESTOCK MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 123 CATTLE MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 124 PIGS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 125 POULTRY MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 126 OTHER LIVESTOCK ANIMALS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 127 VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 128 WIRED MONITORING SYSTEMS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 129 WIRELESS MONITORING SYSTEMS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 130 REMOTE PATIENT MONITORING MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 131 WEARABLE MONITORING TECHNOLOGY MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 132 POINT-OF-CARE MONITORING MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 133 VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 134 VETERINARY GENERAL PRACTICE MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 135 ER/URGENT CARE MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 136 SPECIALTY CENTERS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 137 OTHER END USERS MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 138 VETERINARY MONITORING EQUIPMENT MARKET, BY REGION, 2024-2031 (USD MILLION)
- TABLE 139 NORTH AMERICA: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE 4-2031 (THOUSAND UNITS)
- TABLE 140 NORTH AMERICA: VETERINARY MONITORING EQUIPMENT MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 141 NORTH AMERICA: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 142 NORTH AMERICA: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 143 NORTH AMERICA: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 144 NORTH AMERICA: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 145 NORTH AMERICA: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 146 NORTH AMERICA: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 147 NORTH AMERICA: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 148 NORTH AMERICA: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 149 NORTH AMERICA: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 150 NORTH AMERICA: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 151 NORTH AMERICA: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 152 NORTH AMERICA: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 153 NORTH AMERICA: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 154 NORTH AMERICA: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 155 NORTH AMERICA: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 156 NORTH AMERICA: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 157 NORTH AMERICA: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 158 NORTH AMERICA: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 159 US: KEY MACRO INDICATORS
- TABLE 160 US: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 161 US: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 162 US: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 163 US: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 164 US: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 165 US: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 166 US: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 167 US: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 168 US: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 169 US: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 170 US: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 171 US: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 172 US: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 173 US: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 174 US: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 175 US: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 176 US: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 177 US: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 178 CANADA: KEY MACRO INDICATORS
- TABLE 179 CANADA: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 180 CANADA: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 181 CANADA: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 182 CANADA: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 183 CANADA: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 184 CANADA: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 185 CANADA: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 186 CANADA: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 187 CANADA: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 188 CANADA: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 189 CANADA: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 190 CANADA: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 191 CANADA: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 192 CANADA: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 193 CANADA: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 194 CANADA: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 195 CANADA: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 196 CANADA: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 197 EUROPE: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (THOUSAND UNITS)
- TABLE 198 EUROPE: VETERINARY MONITORING EQUIPMENT MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 199 EUROPE: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 200 EUROPE: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 201 EUROPE: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 202 EUROPE: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 203 EUROPE: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 204 EUROPE: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 205 EUROPE: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 206 EUROPE: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 207 EUROPE: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 208 EUROPE: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 209 EUROPE: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 210 EUROPE: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 211 EUROPE: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 212 EUROPE: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 213 EUROPE: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 214 EUROPE: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 215 EUROPE: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 216 EUROPE: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 217 GERMANY: KEY MACRO INDICATORS
- TABLE 218 GERMANY: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 219 GERMANY: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 220 GERMANY: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 221 GERMANY: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 222 GERMANY: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 223 GERMANY: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 224 GERMANY: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 225 GERMANY: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 226 GERMANY: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 227 GERMANY: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 228 GERMANY: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 229 GERMANY: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 230 GERMANY: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 231 GERMANY: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 232 GERMANY: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 233 GERMANY: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 234 GERMANY: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 235 GERMANY: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 236 UK: KEY MACRO INDICATORS
- TABLE 237 UK: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 238 UK: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 239 UK: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 240 UK: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 241 UK: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 242 UK: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 243 UK: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 244 UK: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 245 UK: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 246 UK: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 247 UK: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 248 UK: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 249 UK: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 250 UK: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 251 UK: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 252 UK: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 253 UK: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 254 UK: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 255 FRANCE: KEY MACRO INDICATORS
- TABLE 256 FRANCE: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 257 FRANCE: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 258 FRANCE: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 259 FRANCE: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 260 FRANCE: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 261 FRANCE: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 262 FRANCE: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 263 FRANCE: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 264 FRANCE: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 265 FRANCE: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 266 FRANCE: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 267 FRANCE: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 268 FRANCE: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 269 FRANCE: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 270 FRANCE: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 271 FRANCE: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 272 FRANCE: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 273 FRANCE: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 274 ITALY: KEY MACRO INDICATORS
- TABLE 275 ITALY: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 276 ITALY: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 277 ITALY: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 278 ITALY: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 279 ITALY: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 280 ITALY: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 281 ITALY: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 282 ITALY: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 283 ITALY: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 284 ITALY: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 285 ITALY: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 286 ITALY: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 287 ITALY: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 288 ITALY: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 289 ITALY: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 290 ITALY: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 291 ITALY: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 292 ITALY: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 293 SPAIN: KEY MACRO INDICATORS
- TABLE 294 SPAIN: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 295 SPAIN: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 296 SPAIN: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 297 SPAIN: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 298 SPAIN: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 299 SPAIN: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 300 SPAIN: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 301 SPAIN: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 302 SPAIN: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 303 SPAIN: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 304 SPAIN: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 305 SPAIN: VETERINARY MONITORING EQUIPMENT MARKET, BY WEIGHT & TEMPERATURE MONITORING, 2024-2031 (USD MILLION)
- TABLE 306 SPAIN: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 307 SPAIN: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 308 SPAIN: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 309 SPAIN: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 310 SPAIN: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 311 SPAIN: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 312 NORWAY: KEY MACRO INDICATORS
- TABLE 313 NORWAY: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 314 NORWAY: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 315 NORWAY: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 316 NORWAY: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 317 NORWAY: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 318 NORWAY: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 319 NORWAY: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 320 NORWAY: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 321 NORWAY: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 322 NORWAY: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 323 NORWAY: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 324 NORWAY: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 325 NORWAY: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 326 NORWAY: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 327 NORWAY: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 328 NORWAY: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 329 NORWAY: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 330 NORWAY: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 331 DENMARK: KEY MACRO INDICATORS
- TABLE 332 DENMARK: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 333 DENMARK: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 334 DENMARK: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 335 DENMARK: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 336 DENMARK: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 337 DENMARK: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 338 DENMARK: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 339 DENMARK: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 340 DENMARK: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 341 DENMARK: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 342 DENMARK: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 343 DENMARK: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 344 DENMARK: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 345 DENMARK: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 346 DENMARK: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 347 DENMARK: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 348 DENMARK: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 349 DENMARK: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 350 REST OF EUROPE: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 351 REST OF EUROPE: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 352 REST OF EUROPE: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 353 REST OF EUROPE: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 354 REST OF EUROPE: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 355 REST OF EUROPE: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 356 REST OF EUROPE: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 357 REST OF EUROPE: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 358 REST OF EUROPE: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 359 REST OF EUROPE: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 360 REST OF EUROPE: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 361 REST OF EUROPE: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 362 REST OF EUROPE: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 363 REST OF EUROPE: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 364 REST OF EUROPE: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 365 REST OF EUROPE: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 366 REST OF EUROPE: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 367 REST OF EUROPE: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 368 ASIA PACIFIC VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (THOUSAND UNITS)
- TABLE 369 ASIA PACIFIC: VETERINARY MONITORING EQUIPMENT MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 370 ASIA PACIFIC: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 371 ASIA PACIFIC: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 372 ASIA PACIFIC: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 373 ASIA PACIFIC: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 374 ASIA PACIFIC: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 375 ASIA PACIFIC: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 376 ASIA PACIFIC: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 377 ASIA PACIFIC: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 378 ASIA PACIFIC: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 379 ASIA PACIFIC: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 380 ASIA PACIFIC: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 381 ASIA PACIFIC: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 382 ASIA PACIFIC: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 383 ASIA PACIFIC: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 384 ASIA PACIFIC: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 385 ASIA PACIFIC: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 386 ASIA PACIFIC: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 387 ASIA PACIFIC: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 388 CHINA: KEY MACRO INDICATORS
- TABLE 389 CHINA: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 390 CHINA: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 391 CHINA: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 392 CHINA: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 393 CHINA: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 394 CHINA: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 395 CHINA: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 396 CHINA: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 397 CHINA: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 398 CHINA: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 399 CHINA: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 400 CHINA: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 401 CHINA: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 402 CHINA: VETERINARY MONITORING EQUIPMENT MARKET ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 403 CHINA: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 404 CHINA: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 405 CHINA: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 406 CHINA: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 407 JAPAN: KEY MACRO INDICATORS
- TABLE 408 JAPAN: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 409 JAPAN: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 410 JAPAN: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 411 JAPAN: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 412 JAPAN: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 413 JAPAN: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 414 JAPAN: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 415 JAPAN: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 416 JAPAN: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 417 JAPAN: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 418 JAPAN: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 419 JAPAN: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 420 JAPAN: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 421 JAPAN: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 422 JAPAN: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 423 JAPAN: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 424 JAPAN: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 425 JAPAN: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 426 INDIA: KEY MACRO INDICATORS
- TABLE 427 INDIA: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 428 INDIA: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 429 INDIA: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 430 INDIA: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 431 INDIA: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 432 INDIA: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 433 INDIA: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 434 INDIA: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 435 INDIA: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 436 INDIA: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 437 INDIA: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 438 INDIA: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 439 INDIA: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 440 INDIA: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 441 INDIA: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 442 INDIA: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 443 INDIA: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 444 INDIA: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 445 AUSTRALIA: KEY MACRO INDICATORS
- TABLE 446 AUSTRALIA: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 447 AUSTRALIA: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 448 AUSTRALIA: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 449 AUSTRALIA: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 450 AUSTRALIA: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 451 AUSTRALIA: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 452 AUSTRALIA: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 453 AUSTRALIA: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 454 AUSTRALIA: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 455 AUSTRALIA: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 456 AUSTRALIA: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 457 AUSTRALIA: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 458 AUSTRALIA: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 459 AUSTRALIA: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 460 AUSTRALIA: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 461 AUSTRALIA: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 462 AUSTRALIA: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 463 AUSTRALIA: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 464 SOUTH KOREA: KEY MACRO INDICATORS
- TABLE 465 SOUTH KOREA: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 466 SOUTH KOREA: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 467 SOUTH KOREA: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 468 SOUTH KOREA: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 469 SOUTH KOREA: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 470 SOUTH KOREA: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 471 SOUTH KOREA: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 472 SOUTH KOREA: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 473 SOUTH KOREA: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 474 SOUTH KOREA: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 475 SOUTH KOREA: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 476 SOUTH KOREA: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 477 SOUTH KOREA: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 478 SOUTH KOREA: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 479 SOUTH KOREA: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 480 SOUTH KOREA: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 481 SOUTH KOREA: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 482 SOUTH KOREA: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 483 REST OF ASIA PACIFIC: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 484 REST OF ASIA PACIFIC: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 485 REST OF ASIA PACIFIC: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 486 REST OF ASIA PACIFIC: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 487 REST OF ASIA PACIFIC: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 488 REST OF ASIA PACIFIC: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 489 REST OF ASIA PACIFIC: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 490 REST OF ASIA PACIFIC: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 491 REST OF ASIA PACIFIC: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 492 REST OF ASIA PACIFIC: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 493 REST OF ASIA PACIFIC: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 494 REST OF ASIA PACIFIC: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 495 REST OF ASIA PACIFIC: VETERINARY MONITORING EQUIPMENT MARKET, BY MULTI-PARAMETER MONITORING, 2024-2031 (USD MILLION)
- TABLE 496 REST OF ASIA PACIFIC: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 497 REST OF ASIA PACIFIC: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 498 REST OF ASIA PACIFIC: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 499 REST OF ASIA PACIFIC: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 500 REST OF ASIA PACIFIC: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 501 LATIN AMERICA: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (THOUSAND UNITS)
- TABLE 502 LATIN AMERICA: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 503 LATIN AMERICA: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 504 LATIN AMERICA: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 505 LATIN AMERICA: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 506 LATIN AMERICA: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 507 LATIN AMERICA: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 508 LATIN AMERICA: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 509 LATIN AMERICA: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 510 LATIN AMERICA: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 511 LATIN AMERICA: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 512 LATIN AMERICA: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 513 LATIN AMERICA: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 514 LATIN AMERICA: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 515 LATIN AMERICA: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 516 LATIN AMERICA: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 517 LATIN AMERICA: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 518 LATIN AMERICA: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 519 LATIN AMERICA: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 520 BRAZIL: KEY MACRO INDICATORS
- TABLE 521 BRAZIL: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 522 BRAZIL: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 523 BRAZIL: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 524 BRAZIL: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 525 BRAZIL: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 526 BRAZIL: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 527 BRAZIL: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 528 BRAZIL: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 529 BRAZIL: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 530 BRAZIL: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 531 BRAZIL: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 532 BRAZIL: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 533 BRAZIL: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 534 BRAZIL: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 535 BRAZIL: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 536 BRAZIL: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 537 BRAZIL: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 538 BRAZIL: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 539 MEXICO: KEY MACRO INDICATORS
- TABLE 540 MEXICO: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 541 MEXICO: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 542 MEXICO: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 543 MEXICO: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 544 MEXICO: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 545 MEXICO: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 546 MEXICO: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 547 MEXICO: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 548 MEXICO: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 549 MEXICO: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 550 MEXICO: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 551 MEXICO: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 552 MEXICO: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 553 MEXICO: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 554 MEXICO: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 555 MEXICO: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 556 MEXICO: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 557 MEXICO: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 558 REST OF LATIN AMERICA: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 559 REST OF LATIN AMERICA: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 560 REST OF LATIN AMERICA: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 561 REST OF LATIN AMERICA: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 562 REST OF LATIN AMERICA: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 563 REST OF LATIN AMERICA: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 564 REST OF LATIN AMERICA: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 565 REST OF LATIN AMERICA: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 566 REST OF LATIN AMERICA: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 567 REST OF LATIN AMERICA: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 568 REST OF LATIN AMERICA: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 569 REST OF LATIN AMERICA: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 570 REST OF LATIN AMERICA: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 571 REST OF LATIN AMERICA: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 572 REST OF LATIN AMERICA: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 573 REST OF LATIN AMERICA: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 574 REST OF LATIN AMERICA: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 575 REST OF LATIN AMERICA: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 576 MIDDLE EAST & AFRICA: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (THOUSAND UNITS)
- TABLE 577 MIDDLE EAST & AFRICA: VETERINARY MONITORING EQUIPMENT MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 578 MIDDLE EAST & AFRICA: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 579 MIDDLE EAST & AFRICA: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 580 MIDDLE EAST & AFRICA: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 581 MIDDLE EAST & AFRICA: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 582 MIDDLE EAST & AFRICA: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 583 MIDDLE EAST & AFRICA: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 584 MIDDLE EAST & AFRICA: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 585 MIDDLE EAST & AFRICA: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 586 MIDDLE EAST & AFRICA: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 587 MIDDLE EAST & AFRICA: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 588 MIDDLE EAST & AFRICA: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 589 MIDDLE EAST & AFRICA: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 590 MIDDLE EAST & AFRICA: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 591 MIDDLE EAST & AFRICA: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 592 MIDDLE EAST & AFRICA: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 593 MIDDLE EAST & AFRICA: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 594 MIDDLE EAST & AFRICA: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 595 MIDDLE EAST & AFRICA: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 596 GCC COUNTRIES: VETERINARY MONITORING EQUIPMENT MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 597 GCC COUNTRIES: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 598 GCC COUNTRIES: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 599 GCC COUNTRIES: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 600 GCC COUNTRIES: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 601 GCC COUNTRIES: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 602 GCC COUNTRIES: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 603 GCC COUNTRIES: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 604 GCC COUNTRIES: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 605 GCC COUNTRIES: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 606 GCC COUNTRIES: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 607 GCC COUNTRIES: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 608 GCC COUNTRIES: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 609 GCC COUNTRIES: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 610 GCC COUNTRIES: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 611 GCC COUNTRIES: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 612 GCC COUNTRIES: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 613 GCC COUNTRIES: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 614 GCC COUNTRIES: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 615 KINGDOM OF SAUDI ARABIA: KEY MACRO INDICATORS
- TABLE 616 KINGDOM OF SAUDI ARABIA: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 617 KINGDOM OF SAUDI ARABIA: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 618 KINGDOM OF SAUDI ARABIA: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 619 KINGDOM OF SAUDI ARABIA: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 620 KINGDOM OF SAUDI ARABIA: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 621 KINGDOM OF SAUDI ARABIA: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 622 KINGDOM OF SAUDI ARABIA: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 623 KINGDOM OF SAUDI ARABIA: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 624 KINGDOM OF SAUDI ARABIA: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 625 KINGDOM OF SAUDI ARABIA: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 626 KINGDOM OF SAUDI ARABIA: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 627 KINGDOM OF SAUDI ARABIA: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 628 KINGDOM OF SAUDI ARABIA: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 629 KINGDOM OF SAUDI ARABIA: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 630 KINGDOM OF SAUDI ARABIA: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 631 KINGDOM OF SAUDI ARABIA: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 632 KINGDOM OF SAUDI ARABIA: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 633 KINGDOM OF SAUDI ARABIA: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 634 UNITED ARAB EMIRATES: KEY MACRO INDICATORS
- TABLE 635 UNITED ARAB EMIRATES: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 636 UNITED ARAB EMIRATES: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 637 UNITED ARAB EMIRATES: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 638 UNITED ARAB EMIRATES: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 639 UNITED ARAB EMIRATES: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 640 UNITED ARAB EMIRATES: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 641 UNITED ARAB EMIRATES: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 642 UNITED ARAB EMIRATES: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 643 UNITED ARAB EMIRATES: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 644 UNITED ARAB EMIRATES: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 645 UNITED ARAB EMIRATES: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 646 UNITED ARAB EMIRATES: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 647 UNITED ARAB EMIRATES: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 648 UNITED ARAB EMIRATES: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 649 UNITED ARAB EMIRATES: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 650 UNITED ARAB EMIRATES: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 651 UNITED ARAB EMIRATES: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 652 UNITED ARAB EMIRATES: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 653 REST OF GCC COUNTRIES: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 654 REST OF GCC COUNTRIES: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 655 REST OF GCC COUNTRIES: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 656 REST OF GCC COUNTRIES: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 657 REST OF GCC COUNTRIES: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 658 REST OF GCC COUNTRIES: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 659 REST OF GCC COUNTRIES: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 660 REST OF GCC COUNTRIES: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 661 REST OF GCC COUNTRIES: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 662 REST OF GCC COUNTRIES: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 663 REST OF GCC COUNTRIES: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 664 REST OF GCC COUNTRIES: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 665 REST OF GCC COUNTRIES: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 666 REST OF GCC COUNTRIES: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 667 REST OF GCC COUNTRIES: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 668 REST OF GCC COUNTRIES: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 669 REST OF GCC COUNTRIES: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 670 REST OF GCC COUNTRIES: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 671 REST OF MIDDLE EAST & AFRICA: VETERINARY MONITORING EQUIPMENT MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 672 REST OF MIDDLE EAST & AFRICA: MULTI-PARAMETER VETERINARY MONITORS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 673 REST OF MIDDLE EAST & AFRICA: CAPNOGRAPHY & OXIMETRY SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 674 REST OF MIDDLE EAST & AFRICA: ANESTHESIA MACHINES & CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 675 REST OF MIDDLE EAST & AFRICA: ANESTHESIA MACHINES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 676 REST OF MIDDLE EAST & AFRICA: ANESTHESIA CONSUMABLES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 677 REST OF MIDDLE EAST & AFRICA: ECG & HOLTER MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 678 REST OF MIDDLE EAST & AFRICA: TELEMETRY & CENTRAL MONITORING SYSTEMS MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 679 REST OF MIDDLE EAST & AFRICA: VETERINARY MONITORING EQUIPMENT MARKET, BY TARGET AREA, 2024-2031 (USD MILLION)
- TABLE 680 REST OF MIDDLE EAST & AFRICA: VETERINARY MONITORING EQUIPMENT MARKET FOR CARDIOLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 681 REST OF MIDDLE EAST & AFRICA: VETERINARY MONITORING EQUIPMENT MARKET FOR NEUROLOGY, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 682 REST OF MIDDLE EAST & AFRICA: VETERINARY MONITORING EQUIPMENT MARKET FOR WEIGHT & TEMPERATURE MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 683 REST OF MIDDLE EAST & AFRICA: VETERINARY MONITORING EQUIPMENT MARKET FOR MULTI-PARAMETER MONITORING, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 684 REST OF MIDDLE EAST & AFRICA: VETERINARY MONITORING EQUIPMENT MARKET, BY ANIMAL TYPE, 2024-2031 (USD MILLION)
- TABLE 685 REST OF MIDDLE EAST & AFRICA: VETERINARY MONITORING EQUIPMENT MARKET FOR COMPANION ANIMALS, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 686 REST OF MIDDLE EAST & AFRICA: VETERINARY MONITORING EQUIPMENT MARKET FOR LIVESTOCK, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 687 REST OF MIDDLE EAST & AFRICA: VETERINARY MONITORING EQUIPMENT MARKET, BY TECHNOLOGY, 2024-2031 (USD MILLION)
- TABLE 688 REST OF MIDDLE EAST & AFRICA: VETERINARY MONITORING EQUIPMENT MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 689 OVERVIEW OF STRATEGIES DEPLOYED BY KEY PLAYERS IN VETERINARY MONITORING EQUIPMENT MARKET, JANUARY 2023-JUNE 2026
- TABLE 690 GLOBAL: VETERINARY MONITORING EQUIPMENT MARKET: DEGREE OF COMPETITION
- TABLE 691 US: VETERINARY MONITORING EQUIPMENT MARKET: DEGREE OF COMPETITION
- TABLE 692 EUROPE: VETERINARY MONITORING EQUIPMENT MARKET: DEGREE OF COMPETITION
- TABLE 693 VETERINARY MONITORING EQUIPMENT MARKET: REGION FOOTPRINT
- TABLE 694 VETERINARY MONITORING EQUIPMENT MARKET: TYPE FOOTPRINT
- TABLE 695 VETERINARY MONITORING EQUIPMENT MARKET: TARGET AREA FOOTPRINT
- TABLE 696 VETERINARY MONITORING EQUIPMENT MARKET: ANIMAL TYPE FOOTPRINT
- TABLE 697 VETERINARY MONITORING EQUIPMENT MARKET: TECHNOLOGY FOOTPRINT
- TABLE 698 VETERINARY MONITORING EQUIPMENT MARKET: END USER FOOTPRINT
- TABLE 699 VETERINARY MONITORING EQUIPMENT MARKET: KEY STARTUPS/SMES
- TABLE 700 VETERINARY MONITORING EQUIPMENT MARKET: COMPETITIVE BENCHMARKING OF STARTUPS/SMES
- TABLE 701 VETERINARY MONITORING EQUIPMENT MARKET: PRODUCT LAUNCHES, 2023-JUNE 2026
- TABLE 702 VETERINARY MONITORING EQUIPMENT MARKET: DEALS, 2023-JUNE 2026
- TABLE 703 VETERINARY MONITORING EQUIPMENT MARKET: EXPANSIONS, 2023-JUNE 2026
- TABLE 704 VETERINARY MONITORING EQUIPMENT MARKET: OTHER DEVELOPMENTS, 2023-JUNE 2026
- TABLE 705 MIDMARK CORPORATION: COMPANY OVERVIEW
- TABLE 706 MIDMARK CORPORATION: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 707 MIDMARK CORPORATION: PRODUCT LAUNCHES
- TABLE 708 SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD.: COMPANY OVERVIEW
- TABLE 709 SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 710 SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD.: PRODUCT LAUNCHES
- TABLE 711 SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD.: EXPANSIONS
- TABLE 712 COVETRUS, INC.: COMPANY OVERVIEW
- TABLE 713 COVETRUS, INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 714 COVETRUS, INC.: DEALS
- TABLE 715 COVETRUS, INC.: EXPANSIONS
- TABLE 716 SUNTECH MEDICAL, INC.: COMPANY OVERVIEW
- TABLE 717 SUNTECH MEDICAL, INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 718 SUNTECH MEDICAL, INC.: PRODUCT LAUNCHES
- TABLE 719 SUNTECH MEDICAL, INC.: EXPANSIONS
- TABLE 720 LEADING EDGE VETERINARY EQUIPMENT: COMPANY OVERVIEW
- TABLE 721 LEADING EDGE VETERINARY EQUIPMENT: PRODUCTS/SOLUTIONS/ SERVICES OFFERED
- TABLE 722 EICKEMEYER VETERINARY EQUIPMENT LTD.: COMPANY OVERVIEW
- TABLE 723 EICKEMEYER VETERINARY EQUIPMENT LTD.: PRODUCTS/SOLUTIONS/ SERVICES OFFERED
- TABLE 724 NONIN MEDICAL, INC.: COMPANY OVERVIEW
- TABLE 725 NONIN MEDICAL, INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 726 NONIN MEDICAL, INC.: DEALS
- TABLE 727 DIGICARE BIOMEDICAL: COMPANY OVERVIEW
- TABLE 728 DIGICARE BIOMEDICAL: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 729 BIONET CO., LTD.: COMPANY OVERVIEW
- TABLE 730 BIONET CO., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 731 BIONET CO., LTD.: OTHER DEVELOPMENTS
- TABLE 732 EDAN INSTRUMENTS, INC.: COMPANY OVERVIEW
- TABLE 733 EDAN INSTRUMENTS, INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 734 EDAN INSTRUMENTS, INC.: EXPANSIONS
- TABLE 735 SHENZHEN COMEN MEDICAL INSTRUMENTS CO., LTD.: COMPANY OVERVIEW
- TABLE 736 SHENZHEN COMEN MEDICAL INSTRUMENTS CO., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 737 SHENZHEN COMEN MEDICAL INSTRUMENTS CO., LTD.: EXPANSIONS
- TABLE 738 GUANGDONG BIOLIGHT MEDITECH CO., LTD.: COMPANY OVERVIEW
- TABLE 739 GUANGDONG BIOLIGHT MEDITECH CO., LTD.: PRODUCTS/SOLUTIONS/ SERVICES OFFERED
- TABLE 740 VETLAND MEDICAL SALES & SERVICES, LLC.: COMPANY OVERVIEW
- TABLE 741 VETLAND MEDICAL SALES & SERVICES LLC.: PRODUCTS/SOLUTIONS/ SERVICES OFFERED
- TABLE 742 BURTONS MEDICAL EQUIPMENT LTD.: COMPANY OVERVIEW
- TABLE 743 BURTONS MEDICAL EQUIPMENT LTD.: PRODUCTS/SOLUTIONS/ SERVICES OFFERED
- TABLE 744 BURTONS MEDICAL EQUIPMENT LTD.: DEALS
- TABLE 745 AVANTE ANIMAL HEALTH: COMPANY OVERVIEW
- TABLE 746 AVANTE ANIMAL HEALTH: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 747 SINO-HERO: COMPANY OVERVIEW
- TABLE 748 DISPOMED LTD.: COMPANY OVERVIEW
- TABLE 749 BMV ANIMAL TECHNOLOGY CO., LTD.: COMPANY OVERVIEW
- TABLE 750 SHENZHEN MED-LINK ELECTRONICS TECH CO., LTD.: COMPANY OVERVIEW
- TABLE 751 VETSPECS, INC.: COMPANY OVERVIEW
- TABLE 752 CONTEC MEDICAL SYSTEMS CO., LTD.: COMPANY OVERVIEW
- TABLE 753 INFINIUM MEDICAL, INC.: COMPANY OVERVIEW
- TABLE 754 DEXTRONIX, INC.: COMPANY OVERVIEW
- TABLE 755 MASIMO CORPORATION: COMPANY OVERVIEW
- TABLE 756 MEDTRONIC: COMPANY OVERVIEW
- TABLE 757 ICU MEDICAL, INC.: COMPANY OVERVIEW
- TABLE 758 RESEARCH ASSUMPTIONS
- TABLE 759 RISK ASSESSMENT ANALYSIS
List of Figures
- FIGURE 1 VETERINARY MONITORING EQUIPMENT MARKET SEGMENTATION
- FIGURE 2 MARKET SCENARIO
- FIGURE 3 VETERINARY MONITORING EQUIPMENT MARKET, 2024-2031
- FIGURE 4 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN VETERINARY MONITORING EQUIPMENT MARKET, 2023-2025
- FIGURE 5 DISRUPTIONS INFLUENCING GROWTH OF VETERINARY MONITORING EQUIPMENT MARKET
- FIGURE 6 HIGH-GROWTH SEGMENTS IN VETERINARY MONITORING EQUIPMENT MARKET, 2026-2031
- FIGURE 7 ASIA PACIFIC TO REGISTER HIGHEST CAGR, IN TERMS OF VALUE, DURING FORECAST PERIOD
- FIGURE 8 CONTINUOUS TECHNOLOGICAL ADVANCEMENTS, SHIFT TOWARD REMOTE MONITORING, AND RISING PET OWNERSHIP TO DRIVE MARKET
- FIGURE 9 VETERINARY GENERAL PRACTICE SEGMENT AND REST OF ASIA PACIFIC ACCOUNTED FOR LARGEST MARKET SHARES IN 2025
- FIGURE 10 CHINA TO REGISTER HIGHEST GROWTH RATE FROM 2026 TO 2031
- FIGURE 11 VETERINARY MONITORING EQUIPMENT MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 12 US: PET OWNERSHIP, BY TYPE, 2024-2025 (MILLION)
- FIGURE 13 US: PET INDUSTRY EXPENDITURE, 2016-2025 (USD BILLION)
- FIGURE 14 VETERINARY MONITORING EQUIPMENT MARKET: PORTER'S FIVE FORCES ANALYSIS
- FIGURE 15 VETERINARY MONITORING EQUIPMENT MARKET: SUPPLY CHAIN ANALYSIS
- FIGURE 16 VETERINARY MONITORING EQUIPMENT MARKET: VALUE CHAIN ANALYSIS
- FIGURE 17 VETERINARY MONITORING EQUIPMENT MARKET: ECOSYSTEM ANALYSIS
- FIGURE 18 AVERAGE SELLING PRICE OF KEY PLAYERS, BY PRODUCT, 2025 (USD)
- FIGURE 19 AVERAGE SELLING PRICE, BY REGION, 2025 (USD)
- FIGURE 20 REVENUE SHIFT AND NEW REVENUE POCKETS FOR VETERINARY MONITORING EQUIPMENT MARKET
- FIGURE 21 INVESTMENT AND FUNDING SCENARIO, 2019-2025
- FIGURE 22 NUMBER OF PATENTS APPLIED AND GRANTED, 2015-2026
- FIGURE 23 VETERINARY MONITORING EQUIPMENT MARKET: AI USE CASES
- FIGURE 24 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR VETERINARY MONITORING EQUIPMENT, BY END USER
- FIGURE 25 KEY BUYING CRITERIA FOR VETERINARY MONITORING EQUIPMENT, BY END USER
- FIGURE 26 NORTH AMERICA: VETERINARY MONITORING EQUIPMENT MARKET SNAPSHOT
- FIGURE 27 ASIA PACIFIC: VETERINARY MONITORING EQUIPMENT MARKET SNAPSHOT
- FIGURE 28 REVENUE ANALYSIS OF KEY PLAYERS IN VETERINARY MONITORING EQUIPMENT MARKET, 2023-2025
- FIGURE 29 GLOBAL: VETERINARY MONITORING EQUIPMENT MARKET SHARE, 2025
- FIGURE 30 US: VETERINARY MONITORING EQUIPMENT MARKET SHARE, 2025
- FIGURE 31 EUROPE: VETERINARY MONITORING EQUIPMENT MARKET SHARE, 2025
- FIGURE 32 VETERINARY MONITORING EQUIPMENT MARKET: BRAND/PRODUCT COMPARATIVE ANALYSIS
- FIGURE 33 VETERINARY MONITORING EQUIPMENT MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- FIGURE 34 VETERINARY MONITORING EQUIPMENT MARKET: COMPANY FOOTPRINT
- FIGURE 35 VETERINARY MONITORING EQUIPMENT MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
- FIGURE 36 EV/EBITDA OF KEY VENDORS
- FIGURE 37 YEAR-TO-DATE (YTD) PRICE TOTAL RETURN AND 5-YEAR STOCK BETA OF KEY VENDORS
- FIGURE 38 SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD.: COMPANY SNAPSHOT (2025)
- FIGURE 39 EDAN INSTRUMENTS, INC.: COMPANY SNAPSHOT (2025)
- FIGURE 40 GUANGDONG BIOLIGHT MEDITECH CO., LTD.: COMPANY SNAPSHOT (2025)
- FIGURE 41 VETERINARY MONITORING EQUIPMENT MARKET: RESEARCH DESIGN
- FIGURE 42 BREAKDOWN OF PRIMARY INTERVIEWS: SUPPLY-SIDE AND DEMAND-SIDE PARTICIPANTS
- FIGURE 43 BREAKDOWN OF PRIMARY INTERVIEWS: BY COMPANY TYPE, DESIGNATION, AND REGION
- FIGURE 44 BREAKDOWN OF PRIMARY INTERVIEWS (DEMAND SIDE): BY END USER, DESIGNATION, AND REGION
- FIGURE 45 RESEARCH METHODOLOGY: HYPOTHESIS BUILDING
- FIGURE 46 MARKET SIZE APPROACH - REVENUE SHARE ANALYSIS
- FIGURE 47 REVENUE SHARE ANALYSIS ILLUSTRATION: SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD. (2025)
- FIGURE 48 TOP-DOWN APPROACH
- FIGURE 49 BOTTOM-UP APPROACH
- FIGURE 50 DEMAND-SIDE APPROACH
- FIGURE 51 CAGR PROJECTIONS FROM ANALYSIS OF DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES OF VETERINARY MONITORING EQUIPMENT MARKET (2026-2031)
- FIGURE 52 CAGR PROJECTIONS: SUPPLY-SIDE ANALYSIS
- FIGURE 53 DATA TRIANGULATION METHODOLOGY


