

 |
市場調查報告書
商品編碼
2129358
全球疊層匯流排市場:依導體材料、絕緣材料、電壓、電流、應用、終端用戶產業及地區分類-預測至2035年Laminated Busbar Market by Conductor Material (Copper, Aluminium), Insulation Material, Voltage, Current Rating, Application, End User Industry (Utilities & Grid Infrastructure, Industrial Equipment, Data Centers), and Region - Global Forecast to 2035 |
||||||

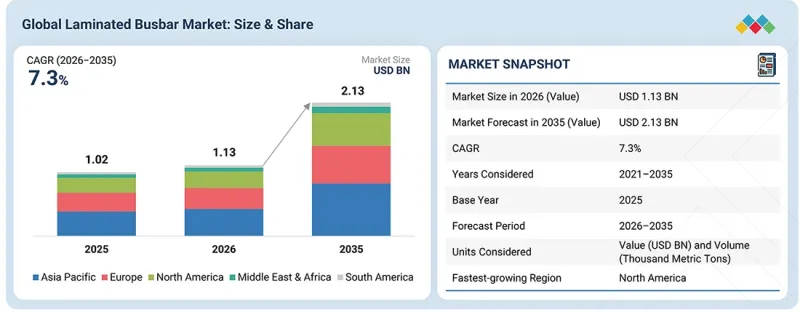
全球疊層匯流排市場預計將從 2025 年的 10.2 億美元成長到 2026 年的 11.3 億美元,到 2035 年達到 21.3 億美元,複合年成長率為 7.3%。
這一市場成長的主要驅動力是交通運輸和工業系統的電氣化程度不斷提高,以及對可再生能源、儲能和數位基礎設施的持續投資。這些趨勢導致電力轉換器、逆變器、電池系統和其他需要高效可靠電氣互連解決方案的高功率設備的應用日益廣泛。
| 調查範圍 | |
|---|---|
| 調查期 | 2021-2035 |
| 基準年 | 2025 |
| 預測期 | 2026-2035 |
| 計算單位 | 數量(千公噸) |
| 部分 | 依導體材料、絕緣材料、電壓、電流、應用、最終用戶產業、地區 |
| 目標區域 | 亞太地區、北美地區、歐洲、中東和非洲地區、南美地區 |
全球工業、電動車和資料中心對電力需求的普遍成長,進一步推動了電力消耗量電力基礎設施的擴張。
此外,隨著設備製造商日益重視提高功率密度、系統小型化和提升電氣性能,全球多層匯流排市場正經歷顯著的變革。先進電力電子技術的廣泛應用,推動了對客製化多層匯流排的需求成長,這些母線旨在滿足電流容量、溫度控管、隔離和設備配置等方面的特定要求。製造商正從設計階段開始加強與原始設備製造商 (OEM) 和系統開發商的合作,使工程能力和針對特定應用的產品開發成為關鍵的競爭優勢。同時,可再生能源發電、電動車、工業電氣化以及資料中心容量的持續擴張,正在加速向更複雜的電力架構轉型,為多層匯流排製造商創造了持續的商機。
“到 2025 年,環氧粉末塗料將在全球層壓匯流排市場(按絕緣材料分類)中佔據第二大佔有率。”
環氧粉末塗料憑藉其優異的介電性能、高機械強度以及耐熱、耐化學腐蝕和耐惡劣工況的特性,預計到2025年將佔據全球疊層匯流排市場第二大佔有率。該材料具有可靠的電氣絕緣性能,可應用於形狀複雜的匯流排,因此適用於各種高功率應用。其成本績效和成熟的製造流程也進一步推動了其在工業設備、電力電子、能源基礎設施、交通運輸和其他電氣系統中的廣泛應用。
此細分市場的發展也得益於對緊湊型、高功率密度電氣架構日益成長的需求,在這些架構中,絕緣性能和可靠性至關重要。環氧粉末塗層匯流排可提供持久的絕緣保護,同時支援高效的系統整合和空間最佳化。包括 Mersen 和 Rogers 在內的領先疊層匯流排供應商,為嚴苛的應用提供環氧粉末塗層匯流排解決方案,並在交通運輸、工業、電信和配電設備領域建立了強大的市場地位。
“到2025年,低壓領域將佔據最大的市場佔有率。”
2025年,低壓多層匯流排在全球多層匯流排市場中佔據最大佔有率,這得益於其在各種電力電子和電氣設備中的廣泛應用。這些匯流排廣泛應用於電動車、電池系統、可再生能源逆變器、工業設備、資料中心電源匯流排以及其他低電壓應用領域。它們具有高效的電流分配、低電感、結構緊湊和溫度控管優異等優點,尤其適用於對空間最佳化和電氣性能要求極高的設備。
電氣化交通、分散式能源系統、電池儲能和數位基礎設施的持續擴張,進一步提升了對低壓堆疊式匯流排的需求。功率變換器、逆變器、電池組和高密度電力電子設備的日益普及,催生了大量需要緊湊型、客製化電氣互連解決方案的應用。因此,低壓堆疊式匯流排在全球市場持續主導地位的關鍵因素在於其在多個終端用戶行業的廣泛適用性。
主要調查主題細分:
為了收集和檢驗重要的定性和定量信息,並評估未來市場前景,我們對主要行業相關人員、專家、主要市場參與者的高管以及行業顧問進行了深入訪談。初步訪談的具體情況如下:
全球疊片匯流排市場主要由成熟的全球領導企業主導。全球疊片匯流排市場的主要參與者包括安費諾公司(美國)、美德電子公司(美國)、梅爾森集團(法國)、羅傑斯公司(美國)、新王科技Group Limited(中國)、株洲中車時代電氣(中國)和良電化成(日本)。
調查範圍:
本報告依導電材料(銅、鋁、銅鋁複合材料)、絕緣材料(聚酯、聚醯亞胺、環氧粉末塗料、Nomex)、電壓(低壓、中壓、高壓)、額定電流(小於250 A、250–1,000 A、1,001–3,000 A、大於3,000 A、大於3,000 A、大於3,000 A、大於3,000 A、大於3,000 A、大於3,000 A、大於3,000 A、大於3,000 A、大於3,000 A、大於3,000 A、大於3,000 A、大於3,000 A、大於3,000 A、大於3,000 A、大於3,000 A、 A)、應用(開關設備和配電、電力轉換系統、逆變器和轉換器、UPS和電池組、母線槽、發電系統、電動汽車充電器、直流配電)、終端用戶行業(公共產業和電網基礎設施、工業設備、資料中心(企業級、託管、超大規模和AI/HPC、邊緣運算)、商業和住宅建築、電池能源儲存系統(BESS)、可再生能源、鐵路和交通運輸、電動汽車和充電基礎設施、其他(電信、航太和國防、醫療設備))以及地區進行細分。本報告對市場促進因素、限制因素、機會和挑戰進行了定性和定量分析。
購買本報告的主要好處
本報告精心設計,旨在惠及全球疊層匯流排市場的所有相關人員,從行業領導企業到新參與企業。報告提供可靠的整體市場及各細分市場的銷售預測。這些數據對相關人員而言是寶貴的資訊來源,幫助他們全面了解競爭格局,並制定有效的市場策略。此外,本報告還幫助相關人員掌握市場現狀,深入洞察市場促進因素、限制因素、挑戰和成長機會。透過運用這些洞察,相關人員可以做出明智的決策,並隨時掌握瞬息萬變的全球疊層匯流排市場的最新動態。
- 關鍵因素分析:我們將分析促進因素(對安全可靠的配電系統的需求不斷成長,對可再生能源的重視)、阻礙因素(疊層匯流排初始成本高,來自本地公司和非正規部門的競爭日益激烈)、機遇(電力基礎設施老化和電力需求不斷成長,高壓直流輸電技術的應用日益廣泛,絕緣材料的不斷進步)以及挑戰(原料價格波動,特別是銅價波動,以及不當處置對環境的影響),以闡明它們對全球疊層匯流排市場成長的影響。
- 產品開發與創新:全球多層匯流排市場的產品開發日益聚焦於高功率密度、低電感、更優異的熱性能以及組件的進一步整合。製造商正在為電動車、電池能源儲存系統、可再生能源轉換器、工業驅動器和資料中心電力基礎設施等應用開發客製化的匯流排設計。創新也延伸至先進介電材料、用於寬能隙半導體應用的高溫匯流排以及滿足更高電流和電壓需求的緊湊型多層設計。例如,Mersen 提供專為高溫動作溫度設計的高溫匯流排,以及整合冷卻、熔斷器和監控感測器等功能的匯流排組件。
- 市場趨勢:受電動車、可再生能源、電池儲能、工業自動化和資料中心基礎設施快速發展的推動,全球多層匯流排市場正朝著更高效能、更緊湊、更針對特定應用的電氣互連解決方案方向發展。不斷提高的功率密度要求和先進電力電子技術的日益普及,催生了對具有更佳溫度控管、更低電感、更強絕緣性和更高載流能力的多層匯流排的需求。這促使製造商擴展其工程和生產能力,並與原始設備製造商 (OEM) 更緊密地合作,為特定設備架構開發客製化解決方案。同時,導體材料、絕緣技術、多層設計和自動化製造技術的進步,也為開發更有效率、更可靠的匯流排系統提供了支援。因此,市場發展正從傳統的電氣互連轉向整合、緊湊型、技術先進的多層匯流排解決方案,旨在滿足全球終端用戶產業不斷變化的需求。
- 市場多元化:全球多層匯流排市場正日益多元化,涵蓋公共產業和電網基礎設施、電動車、可再生能源、儲能、工業應用和資料中心等多個工業領域,降低了對特定應用領域的依賴。電動車 (EV) 生產、電池製造、可再生能源設施和儲能的快速發展,催生了對緊湊高效的電氣連接解決方案的新需求。同時,工業自動化和數位基礎設施投資的不斷增加,也拓寬了多層匯流排的應用範圍。這種多元化促使製造商開發具有不同額定電流、導體材料、絕緣系統和溫度控管功能的特定應用產品。因此,市場機會正在電力電子和電氣設備等廣泛領域不斷擴展,為全球多層匯流排製造商創造了更多元化的需求基礎。
競爭格局評估:我們對全球疊層匯流排市場主要參與者的市場地位、成長策略和服務產品進行了全面評估。這些主要參與者包括:安費諾公司(美國)、美德電子公司(美國)、默森集團(法國)、羅傑斯公司(美國)、新王科技Group Limited(中國)、株洲中車時代電氣有限公司(中國)和龍電化成株式會社(日本)。本分析深入剖析了這些主要參與者的競爭定位、市場成長策略以及在全球疊層匯流排市場的市場佔有率。
目錄
第1章:引言
第2章執行摘要
第3章重要考察
第4章 市場概覽
- 市場動態
- 促進因素
- 抑制因子
- 機會
- 任務
- 未滿足的需求和未開發的領域
- 相互關聯的市場與跨產業機遇
- 一級/二級/三級公司的策略性舉措
第5章 產業趨勢
- 波特五力分析
- 宏觀經濟展望
- 價值鏈分析
- 生態系分析
- 價格分析
- 貿易分析
- 2026-2027 年主要會議和活動
- 影響客戶業務的趨勢/顛覆性變革
- 案例研究分析
- 投資和資金籌措場景
- 美國關稅的影響-全球層壓匯流排市場
第6章:技術進步、人工智慧的影響、專利、創新與未來應用
- 主要技術
- 互補技術
- 鄰近技術
- 技術/產品藍圖
- 專利分析
- 未來應用
- 人工智慧/生成式人工智慧對疊層匯流排市場的影響
- 成功案例和實際應用
第7章:監理情勢與永續性舉措
- 當地法規和合規性
- 對永續性的承諾
- 監理政策對永續性舉措的影響
- 認證、標籤檢視和環境標準
第8章:顧客趨勢與購買行為
- 決策流程
- 採購過程中的關鍵相關人員及其評估標準
- 實施障礙和內部挑戰
- 各個終端用戶產業尚未滿足的需求
- 市場盈利
第9章:疊層匯流排市場(依導體材料分類)
- 銅
- 鋁
- 銅鋁複合材料
第10章:疊層匯流排市場(依絕緣材料分類)
- 聚酯纖維
- 聚醯亞胺
- 環氧粉末塗料
- 諾梅克斯
第11章:多層匯流排市場(依電壓等級分類)
- 低的
- 中等的
第12章:多層匯流排市場(依電流)
- 小於250安培
- 250~1,000A
- 1,001-3,000 A
- 3000 安培或以上
第13章:疊層匯流排市場(依應用領域分類)
- 開關設備及配電
- 功率轉換系統
- 逆變器和轉換器
- UPS和電池組
- 公車專用道
- 發電機系統
- 電動汽車充電器
- 直流配電
第14章:疊層匯流排市場(依應用領域分類)
- 公共產業及電網基礎設施
- 工業設備
- 資料中心
- 電動車和充電基礎設施
- 電池能源儲存系統
- 可再生能源
- 商業建築及住宅建築
- 鐵路和交通運輸
- 其他
第15章:層壓匯流排市場(依地區分類)
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 其他
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 中東和非洲
- GCC
- 南非
- 其他
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他
第16章 競爭格局
- 概述
- 2023-2026年主要參與企業的競爭策略/優勢
- 2025年市佔率分析
- 2021-2025年收入分析
- 企業估值矩陣:主要公司,2025 年
- 公司估值矩陣:新創企業/中小企業,2025 年
- 企業估值和財務指標
- 品牌對比
- 競爭格局
第17章:公司簡介
- 主要參與企業
- AMPHENOL CORPORATION
- METHODE ELECTRONICS
- MERSEN
- ROGERS CORPORATION
- SUN.KING TECHNOLOGY GROUP LIMITED
- ZHUZHOU CRRC TIMES ELECTRIC CO., LTD.
- RYODEN KASEI CO., LTD.
- EAE ELECTRIC
- SHANGHAI EAGTOP ELECTRONIC TECHNOLOGY CO., LTD.
- SHENZHEN BUSBAR SCI-TECH DEVELOPMENT CO., LTD.
- STORM POWER COMPONENTS
- SUZHOU WEST DEANE MACHINERY INC.
- ELECTRONIC SYSTEMS PACKAGING LLC
- RAYCHEM RPG PRIVATE LIMITED
- MOLEX
- SHENZHEN WOER ELECTRIC TECHNOLOGY CO., LTD.
- 其他公司
- ZHEJIANG RHI ELECTRIC CO., LTD.
- SEGUE ELECTRONICS, INC.
- KINTO GROUP
- TULING
- CARSAI PRECISION PARTS
- ERIE INDUSTRIAL PRODUCTS
- XIAMEN APOLLO STAMPING WELDING TECHNOLOGY CO., LTD.
- XIAMEN NEER ELECTRONIC TECHNOLOGY CO., LTD.
- DRAMETAL
第18章:調查方法
第19章附錄
The global laminated busbar market is estimated to grow from USD 1.02 billion in 2025 to USD 1.13 billion in 2026 and reach USD 2.13 billion by 2035, registering a CAGR of 7.3%. The growth of the market is primarily driven by the rising electrification of transportation and industrial systems, along with continued investments in renewable energy, energy storage, and digital infrastructure. These developments are increasing the deployment of power converters, inverters, battery systems, and other high-power equipment that require efficient and reliable electrical interconnection solutions.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2021-2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Units Considered | Value, Volume ( Thousand Metric Tons) |
| Segments | by Conductor Material, Insulation Material, Voltage, Current Rating, Application, End User Industry, Region |
| Regions covered | Asia Pacific, North America, Europe, Middle East & Africa, South America |
The broader growth in global electricity demand from industry, electric vehicles, and data centers further supports the expansion of power-intensive electrical infrastructure.
The global laminated busbar market is also undergoing a significant transformation as equipment manufacturers increasingly prioritize higher power density, system miniaturization, and improved electrical performance. The growing adoption of advanced power electronics is creating greater demand for customized laminated busbars designed to meet specific requirements related to current carrying capacity, thermal management, insulation, and equipment configuration. Manufacturers are increasingly collaborating with OEMs and system developers at the design stage, making engineering capabilities and application-specific product development important competitive factors. At the same time, continued expansion of renewable generation, electric mobility, industrial electrification, and data center capacity is accelerating the transition toward more sophisticated power architectures, creating sustained opportunities for laminated busbar manufacturers.
"Epoxy powder coating held the second-largest share of the global laminated busbar market, by insulation material, in 2025."
Epoxy powder coating held the second-largest share of the global laminated busbar market in 2025, owing to its strong dielectric properties, high mechanical strength, and resistance to heat, chemicals, and harsh operating conditions. The material provides reliable electrical insulation and can be applied to complex busbar geometries, making it suitable for a wide range of high-power applications. Its cost-effectiveness and established manufacturing processes further support its widespread adoption across industrial equipment, power electronics, energy infrastructure, transportation, and other electrical systems.
The segment is also supported by the increasing demand for compact and high-power-density electrical architectures, where insulation performance and reliability are critical. Epoxy powder-coated busbars can provide durable dielectric protection while supporting efficient system integration and space optimization. Major laminated busbar suppliers, including Mersen and Rogers, offer epoxy powder-coated busbar solutions for demanding applications, highlighting their established role across transportation, industrial, communication, and power-distribution equipment.
"Low voltage segment accounted for the largest market share in 2025."
Low voltage laminated busbars accounted for the largest share of the global laminated busbar market in 2025, supported by their extensive adoption across a broad range of power-electronic and electrical equipment. These busbars are widely used in electric vehicles, battery systems, renewable energy inverters, industrial equipment, data center power systems, and other applications that operate within the low voltage range. Their ability to provide efficient current distribution, low inductance, compact design, and effective thermal management makes them particularly suitable for equipment where space optimization and electrical performance are critical.
The continued expansion of electrified transportation, distributed energy systems, battery energy storage, and digital infrastructure is further strengthening demand for low-voltage laminated busbars. Increasing deployment of power converters, inverters, battery packs, and high-density power electronics is creating a large volume of applications requiring compact and customized electrical interconnection solutions. This broad applicability across multiple end-user industries supports the continued dominance of the low voltage segment in the global laminated busbar market.
Breakdown of Primaries:
In-depth interviews with key industry participants, subject-matter experts, C-level executives of key market players, and industry consultants, among other experts, were conducted to obtain and verify critical qualitative and quantitative information, as well as to assess future market prospects. The primary interviews were distributed as follows:
By Company Type: Tier 1 - 40%, Tier 2 - 35%, and Tier 3 - 25%
By Designation: C-Level Executives - 30%, Directors - 25%, and Managers - 45%
By Region: Asia Pacific - 35%, North America - 25%, Middle East & Africa - 12%, Europe - 20% and South America - 4%,
Notes: Managers include sales managers, production managers, and regional managers.
Tier 1 company: revenue >USD 5 billion; tier 2 company: revenue between USD 1 and USD 5 billion; and tier 3 company: revenue <USD 1 billion in 2025
Well-established global leaders predominantly govern the global laminated busbar market. Notable players in the global laminated busbar market include Amphenol Corporation (US), Methode Electronics, Inc. (US), Mersen Group (France), Rogers Corporation (US), Sun.King Technology Group Limited (China), Zhuzhou CRRC Times Electric Co., Ltd. (China), and Ryoden Kasei Co., Ltd. (Japan).
Research Coverage:
The report offers a detailed definition, description, and forecast of the global laminated busbar market, focusing on conductor material (copper, aluminum, copper-aluminum hybrid), insulation material (polyester, polyimide, epoxy powder coating, Nomex), voltage (low voltage, medium voltage, and high voltage), current rating (Below 250 A, 250-1,000 A, 1,001-3,000 A, above 3,000 A ), application (switchgear & power distribution, power conversion systems, inverters & converters, UPS & battery packs, busways, generator systems, EV chargers, DC power distribution), end user industry (utilities & grid infrastructure, industrial equipment, data centers (enterprise, colocation, hyperscale & AI/HPC, edge), commercial & residential buildings, battery energy storage systems (BESS), renewable energy, rail & transportation, electric mobility & charging infrastructure, others (telecom, aerospace & defense, medical equipment)), and region. It provides a qualitative and quantitative analysis of market drivers, restraints, opportunities, and challenges.
Key Benefits of Buying the Report
The report is thoughtfully designed to benefit both established industry leaders and newcomers in the global laminated busbar market. It provides reliable revenue forecasts for the entire market as well as its individual sub-segments. This data is a valuable resource for stakeholders, enabling them to gain a comprehensive understanding of the competitive landscape and formulate effective market strategies for their businesses. Furthermore, the report serves as a channel for stakeholders to grasp the current state of the market, providing essential insights into market drivers, limitations, challenges, and growth opportunities. By incorporating these insights, stakeholders can make well-informed decisions and stay informed about the constantly evolving dynamics of the global laminated busbar market.
- Analysis of key: drivers (Growing demand for safe and secure electrical distribution systems, Strong emphasis on renewables), restraints (High initial cost of laminated busbars, Growing competition from local firms or unorganized sector), opportunities (Aging electrical infrastructure and rising electricity demand, Increasing adoption of HVDC technology, Ongoing advancements in insulation materials), and challenges (Volatility in raw material prices, especially copper, environmental impact of improper disposal) influencing the growth of global laminated busbar market.
- Product Development/Innovation: Product development in the global laminated busbar market is increasingly focused on higher power density, lower inductance, improved thermal performance, and greater component integration. Manufacturers are developing customized and application-specific busbar designs for electric vehicles, battery energy storage systems, renewable energy converters, industrial drives, and data center power infrastructure. Innovation is also extending toward advanced dielectric materials, high-temperature busbars for wide-bandgap semiconductor applications, and compact multilayer designs that support higher current and voltage requirements. Mersen, for example, offers high-temperature busbars designed for elevated operating temperatures and integrated busbar assemblies incorporating functions such as cooling, fuses, and monitoring sensors
- Market Development: The global laminated busbar market is evolving toward higher-performance, compact, and application-specific electrical interconnection solutions, driven by the rapid expansion of electric mobility, renewable energy, battery energy storage, industrial automation, and data center infrastructure. Increasing power density requirements and the growing use of advanced power electronics are creating demand for laminated busbars with improved thermal management, lower inductance, enhanced insulation performance, and greater current-carrying capabilities. This is encouraging manufacturers to expand their engineering and production capabilities while working more closely with OEMs to develop customized solutions for specific equipment architectures. At the same time, advancements in conductor materials, insulation technologies, multilayer designs, and automated manufacturing are supporting the development of more efficient and reliable busbar systems. Market development is therefore shifting from conventional electrical interconnection toward integrated, compact, and technologically advanced laminated busbar solutions designed to meet the evolving requirements of global end-use industries.
- Market Diversification: The global laminated busbar market is becoming increasingly diversified across utilities & grid infrastructure, electric mobility, renewable energy, energy storage, industrial, and data center industries, reducing its dependence on any single application area. The rapid expansion of EV production, battery manufacturing, renewable power installations, and energy storage is creating new demand for compact and efficient electrical interconnection solutions. At the same time, increasing investments in industrial automation and digital infrastructure are broadening the application base for laminated busbars. This diversification is encouraging manufacturers to develop application-specific products with varying current ratings, conductor materials, insulation systems, and thermal management capabilities. As a result, market opportunities are expanding across a wider range of power-electronic and electrical equipment, creating a more diversified demand base for laminated busbar manufacturers globally
Competitive Assessment: A comprehensive evaluation has been conducted to scrutinize the market presence, growth strategies, and service offerings of key players in the global laminated busbar market. These prominent companies include Amphenol Corporation (US), Methode Electronics, Inc. (US), Mersen Group (France), Rogers Corporation (US), Sun.King Technology Group Limited (China), Zhuzhou CRRC Times Electric Co., Ltd. (China), Ryoden Kasei Co., Ltd. (Japan), and several others. This analysis provides in-depth insights into the competitive positions of these major players, their approaches to driving market growth, top companies' market shares within the global laminated busbar market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKETS COVERED AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 UNIT CONSIDERED
- 1.6 LIMITATIONS
- 1.7 STAKEHOLDERS
- 1.8 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN LAMINATED BUSBAR MARKET
- 2.4 HIGH GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN LAMINATED BUSBAR MARKET
- 3.2 LAMINATED BUSBAR MARKET, BY REGION
- 3.3 LAMINATED BUSBAR MARKET IN ASIA PACIFIC, BY CONDUCTOR MATERIAL AND COUNTRY
- 3.4 LAMINATED BUSBAR MARKET, BY VOLTAGE
- 3.5 LAMINATED BUSBAR MARKET, BY INSULATION MATERIAL
- 3.6 LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY
- 3.7 LAMINATED BUSBAR MARKET, BY REGION
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Mounting adoption of power distribution systems and electric vehicles
- 4.2.1.2 Increasing investment in renewable energy storage infrastructure
- 4.2.1.3 Burgeoning demand for compact, energy-efficient, and reliable electrical devices
- 4.2.2 RESTRAINTS
- 4.2.2.1 High initial costs and raw material price volatility
- 4.2.2.2 Complex manufacturing process
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Rapid expansion of EV charging infrastructure
- 4.2.3.2 Increasing development of data centers and AI infrastructure
- 4.2.4 CHALLENGES
- 4.2.4.1 Issues in maintaining thermal and electrical reliability at high power densities
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 INTENSITY OF COMPETITIVE RIVALRY
- 5.1.2 THREAT OF NEW ENTRANTS
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 THREATS OF SUBSTITUTES
- 5.2 MACROECONOMIC OUTLOOK
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST
- 5.2.3 TRENDS IN GLOBAL ELECTRICAL EQUIPMENT & POWER DISTRIBUTION INDUSTRY
- 5.2.4 TRENDS IN GLOBAL DATA CENTERS INDUSTRY
- 5.3 VALUE CHAIN ANALYSIS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 AVERAGE SELLING PRICE TREND OF LAMINATED BUSBARS, BY VOLTAGE, 2022-2025
- 5.5.2 AVERAGE SELLING PRICE TREND OF LAMINATED BUSBARS, BY REGION, 2022-2025
- 5.6 TRADE ANALYSIS
- 5.6.1 IMPORT SCENARIO (HS CODE 853690)
- 5.6.2 EXPORT SCENARIO (HS CODE 853690)
- 5.7 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.8 TRENDS/DISRUPTION IMPACTING CUSTOMER BUSINESS
- 5.9 CASE STUDY ANALYSIS
- 5.9.1 AUTOMOTIVE CELLS COMPANY SELECTS MERSEN TO SUPPLY SMART LAMINATED BUSBARS FOR NEXT-GENERATION EV BATTERIES
- 5.9.2 MOLEX DEVELOPS LIQUID-COOLED BUSBAR SOLUTION TO ADDRESS RISING POWER AND THERMAL MANAGEMENT DEMANDS IN AI DATA CENTERS
- 5.9.3 MERSEN PARTNERS WITH F&K DELVOTEC TO DEVELOP INFINI CELL BATTERY ASSEMBLY SOLUTION FOR HIGH-SPEED EV BATTERY ASSEMBLY
- 5.10 INVESTMENT AND FUNDING SCENARIO
- 5.11 IMPACT OF US TARIFFS - GLOBAL LAMINATED BUSBAR MARKET
- 5.11.1 INTRODUCTION
- 5.11.2 KEY TARIFF RATES
- 5.11.3 PRICE IMPACT ANALYSIS
- 5.11.4 IMPACT ON COUNTRIES/REGIONS
- 5.11.4.1 US
- 5.11.4.2 Europe
- 5.11.4.3 Asia Pacific
- 5.11.5 IMPACT ON APPLICATIONS
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY TECHNOLOGIES
- 6.1.1 LOW-INDUCTANCE LAMINATED BUSBAR
- 6.1.2 ADVANCED INSULATION AND HIGH-TEMPERATURE LAMINATION
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 SIC AND GAN
- 6.2.2 ADVANCED THERMAL-MANAGEMENT AND COOLING
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 INTEGRATED DC-LINK/BUSBAR-CAPACITOR SYSTEMS
- 6.3.2 3D/EMBEDDED POWER-MODULE INTERCONNECTION
- 6.4 TECHNOLOGY/PRODUCT ROADMAP
- 6.4.1 SHORT-TERM (2026-2028) | MATERIAL DEVELOPMENT & PRODUCT ENHANCEMENT
- 6.4.2 MID-TERM (2028-2031) | HIGH-POWER DENSITY & ADVANCED POWER ELECTRONICS
- 6.4.3 LONG-TERM (2031-2035+) | SMART, INTEGRATED & NEXT-GENERATION POWER DISTRIBUTION
- 6.5 PATENT ANALYSIS
- 6.6 FUTURE APPLICATIONS
- 6.7 IMPACT OF AI/GEN AI ON LAMINATED BUSBAR MARKET
- 6.7.1 TOP USE CASES AND MARKET POTENTIAL
- 6.7.2 BEST PRACTICES FOLLOWED BY OEMS IN LAMINATED BUSBAR MARKET
- 6.7.3 CASE STUDIES RELATED TO AI/GEN AI IMPLEMENTATION IN LAMINATED BUSBAR MARKET
- 6.7.4 INTERCONNECTED ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.7.5 CLIENTS' READINESS TO ADOPT AI/GEN AI-INTEGRATED LAMINATED BUSBARS
- 6.8 SUCCESS STORIES AND REAL-WORLD APPLICATIONS
7 REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.2 SUSTAINABILITY INITIATIVES
- 7.3 IMPACT OF REGULATORY POLICIES ON SUSTAINABILITY INITIATIVES
- 7.4 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.4 UNMET NEEDS OF VARIOUS END-USE INDUSTRIES
- 8.5 MARKET PROFITABILITY
9 LAMINATED BUSBAR MARKET, BY CONDUCTOR MATERIAL
- 9.1 INTRODUCTION
- 9.2 COPPER
- 9.2.1 SUPERIOR ELECTRICAL AND THERMAL CONDUCTIVITY TO CONTRIBUTE TO SEGMENTAL GROWTH
- 9.3 ALUMINUM
- 9.3.1 LIGHTWEIGHT AND IMPROVED EFFICIENCY TO ACCELERATE SEGMENTAL GROWTH
- 9.4 COPPER-ALUMINUM HYBRID
- 9.4.1 NEED TO OPTIMIZE ELECTRICAL PERFORMANCE, WEIGHT, AND MATERIAL UTILIZATION TO FOSTER SEGMENTAL GROWTH
10 LAMINATED BUSBAR MARKET, BY INSULATION MATERIAL
- 10.1 INTRODUCTION
- 10.2 POLYESTER
- 10.2.1 COST-EFFECTIVE THIN-FILM INSULATION AND BROAD APPLICATION COMPATIBILITY TO AUGMENT SEGMENTAL GROWTH
- 10.3 POLYIMIDE
- 10.3.1 ABILITY TO OPERATE UNDER HIGHER TEMPERATURES, GREATER ELECTRICAL STRESS, AND COMPACT SYSTEM ARCHITECTURES TO FUEL SEGMENTAL GROWTH
- 10.4 EPOXY POWDER COATING
- 10.4.1 SUPERIOR SURFACE PROTECTION AND COMPACT EQUIPMENT DESIGN TO BOLSTER SEGMENTAL GROWTH
- 10.5 NOMEX
- 10.5.1 LONG-TERM THERMAL ENDURANCE AND HIGH-RELIABILITY PERFORMANCE TO CONTRIBUTE TO SEGMENTAL GROWTH
11 LAMINATED BUSBAR MARKET, BY VOLTAGE
- 11.1 INTRODUCTION
- 11.2 LOW
- 11.2.1 EXPANDING ELECTRIC MOBILITY AND BATTERY STORAGE DEPLOYMENTS TO EXPEDITE SEGMENTAL GROWTH
- 11.3 MEDIUM
- 11.3.1 RISING POWER REQUIREMENT OF DIGITAL, RENEWABLE, AND TRANSPORT INFRASTRUCTURE TO ACCELERATE SEGMENTAL GROWTH
12 LAMINATED BUSBAR MARKET, BY CURRENT
- 12.1 INTRODUCTION
- 12.2 BELOW 250 A
- 12.2.1 RISING INDUSTRIAL AUTOMATION AND DEMAND FOR COMPACT POWER ELECTRONICS TO FACILITATE SEGMENTAL GROWTH
- 12.3 250-1,000 A
- 12.3.1 INCREASING MODERNIZATION OF TELECOMMUNICATIONS AND DISTRIBUTED POWER INFRASTRUCTURE TO BOOST SEGMENTAL GROWTH
- 12.4 1,001-3,000 A
- 12.4.1 RAPID EXPANSION OF SEMICONDUCTOR MANUFACTURING AND OTHER ADVANCED INDUSTRIAL FACILITIES TO AUGMENT SEGMENTAL GROWTH
- 12.5 ABOVE 3,000 A
- 12.5.1 RISING POWER DENSITY ACROSS DATA CENTERS AND LARGE-SCALE ELECTRICAL INFRASTRUCTURE TO FUEL SEGMENTAL GROWTH
13 LAMINATED BUSBAR MARKET, BY APPLICATION
- 13.1 INTRODUCTION
- 13.2 SWITCHGEAR & POWER DISTRIBUTION
- 13.2.1 INCREASING GRID MODERNIZATION AND POWER INFRASTRUCTURE INVESTMENT TO FOSTER SEGMENTAL GROWTH
- 13.3 POWER CONVERSION SYSTEMS
- 13.3.1 RAPID EXPANSION OF RENEWABLE ENERGY AND ENERGY STORAGE INFRASTRUCTURE TO BOLSTER SEGMENTAL GROWTH
- 13.4 INVERTERS & CONVERTERS
- 13.4.1 GROWING INTEGRATION OF SOLAR SYSTEMS WITH BATTERY STORAGE TO CONTRIBUTE TO SEGMENTAL GROWTH
- 13.5 UPS & BATTERY PACKS
- 13.5.1 RISING DEVELOPMENT OF TELECOMMUNICATION INFRASTRUCTURE TO EXPEDITE SEGMENTAL GROWTH
- 13.6 BUSWAYS
- 13.6.1 EXPANDING POWER-DENSE FACILITIES TO CONTRIBUTE TO SEGMENTAL GROWTH
- 13.7 GENERATOR SYSTEMS
- 13.7.1 GROWING POWER RESILIENCE REQUIREMENTS IN DATA CENTERS AND INDUSTRIAL SECTORS TO DRIVE MARKET
- 13.8 EV CHARGERS
- 13.8.1 RAPID EXPANSION OF HIGH-POWER CHARGING INFRASTRUCTURE TO AUGMENT SEGMENTAL GROWTH
- 13.9 DC POWER DISTRIBUTION
- 13.9.1 MOUNTING DEPLOYMENT OF BATTERY-BASED SYSTEMS TO FOSTER SEGMENTAL GROWTH
14 LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY
- 14.1 INTRODUCTION
- 14.2 UTILITIES & GRID INFRASTRUCTURE
- 14.2.1 RAPID MODERNIZATION AND EXPANSION OF TRANSMISSION AND DISTRIBUTION NETWORKS TO BOOST SEGMENTAL GROWTH
- 14.3 INDUSTRIAL EQUIPMENT
- 14.3.1 RISING ELECTRIFICATION AND POWER DENSITY OF INDUSTRIAL MACHINERY TO ACCELERATE SEGMENTAL GROWTH
- 14.4 DATA CENTERS
- 14.4.1 INCREASING COMPUTE DENSITY AND AI INFRASTRUCTURE INVESTMENT TO EXPEDITE SEGMENTAL GROWTH
- 14.5 ELECTRIC MOBILITY & CHARGING INFRASTRUCTURE
- 14.5.1 EXPANDING EV FLEETS, HIGHER-POWER CHARGING, AND ELECTRIFIED TRANSPORT ARCHITECTURES TO FOSTER SEGMENTAL GROWTH
- 14.6 BATTERY ENERGY STORAGE SYSTEM
- 14.6.1 GROWING SCALE AND POWER DENSITY OF BATTERY SYSTEMS TO ACCELERATE SEGMENTAL GROWTH
- 14.7 RENEWABLE ENERGY
- 14.7.1 INCREASING SOLAR PV CAPACITY ADDITIONS AND INVERTER-BASED POWER GENERATION TO CONTRIBUTE TO SEGMENTAL GROWTH
- 14.8 COMMERCIAL & RESIDENTIAL BUILDINGS
- 14.8.1 RISING ELECTRIFICATION AND POWER-MANAGEMENT REQUIREMENTS OF BUILDINGS TO FUEL SEGMENTAL GROWTH
- 14.9 RAIL & TRANSPORTATION
- 14.9.1 CONTINUED TRANSITION TOWARD ELECTRIFIED SYSTEMS TO EXPEDITE SEGMENTAL GROWTH
- 14.10 OTHERS
15 LAMINATED BUSBAR MARKET, BY REGION
- 15.1 INTRODUCTION
- 15.2 ASIA PACIFIC
- 15.2.1 CHINA
- 15.2.1.1 Large-scale EV production and rapid energy storage deployment to boost market growth
- 15.2.2 INDIA
- 15.2.2.1 Accelerating power-capacity additions strengthen demand for high-current distribution and conversion systems
- 15.2.3 JAPAN
- 15.2.3.1 Increasing electrification and investment in semiconductor and advanced electronics manufacturing to drive market
- 15.2.4 AUSTRALIA
- 15.2.4.1 Rapid deployment of utility-scale battery storage systems to expedite market growth
- 15.2.5 SOUTH KOREA
- 15.2.5.1 Rising advanced semiconductor manufacturing and AI computing infrastructure development to fuel market growth
- 15.2.6 REST OF ASIA PACIFIC
- 15.2.1 CHINA
- 15.3 EUROPE
- 15.3.1 GERMANY
- 15.3.1.1 Substantial grid expansion, industrial automation, and energy-transition investments to foster market growth
- 15.3.2 UK
- 15.3.2.1 Increasing grid modernization, renewable-energy integration, and data center growth to drive market
- 15.3.3 FRANCE
- 15.3.3.1 Rising development of electricity infrastructure, industrial base, and nuclear and renewable-energy systems to support market growth
- 15.3.4 ITALY
- 15.3.4.1 Expanding industrial base, renewable energy and rail infrastructure, and grid modernization needs to boost market growth
- 15.3.5 SPAIN
- 15.3.5.1 Increasing renewable energy development, EV manufacturing, and industrial electrification to accelerate market growth
- 15.3.6 REST OF EUROPE
- 15.3.1 GERMANY
- 15.4 NORTH AMERICA
- 15.4.1 US
- 15.4.1.1 Rapid expansion of AI and hyperscale data centers to contribute to market growth
- 15.4.2 CANADA
- 15.4.2.1 Rising clean electricity generation and industrial electrification infrastructure development to expedite market growth
- 15.4.3 MEXICO
- 15.4.3.1 Thriving automotive industry ecosystem and manufacturing capacity expansion to bolster market growth
- 15.4.1 US
- 15.5 MIDDLE EAST & AFRICA
- 15.5.1 GCC
- 15.5.1.1 Saudi Arabia
- 15.5.1.1.1 Increasing investment in power infrastructure and expansion of installed generation capacity to drive market
- 15.5.1.2 UAE
- 15.5.1.2.1 Rapid expansion of transmission network and grid capacity to bolster market growth
- 15.5.1.3 Rest of GCC
- 15.5.1.1 Saudi Arabia
- 15.5.2 SOUTH AFRICA
- 15.5.2.1 Rising implementation of ambitious transmission expansion plans to augment market growth
- 15.5.3 REST OF MIDDLE EAST & AFRICA
- 15.5.1 GCC
- 15.6 SOUTH AMERICA
- 15.6.1 BRAZIL
- 15.6.1.1 Continued expansion of renewable generation and transmission infrastructure to expedite market growth
- 15.6.2 ARGENTINA
- 15.6.2.1 Increasing development of battery energy storage and renewable-energy infrastructure to drive market
- 15.6.3 CHILE
- 15.6.3.1 Mounting adoption of utility-scale solar generation and battery energy storage systems to fuel market growth
- 15.6.4 REST OF SOUTH AMERICA
- 15.6.1 BRAZIL
16 COMPETITIVE LANDSCAPE
- 16.1 OVERVIEW
- 16.2 KEY PLAYER COMPETITIVE STRATEGIES/RIGHT TO WIN, 2023-2026
- 16.3 MARKET SHARE ANALYSIS, 2025
- 16.4 REVENUE ANALYSIS, 2021-2025
- 16.5 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 16.5.1 STARS
- 16.5.2 EMERGING LEADERS
- 16.5.3 PERVASIVE PLAYERS
- 16.5.4 PARTICIPANTS
- 16.5.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 16.5.5.1 Region footprint
- 16.5.5.2 Conductor material footprint
- 16.5.5.3 End-use industry footprint
- 16.5.5.4 Application footprint
- 16.5.5.5 Voltage footprint
- 16.5.5.6 Current footprint
- 16.6 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 16.6.1 PROGRESSIVE COMPANIES
- 16.6.2 RESPONSIVE COMPANIES
- 16.6.3 DYNAMIC COMPANIES
- 16.6.4 STARTING BLOCKS
- 16.6.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 16.6.5.1 Detailed list of key startups/SMEs
- 16.6.5.2 Competitive benchmarking of key startups/SMEs
- 16.7 COMPANY VALUATION AND FINANCIAL METRICS
- 16.8 BRAND COMPARISON
- 16.8.1 AMPHENOL CORPORATION (US)
- 16.8.2 METHODE ELECTRONICS (US)
- 16.8.3 MERSEN (FRANCE)
- 16.8.4 ROGERS CORPORATION (US)
- 16.8.5 SUN.KING TECHNOLOGY GROUP LIMITED (CHINA)
- 16.9 COMPETITIVE SCENARIO
- 16.9.1 PRODUCT LAUNCHES
- 16.9.2 DEALS
- 16.9.3 EXPANSIONS
17 COMPANY PROFILES
- 17.1 KEY PLAYERS
- 17.1.1 AMPHENOL CORPORATION
- 17.1.1.1 Business overview
- 17.1.1.2 Products/Solutions/Services offered
- 17.1.1.3 Recent developments
- 17.1.1.3.1 Deals
- 17.1.1.3.2 Expansions
- 17.1.1.4 MnM view
- 17.1.1.4.1 Key strengths/Right to win
- 17.1.1.4.2 Strategic choices
- 17.1.1.4.3 Weaknesses/Competitive threats
- 17.1.2 METHODE ELECTRONICS
- 17.1.2.1 Business overview
- 17.1.2.2 Products/Solutions/Services offered
- 17.1.2.3 Recent developments
- 17.1.2.3.1 Deals
- 17.1.2.4 MnM view
- 17.1.2.4.1 Key strengths/Right to win
- 17.1.2.4.2 Strategic choices
- 17.1.2.4.3 Weaknesses/Competitive threats
- 17.1.3 MERSEN
- 17.1.3.1 Business overview
- 17.1.3.2 Products/Solutions/Services offered
- 17.1.3.3 Recent developments
- 17.1.3.3.1 Product launches
- 17.1.3.3.2 Deals
- 17.1.3.4 MnM view
- 17.1.3.4.1 Key strengths/Right to win
- 17.1.3.4.2 Strategic choices
- 17.1.3.4.3 Weaknesses/Competitive threats
- 17.1.4 ROGERS CORPORATION
- 17.1.4.1 Business overview
- 17.1.4.2 Products/Solutions/Services offered
- 17.1.4.3 Recent developments
- 17.1.4.3.1 Deals
- 17.1.4.3.2 Expansions
- 17.1.4.4 MnM view
- 17.1.4.4.1 Key strengths/Right to win
- 17.1.4.4.2 Strategic choices
- 17.1.4.4.3 Weaknesses/Competitive threats
- 17.1.5 SUN.KING TECHNOLOGY GROUP LIMITED
- 17.1.5.1 Business overview
- 17.1.5.2 Products/Solutions/Services offered
- 17.1.5.3 MnM view
- 17.1.5.3.1 Key strengths/Right to win
- 17.1.5.3.2 Strategic choices
- 17.1.5.3.3 Weaknesses/Competitive threats
- 17.1.6 ZHUZHOU CRRC TIMES ELECTRIC CO., LTD.
- 17.1.6.1 Business overview
- 17.1.6.2 Products/Solutions/Services offered
- 17.1.7 RYODEN KASEI CO., LTD.
- 17.1.7.1 Business overview
- 17.1.7.2 Products/Solutions/Services offered
- 17.1.8 EAE ELECTRIC
- 17.1.8.1 Business overview
- 17.1.8.2 Products/Solutions/Services offered
- 17.1.9 SHANGHAI EAGTOP ELECTRONIC TECHNOLOGY CO., LTD.
- 17.1.9.1 Business overview
- 17.1.9.2 Products/Solutions/Services offered
- 17.1.10 SHENZHEN BUSBAR SCI-TECH DEVELOPMENT CO., LTD.
- 17.1.10.1 Business overview
- 17.1.10.2 Products/Solutions/Services offered
- 17.1.11 STORM POWER COMPONENTS
- 17.1.11.1 Business overview
- 17.1.11.2 Products/Solutions/Services offered
- 17.1.12 SUZHOU WEST DEANE MACHINERY INC.
- 17.1.12.1 Business overview
- 17.1.12.2 Products/Solutions/Services offered
- 17.1.13 ELECTRONIC SYSTEMS PACKAGING LLC
- 17.1.13.1 Business overview
- 17.1.13.2 Products/Solutions/Services offered
- 17.1.14 RAYCHEM RPG PRIVATE LIMITED
- 17.1.14.1 Business overview
- 17.1.14.2 Products/Solutions/Services offered
- 17.1.15 MOLEX
- 17.1.15.1 Business overview
- 17.1.15.2 Products/Solutions/Services offered
- 17.1.16 SHENZHEN WOER ELECTRIC TECHNOLOGY CO., LTD.
- 17.1.16.1 Business overview
- 17.1.16.2 Products/Solutions/Services offered
- 17.1.1 AMPHENOL CORPORATION
- 17.2 OTHER PLAYERS
- 17.2.1 ZHEJIANG RHI ELECTRIC CO., LTD.
- 17.2.2 SEGUE ELECTRONICS, INC.
- 17.2.3 KINTO GROUP
- 17.2.4 TULING
- 17.2.5 CARSAI PRECISION PARTS
- 17.2.6 ERIE INDUSTRIAL PRODUCTS
- 17.2.7 XIAMEN APOLLO STAMPING WELDING TECHNOLOGY CO., LTD.
- 17.2.8 XIAMEN NEER ELECTRONIC TECHNOLOGY CO., LTD.
- 17.2.9 DRAMETAL
18 RESEARCH METHODOLOGY
- 18.1 RESEARCH DATA
- 18.1.1 SECONDARY DATA
- 18.1.1.1 List of key secondary sources
- 18.1.1.2 Key data from secondary sources
- 18.1.2 PRIMARY DATA
- 18.1.2.1 Key data from primary sources
- 18.1.2.2 List of primary interview participants
- 18.1.2.3 Key industry insights
- 18.1.2.4 Breakdown of primary interviews
- 18.1.1 SECONDARY DATA
- 18.2 MARKET SIZE ESTIMATION
- 18.2.1 BOTTOM-UP APPROACH
- 18.2.2 TOP-DOWN APPROACH
- 18.2.3 MARKET SIZE CALCULATION FOR BASE YEAR
- 18.2.3.1 Demand-side analysis
- 18.2.3.1.1 Demand-side assumptions
- 18.2.3.1.2 Demand-side calculations
- 18.2.3.2 Supply-side analysis
- 18.2.3.2.1 Supply-side assumptions
- 18.2.3.2.2 Supply-side calculations
- 18.2.3.1 Demand-side analysis
- 18.3 MARKET FORECAST APPROACH
- 18.3.1 DEMAND SIDE
- 18.3.2 SUPPLY SIDE
- 18.4 DATA TRIANGULATION
- 18.5 FACTOR ANALYSIS
- 18.6 RESEARCH ASSUMPTIONS AND LIMITATIONS
- 18.7 RISK ANALYSIS
19 APPENDIX
- 19.1 INSIGHTS FROM INDUSTRY EXPERTS
- 19.2 DISCUSSION GUIDE
- 19.3 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 19.4 CUSTOMIZATION OPTIONS
- 19.5 RELATED REPORTS
- 19.6 AUTHOR DETAILS
List of Tables
- TABLE 1 LAMINATED BUSBAR MARKET: INCLUSIONS AND EXCLUSIONS
- TABLE 2 LAMINATED BUSBAR MARKET: SUMMARY OF CHANGES
- TABLE 3 INTERCONNECTED MARKETS
- TABLE 4 KEY MOVES AND STRATEGIC FOCUS OF TIER-1/2/3 PLAYERS
- TABLE 5 IMPACT OF PORTER'S FIVE FORCES
- TABLE 6 ROLE OF COMPANIES IN LAMINATED BUSBAR ECOSYSTEM
- TABLE 7 AVERAGE SELLING PRICE TREND OF LAMINATED BUSBARS, BY VOLTAGE, 2022-2025 (USD/KG)
- TABLE 8 AVERAGE SELLING PRICE TREND OF LAMINATED BUSBARS, BY REGION, 2022-2025 (USD/KG)
- TABLE 9 IMPORT DATA FOR HS CODE 853690-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 10 EXPORT DATA FOR HS CODE 853690-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 11 LIST OF KEY CONFERENCES AND EVENTS, 2026-2027
- TABLE 12 MERSEN GROUP DEVELOPS SMART LAMINATED BUSBARS FOR NEXT-GENERATION EV BATTERIES OF AUTOMOTIVE CELLS COMPANY
- TABLE 13 MOLEX PROVIDES LIQUID-COOLED BUSBAR TO SUPPORT EFFICIENT POWER DISTRIBUTION IN HIGH-POWER AI DATA CENTERS
- TABLE 14 MERSEN UNITES WITH F&K DELVOTEC TO DEVELOP INFINI CELL BATTERY ASSEMBLY SOLUTION TO OPTIMIZE EV BATTERY ASSEMBLY
- TABLE 15 US-ADJUSTED RECIPROCAL TARIFF RATES
- TABLE 16 EXPECTED CHANGE IN PRICES AND POTENTIAL IMPACT ON MARKET PLAYERS DUE TO TARIFFS
- TABLE 17 LIST OF KEY PATENTS, 2025-2026
- TABLE 18 AI-DRIVEN DATA CENTERS & HIGH-DENSITY COMPUTING
- TABLE 19 RENEWABLE ENERGY & POWER CONVERSION SYSTEMS
- TABLE 20 MICROGRIDS & VIRTUAL POWER PLANTS (VPPS)
- TABLE 21 GRID-SCALE ENERGY STORAGE & BATTERY SYSTEMS
- TABLE 22 NEXT-GENERATION INDUSTRIAL & POWER ELECTRONICS
- TABLE 23 MAJOR USE CASES AND MARKET POTENTIAL
- TABLE 24 BEST PRACTICES FOLLOWED BY COMPANIES
- TABLE 25 CASE STUDIES RELATED TO AI/GEN AI IMPLEMENTATION
- TABLE 26 INTERCONNECTED ECOSYSTEM AND IMPACT ON LAMINATED BUSBAR MARKET PLAYERS
- TABLE 27 NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 28 EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 29 ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 30 SOUTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 31 MIDDLE EAST & AFRICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 32 GLOBAL INDUSTRY STANDARDS
- TABLE 33 CERTIFICATIONS, LABELING, AND ECO-STANDARDS IN LAMINATED BUSBAR MARKET
- TABLE 34 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR THREE MAJOR END-USE INDUSTRIES (%)
- TABLE 35 BUYING CRITERIA FOR THREE MAJOR END-USE INDUSTRIES
- TABLE 36 UNMET NEEDS, BY END-USE INDUSTRY
- TABLE 37 LAMINATED BUSBAR MARKET, BY CONDUCTOR MATERIAL, 2021-2025 (USD MILLION)
- TABLE 38 LAMINATED BUSBAR MARKET, BY CONDUCTOR MATERIAL, 2026-2035 (USD MILLION)
- TABLE 39 COPPER: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 40 COPPER: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 41 ALUMINUM: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 42 ALUMINUM: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 43 COPPER-ALUMINUM HYBRID: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 44 COPPER-ALUMINUM HYBRID: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 45 LAMINATED BUSBAR MARKET, BY INSULATION MATERIAL, 2021-2025 (USD MILLION)
- TABLE 46 LAMINATED BUSBAR MARKET, BY INSULATION MATERIAL, 2026-2035 (USD MILLION)
- TABLE 47 POLYESTER: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 48 POLYESTER: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 49 POLYIMIDE: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 50 POLYIMIDE: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 51 EPOXY POWDER COATING: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 52 EPOXY POWDER COATING: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 53 NOMEX: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 54 NOMEX: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 55 LAMINATED BUSBAR MARKET, BY VOLTAGE, 2021-2025 (USD MILLION)
- TABLE 56 LAMINATED BUSBAR MARKET, BY VOLTAGE, 2026-2035 (USD MILLION)
- TABLE 57 LOW: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 58 LOW: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 59 MEDIUM: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 60 MEDIUM: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 61 LAMINATED BUSBAR MARKET, BY CURRENT, 2021-2025 (USD MILLION)
- TABLE 62 LAMINATED BUSBAR MARKET, BY CURRENT, 2026-2035 (USD MILLION)
- TABLE 63 BELOW 250 A: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 64 BELOW 250 A: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 65 250-1,000 A: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 66 250-1,000 A: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 67 1,001-3,000 A: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 68 1,001-3,000 A: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 69 ABOVE 3,000 A: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 70 ABOVE 3,000 A: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 71 LAMINATED BUSBAR MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 72 LAMINATED BUSBAR MARKET, BY APPLICATION, 2026-2035 (USD MILLION)
- TABLE 73 SWITCHGEAR & POWER DISTRIBUTION: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 74 SWITCHGEAR & POWER DISTRIBUTION: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 75 POWER CONVERSION SYSTEMS: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 76 POWER CONVERSION SYSTEMS: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 77 INVERTERS & CONVERTERS: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 78 INVERTERS & CONVERTERS: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 79 UPS & BATTERY PACKS: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 80 UPS & BATTERY PACKS: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 81 BUSWAYS: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 82 BUSWAYS: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 83 GENERATOR SYSTEMS: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 84 GENERATOR SYSTEMS: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 85 EV CHARGERS: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 86 EV CHARGERS: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 87 DC POWER DISTRIBUTION: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 88 DC POWER DISTRIBUTION: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 89 LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 90 LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 91 UTILITIES & GRID INFRASTRUCTURE: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 92 UTILITIES & GRID INFRASTRUCTURE: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 93 INDUSTRIAL EQUIPMENT: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 94 INDUSTRIAL EQUIPMENT: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 95 DATA CENTERS: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 96 DATA CENTERS: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 97 ELECTRIC MOBILITY & CHARGING INFRASTRUCTURE: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 98 ELECTRIC MOBILITY & CHARGING INFRASTRUCTURE: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 99 BATTERY ENERGY STORAGE SYSTEM: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 100 BATTERY ENERGY STORAGE SYSTEM: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 101 RENEWABLE ENERGY: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 102 RENEWABLE ENERGY: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 103 COMMERCIAL & RESIDENTIAL BUILDINGS: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 104 COMMERCIAL & RESIDENTIAL BUILDINGS: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 105 RAIL & TRANSPORTATION: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 106 RAIL & TRANSPORTATION: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 107 OTHERS: LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 108 OTHERS: LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 109 LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (USD MILLION)
- TABLE 110 LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (USD MILLION)
- TABLE 111 LAMINATED BUSBAR MARKET, BY REGION, 2021-2025 (THOUSAND METRIC TONS)
- TABLE 112 LAMINATED BUSBAR MARKET, BY REGION, 2026-2035 (THOUSAND METRIC TONS)
- TABLE 113 ASIA PACIFIC: LAMINATED BUSBAR MARKET, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 114 ASIA PACIFIC: LAMINATED BUSBAR MARKET, BY COUNTRY, 2026-2035 (USD MILLION)
- TABLE 115 ASIA PACIFIC: LAMINATED BUSBAR MARKET, BY CONDUCTOR MATERIAL, 2021-2025 (USD MILLION)
- TABLE 116 ASIA PACIFIC: LAMINATED BUSBAR MARKET, BY CONDUCTOR MATERIAL, 2026-2035 (USD MILLION)
- TABLE 117 ASIA PACIFIC: LAMINATED BUSBAR MARKET, BY INSULATION MATERIAL, 2021-2025 (USD MILLION)
- TABLE 118 ASIA PACIFIC: LAMINATED BUSBAR MARKET, BY INSULATION MATERIAL, 2026-2035 (USD MILLION)
- TABLE 119 ASIA PACIFIC: LAMINATED BUSBAR MARKET, BY VOLTAGE, 2021-2025 (USD MILLION)
- TABLE 120 ASIA PACIFIC: LAMINATED BUSBAR MARKET, BY VOLTAGE, 2026-2035 (USD MILLION)
- TABLE 121 ASIA PACIFIC: LAMINATED BUSBAR MARKET, BY CURRENT, 2021-2025 (USD MILLION)
- TABLE 122 ASIA PACIFIC: LAMINATED BUSBAR MARKET, BY CURRENT, 2026-2035 (USD MILLION)
- TABLE 123 ASIA PACIFIC: LAMINATED BUSBAR MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 124 ASIA PACIFIC: LAMINATED BUSBAR MARKET, BY APPLICATION, 2026-2035 (USD MILLION)
- TABLE 125 ASIA PACIFIC: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 126 ASIA PACIFIC: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 127 CHINA: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 128 CHINA: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 129 INDIA: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 130 INDIA: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 131 JAPAN: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 132 JAPAN: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 133 AUSTRALIA: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 134 AUSTRALIA: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 135 SOUTH KOREA: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 136 SOUTH KOREA: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 137 REST OF ASIA PACIFIC: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 138 REST OF ASIA PACIFIC: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 139 EUROPE: LAMINATED BUSBAR MARKET, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 140 EUROPE: LAMINATED BUSBAR MARKET, BY COUNTRY, 2026-2035 (USD MILLION)
- TABLE 141 EUROPE: LAMINATED BUSBAR MARKET, BY CONDUCTOR MATERIAL, 2021-2025 (USD MILLION)
- TABLE 142 EUROPE: LAMINATED BUSBAR MARKET, BY CONDUCTOR MATERIAL, 2026-2035 (USD MILLION)
- TABLE 143 EUROPE: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 144 EUROPE: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 145 EUROPE: LAMINATED BUSBAR MARKET, BY INSULATION MATERIAL, 2021-2025 (USD MILLION)
- TABLE 146 EUROPE: LAMINATED BUSBAR MARKET, BY INSULATION MATERIAL, 2026-2035 (USD MILLION)
- TABLE 147 EUROPE: LAMINATED BUSBAR MARKET, BY VOLTAGE, 2021-2025 (USD MILLION)
- TABLE 148 EUROPE: LAMINATED BUSBAR MARKET, BY VOLTAGE, 2026-2035 (USD MILLION)
- TABLE 149 EUROPE: LAMINATED BUSBAR MARKET, BY CURRENT RATING, 2021-2025 (USD MILLION)
- TABLE 150 EUROPE: LAMINATED BUSBAR MARKET, BY CURRENT RATING, 2026-2035 (USD MILLION)
- TABLE 151 EUROPE: LAMINATED BUSBAR MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 152 EUROPE: LAMINATED BUSBAR MARKET, BY APPLICATION, 2026-2035 (USD MILLION)
- TABLE 153 GERMANY: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 154 GERMANY: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 155 UK: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 156 UK: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 157 FRANCE: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 158 FRANCE: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 159 ITALY: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 160 ITALY: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 161 SPAIN: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 162 SPAIN: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 163 REST OF EUROPE: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 164 REST OF EUROPE: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 165 NORTH AMERICA: LAMINATED BUSBAR MARKET, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 166 NORTH AMERICA: LAMINATED BUSBAR MARKET, BY COUNTRY, 2026-2035 (USD MILLION)
- TABLE 167 NORTH AMERICA: LAMINATED BUSBAR MARKET, BY CONDUCTOR MATERIAL, 2021-2025 (USD MILLION)
- TABLE 168 NORTH AMERICA: LAMINATED BUSBAR MARKET, BY CONDUCTOR MATERIAL, 2026-2035 (USD MILLION)
- TABLE 169 NORTH AMERICA: LAMINATED BUSBAR MARKET, BY INSULATION MATERIAL, 2021-2025 (USD MILLION)
- TABLE 170 NORTH AMERICA: LAMINATED BUSBAR MARKET, BY INSULATION MATERIAL, 2026-2035 (USD MILLION)
- TABLE 171 NORTH AMERICA: LAMINATED BUSBAR MARKET, BY VOLTAGE, 2021-2025 (USD MILLION)
- TABLE 172 NORTH AMERICA: LAMINATED BUSBAR MARKET, BY VOLTAGE, 2026-2035 (USD MILLION)
- TABLE 173 NORTH AMERICA: LAMINATED BUSBAR MARKET, BY CURRENT, 2021-2025 (USD MILLION)
- TABLE 174 NORTH AMERICA: LAMINATED BUSBAR MARKET, BY CURRENT, 2026-2035 (USD MILLION)
- TABLE 175 NORTH AMERICA: LAMINATED BUSBAR MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 176 NORTH AMERICA: LAMINATED BUSBAR MARKET, BY APPLICATION, 2026-2035 (USD MILLION)
- TABLE 177 NORTH AMERICA: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 178 NORTH AMERICA: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 179 US: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 180 US: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 181 CANADA: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 182 CANADA: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 183 MEXICO: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 184 MEXICO: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 185 MIDDLE EAST & AFRICA: LAMINATED BUSBAR MARKET, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 186 MIDDLE EAST & AFRICA: LAMINATED BUSBAR MARKET, BY COUNTRY, 2026-2035 (USD MILLION)
- TABLE 187 MIDDLE EAST & AFRICA: LAMINATED BUSBAR MARKET, BY CONDUCTOR MATERIAL, 2021-2025 (USD MILLION)
- TABLE 188 MIDDLE EAST & AFRICA: LAMINATED BUSBAR MARKET, BY CONDUCTOR MATERIAL, 2026-2035 (USD MILLION)
- TABLE 189 MIDDLE EAST & AFRICA: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 190 MIDDLE EAST & AFRICA: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 191 MIDDLE EAST & AFRICA: LAMINATED BUSBAR MARKET, BY INSULATION MATERIAL, 2021-2025 (USD MILLION)
- TABLE 192 MIDDLE EAST & AFRICA: LAMINATED BUSBAR MARKET, BY INSULATION MATERIAL, 2026-2035 (USD MILLION)
- TABLE 193 MIDDLE EAST & AFRICA: LAMINATED BUSBAR MARKET, BY VOLTAGE, 2021-2025 (USD MILLION)
- TABLE 194 MIDDLE EAST & AFRICA: LAMINATED BUSBAR MARKET, BY VOLTAGE, 2026-2035 (USD MILLION)
- TABLE 195 MIDDLE EAST & AFRICA: LAMINATED BUSBAR MARKET, BY CURRENT RATING, 2021-2025 (USD MILLION)
- TABLE 196 MIDDLE EAST & AFRICA: LAMINATED BUSBAR MARKET, BY CURRENT RATING, 2026-2035 (USD MILLION)
- TABLE 197 MIDDLE EAST & AFRICA: LAMINATED BUSBAR MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 198 MIDDLE EAST & AFRICA: LAMINATED BUSBAR MARKET, BY APPLICATION, 2026-2035 (USD MILLION)
- TABLE 199 GCC: LAMINATED BUSBAR MARKET, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 200 GCC: LAMINATED BUSBAR MARKET, BY COUNTRY, 2026-2035 (USD MILLION)
- TABLE 201 SAUDI ARABIA: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 202 SAUDI ARABIA: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 203 UAE: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 204 UAE: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 205 REST OF GCC: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 206 REST OF GCC: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 207 SOUTH AFRICA: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 208 SOUTH AFRICA: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 209 REST OF MIDDLE EAST & AFRICA (MEA): LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 210 REST OF MIDDLE EAST & AFRICA (MEA): LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 211 SOUTH AMERICA: LAMINATED BUSBAR MARKET, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 212 SOUTH AMERICA: LAMINATED BUSBAR MARKET, BY COUNTRY, 2026-2035 (USD MILLION)
- TABLE 213 SOUTH AMERICA: LAMINATED BUSBAR MARKET, BY CONDUCTOR MATERIAL, 2021-2025 (USD MILLION)
- TABLE 214 SOUTH AMERICA: LAMINATED BUSBAR MARKET, BY CONDUCTOR MATERIAL, 2026-2035 (USD MILLION)
- TABLE 215 SOUTH AMERICA: LAMINATED BUSBAR MARKET, BY INSULATION MATERIAL, 2021-2025 (USD MILLION)
- TABLE 216 SOUTH AMERICA: LAMINATED BUSBAR MARKET, BY INSULATION MATERIAL, 2026-2035 (USD MILLION)
- TABLE 217 SOUTH AMERICA: LAMINATED BUSBAR MARKET, BY VOLTAGE, 2021-2025 (USD MILLION)
- TABLE 218 SOUTH AMERICA: LAMINATED BUSBAR MARKET, BY VOLTAGE, 2026-2035 (USD MILLION)
- TABLE 219 SOUTH AMERICA: LAMINATED BUSBAR MARKET, BY CURRENT, 2021-2025 (USD MILLION)
- TABLE 220 SOUTH AMERICA: LAMINATED BUSBAR MARKET, BY CURRENT, 2026-2035 (USD MILLION)
- TABLE 221 SOUTH AMERICA: LAMINATED BUSBAR MARKET, BY APPLICATION, 2021-2025 (USD MILLION)
- TABLE 222 SOUTH AMERICA: LAMINATED BUSBAR MARKET, BY APPLICATION, 2026-2035 (USD MILLION)
- TABLE 223 SOUTH AMERICA: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 224 SOUTH AMERICA: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 225 BRAZIL: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 226 BRAZIL: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 227 ARGENTINA: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 228 ARGENTINA: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 229 CHILE: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 230 CHILE: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 231 REST OF SOUTH AMERICA: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2021-2025 (USD MILLION)
- TABLE 232 REST OF SOUTH AMERICA: LAMINATED BUSBAR MARKET, BY END-USE INDUSTRY, 2026-2035 (USD MILLION)
- TABLE 233 LAMINATED BUSBAR MARKET: OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS, JANUARY 2023-JULY 2026
- TABLE 234 LAMINATED BUSBAR MARKET: DEGREE OF COMPETITION, 2025
- TABLE 235 LAMINATED BUSBAR MARKET: REGION FOOTPRINT
- TABLE 236 LAMINATED BUSBAR MARKET: CONDUCTOR MATERIAL FOOTPRINT
- TABLE 237 LAMINATED BUSBAR MARKET: END-USE INDUSTRY FOOTPRINT
- TABLE 238 LAMINATED BUSBAR MARKET: APPLICATION FOOTPRINT
- TABLE 239 LAMINATED BUSBAR MARKET: VOLTAGE FOOTPRINT
- TABLE 240 LAMINATED BUSBAR MARKET: CURRENT FOOTPRINT
- TABLE 241 LAMINATED BUSBAR MARKET: DETAILED LIST OF KEY STARTUPS/SMES
- TABLE 242 LAMINATED BUSBAR MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
- TABLE 243 LAMINATED BUSBAR MARKET: PRODUCT LAUNCHES, JANUARY 2023-JULY 2026
- TABLE 244 LAMINATED BUSBAR MARKET: DEALS, JANUARY 2023-JULY 2026
- TABLE 245 LAMINATED BUSBAR MARKET: EXPANSIONS, JANUARY 2023-JULY 2026
- TABLE 246 AMPHENOL CORPORATION: COMPANY OVERVIEW
- TABLE 247 AMPHENOL CORPORATION: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 248 AMPHENOL CORPORATION: DEALS
- TABLE 249 AMPHENOL CORPORATION: EXPANSIONS
- TABLE 250 METHODE ELECTRONICS: COMPANY OVERVIEW
- TABLE 251 METHODE ELECTRONICS: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 252 METHODE ELECTRONICS: DEALS
- TABLE 253 MERSEN: COMPANY OVERVIEW
- TABLE 254 MERSEN: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 255 MERSEN: PRODUCT LAUNCHES
- TABLE 256 MERSEN: OTHER DEVELOPMENTS
- TABLE 257 ROGERS CORPORATION: COMPANY OVERVIEW
- TABLE 258 ROGERS CORPORATION: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 259 ROGERS CORPORATION: DEALS
- TABLE 260 ROGERS CORPORATION: EXPANSIONS
- TABLE 261 SUN.KING TECHNOLOGY GROUP LIMITED: COMPANY OVERVIEW
- TABLE 262 SUN.KING TECHNOLOGY GROUP LIMITED: PRODUCTS OFFERED
- TABLE 263 ZHUZHOU CRRC TIMES ELECTRIC CO., LTD.: COMPANY OVERVIEW
- TABLE 264 ZHUZHOU CRRC TIMES ELECTRIC CO., LTD.: PRODUCTS/SOLUTIONS/ SERVICES OFFERED
- TABLE 265 RYODEN KASEI CO., LTD.: COMPANY OVERVIEW
- TABLE 266 RYODEN KASEI CO., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 267 EAE ELECTRIC: COMPANY OVERVIEW
- TABLE 268 EAE ELECTRIC: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 269 SHANGHAI EAGTOP ELECTRONIC TECHNOLOGY CO., LTD.: COMPANY OVERVIEW
- TABLE 270 SHANGHAI EAGTOP ELECTRONIC TECHNOLOGY CO., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 271 SHENZHEN BUSBAR SCI-TECH DEVELOPMENT CO., LTD.: COMPANY OVERVIEW
- TABLE 272 SHENZHEN BUSBAR SCI-TECH DEVELOPMENT CO., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 273 STORM POWER COMPONENTS: COMPANY OVERVIEW
- TABLE 274 STORM POWER COMPONENTS: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 275 SUZHOU WEST DEANE MACHINERY INC.: COMPANY OVERVIEW
- TABLE 276 SUZHOU WEST DEANE MACHINERY INC.: PRODUCTS/SOLUTIONS/ SERVICES OFFERED
- TABLE 277 ELECTRONIC SYSTEMS PACKAGING LLC: COMPANY OVERVIEW
- TABLE 278 ELECTRONIC SYSTEMS PACKAGING LLC: PRODUCTS/SOLUTIONS/ SERVICES OFFERED
- TABLE 279 RAYCHEM RPG PRIVATE LIMITED: COMPANY OVERVIEW
- TABLE 280 RAYCHEM RPG PRIVATE LIMITED: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 281 MOLEX: COMPANY OVERVIEW
- TABLE 282 MOLEX: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 283 SHENZHEN WOER ELECTRIC TECHNOLOGY CO., LTD.: COMPANY OVERVIEW
- TABLE 284 SHENZHEN WOER ELECTRIC TECHNOLOGY CO., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 285 ZHEJIANG RHI ELECTRIC CO., LTD.: COMPANY OVERVIEW
- TABLE 286 SEGUE ELECTRONICS, INC: COMPANY OVERVIEW
- TABLE 287 KINTO GROUP: COMPANY OVERVIEW
- TABLE 288 TULING: COMPANY OVERVIEW
- TABLE 289 CARSAI PRECISION PARTS: COMPANY OVERVIEW
- TABLE 290 ERIE INDUSTRIAL PRODUCTS: COMPANY OVERVIEW
- TABLE 291 XIAMEN APOLLO STAMPING WELDING TECHNOLOGY CO., LTD.: COMPANY OVERVIEW
- TABLE 292 XIAMEN NEER ELECTRONIC TECHNOLOGY CO., LTD.: COMPANY OVERVIEW
- TABLE 293 DRAMETALL (SHENZHEN SHIXIN METAL PRODUCTS CO., LTD.): COMPANY OVERVIEW
- TABLE 294 MAJOR SECONDARY SOURCES
- TABLE 295 DATA CAPTURED FROM PRIMARY SOURCES
- TABLE 296 PRIMARY INTERVIEW PARTICIPANTS, BY COMPANY
- TABLE 297 LAMINATED BUSBAR MARKET: RISK ANALYSIS
List of Figures
- FIGURE 1 LAMINATED BUSBAR MARKET SEGMENTATION AND REGIONAL SCOPE
- FIGURE 2 LAMINATED BUSBAR MARKET: DURATION CONSIDERED
- FIGURE 3 LAMINATED BUSBAR MARKET SCENARIO
- FIGURE 4 GLOBAL LAMINATED BUSBAR MARKET SIZE, 2021-2035
- FIGURE 5 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN LAMINATED BUSBAR MARKET, 2023-2026
- FIGURE 6 DISRUPTIONS IMPACTING GROWTH OF LAMINATED BUSBAR MARKET
- FIGURE 7 HIGH-GROWTH SEGMENTS IN LAMINATED BUSBAR MARKET, 2026-2035
- FIGURE 8 ASIA PACIFIC TO HOLD LARGEST SHARE OF LAMINATED BUSBAR MARKET IN 2026 AND 2035
- FIGURE 9 RISING RENEWABLE ENERGY INTEGRATION AND ELECTRIFICATION TO DRIVE LAMINATED BUSBAR MARKET
- FIGURE 10 NORTH AMERICA TO EXHIBIT HIGHEST CAGR BETWEEN 2026 AND 2035
- FIGURE 11 COPPER SEGMENT AND CHINA DOMINATED LAMINATED BUSBAR MARKET IN ASIA PACIFIC IN 2025
- FIGURE 12 LOW SEGMENT TO ACCOUNT FOR LARGER MARKET SHARE IN 2035
- FIGURE 13 POLYESTER SEGMENT TO CAPTURE LARGEST MARKET SHARE IN 2035
- FIGURE 14 SWITCHGEAR & POWER DISTRIBUTION SEGMENT TO HOLD MAJOR MARKET SHARE IN 2035
- FIGURE 15 UTILITIES & GRID INFRASTRUCTURE SEGMENT TO HOLD LARGEST MARKET SHARE IN 2035
- FIGURE 16 ASIA PACIFIC TO ACCOUNT FOR LARGEST MARKET SHARE IN 2035
- FIGURE 17 DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 18 GLOBAL ELECTRIC CAR SALES, 2020-2026
- FIGURE 19 ALUMINIUM AND COPPER PRICE TRENDS, 2016-2030
- FIGURE 20 GLOBAL STOCK OF PUBLIC CHARGING POINTS, BY SPEED, 2020-2025
- FIGURE 21 PORTER'S FIVE FORCES ANALYSIS
- FIGURE 22 LAMINATED BUSBAR VALUE CHAIN ANALYSIS
- FIGURE 23 LAMINATED BUSBAR ECOSYSTEM
- FIGURE 24 ASP TREND OF LAMINATED BUSBARS, BY VOLTAGE, 2022-2025
- FIGURE 25 ASP TREND OF LAMINATED BUSBARS, BY REGION, 2022-2025
- FIGURE 26 IMPORT DATA FOR HS CODE 853690-COMPLIANT PRODUCTS FOR TOP FIVE COUNTRIES, 2021-2025
- FIGURE 27 EXPORT DATA FOR HS CODE 853690-COMPLIANT PRODUCTS FOR TOP FIVE COUNTRIES, 2021-2025
- FIGURE 28 TRENDS/DISRUPTIONS INFLUENCING CUSTOMER BUSINESS
- FIGURE 29 INVESTMENT AND FUNDING SCENARIO, 2025
- FIGURE 30 PATENTS GRANTED AND APPLIED, 2016-2025
- FIGURE 31 FUTURE APPLICATIONS OF LAMINATED BUSBARS
- FIGURE 32 SUCCESS STORIES AND REAL-WORLD APPLICATIONS OF LAMINATED BUSBARS
- FIGURE 33 DECISION-MAKING FACTORS IN LAMINATED BUSBAR MARKET
- FIGURE 34 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP THREE END-USE INDUSTRIES
- FIGURE 35 KEY BUYING CRITERIA FOR TOP THREE END-USE INDUSTRIES
- FIGURE 36 ADOPTION BARRIERS AND INTERNAL CHALLENGES IN LAMINATED BUSBAR MARKET
- FIGURE 37 COPPER SEGMENT CAPTURED LARGEST SHARE OF LAMINATED BUSBAR MARKET IN 2025
- FIGURE 38 POLYESTER SEGMENT HELD LARGEST SHARE OF LAMINATED BUSBAR MARKET IN 2025
- FIGURE 39 LOW SEGMENT ACCOUNTED FOR LARGER SHARE OF LAMINATED BUSBAR MARKET IN 2025
- FIGURE 40 1,001-3,000 A SEGMENT CAPTURED LARGEST MARKET SHARE IN 2025
- FIGURE 41 SWITCHGEAR & POWER DISTRIBUTION SEGMENT HELD LARGEST MARKET SHARE IN 2025
- FIGURE 42 DATA CENTERS SEGMENT CAPTURED LARGEST SHARE OF LAMINATED BUSBAR MARKET IN 2025
- FIGURE 43 NORTH AMERICA TO GROW AT HIGHEST CAGR FROM 2026 TO 2035
- FIGURE 44 ASIA PACIFIC: LAMINATED BUSBAR MARKET SNAPSHOT
- FIGURE 45 EUROPE: LAMINATED BUSBAR MARKET SNAPSHOT
- FIGURE 46 MARKET SHARE ANALYSIS OF COMPANIES OFFERING LAMINATED BUSBARS, 2025
- FIGURE 47 LAMINATED BUSBAR MARKET: REVENUE ANALYSIS OF TOP FIVE PLAYERS, 2021-2025
- FIGURE 48 LAMINATED BUSBAR MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- FIGURE 49 LAMINATED BUSBAR MARKET: COMPANY FOOTPRINT
- FIGURE 50 LAMINATED BUSBAR MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
- FIGURE 51 COMPANY VALUATION
- FIGURE 52 FINANCIAL METRICS (EV/EBITDA)
- FIGURE 53 BRAND COMPARISON OF KEY VENDORS
- FIGURE 54 AMPHENOL CORPORATION: COMPANY SNAPSHOT
- FIGURE 55 METHODE ELECTRONICS: COMPANY SNAPSHOT
- FIGURE 56 MERSEN: COMPANY SNAPSHOT
- FIGURE 57 ROGERS CORPORATION: COMPANY SNAPSHOT
- FIGURE 58 SUN.KING TECHNOLOGY GROUP LIMITED: COMPANY SNAPSHOT
- FIGURE 59 ZHUZHOU CRRC TIMES ELECTRIC CO., LTD.: COMPANY SNAPSHOT
- FIGURE 60 LAMINATED BUSBAR MARKET: RESEARCH DESIGN
- FIGURE 61 DATA CAPTURED FROM SECONDARY SOURCES
- FIGURE 62 CORE FINDINGS FROM INDUSTRY EXPERTS
- FIGURE 63 BREAKDOWN OF PRIMARY INTERVIEWS, BY COMPANY TYPE, DESIGNATION, AND REGION
- FIGURE 64 LAMINATED BUSBAR MARKET: BOTTOM-UP APPROACH
- FIGURE 65 LAMINATED BUSBAR MARKET: TOP-DOWN APPROACH
- FIGURE 66 LAMINATED BUSBAR MARKET: DEMAND-SIDE ANALYSIS
- FIGURE 67 KEY STEPS CONSIDERED TO ASSESS SUPPLY OF LAMINATED BUSBARS
- FIGURE 68 LAMINATED BUSBAR MARKET: SUPPLY-SIDE ANALYSIS
- FIGURE 69 LAMINATED BUSBAR MARKET: DATA TRIANGULATION
- FIGURE 70 LAMINATED BUSBAR MARKET: FACTOR ANALYSIS
- FIGURE 71 LAMINATED BUSBAR MARKET: RESEARCH ASSUMPTIONS AND LIMITATIONS
- FIGURE 72 LAMINATED BUSBAR MARKET: INSIGHTS FROM INDUSTRY EXPERTS

 層壓匯流排市場-2026-2032年全球市場預測
 風力渦輪機匯流排市場報告:趨勢、預測與競爭分析(至2035年)
 疊層匯流排:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 全球層壓匯流排市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 疊層匯流排市場-全球產業規模、佔有率、趨勢、機會與預測:絕緣材料、導體、終端用戶、地區和競爭格局,2021-2031年
 2026-2030年全球層壓母線市場邊緣封裝層壓匯流排市場按導體材料、額定電壓、額定電流、層數、安裝類型、匯流排結構、終端用戶行業和應用分類 - 全球預測(2026-2032 年)