


 |
市場調查報告書
商品編碼
2066265
全球 RISC-V 市場:按類型、產品、位元架構、應用和地區分類 - 預測至 2032 年RISC-V Market By Offering (Hardware, RISC-V IP (IP Royalties, IP Licensing), Software), Bit Architecture (32-bit, 64-bit, 128-bit), Application (Industrial, Automotive, Networking, Computer, Consumer, Aerospace & Defense) - Global Forecast to 2032 |
||||||

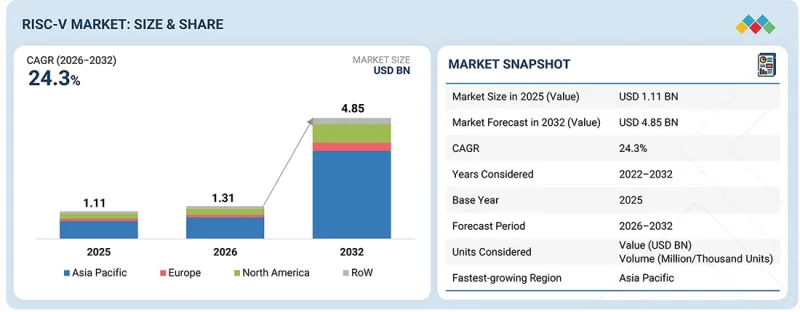
RISC-V 市場預計將從 2026 年的 13.1 億美元成長到 2032 年的 48.5 億美元,複合年成長率為 24.3%。
最大的成長要素是加速向開放標準處理器架構的轉變,越來越多的公司採用 RISC-V 來避免與專有指令集架構 (ISA) 相關的高昂授權成本和供應商鎖定。
| 調查範圍 | |
|---|---|
| 調查期 | 2021-2032 |
| 基準年 | 2025 |
| 預測期 | 2026-2032 |
| 計算單位 | 金額(10億美元) |
| 部分 | 按類型、按產品、位元架構、按應用、按區域 |
| 目標區域 | 北美、歐洲、亞太地區及其他地區 |
另一個關鍵因素是人工智慧 (AI)、機器學習 (ML) 和邊緣運算工作負載的快速擴展,因為 RISC-V 能夠實現高度可自訂的加速器和異質運算設計,從而最佳化效能和能源效率。
到 2025 年,消費者應用將佔據最大的市場佔有率。
到2025年,消費應用將佔據RISC-V市場最大的佔有率,這主要得益於RISC-V解決方案在智慧型手機、筆記型電腦、穿戴式裝置、智慧家居設備和個人電子產品中的廣泛應用。低功耗RISC-V MCU和SoC在注重成本的消費性產品中的大規模應用,將顯著提升出貨量和IP利用率。該領域的製造商優先考慮成本效益、設計柔軟性和功耗最佳化,而這些都與RISC-V開放且可自訂的架構高度契合。此外,隨著語音助理、設備內推理工具和邊緣處理工具等人工智慧功能日益整合到消費性設備中,對異質運算架構的需求也在不斷成長,其中RISC-V核心被用於控制和輔助處理任務。大規模ODM和OEM廠商將RISC-V架構快速整合到下一代消費平台中,這將進一步鞏固RISC-V在2025年出貨量的領先地位。
在預測期內,軟體產業預計將錄得最高的複合年成長率。
預計在2026年至2032年期間,軟體領域將成為RISC-V市場中複合年成長率最高的領域,這主要得益於RISC-V生態系統的快速擴張以及基於RISC-V的系統開發日益複雜。隨著硬體採用率的加速提升,對設計和檢驗工具、編譯器和工具鏈、整合開發環境(IDE)、作業系統、中介軟體和安全軟體的需求也隨之激增,以支援可擴展的開發環境。隨著RISC-V從早期採用階段過渡到主流商業化階段,各方正大力投資於提升軟體成熟度,包括針對人工智慧工作負載、雲端原生開發和嵌入式應用的最佳化。開放原始碼社群和商業供應商的貢獻不斷增加,正在提升相容性,縮短產品上市時間,並增強跨平台的效能可攜性。此外,跨越分散化硬體實現的標準化軟體堆疊的需求日益成長,也正在加速企業採用RISC-V。隨著RISC-V擴展到資料中心、汽車系統和邊緣人工智慧平台,軟體正成為關鍵的基礎層,其成長速度將超過IP和硬體領域。
在預測期內,亞太地區預計將呈現最高的複合年成長率。
由於人工智慧、邊緣運算、工業IoT和汽車電子應用領域的快速發展,亞太地區預計將成為RISC-V市場複合年成長率最高的地區。人工智慧設備、智慧工廠、機器人系統、自動駕駛汽車和智慧交通基礎設施的日益普及,催生了對可客製化和節能型處理器架構的強勁需求。 RISC-V處理器為亞太地區的半導體公司提供了柔軟性,使其能夠整合針對邊緣運算和人工智慧工作負載最佳化的特定應用指令、人工智慧加速器、向量處理能力和低功耗運算能力。此外,該地區的超大規模資料中心業者資料中心和雲端服務供應商也擴大評估RISC-V在資料中心、網路和人工智慧基礎架構應用中的可行性,以最佳化工作負載並降低整體開發成本。中國大陸、台灣、韓國和日本等地強大的家用電子電器製造地,進一步加速了RISC-V架構在下一代連網型設備的應用。此外,阿里巴巴、安第斯科技和星五科技等公司加大對先進 RISC-V 處理器的研發投入,並擴大其生態系統,這正在加強該地區的技術領先地位,並支持商業和工業運算平台的長期市場成長。
為了識別和檢驗透過二手研究收集到的各個細分市場和子細分市場的市場規模,我們對RISC-V行業的關鍵專家進行了廣泛的一手訪談。本報告中一手訪談對象的詳細情況如下:
本次調查匯集了來自眾多行業專家的見解,涵蓋零件供應商、一級供應商和整車製造商。主要受訪者組成如下:
本報告介紹了RISC-V市場的主要參與者及其各自的排名分析。本報告涵蓋的主要參與者包括SiFive公司(美國)、安德斯科技股份有限公司(台灣)、Codasip公司(德國)、Synopsys公司(美國)、Imagination Technologies公司(英國)、MIPS公司(美國)、Tensorrent公司(美國)、上海星五導體股份有限公司(中國)、Nuclei Systems(中國)和Efinix公司(中國)。
RISC-V 市場的其他主要參與者包括 Semidynamics(西班牙)、阿里巴巴(中國)、Cortus(法國)、Syntacore(塞普勒斯)、InCore(印度)、Bluespec(美國)、Lattice Semiconductor(美國)、Segger(德國)、IAR(瑞典)、Wind River Software(美國)、GreenLabach(美國)、德國) GmbH(荷蘭)、Canonical(英國)、Cadence Design Systems, Inc.(美國)和 Spandea(美國)。
調查範圍:
本研究報告基於產品和服務、位元架構、應用和地區對 RISC-V 市場進行了細分。報告說明了RISC-V 市場的主要促進因素、限制因素、挑戰和機遇,並提供了直至 2032 年的市場預測。此外,報告還對 RISC-V 生態系統中的所有公司進行了領導地位分析。
購買本報告的主要好處
本報告為市場領導和新參與企業提供最準確的RISC-V市場整體及其各個細分市場的估算數據。它還有助於相關人員了解競爭格局,更好地定位自身業務,並制定合適的打入市場策略。此外,本報告還幫助相關人員了解市場趨勢,並提供關鍵市場促進因素、限制因素、挑戰和機會的資訊。
本報告深入分析了以下幾點:
- 分析關鍵促進因素(成本效益和授權靈活性)、阻礙因素(生態系統成熟度的差異)、機會(邊緣人工智慧和人工智慧物聯網基礎設施的擴展)以及挑戰(與現有架構的競爭)。
- 產品開發/創新:深入了解 RISC-V 市場的未來技術、研發活動和新產品發布。
- 市場發展:我們透過分析各地區的 RISC-V 市場,提供有關盈利市場的全面資訊。
- 市場多元化:全面介紹 RISC-V 市場的新產品、未開發的市場、近期趨勢和投資情況。
- 競爭分析:對主要市場參與企業(如 SiFive, Inc.(美國)、Andes Technology Corporation(台灣)、Codasip(德國)、Synopsys, Inc.(美國)和 Imagination Technologies(英國))的市場佔有率、成長策略和服務產品進行詳細評估。
目錄
第1章:引言
第2章執行摘要
第3章重要考察
第4章 市場概覽
- 市場動態
- 促進因素
- 抑制因子
- 機會
- 任務
- 相互關聯的市場與跨產業機遇
- 一級/二級/三級公司的策略性舉措
- RISC-V國際成員擴大至70個國家(2015-2024年)
第5章 產業趨勢
- 波特五力分析
- 宏觀經濟展望
- 價值鏈分析
- 生態系分析
- 價格分析
- 貿易分析
- 2026-2027 年主要會議和活動
- 影響客戶業務的趨勢/顛覆性因素
- 2022-2026年投資及資金籌措狀況
- 案例研究分析
- 美國關稅對 RISC-V 市場的影響
第6章:技術進步、人工智慧的影響、專利與創新
- 主要新興技術
- 互補技術
- 鄰近技術
- 技術藍圖
- 專利分析
- 人工智慧/生成式人工智慧對 RISC-V 市場的影響
第7章 監理情勢
- 當地法規和合規性
- 監管機構、政府機構和其他組織
- 業界標準
第8章:顧客趨勢與購買行為
- 決策流程
- 採購過程中的關鍵相關人員及其評估標準
- 實施障礙和內部挑戰
- 與應用相關的未滿足需求
第9章:RISC-V 市場(按類型分類)
- CPU(通用)
- 應用程式處理器
- GPU
- 人工智慧加速器
- DSP
- 安全處理器
- MCU
- FPGA
- 儲存控制器
第10章:RISC-V 市場(按產品/服務分類)
- RISC-V IP
- RISC-V軟體
第11章:RISC-V 市場(按位架構分類)
- 32 位元
- 64 位元
- 128 位元
第12章 RISC-V 市場(按應用領域分類)
- 產業
- 車
- 聯網
- 電腦
- 消費者
- 其他
第13章 RISC-V 市場(按地區分類)
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 其他
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 台灣
- 其他
- 其他地區
- 中東
- 非洲
- 南美洲
第14章 競爭格局
- 概述
- 2022-2026年主要參與企業的競爭策略/優勢
- 2025年市佔率分析
- 2022-2025年收入分析
- 企業估值和財務指標
- 產品/品牌對比
- 企業估值矩陣:主要公司,2025 年
- 公司估值矩陣:新創企業/中小企業,2025 年
- 競爭格局
第15章:公司簡介
- 主要參與企業
- SIFIVE, INC.
- ANDES TECHNOLOGY CORPORATION
- CODASIP
- GLOBALFOUNDRIES
- IMAGINATION TECHNOLOGIES
- TENSTORRENT
- SHANGHAI STARFIVE SEMICONDUCTOR CO., LTD.
- EFINIX
- NUCLEI SYSTEM
- SEMIDYNAMICS
- 其他公司
- ALIBABA GROUP
- CORTUS
- SYNTACORE
- BLUESPEC
- LATTICE SEMICONDUCTOR
- SEGGER
- IAR
- WIND RIVER
- LAUTERBACH GMBH
- SIEMENS
- CADENCE DESIGN SYSTEMS, INC.
- MICROCHIP TECHNOLOGY INC.
- RENESAS ELECTRONICS CORPORATION
- SOPHGO
- GIGADEVICE
第16章調查方法
第17章附錄
The RISC-V market is anticipated to grow from USD 1.31 billion in 2026 to USD 4.85 billion by 2032, at a CAGR of 24.3%. The strongest driver is the accelerating shift toward open-standard processor architectures, where companies prefer RISC-V to avoid high licensing costs and vendor lock-in associated with proprietary Instruction Set Architectures (ISAs).
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2021-2032 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Units Considered | Value (USD Billion) |
| Segments | By Offering, Application and Region |
| Regions covered | North America, Europe, APAC, RoW |
Rapid growth in artificial intelligence (AI), machine learning (ML), and edge computing workloads is another key factor, as RISC-V enables highly customizable accelerators and heterogeneous compute designs optimized for performance and power efficiency.
Consumer applications held largest market share in 2025
Consumer applications held the largest share of the RISC-V market in 2025 due to the massive deployment of RISC-V solutions across smartphones, laptops, wearables, smart home devices, and personal electronics. High-volume adoption of low-power RISC-V MCUs and SoCs in cost-sensitive consumer products significantly boosted shipment scale and IP consumption. Manufacturers in this segment prioritize cost efficiency, design flexibility, and power optimization, all of which align strongly with RISC-V's open and customizable architecture. Additionally, the growing integration of AI-enabled features in consumer devices, such as voice assistants, on-device inference tools, and edge processing tools, has increased demand for heterogeneous computing architectures where RISC-V cores are used for control and auxiliary processing tasks. The presence of large ODMs and OEMs rapidly integrating RISC-V architecture into next-generation consumer platforms further strengthened its dominance in terms of volume contribution in 2025.
Software offerings to record highest CAGR during forecast period
The software segment is expected to register the highest CAGR in the RISC-V market from 2026 to 2032 due to rapid ecosystem expansion and increasing complexity of RISC-V-based system development. As hardware adoption accelerates, demand for design and verification tools, compiler toolchains, integrated development environments (IDEs), operating systems, middleware, and security software is rising sharply to support scalable development environments. The transition from early-stage adoption to mainstream commercialization is driving strong investment in software maturity, including optimization for AI workloads, cloud-native development, and embedded applications. Growing contributions from open-source communities and commercial vendors are improving compatibility, reducing time-to-market, and enhancing performance portability across platforms. Furthermore, the need for standardized software stacks across fragmented hardware implementations is accelerating enterprise adoption. As RISC-V moves into data centers, automotive systems, and edge AI platforms, software becomes the critical enabler layer, leading to a faster growth rate compared to IP and hardware segments.
Asia Pacific to exhibit highest CAGR during forecast period
Asia Pacific is expected to register the highest CAGR in the RISC-V market owing to the rapid expansion of AI, edge computing, industrial IoT, and automotive electronics applications across the region. The growing deployment of AI-enabled devices, smart factories, robotics systems, autonomous vehicles, and intelligent transportation infrastructure is creating strong demand for customizable and energy-efficient processor architectures. RISC-V processors provide regional semiconductor companies with the flexibility to integrate application-specific instructions, AI accelerators, vector processing capabilities, and low-power computing features optimized for edge and AI workloads. Additionally, hyperscalers and cloud service providers in the region are increasingly evaluating RISC-V for data center, networking, and AI infrastructure applications to improve workload optimization and reduce total development costs. The strong presence of consumer electronics manufacturing hubs across China, Taiwan, South Korea, and Japan is further accelerating the adoption of RISC-V architectures in next-generation connected devices. Moreover, increasing investments by companies such as Alibaba, Andes Technology, and StarFive in advanced RISC-V processor development and ecosystem expansion are strengthening the region's technological leadership and supporting long-term market growth across commercial and industrial computing platforms.
Extensive primary interviews were conducted with key experts in the RIS-V industry to determine and verify the market size for various segments and subsegments gathered through secondary research. The breakdown of primary participants for the report is provided below:
The study contains insights from various industry experts, from component suppliers to Tier 1 companies and OEMs. The break-up of the primaries is as follows:
- By Company Type: Tier 1-20%, Tier 2-25%, and Tier 3-55%
- By Designation: C-level Executives-30%, Directors-30%, and Others-40%
- By Region: North America-30%, Europe-15%, Asia Pacific-50%, and RoW-5%
The report profiles the key players in the RISC-V market with their respective ranking analysis. Prominent players profiled in this report are SiFive, Inc. (US), Andes Technology Corporation (Taiwan), Codasip (Germany), Synopsys, Inc. (US), Imagination Technologies (UK), MIPS (US), Tenstorrent (US), Shanghai StarFive Semiconductor Co., Ltd. (China), Nuclei System (China), and Efinix, Inc. (US), among others.
Apart from this, Semidynamics (Spain), Alibaba (China), CORTUS (France), Syntacore (Cyprus), InCore (India), Bluespec (US), Lattice Semiconductor (US), SEGGER (Germany), IAR (Sweden), Wind River (US), Green Hills Software (US), Lauterbach GmbH (Germany), emproof GmbH (Netherlands), Canonical (UK), Cadence Design Systems, Inc. (US), and Spanidea (US) are among a few other players in the RISC-V market.
Research Coverage:
This research report categorizes the RISC-V market based on offering, bit architecture, application, and region. The report describes the major drivers, restraints, challenges, and opportunities pertaining to the RISC-V market and forecasts the same till 2032. Apart from these, the report also consists of leadership mapping and analysis of all the companies included in the RISC-V ecosystem.
Key Benefits of Buying the Report
The report will help the market leaders/new entrants in this market with information on the closest approximations of the numbers for the overall RISC-V market and the subsegments. This report will help stakeholders understand the competitive landscape and gain more insights to position their businesses better and plan suitable go-to-market strategies. The report also helps stakeholders understand the pulse of the market and provides them with information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following pointers:
- Analysis of key drivers (Cost Efficiency & Licensing Freedom), restraints (Ecosystem Maturity Gap), opportunities (Expansion of Edge AI and AIoT infrastructure), and challenges (Competition from Established Architectures)
- Product Development/Innovation: Detailed insights on upcoming technologies, research & development activities, and new product launches in the RISC-V market
- Market Development: Comprehensive information about lucrative markets by analyzing the RISC-V market across varied regions
- Market Diversification: Exhaustive information about new products, untapped geographies, recent developments, and investments in the RISC-V market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and service offerings of leading market players such as SiFive, Inc. (US), Andes Technology Corporation (Taiwan), Codasip (Germany), Synopsys, Inc. (US), and Imagination Technologies (UK)
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 MARKET SCOPE
- 1.3.1 MARKET SEGMENTATION AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 UNIT CONSIDERED
- 1.6 STAKEHOLDERS
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN RISC-V MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN RISC-V MARKET
- 3.2 RISC-V MARKET, BY OFFERING
- 3.3 RISC-V MARKET, BY BIT ARCHITECTURE
- 3.4 RISC-V MARKET, BY APPLICATION
- 3.5 RISC-V MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Growing preference for open architectures and license-free processor development
- 4.2.1.2 Elevating demand for domain-specific architectures to create high-performance SOCs
- 4.2.1.3 Rapid proliferation of IoT & edge AI infrastructure
- 4.2.1.4 Geopolitical push for semiconductor independence
- 4.2.2 RESTRAINTS
- 4.2.2.1 Limited penetration in premium SoC segment due to ecosystem maturity constraints
- 4.2.2.2 Lack of unified software ecosystem
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Expansion of edge AI and AIoT applications
- 4.2.3.2 Increasing hyperscaler investment in custom compute architectures
- 4.2.3.3 Expansion of data centers and HPC workloads
- 4.2.3.4 Automotive transition from distributed ECUs to zonal architectures
- 4.2.4 CHALLENGES
- 4.2.4.1 Dominance of established architectures and high switching cost due to ecosystem lock-in
- 4.2.4.2 Ecosystem fragmentation, software maturity gaps, and uncertain monetization pathways
- 4.2.1 DRIVERS
- 4.3 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
- 4.5 EXPANSION OF RISC-V INTERNATIONAL MEMBERSHIP ACROSS 70 COUNTRIES, 2015-2024
5 INDUSTRY TRENDS
- 5.1 INTRODUCTION
- 5.2 PORTER'S FIVE FORCES ANALYSIS
- 5.2.1 THREAT OF NEW ENTRANTS
- 5.2.2 THREAT OF SUBSTITUTES
- 5.2.3 BARGAINING POWER OF SUPPLIERS
- 5.2.4 BARGAINING POWER OF BUYERS
- 5.2.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.3 MACROECONOMIC OUTLOOK
- 5.3.1 INTRODUCTION
- 5.3.2 GDP TRENDS AND FORECAST
- 5.3.3 TRENDS IN RISC-V MARKET
- 5.3.4 TRENDS IN IP MARKET
- 5.4 VALUE CHAIN ANALYSIS
- 5.5 ECOSYSTEM ANALYSIS
- 5.6 PRICING ANALYSIS
- 5.6.1 PRICING RANGE OF RISC-V IP PRODUCTS, BY KEY PLAYER, 2025
- 5.6.2 PRICING RANGE OF RISC-V IP PRODUCTS, BY REGION, 2022-2025
- 5.7 TRADE ANALYSIS
- 5.7.1 IMPORT SCENARIO (HS CODE 854231)
- 5.7.2 EXPORT SCENARIO (HS CODE 854231)
- 5.8 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.9 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.10 INVESTMENT AND FUNDING SCENARIO, 2022-2026
- 5.11 CASE STUDY ANALYSIS
- 5.11.1 RENESAS OFFERS RISC-V MICROCONTROLLERS TO SHORTEN TIME-TO-MARKET FOR PROTOTYPE APPLICATIONS
- 5.11.2 SIFIVE LAUNCHES RISC-V PROCESSOR TO ACHIEVE END-TO-END VISIBILITY INTO FACTORY OPERATIONS FROM REMOTE LOCATIONS
- 5.11.3 ANDES TECHNOLOGY DESIGNS RISC-V ISA TO REDUCE SOC DESIGN ITERATIONS
- 5.12 IMPACT OF US TARIFF ON RISC-V MARKET
- 5.12.1 INTRODUCTION
- 5.12.1.1 Key tariff rates
- 5.12.2 PRICE IMPACT ANALYSIS
- 5.12.3 IMPACT ON COUNTRIES/REGIONS
- 5.12.3.1 US
- 5.12.3.2 Europe
- 5.12.3.3 Asia Pacific
- 5.12.4 IMPACT ON APPLICATIONS
- 5.12.4.1 Networking
- 5.12.4.2 Computer
- 5.12.4.3 Consumer
- 5.12.1 INTRODUCTION
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 RISC-V ISA WITH VECTOR EXTENSIONS
- 6.1.2 CUSTOM INSTRUCTION EXTENSIONS
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 COMPILERS (GCC, LLVM), OPERATING SYSTEMS (LINUX, RTOS), AND MIDDLEWARE FRAMEWORKS
- 6.2.2 EDA TOOLS AND VERIFICATION IP
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 ARTIFICIAL INTELLIGENCE (AI) AND EDGE AI
- 6.3.2 ADVANCED SOC INTEGRATION AND HETEROGENEOUS COMPUTING
- 6.4 TECHNOLOGY ROADMAP
- 6.5 PATENT ANALYSIS
- 6.6 IMPACT OF AI/GEN AI ON RISC-V MARKET
- 6.6.1 TOP USE CASES AND MARKET POTENTIAL
- 6.6.2 BEST PRACTICES FOLLOWED BY PLAYERS IN RISC-V MARKET
- 6.6.3 CASE STUDIES RELATED TO AI IMPLEMENTATION IN RISC-V MARKET
- 6.6.4 INTERCONNECTED/ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.6.5 CLIENTS' READINESS TO ADOPT AI IN RISC-V MARKET
7 REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.4 UNMET NEEDS RELATED TO APPLICATIONS
9 RISC-V-BASED SEMICONDUCTOR MARKET, BY TYPE
- 9.1 INTRODUCTION
- 9.1.1 CPU (GENERAL PURPOSE)
- 9.1.1.1 Increasing demand for scalable and power-efficient computing architectures across data centers to drive market
- 9.1.2 APPLICATION PROCESSOR
- 9.1.2.1 Rising adoption of smart edge devices to boost segmental growth
- 9.1.3 GPU
- 9.1.3.1 Growing use of open-source and flexible AI infrastructure platforms to accelerate adoption
- 9.1.4 AI ACCELERATOR
- 9.1.4.1 Increasing adoption of AI workloads across industrial automation platforms to fuel segmental growth
- 9.1.5 DSP
- 9.1.5.1 Surging deployment of 5G infrastructure and autonomous systems to spur demand
- 9.1.6 SECURITY PROCESSORS
- 9.1.6.1 Rising cybersecurity requirements across verticals to spike deployment
- 9.1.7 MCU
- 9.1.7.1 Growing deployment of edge AI, TinyML, and intelligent IoT applications to stimulate segmental growth
- 9.1.8 FPGA
- 9.1.8.1 Increasing focus on edge intelligence and low-power computing to support segmental growth
- 9.1.9 STORAGE CONTROLLER
- 9.1.9.1 Ability to manage data transfer, error correction, security, and storage virtualization workloads to boost adoption
- 9.1.1 CPU (GENERAL PURPOSE)
10 RISC-V MARKET, BY OFFERING
- 10.1 INTRODUCTION
- 10.2 RISC-V IP
- 10.2.1 RISC-V IP ROYALTIES
- 10.2.1.1 Elevating adoption of customizable, domain-optimized, and application-specific processors to support segmental growth
- 10.2.2 RISC-V IP LICENSING
- 10.2.2.1 Growing inclination toward accelerating chip development and reducing design complexity to boost segmental growth
- 10.2.1 RISC-V IP ROYALTIES
- 10.3 RISC-V SOFTWARE
- 10.3.1 DESIGN & VERIFICATION SOFTWARE
- 10.3.1.1 Greater focus on reducing chip design errors and improving reliability to escalate demand
- 10.3.2 DEVELOPMENT TOOLCHAINS & IDE SOFTWARE
- 10.3.2.1 Ability to validate software, debug issues, and assess system performance across hardware platforms to elevate adoption
- 10.3.3 OPERATING SYSTEMS & SYSTEM SOFTWARE
- 10.3.3.1 Increasing adoption of open-standard processor architectures to strengthen segmental growth
- 10.3.4 APPLICATION & MIDDLEWARE SOFTWARE
- 10.3.4.1 Growing deployment of RISC-V processors across networking, IoT, and edge AI applications to fuel segmental growth
- 10.3.5 SECURITY SOFTWARE
- 10.3.5.1 Pressing need for secure and trusted computing platforms to foster segmental growth
- 10.3.1 DESIGN & VERIFICATION SOFTWARE
11 RISC-V MARKET, BY BIT ARCHITECTURE
- 11.1 INTRODUCTION
- 11.2 32-BIT
- 11.2.1 OPTIMIZED SILICON FOOTPRINT AND ENHANCED POWER EFFICIENCY TO ACCELERATE ADOPTION IN BATTERY-OPERATED DEVICES
- 11.3 64-BIT
- 11.3.1 COMPETENCY IN HANDLING LARGER WORKLOADS AND MORE COMPLEX SOFTWARE STACKS TO BOOST DEMAND
- 11.4 128-BIT
- 11.4.1 SURGING AI INFRASTRUCTURE INVESTMENTS TO FACILITATE SEGMENTAL GROWTH
12 RISC-V MARKET, BY APPLICATION
- 12.1 INTRODUCTION
- 12.2 INDUSTRIAL
- 12.2.1 INCREASING DEPLOYMENT OF ROBOTICS AND EDGE COMPUTING ACROSS INDUSTRIAL PLANTS TO CREATE GROWTH POTENTIAL
- 12.3 AUTOMOTIVE
- 12.3.1 INCREASING INVESTMENTS IN AUTONOMOUS DRIVING CHIPS AND V2X COMMUNICATION PLATFORMS TO SUPPORT MARKET GROWTH
- 12.4 NETWORKING
- 12.4.1 ELEVATING DEPLOYMENT OF 5G AND 6G INFRASTRUCTURE AND SOFTWARE-DEFINED NETWORKING TO FOSTER MARKET GROWTH
- 12.5 COMPUTER
- 12.5.1 ADVANCING STRATEGIES FOR ENERGY-EFFICIENT COMPUTING AND SOVEREIGN SEMICONDUCTOR DEVELOPMENT TO DRIVE MARKET
- 12.6 CONSUMER
- 12.6.1 RISING DEMAND FOR SMART ELECTRONICS AND CONNECTED HOME ECOSYSTEMS TO SUPPORT MARKET EXPANSION
- 12.7 OTHER APPLICATIONS
13 RISC-V MARKET, BY REGION
- 13.1 INTRODUCTION
- 13.2 NORTH AMERICA
- 13.2.1 US
- 13.2.1.1 Prominent presence of leading RISC-V IP vendors, hyperscalers, and semiconductor designers to support market growth
- 13.2.2 CANADA
- 13.2.2.1 Rising investments in AI infrastructure and semiconductor R&D to offer lucrative growth opportunities
- 13.2.3 MEXICO
- 13.2.3.1 Large manufacturing plants of automotive and electronics companies to support market growth
- 13.2.1 US
- 13.3 EUROPE
- 13.3.1 UK
- 13.3.1.1 Robust semiconductor ecosystem and greater focus on embedded software development to foster market growth
- 13.3.2 GERMANY
- 13.3.2.1 High demand for automotive-grade microcontrollers, secure processors, and AI-enabled embedded systems by automakers to drive market
- 13.3.3 FRANCE
- 13.3.3.1 Growing importance of secure and customizable processors in avionics and satellite systems to promote market growth
- 13.3.4 ITALY
- 13.3.4.1 Escalating adoption of Industry 4.0, robotics, and smart manufacturing technologies to accelerate market growth
- 13.3.5 SPAIN
- 13.3.5.1 Rapid expansion of electric vehicle manufacturing facilities and connected mobility platforms to spur demand
- 13.3.6 REST OF EUROPE
- 13.3.1 UK
- 13.4 ASIA PACIFIC
- 13.4.1 CHINA
- 13.4.1.1 National semiconductor localization and industrial digitalization policies to elevate demand
- 13.4.2 JAPAN
- 13.4.2.1 Increasing compute requirements in smart manufacturing applications to unlock growth opportunities
- 13.4.3 INDIA
- 13.4.3.1 Rising focus on development of locally designed semiconductors and microcontrollers to strength market expansion
- 13.4.4 SOUTH KOREA
- 13.4.4.1 Expansion of advanced semiconductor fabrication capabilities to expedite market growth
- 13.4.5 TAIWAN
- 13.4.5.1 Escalating demand for heterogeneous computing and edge AI hardware to fuel market growth
- 13.4.6 REST OF ASIA PACIFIC
- 13.4.1 CHINA
- 13.5 ROW
- 13.5.1 MIDDLE EAST
- 13.5.1.1 GCC
- 13.5.1.1.1 UAE
- 13.5.1.1.1.1 Smart city deployments, AI infrastructure investments, and expansion of connected mobility systems to expand market reach
- 13.5.1.1.2 Saudi Arabia
- 13.5.1.1.2.1 Emphasis on digital economy expansion to drive market
- 13.5.1.1.3 Rest of GCC
- 13.5.1.1.1 UAE
- 13.5.1.2 Rest of Middle East
- 13.5.1.1 GCC
- 13.5.2 AFRICA
- 13.5.2.1 Increasing adoption of low-cost digital infrastructure and IoT-enabled services to support market expansion
- 13.5.3 SOUTH AMERICA
- 13.5.3.1 Increasing implementation of smart agriculture solutions to offer lucrative growth opportunities
- 13.5.1 MIDDLE EAST
14 COMPETITIVE LANDSCAPE
- 14.1 OVERVIEW
- 14.2 KEY PLAYER COMPETITIVE STRATEGIES/RIGHT TO WIN, 2022-2026
- 14.3 MARKET SHARE ANALYSIS, 2025
- 14.4 REVENUE ANALYSIS, 2022-2025
- 14.5 COMPANY VALUATION AND FINANCIAL METRICS
- 14.6 PRODUCT/BRAND COMPARISON
- 14.6.1 SIFIVE, INC. (US)
- 14.6.2 ANDES TECHNOLOGY CORPORATION (TAIWAN)
- 14.6.3 CODASIP (GERMANY)
- 14.6.4 GLOBALFOUNDRIES (US)
- 14.6.5 IMAGINATION TECHNOLOGIES (UK)
- 14.7 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 14.7.1 STARS
- 14.7.2 EMERGING LEADERS
- 14.7.3 PERVASIVE PLAYERS
- 14.7.4 PARTICIPANTS
- 14.7.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 14.7.5.1 Region footprint
- 14.7.5.2 Offering footprint
- 14.7.5.3 Bit architecture footprint
- 14.7.5.4 Application footprint
- 14.8 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 14.8.1 PROGRESSIVE COMPANIES
- 14.8.2 RESPONSIVE COMPANIES
- 14.8.3 DYNAMIC COMPANIES
- 14.8.4 STARTING BLOCKS
- 14.8.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 14.8.5.1 Detailed list of key startups/SMEs
- 14.8.5.2 Competitive benchmarking of key startups/SMEs
- 14.9 COMPETITIVE SCENARIO
- 14.9.1 PRODUCT LAUNCHES
- 14.9.2 DEALS
15 COMPANY PROFILES
- 15.1 KEY PLAYERS
- 15.1.1 SIFIVE, INC.
- 15.1.1.1 Business overview
- 15.1.1.2 Products/Solutions/Services offered
- 15.1.1.3 Recent developments
- 15.1.1.3.1 Product launches
- 15.1.1.3.2 Deals
- 15.1.1.4 MnM view
- 15.1.1.4.1 Key strengths
- 15.1.1.4.2 Strategic choices
- 15.1.1.4.3 Weaknesses and competitive threats
- 15.1.2 ANDES TECHNOLOGY CORPORATION
- 15.1.2.1 Business overview
- 15.1.2.2 Products/Solutions/Services offered
- 15.1.2.3 Recent developments
- 15.1.2.3.1 Product launches
- 15.1.2.3.2 Deals
- 15.1.2.4 MnM view
- 15.1.2.4.1 Key strengths
- 15.1.2.4.2 Strategic choices
- 15.1.2.4.3 Weaknesses and competitive threats
- 15.1.3 CODASIP
- 15.1.3.1 Business overview
- 15.1.3.2 Products/Solutions/Services offered
- 15.1.3.3 Recent developments
- 15.1.3.3.1 Product launches
- 15.1.3.3.2 Deals
- 15.1.3.4 MnM view
- 15.1.3.4.1 Key strengths
- 15.1.3.4.2 Strategic choices
- 15.1.3.4.3 Weaknesses and competitive threats
- 15.1.4 GLOBALFOUNDRIES
- 15.1.4.1 Business overview
- 15.1.4.2 Products/Solutions/Services offered
- 15.1.4.3 Recent developments
- 15.1.4.3.1 Deals
- 15.1.4.4 MnM view
- 15.1.4.4.1 Key strengths
- 15.1.4.4.2 Strategic choices
- 15.1.4.4.3 Weaknesses and competitive threats
- 15.1.5 IMAGINATION TECHNOLOGIES
- 15.1.5.1 Business overview
- 15.1.5.2 Products/Solutions/Services offered
- 15.1.5.3 Recent developments
- 15.1.5.3.1 Product launches
- 15.1.5.3.2 Deals
- 15.1.5.4 MnM view
- 15.1.5.4.1 Key strengths
- 15.1.5.4.2 Strategic choices
- 15.1.5.4.3 Weaknesses and competitive threats
- 15.1.6 TENSTORRENT
- 15.1.6.1 Business overview
- 15.1.6.2 Products/Solutions/Services offered
- 15.1.6.3 Recent developments
- 15.1.6.3.1 Product launches
- 15.1.6.3.2 Deals
- 15.1.7 SHANGHAI STARFIVE SEMICONDUCTOR CO., LTD.
- 15.1.7.1 Business overview
- 15.1.7.2 Products/Solutions/Services offered
- 15.1.7.3 Recent developments
- 15.1.7.3.1 Product launches
- 15.1.7.3.2 Deals
- 15.1.8 EFINIX
- 15.1.8.1 Business overview
- 15.1.8.2 Products/Solutions/Services offered
- 15.1.8.3 Recent developments
- 15.1.8.3.1 Product launches
- 15.1.8.3.2 Deals
- 15.1.9 NUCLEI SYSTEM
- 15.1.9.1 Business overview
- 15.1.9.2 Products/Solutions/Services offered
- 15.1.9.3 Recent developments
- 15.1.9.3.1 Deals
- 15.1.10 SEMIDYNAMICS
- 15.1.10.1 Business overview
- 15.1.10.2 Products/Solutions/Services offered
- 15.1.10.3 Recent developments
- 15.1.10.3.1 Product launches
- 15.1.10.3.2 Deals
- 15.1.1 SIFIVE, INC.
- 15.2 OTHER PLAYERS
- 15.2.1 ALIBABA GROUP
- 15.2.2 CORTUS
- 15.2.3 SYNTACORE
- 15.2.4 BLUESPEC
- 15.2.5 LATTICE SEMICONDUCTOR
- 15.2.6 SEGGER
- 15.2.7 IAR
- 15.2.8 WIND RIVER
- 15.2.9 LAUTERBACH GMBH
- 15.2.10 SIEMENS
- 15.2.11 CADENCE DESIGN SYSTEMS, INC.
- 15.2.12 MICROCHIP TECHNOLOGY INC.
- 15.2.13 RENESAS ELECTRONICS CORPORATION
- 15.2.14 SOPHGO
- 15.2.15 GIGADEVICE
16 RESEARCH METHODOLOGY
- 16.1 RESEARCH DATA
- 16.2 SECONDARY AND PRIMARY RESEARCH
- 16.2.1 SECONDARY DATA
- 16.2.1.1 Key data from secondary sources
- 16.2.1.2 List of key secondary sources
- 16.2.2 PRIMARY DATA
- 16.2.2.1 Key data from primary sources
- 16.2.2.2 List of primary interview participants
- 16.2.2.3 Breakdown of primaries
- 16.2.2.4 Key industry insights
- 16.2.1 SECONDARY DATA
- 16.3 MARKET SIZE ESTIMATION
- 16.3.1 BOTTOM-UP APPROACH
- 16.3.2 TOP-DOWN APPROACH
- 16.3.3 MARKET SIZE CALCULATION FOR BASE YEAR
- 16.4 MARKET FORECAST APPROACH
- 16.4.1 BOTTOM-UP APPROACH (SUPPLY SIDE)
- 16.4.2 TOP-DOWN APPROACH (DEMAND SIDE)
- 16.5 DATA TRIANGULATION
- 16.6 FACTOR ANALYSIS
- 16.7 RESEARCH ASSUMPTIONS
- 16.8 RESEARCH LIMITATIONS
- 16.9 RISK ANALYSIS
17 APPENDIX
- 17.1 DISCUSSION GUIDE
- 17.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 17.3 CUSTOMIZATION OPTIONS
- 17.4 RELATED REPORTS
- 17.5 AUTHOR DETAILS
List of Tables
- TABLE 1 RISC-V MARKET: INCLUSIONS AND EXCLUSIONS
- TABLE 2 STRATEGIC FOCUS OF TIER 1/2/3 PLAYERS
- TABLE 3 RISC-V MARKET: PORTER'S FIVE FORCES ANALYSIS
- TABLE 4 GDP PERCENTAGE CHANGE, BY COUNTRY, 2021-2030
- TABLE 5 KEY PARTICIPANTS AND THEIR ROLES IN ECOSYSTEM
- TABLE 6 PRICING RANGE OF RISC-V IP PRODUCTS OFFERED BY KEY PLAYERS, 2025 (USD)
- TABLE 7 PRICING RANGE OF RISC-V IP PRODUCTS, BY REGION, 2022-2025 (USD MILLION)
- TABLE 8 IMPORT DATA FOR HS CODE 854231-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 9 EXPORT DATA FOR HS CODE 847150-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 10 RISC-V MARKET: KEY CONFERENCES AND EVENTS, 2026-2027
- TABLE 11 INTRODUCTION OF RISC-V MICROCONTROLLERS BY RENESAS TO ACCELERATE PROTOTYPE DEVELOPMENT
- TABLE 12 RELEASE OF RISC-V PROCESSOR TO ENABLE MONITORING OF FACTORY OPERATIONS
- TABLE 13 IMPLEMENTATION OF RISC-V ISA EXTENSIONS BY ANDES TECHNOLOGY TO ENSURE EFFICIENT SOC DESIGN
- TABLE 14 US-ADJUSTED RECIPROCAL TARIFF RATES, 2024
- TABLE 15 EVOLUTION OF RISC-V TECHNOLOGIES
- TABLE 16 LIST OF APPLIED/GRANTED PATENTS RELATED TO RISC-V ARCHITECTURE, JANUARY 2025-JANUARY 2026
- TABLE 17 KEY USE CASES AND MARKET OPPORTUNITIES
- TABLE 18 RISC-V MARKET: CASE STUDIES RELATED TO AI IMPLEMENTATION
- TABLE 19 INTERCONNECTED/ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- TABLE 20 NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 21 EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 22 ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 23 ROW: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 24 REGULATORY STANDARDS
- TABLE 25 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP 3 APPLICATIONS (%)
- TABLE 26 KEY BUYING CRITERIA FOR TOP 3 APPLICATIONS
- TABLE 27 APPLICATION-SPECIFIC UNMET NEEDS IN RISC-V MARKET
- TABLE 28 RISC-V-BASED SEMICONDUCTOR MARKET, BY TYPE, 2022-2025 (USD THOUSAND)
- TABLE 29 RISC-V-BASED SEMICONDUCTOR MARKET, BY TYPE, 2026-2032 (USD THOUSAND)
- TABLE 30 RISC-V-BASED SEMICONDUCTOR MARKET, BY TYPE, 2022-2025 (THOUSAND UNITS)
- TABLE 31 RISC-V-BASED SEMICONDUCTOR MARKET, BY TYPE, 2026-2032 (THOUSAND UNITS)
- TABLE 32 RISC-V MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 33 RISC-V MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 34 RISC-V IP: RISC-V MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 35 RISC-V IP: RISC-V MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 36 RISC-V SOFTWARE: RISC-V MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 37 RISC-V SOFTWARE: RISC-V MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 38 RISC-V MARKET, BY BIT ARCHITECTURE, 2022-2025 (USD MILLION)
- TABLE 39 RISC-V MARKET, BY BIT ARCHITECTURE, 2026-2032 (USD MILLION)
- TABLE 40 RISC-V MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 41 RISC-V MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 42 INDUSTRIAL: RISC-V MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 43 INDUSTRIAL: RISC-V MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 44 INDUSTRIAL: RISC-V MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 45 INDUSTRIAL: RISC-V MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 46 INDUSTRIAL: RISC-V MARKET IN NORTH AMERICA, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 47 INDUSTRIAL: RISC-V MARKET IN NORTH AMERICA, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 48 INDUSTRIAL: RISC-V MARKET IN EUROPE, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 49 INDUSTRIAL: RISC-V MARKET IN EUROPE, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 50 INDUSTRIAL: RISC-V MARKET IN ASIA PACIFIC, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 51 INDUSTRIAL: RISC-V MARKET IN ASIA PACIFIC, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 52 INDUSTRIAL: RISC-V MARKET IN ROW, BY REGION, 2022-2025 (USD MILLION)
- TABLE 53 INDUSTRIAL: RISC-V MARKET IN ROW, BY REGION, 2026-2032 (USD MILLION)
- TABLE 54 AUTOMOTIVE: RISC-V MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 55 AUTOMOTIVE: RISC-V MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 56 AUTOMOTIVE: RISC-V MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 57 AUTOMOTIVE: RISC-V MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 58 AUTOMOTIVE: RISC-V MARKET IN NORTH AMERICA, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 59 AUTOMOTIVE: RISC-V MARKET IN NORTH AMERICA, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 60 AUTOMOTIVE: RISC-V MARKET IN EUROPE, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 61 AUTOMOTIVE: RISC-V MARKET IN EUROPE, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 62 AUTOMOTIVE: RISC-V MARKET IN ASIA PACIFIC, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 63 AUTOMOTIVE: RISC-V MARKET IN ASIA PACIFIC, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 64 AUTOMOTIVE: RISC-V MARKET IN ROW, BY REGION, 2022-2025 (USD MILLION)
- TABLE 65 AUTOMOTIVE: RISC-V MARKET IN ROW, BY REGION, 2026-2032 (USD MILLION)
- TABLE 66 NETWORKING: RISC-V MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 67 NETWORKING: RISC-V MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 68 NETWORKING: RISC-V MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 69 NETWORKING: RISC-V MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 70 NETWORKING: RISC-V MARKET IN NORTH AMERICA, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 71 NETWORKING: RISC-V MARKET IN NORTH AMERICA, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 72 NETWORKING: RISC-V MARKET IN EUROPE, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 73 NETWORKING: RISC-V MARKET IN EUROPE, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 74 NETWORKING: RISC-V MARKET IN ASIA PACIFIC, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 75 NETWORKING: RISC-V MARKET IN ASIA PACIFIC, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 76 NETWORKING: RISC-V MARKET IN ROW, BY REGION, 2022-2025 (USD MILLION)
- TABLE 77 NETWORKING: RISC-V MARKET IN ROW, BY REGION, 2026-2032 (USD MILLION)
- TABLE 78 COMPUTER: RISC-V MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 79 COMPUTER: RISC-V MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 80 COMPUTER: RISC-V MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 81 COMPUTER: RISC-V MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 82 COMPUTER: RISC-V MARKET IN NORTH AMERICA, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 83 COMPUTER: RISC-V MARKET IN NORTH AMERICA, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 84 COMPUTER: RISC-V MARKET IN EUROPE, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 85 COMPUTER: RISC-V MARKET IN EUROPE, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 86 COMPUTER: RISC-V MARKET IN ASIA PACIFIC, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 87 COMPUTER: RISC-V MARKET IN ASIA PACIFIC, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 88 COMPUTER: RISC-V MARKET IN ROW, BY REGION, 2022-2025 (USD MILLION)
- TABLE 89 COMPUTER: RISC-V MARKET IN ROW, BY REGION, 2026-2032 (USD MILLION)
- TABLE 90 CONSUMER: RISC-V MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 91 CONSUMER: RISC-V MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 92 CONSUMER: RISC-V MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 93 CONSUMER: RISC-V MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 94 CONSUMER: RISC-V MARKET IN NORTH AMERICA, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 95 CONSUMER: RISC-V MARKET IN NORTH AMERICA, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 96 CONSUMER: RISC-V MARKET IN EUROPE, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 97 CONSUMER: RISC-V MARKET IN EUROPE, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 98 CONSUMER: RISC-V MARKET IN ASIA PACIFIC, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 99 CONSUMER: RISC-V MARKET IN ASIA PACIFIC, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 100 CONSUMER: RISC-V MARKET IN ROW, BY REGION, 2022-2025 (USD MILLION)
- TABLE 101 CONSUMER: RISC-V MARKET IN ROW, BY REGION, 2026-2032 (USD MILLION)
- TABLE 102 OTHER APPLICATIONS: RISC-V MARKET, BY OFFERING, 2022-2025 (USD MILLION)
- TABLE 103 OTHER APPLICATIONS: RISC-V MARKET, BY OFFERING, 2026-2032 (USD MILLION)
- TABLE 104 OTHER APPLICATIONS: RISC-V MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 105 OTHER APPLICATIONS: RISC-V MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 106 OTHER APPLICATIONS: RISC-V MARKET IN NORTH AMERICA, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 107 OTHER APPLICATIONS: RISC-V MARKET IN NORTH AMERICA, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 108 OTHER APPLICATIONS: RISC-V MARKET IN EUROPE, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 109 OTHER APPLICATIONS: RISC-V MARKET IN EUROPE, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 110 OTHER APPLICATIONS: RISC-V MARKET IN ASIA PACIFIC, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 111 OTHER APPLICATIONS: RISC-V MARKET IN ASIA PACIFIC, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 112 OTHER APPLICATIONS: RISC-V MARKET IN ROW, BY REGION, 2022-2025 (USD MILLION)
- TABLE 113 OTHER APPLICATIONS: RISC-V MARKET IN ROW, BY REGION, 2026-2032 (USD MILLION)
- TABLE 114 RISC-V MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 115 RISC-V MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 116 NORTH AMERICA: RISC-V MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 117 NORTH AMERICA: RISC-V MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 118 NORTH AMERICA: RISC-V MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 119 NORTH AMERICA: RISC-V MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 120 US: RISC-V MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 121 US: RISC-V MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 122 CANADA: RISC-V MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 123 CANADA: RISC-V MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 124 MEXICO: RISC-V MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 125 MEXICO: RISC-V MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 126 EUROPE: RISC-V MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 127 EUROPE: RISC-V MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 128 EUROPE: RISC-V MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 129 EUROPE: RISC-V MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 130 UK: RISC-V MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 131 UK: RISC-V MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 132 GERMANY: RISC-V MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 133 GERMANY: RISC-V MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 134 FRANCE: RISC-V MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 135 FRANCE: RISC-V MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 136 ITALY: RISC-V MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 137 ITALY: RISC-V MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 138 SPAIN: RISC-V MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 139 SPAIN: RISC-V MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 140 REST OF EUROPE: RISC-V MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 141 REST OF EUROPE: RISC-V MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 142 ASIA PACIFIC: RISC-V MARKET BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 143 ASIA PACIFIC: RISC-V MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 144 ASIA PACIFIC: RISC-V MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 145 ASIA PACIFIC: RISC-V MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 146 CHINA: RISC-V MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 147 CHINA: RISC-V MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 148 JAPAN: RISC-V MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 149 JAPAN: RISC-V MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 150 INDIA: RISC-V MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 151 INDIA: RISC-V MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 152 SOUTH KOREA: RISC-V MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 153 SOUTH KOREA: RISC-V MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 154 TAIWAN: RISC-V MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 155 TAIWAN: RISC-V MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 156 REST OF ASIA PACIFIC: RISC-V MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 157 REST OF ASIA PACIFIC: RISC-V MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 158 ROW: RISC-V MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 159 ROW: RISC-V MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 160 ROW: RISC-V MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 161 ROW: RISC-V MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 162 MIDDLE EAST: RISC-V MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 163 MIDDLE EAST: RISC-V MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 164 MIDDLE EAST: RISC-V MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 165 MIDDLE EAST: RISC-V MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 166 GCC: RISC-V MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 167 GCC: RISC-V MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 168 AFRICA: RISC-V MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 169 AFRICA: RISC-V MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 170 SOUTH AMERICA: RISC-V MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 171 SOUTH AMERICA: RISC-V MARKET, BY APPLICATION, 2026-2032 (USD MILLION)
- TABLE 172 RISC-V MARKET: OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS, JANUARY 2022-MAY 2026
- TABLE 173 RISC-V MARKET: DEGREE OF COMPETITION, 2025
- TABLE 174 RISC-V MARKET: REGION FOOTPRINT
- TABLE 175 RISC-V MARKET: OFFERING FOOTPRINT
- TABLE 176 RISC-V MARKET: BIT ARCHITECTURE FOOTPRINT
- TABLE 177 RISC-V MARKET: APPLICATION FOOTPRINT
- TABLE 178 RISC-V MARKET: DETAILED LIST OF KEY STARTUP/SME PLAYERS
- TABLE 179 RISC-V MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
- TABLE 180 RISC-V MARKET: PRODUCT LAUNCHES, JANUARY 2022-JUNE 2026
- TABLE 181 RISC-V MARKET: DEALS, JANUARY 2022-JUNE 2026
- TABLE 182 SIFIVE, INC.: COMPANY OVERVIEW
- TABLE 183 SIFIVE, INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 184 SIFIVE, INC.: PRODUCT LAUNCHES
- TABLE 185 SIFIVE, INC.: DEALS
- TABLE 186 ANDES TECHNOLOGY CORPORATION: COMPANY OVERVIEW
- TABLE 187 ANDES TECHNOLOGY CORPORATION: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 188 ANDES TECHNOLOGY CORPORATION: PRODUCT LAUNCHES
- TABLE 189 ANDES TECHNOLOGY CORPORATION: DEALS
- TABLE 190 CODASIP: COMPANY OVERVIEW
- TABLE 191 CODASIP: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 192 CODASIP: PRODUCT LAUNCHES
- TABLE 193 CODASIP: DEALS
- TABLE 194 GLOBALFOUNDRIES: COMPANY OVERVIEW
- TABLE 195 GLOBALFOUNDRIES: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 196 GLOBALFOUNDRIES: DEALS
- TABLE 197 IMAGINATION TECHNOLOGIES: COMPANY OVERVIEW
- TABLE 198 IMAGINATION TECHNOLOGIES: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 199 IMAGINATION TECHNOLOGIES: PRODUCT LAUNCHES
- TABLE 200 IMAGINATION TECHNOLOGIES: DEALS
- TABLE 201 TENSTORRENT: COMPANY OVERVIEW
- TABLE 202 TENSTORRENT: PRODUCTS/SOLUTIONS/SERVICES OFFERINGS
- TABLE 203 TENSTORRENT: PRODUCT LAUNCHES
- TABLE 204 TENSTORRENT: DEALS
- TABLE 205 SHANGHAI STARFIVE SEMICONDUCTOR CO., LTD.: COMPANY OVERVIEW
- TABLE 206 SHANGHAI STARFIVE SEMICONDUCTOR CO., LTD.: PRODUCTS/SOLUTIONS/ SERVICES OFFERINGS
- TABLE 207 SHANGHAI STARFIVE SEMICONDUCTOR CO., LTD.: PRODUCT LAUNCHES
- TABLE 208 SHANGHAI STARFIVE SEMICONDUCTOR CO., LTD.: DEALS
- TABLE 209 EFINIX: COMPANY OVERVIEW
- TABLE 210 EFINIX: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 211 EFINIX: PRODUCT LAUNCHES
- TABLE 212 EFINIX: DEALS
- TABLE 213 NUCLEI SYSTEM: COMPANY OVERVIEW
- TABLE 214 NUCLEI SYSTEM: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 215 NUCLEI SYSTEM: DEALS
- TABLE 216 SEMIDYNAMICS: COMPANY OVERVIEW
- TABLE 217 SEMIDYNAMICS: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 218 SEMIDYNAMICS: PRODUCT LAUNCHES
- TABLE 219 SEMIDYNAMICS: DEALS
- TABLE 220 MAJOR SECONDARY SOURCES
- TABLE 221 PRIMARY INTERVIEW PARTICIPANTS
- TABLE 222 RISC-V MARKET: RESEARCH ASSUMPTIONS
- TABLE 223 RISC-V MARKET: RISK ANALYSIS
List of Figures
- FIGURE 1 MARKETS COVERED AND REGIONAL SCOPE
- FIGURE 2 MARKET SCENARIO
- FIGURE 3 RISC-V MARKET, 2022-2032
- FIGURE 4 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN RISC-V MARKET (JANUARY 2022-MAY 2026)
- FIGURE 5 DISRUPTIVE TRENDS IMPACTING GROWTH OF RISC-V MARKET
- FIGURE 6 HIGH-GROWTH SEGMENTS IN RISC-V MARKET, 2026-2032
- FIGURE 7 ASIA PACIFIC TO BE FASTEST-GROWING MARKET FOR RISC-V DURING FORECAST PERIOD
- FIGURE 8 GROWING ADOPTION OF OPEN-STANDARD COMPUTING, EDGE AI, AND CUSTOM PROCESSOR ARCHITECTURES TO CREATE OPPORTUNITIES
- FIGURE 9 RISC-V IP SEGMENT TO CAPTURE MAJORITY OF MARKET SHARE IN 2032
- FIGURE 10 64-BIT SEGMENT TO ACCOUNT FOR PROMINENT MARKET SHARE IN 2032
- FIGURE 11 COMPUTER APPLICATIONS TO HOLD LARGEST MARKET SHARE IN 2032
- FIGURE 12 INDIA TO RECORD HIGHEST CAGR IN GLOBAL RISC-V MARKET DURING FORECAST PERIOD
- FIGURE 13 RISC-V MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 14 RISC-V MARKET: IMPACT ANALYSIS OF DRIVERS
- FIGURE 15 RISC-V MARKET: IMPACT ANALYSIS OF RESTRAINTS
- FIGURE 16 RISC-V MARKET: IMPACT ANALYSIS OF OPPORTUNITIES
- FIGURE 17 RISC-V MARKET: IMPACT ANALYSIS OF CHALLENGES
- FIGURE 18 RISC-V MEMBERSHIP GROWTH TREND, 2015-2024
- FIGURE 19 PORTER'S FIVE FORCES ANALYSIS
- FIGURE 20 RISC-V VALUE CHAIN ANALYSIS
- FIGURE 21 RISC-V ECOSYSTEM PARTICIPANTS
- FIGURE 22 IMPORT SCENARIO FOR HS CODE 854231-COMPLIANT PRODUCTS IN TOP 5 COUNTRIES, 2021-2025
- FIGURE 23 EXPORT SCENARIO FOR HS CODE 854231-COMPLIANT PRODUCTS IN TOP 5 COUNTRIES, 2021-2025
- FIGURE 24 TRENDS AND DISRUPTIONS INFLUENCING CUSTOMER BUSINESS
- FIGURE 25 INVESTMENT AND FUNDING SCENARIO, JANUARY 2022-MAY 2026
- FIGURE 26 RISC-V MARKET: PATENT ANALYSIS, 2016-2025
- FIGURE 27 RISC-V MARKET: FACTORS INFLUENCING DECISION-MAKING
- FIGURE 28 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP 3 APPLICATIONS
- FIGURE 29 KEY BUYING CRITERIA FOR TOP 3 APPLICATIONS
- FIGURE 30 ADOPTION BARRIERS AND INTERNAL CHALLENGES RELATED TO RISC-V ARCHITECTURE
- FIGURE 31 MCU SEGMENT TO HOLD LARGEST MARKET SHARE IN 2032
- FIGURE 32 RISC-V IP SEGMENT TO HOLD LARGER MARKET SHARE IN 2032
- FIGURE 33 64-BIT SEGMENT TO HOLD LARGEST MARKET SHARE IN 2032
- FIGURE 34 COMPUTER APPLICATIONS TO HOLD MAJORITY OF MARKET SHARE IN 2032
- FIGURE 35 ASIA PACIFIC TO DOMINATE RISC-V MARKET THROUGHOTU FORECAST PERIOD
- FIGURE 36 NORTH AMERICA: RISC-V MARKET SNAPSHOT
- FIGURE 37 EUROPE: RISC-V MARKET SNAPSHOT
- FIGURE 38 ASIA PACIFIC: RISC-V MARKET SNAPSHOT
- FIGURE 39 ROW: AI DATACENTER MARKET SNAPSHOT
- FIGURE 40 MARKET SHARE ANALYSIS OF COMPANIES OFFERING RISC-V IP & SOFTWARE SOLUTIONS, 2025
- FIGURE 41 REVENUE ANALYSIS OF TOP 5 PLAYERS, 2022-2025
- FIGURE 42 COMPANY VALUATION
- FIGURE 43 FINANCIAL METRICS (EV/EBITDA)
- FIGURE 44 PRODUCT/BRAND COMPARISON ANALYSIS
- FIGURE 45 RISC-V MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- FIGURE 46 RISC-V MARKET: COMPANY FOOTPRINT
- FIGURE 47 RISC-V MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
- FIGURE 48 ANDES TECHNOLOGY CORPORATION: COMPANY SNAPSHOT
- FIGURE 49 GLOBALFOUNDRIES: COMPANY SNAPSHOT
- FIGURE 50 RISC-V MARKET: RESEARCH DESIGN
- FIGURE 51 RISC-V MARKET: RESEARCH APPROACH
- FIGURE 52 DATA CAPTURED FROM SECONDARY SOURCES
- FIGURE 53 DATA CAPTURED FROM PRIMARY SOURCES
- FIGURE 54 BREAKDOWN OF PRIMARY INTERVIEWS: BY COMPANY TYPE, DESIGNATION, AND REGION
- FIGURE 55 CORE FINDINGS FROM INDUSTRY EXPERTS
- FIGURE 56 RISC-V MARKET: RESEARCH FLOW
- FIGURE 57 RISC-V MARKET: BOTTOM-UP APPROACH
- FIGURE 58 RISC-V MARKET: TOP-DOWN APPROACH
- FIGURE 59 RISC-V MARKET SIZE ESTIMATION (SUPPLY SIDE)
- FIGURE 60 RISC-V MARKET: DATA TRIANGULATION
- FIGURE 61 RISC-V MARKET: RESEARCH LIMITATIONS


