

 |
市場調查報告書
商品編碼
2101870
RISC-V市場商業機會、成長要素、產業趨勢分析及2026-2035年預測RISC-V Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

2025 年全球 RISC-V 市場價值為 23 億美元,預計到 2035 年將以 31.3% 的複合年成長率成長至 347 億美元。
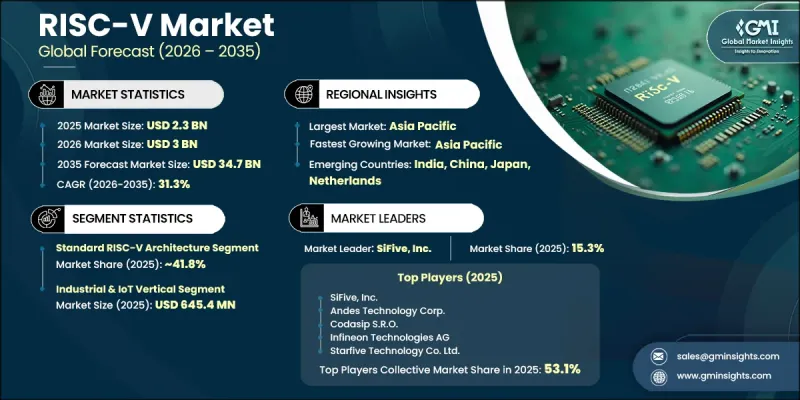
隨著半導體產業擴大採用開放標準、免版稅的處理器架構來滿足下一代運算需求,RISC-V 市場正經歷快速成長。人工智慧、邊緣運算、嵌入式系統和先進半導體開發等領域對可客製化處理器設計的需求日益成長,為 RISC-V 技術創造了巨大的機會。此外,人們對靈活指令集架構的興趣日益濃厚,這種架構既能支援特定應用處理器的開發,又能消除專有授權成本,這進一步推動了市場成長。國內半導體製造舉措投資的增加以及開放硬體生態系統的擴展也加速了 RISC-V 的商業化應用。軟體開發工具、處理器智慧財產權、作業系統相容性和開發框架的持續改進降低了實施門檻,並促進了 RISC-V 在商業應用中的更廣泛部署。隨著各組織不斷優先考慮處理器客製化、可擴展性和設計柔軟性,RISC-V 正成為專有處理器架構越來越有吸引力的替代方案。預計在整個預測期內,開放處理器生態系統的長期轉型將繼續成為全球 RISC-V 市場持續成長的關鍵驅動力。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 初始市場規模 | 23億美元 |
| 預計金額 | 347億美元 |
| 複合年成長率 | 31.3% |
預計到2025年,標準RISC-V架構市場規模將達到9.638億美元,市佔率為41.8%。該細分市場之所以能保持主導地位,是因為其標準化實現支援廣泛的處理器應用,同時相容於廣泛採用的指令集和成熟的擴展。其柔軟性、擴充性和易整合性持續推動著嵌入式運算、邊緣處理和人工智慧(AI)應用領域的普及。預計在整個預測期內,對能夠支援各種商業工作負載的標準化處理器平台的需求不斷成長,將進一步鞏固該細分市場的主導地位。
預計到2025年,工業與物聯網(IIoT)領域的市場規模將達到6.454億美元。工業自動化、連網型設備和智慧邊緣運算平台的持續擴張,正推動RISC-V處理器在該領域的廣泛應用。企業正日益採用先進的多核心片系統晶片(SoC)解決方案,這些方案能夠在單一整合平台上同時支援即時處理和邊緣智慧。這種向高效能處理架構的演進,在提升營運效率的同時,也實現了更複雜的工業運算能力,從而進一步增強了工業和物聯網應用對RISC-V技術的需求。
預計到2025年,北美RISC-V市場規模將達到5.645億美元,主要得益於半導體創新、客製化處理器開發、研究舉措和先進晶片設計專案投資的增加。商業、工業和高效能運算(HPC)應用領域對開放標準處理器架構的需求不斷成長,並持續鞏固北美在全球RISC-V市場的領先地位。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 影響產業的因素
- 促進因素
- 對開放原始碼和可自訂處理器架構的需求日益成長
- 擴大人工智慧、邊緣運算和機器學習工作負載的應用
- 物聯網、汽車和嵌入式半導體應用領域的擴展
- 政府加大對國內半導體生態系的投資
- 產業潛在風險與挑戰
- 與 ARM 和 x86 相比,此軟體生態系統成熟度較低。
- 由於廠商特定的自訂擴充功能而導致的碎片化
- 市場機遇
- 邊緣人工智慧和智慧互聯設備的快速發展。
- 高效能運算和資料中心對處理器的需求不斷成長。
- 促進因素
- 成長潛力分析
- 監理情勢
- 技術展望
- 最新科技趨勢
- 新興技術
- 價格趨勢分析
- 未來市場趨勢
- 專利分析
- 波特的分析
- PESTLE分析
- 人工智慧和生成式人工智慧對市場的影響
- 價值鏈分析
- 投資與資金籌措分析
- 消費者洞察
第4章 競爭情勢
- 介紹
- 企業市佔率分析:按地區分類
- 北美洲
- 歐洲
- 亞太地區
- 中東和非洲
- 拉丁美洲
- 主要進展
- 重要合作夥伴關係和合作
- 主要併購活動
- 產品創新和新產品發布
- 市場擴大策略
- 競爭定位矩陣
第5章 市場規模及預測:依建築類型分類 2022–2035 年
- 標準 RISC-V 架構
- 客製化 RISC-V 架構
- 可擴充的 RISC-V 架構
第6章 市場規模及預測:依產業分類,2022-2035年
- 家用電子產品
- 車
- 工業物聯網
- 資料中心和高效能運算
- 網路與通訊
- 航太/國防
- 其他
第7章 市場規模與預測:依最終用戶分類,2022-2035年
- 晶片設計公司/IP整合商
- OEM/設備製造商
- 軟體開發者
- 政府和國防機構
- 其他
第8章 市場規模及預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 法國
- 英國
- 荷蘭
- 西班牙
- 義大利
- 亞太地區
- 中國
- 日本
- 韓國
- 印度
- 澳洲
- 中東和非洲
- 沙烏地阿拉伯
- UAE
- 南非
- 拉丁美洲
- 巴西
- 阿根廷
- 墨西哥
第9章:公司簡介
- Andes Technology Corp.
- Bluespec
- Codasip SRO
- IAR Systems AB
- Infineon Technologies AG
- Lattice Semiconductor Corporation
- Microchip Technology Incorporated
- Renesas Electronics Corporation
- SiFive, Inc.
- StarFive Technology Co. Ltd.
The Global RISC-V Market was valued at USD 2.3 billion in 2025 and is estimated to grow at a CAGR of 31.3% to reach USD 34.7 billion by 2035.
The RISC-V market is experiencing rapid growth as the semiconductor industry increasingly adopts open-standard, royalty-free processor architectures to support next-generation computing requirements. Rising demand for customizable processor designs across artificial intelligence, edge computing, embedded systems, and advanced semiconductor development is creating significant opportunities for RISC-V technology. The market is further supported by growing interest in flexible instruction set architectures that eliminate proprietary licensing costs while enabling application-specific processor development. Increasing investments in domestic semiconductor manufacturing initiatives and the expansion of open-hardware ecosystems are also accelerating commercial adoption. Continuous improvements in software development tools, processor intellectual property, operating system compatibility, and development frameworks are reducing implementation barriers and encouraging broader deployment across commercial applications. As organizations continue to prioritize processor customization, scalability, and design flexibility, RISC-V is becoming an increasingly attractive alternative to proprietary processor architectures. This long-term transition toward open processor ecosystems is expected to remain a primary factor driving sustained growth across the global RISC-V market throughout the forecast period.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $2.3 Billion |
| Forecast Value | $34.7 Billion |
| CAGR | 31.3% |
The standard RISC-V architecture segment generated USD 963.8 million in 2025, accounting for 41.8% share. The segment maintains its leading position because standardized implementations support a broad range of processor applications while providing compatibility with widely adopted instruction sets and established extensions. Their flexibility, scalability, and ease of integration continue to drive adoption across embedded computing, edge processing, and artificial intelligence applications. Growing demand for standardized processor platforms capable of supporting diverse commercial workloads is expected to reinforce the segment's market leadership over the forecast period.
The Industrial & IoT segment accounted for USD 645.4 million in 2025. Continued expansion of industrial automation, connected devices, and intelligent edge computing platforms is driving strong adoption of RISC-V processors across this vertical. Organizations are increasingly deploying advanced multi-core system-on-chip solutions capable of supporting both real-time processing and edge intelligence within a single integrated platform. This evolution toward higher-performance processing architectures is improving operational efficiency while enabling more sophisticated industrial computing capabilities, further strengthening demand for RISC-V technology across industrial and IoT applications.
North America RISC-V Market generated USD 564.5 million in 2025, supported by growing investments in semiconductor innovation, custom processor development, research initiatives, and advanced chip design programs. Rising demand for open-standard processor architectures across commercial, industrial, and high-performance computing applications continues to reinforce North America's leadership in the global RISC-V market.
Key companies operating in the Global RISC-V Market include Andes Technology Corp., Bluespec, Codasip S.R.O., IAR Systems AB, Infineon Technologies AG, Lattice Semiconductor Corporation, Microchip Technology Incorporated, Renesas Electronics Corporation, SiFive, Inc., and StarFive Technology Co. Ltd. Companies operating in the RISC-V market are strengthening their market position by investing heavily in processor innovation, software ecosystem development, and customizable chip design solutions. Manufacturers continue to enhance processor performance, improve development tools, and expand intellectual property portfolios to support a broader range of commercial applications. Strategic collaborations with semiconductor companies, technology providers, and system integrators are enabling faster product development and wider adoption of RISC-V-based solutions. Businesses are also focusing on expanding global partnerships, increasing research and development investments, and strengthening engineering capabilities to address evolving customer requirements.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Research approach
- 1.2 Quality commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research trail & confidence scoring
- 1.3.1 Research trail components
- 1.3.2 Scoring components
- 1.4 Data collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Market estimates & forecasts parameters
- 1.8 Forecast model
- 1.8.1 Quantified market impact analysis
- 1.8.1.1 Mathematical impact of growth parameters on forecast
- 1.8.1 Quantified market impact analysis
- 1.9 Research transparency addendum
- 1.9.1 Source attribution framework
- 1.9.2 Quality assurance metrics
- 1.9.3 Our commitment to trust
- 1.10 Market definitions
Chapter 2 Executive Summary
- 2.1 Industry synopsis, 2022 - 2035
- 2.1.1 Industry Vertical trends
- 2.1.2 Architecture Type trends
- 2.1.3 End User trends
- 2.1.4 Regional trends
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising demand for open-source and customizable processor architectures
- 3.2.1.2 Growing adoption of AI, edge computing, and machine learning workloads
- 3.2.1.3 Expansion of IoT, automotive, and embedded semiconductor applications
- 3.2.1.4 Increasing government investment in domestic semiconductor ecosystems
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 Limited software ecosystem maturity compared with ARM and x86
- 3.2.2.2 Fragmentation caused by vendor-specific custom extensions
- 3.2.3 Market opportunities
- 3.2.3.1 Rapid expansion of edge AI and intelligent connected devices
- 3.2.3.2 Increasing adoption in high-performance computing and data center processors
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape (Driven by primary research)
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 MEA
- 3.5 Technology landscape
- 3.5.1 Current technological trends
- 3.5.2 Emerging technologies
- 3.6 Pricing trend analysis (Driven by primary research)
- 3.7 Future market trends
- 3.8 Patent analysis
- 3.9 Porter's analysis
- 3.10 PESTEL analysis
- 3.11 Impact of AI and Generative AI on the market (Driven by primary research)
- 3.12 Value chain analysis (Driven by primary research)
- 3.13 Investment & funding analysis (Driven by primary research)
- 3.14 Consumer insights (Driven by primary research)
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis, by region, 2025
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 Middle East & Africa
- 4.2.5 Latin America
- 4.3 Key developments
- 4.3.1 Key partnerships & collaborations
- 4.3.2 Major M&A activities
- 4.3.3 Product innovations & launches
- 4.3.4 Market expansion strategies
- 4.4 Competitive positioning matrix
Chapter 5 Market Size and Forecast, By Architecture Type 2022 - 2035 (USD Million & units)
- 5.1 Key trends
- 5.2 Standard RISC-V Architecture
- 5.3 Custom RISC-V Architecture
- 5.4 Extensible RISC-V Architecture
Chapter 6 Market Size and Forecast, By Industry Vertical, 2022 - 2035 (USD Million & units)
- 6.1 Key trends
- 6.2 Consumer Electronics
- 6.3 Automotive
- 6.4 Industrial & IoT
- 6.5 Data Centers & HPC
- 6.6 Networking & Telecom
- 6.7 Aerospace & Defense
- 6.8 Others
Chapter 7 Market Size and Forecast, By End User, 2022 - 2035 (USD Million & units)
- 7.1 Key trends
- 7.2 Chip Designers / IP Integrators
- 7.3 OEMs / Device Manufacturers
- 7.4 Software Developers
- 7.5 Government & Defense Agencies
- 7.6 Others
Chapter 8 Market Size and Forecast, By Region, 2022 - 2035 (USD Million & units)
- 8.1 Key trends
- 8.2 North America
- 8.2.1 U.S.
- 8.2.2 Canada
- 8.3 Europe
- 8.3.1 Germany
- 8.3.2 France
- 8.3.3 UK
- 8.3.4 Netherlands
- 8.3.5 Spain
- 8.3.6 Italy
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 Japan
- 8.4.3 South Korea
- 8.4.4 India
- 8.4.5 Australia
- 8.5 Middle East & Africa
- 8.5.1 Saudi Arabia
- 8.5.2 UAE
- 8.5.3 South Africa
- 8.6 Latin America
- 8.6.1 Brazil
- 8.6.2 Argentina
- 8.6.3 Mexico
Chapter 9 Company Profiles
- 9.1 Andes Technology Corp.
- 9.2 Bluespec
- 9.3 Codasip S.R.O.
- 9.4 IAR Systems AB
- 9.5 Infineon Technologies AG
- 9.6 Lattice Semiconductor Corporation
- 9.7 Microchip Technology Incorporated
- 9.8 Renesas Electronics Corporation
- 9.9 SiFive, Inc.
- 9.10 StarFive Technology Co. Ltd.


