


 |
市場調查報告書
商品編碼
2057475
全球阻垢劑市場:按類型、製程類型、應用和地區分類-預測至2031年Antiscalants Market by Type Application (Power & Construction, Oil & Gas, Mining, Municipal Water Treatment & Desalination, Food & Beverage, Chemical & Pharmaceutical, Pulp & Paper), Process Type & Region - Global Forecast to 2031 |
||||||

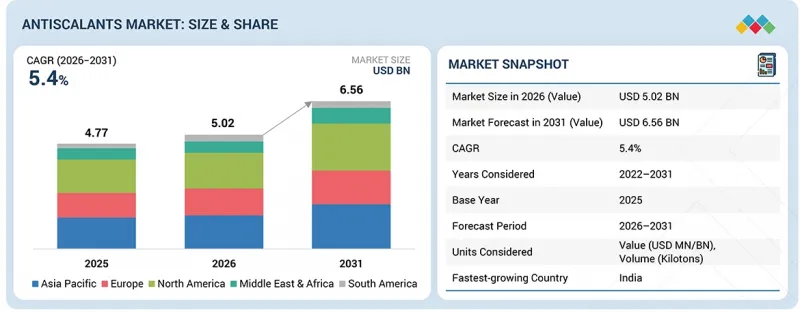
預計到 2031 年,阻垢劑市場規模將從 2026 年的 50.2 億美元成長到 65.6 億美元,預測期內複合年成長率為 5.4%。
| 調查範圍 | |
|---|---|
| 調查期 | 2022-2031 |
| 基準年 | 2025 |
| 預測期 | 2026-2031 |
| 計算單位 | 金額(百萬美元),數量(千噸) |
| 部分 | 按類型、按流程類型、按應用程式、按區域 |
| 目標區域 | 歐洲、北美、亞太地區、中東和非洲、南美 |
在預測期內,該細分市場預計將呈現第二高的成長率。這是因為羧酸鹽/碳酸鹽阻垢劑具有優異的分散性,並在現代水處理系統中發揮有效作用。聚合物配方因其能有效抑制結垢和防止顆粒沉積,成為逆滲透、海水淡化和市政水處理應用的首選。此外,該產品對環境的影響低於傳統的磷酸酯產品,且在各種水質條件下均表現良好,因此進一步推動了市場需求。對永續和環保型水處理方法的日益成長的需求,正在促進各行業對羧酸鹽阻垢劑的應用。
“從類型上看,晶體改性類型是以金額為準成長速度第二快的細分市場。”
結晶型阻垢劑市場正經歷最快的成長,其市場價值也因此成為第二大重要製程類型。此機制透過高效的系統去除沉積物,同時保持系統清潔和運作效率。隨著對運作性能和維護成本降低的需求,結晶技術在逆滲透系統、冷卻系統和工業水處理設施中的應用日益廣泛。由於該系統能夠有效運作各種水質和水處理流程,其市場覆蓋範圍也不斷擴大。在工業領域,隨著可靠且先進的結垢控制方法的開發,對結晶型阻垢劑的需求也不斷成長。
“從應用領域來看,在預測期內,以金額為準第二快的市場是城市水處理和海水淡化。”
由於全球水資源短缺日益嚴重,飲用水需求不斷成長,阻垢劑市場在水處理和海水淡化領域中成長排名第二。各國政府和公共產業正大力投資,在缺水地區建造海水淡化廠和污水處理設施。逆滲透膜,進而提高系統性能並降低維護成本。嚴格的水質法規和污水處理標準正在推動先進處理技術的應用。都市化和人口成長也推動了該細分市場需求的成長,進而顯著擴大了阻垢劑市場。
“從區域差異來看,中東和非洲地區是反規模化市場中以金額為準成長速度第二快的市場。”
中東和非洲地區目前是全球第二大成長最快的阻垢劑市場,預計該地區收入將持續成長,這主要得益於該地區對海水淡化的依賴,以應對水資源短缺和飲用水供應問題。該地區各國正在建造大規模海水淡化廠和水處理廠,從而催生了對先進阻垢劑的需求,這些阻垢劑能夠保護薄膜並提高系統性能。此外,該地區擁有龐大的石油和天然氣產業,也推動了對阻垢劑的需求,以保護運作系統免受水垢積聚的影響。市場擴張主要受兩大因素驅動:工業活動的活性化和公眾節水意識的提升。這些因素使得該地區成為阻垢劑的重要成長市場。
本報告對以下公司概況進行了全面分析:
主要公司包括陶氏化學(美國)、BASF股份公司(德國)、藝康集團(美國)、索萊尼斯(美國)、凱米拉(芬蘭)、科萊恩(瑞士)、賽恩斯科(比利時)、栗田水務工業株式會社(日本)、威立雅集團(法國)和伊塔爾馬奇化學股份公司(義大利)。
調查範圍
本研究報告按類型、製程類型、應用和地區對阻垢劑市場進行細分。研究範圍涵蓋影響阻垢劑市場成長的關鍵因素的詳細資訊,包括成長要素、限制因素、挑戰和機會。對主要產業參與者的深入調查,揭示了他們的業務概況、解決方案和服務、關鍵策略、協議和夥伴關係關係。報告還涵蓋了阻垢劑市場的產品發布、併購以及最新發展動態。此外,報告還對阻垢劑市場生態系統中的新興新創公司進行了競爭考察。
購買本報告的理由:
本報告透過提供整體阻垢劑市場及其細分市場的近似銷售數據,幫助市場領導和新參與企業。它有助於相關人員了解競爭格局,更好地定位自身業務,並獲得更深入的洞察,從而製定合適的打入市場策略。此外,本報告還幫助相關人員了解市場趨勢,並提供關鍵市場促進因素、限制因素、挑戰和機會的資訊。
本報告深入分析了以下幾點:
- 分析關鍵促進因素(對水處理解決方案的需求不斷成長、薄膜技術的發展)、阻礙因素(對化學排放的環境問題、替代技術的可用性)、機會(開發環保配方、新興市場擴張)和挑戰(原料價格波動、不同水質下的性能差異)進行分析。
- 產品開發與創新:深入了解阻垢劑市場的未來技術、研發活動和服務推出。
- 市場發展:提供盈利市場的全面資訊。本報告分析了不同地區的阻垢劑市場。
- 市場多元化:有關阻垢劑市場的服務、未開發地區、最新趨勢和投資的全面資訊。
- 競爭分析:對陶氏化學(美國)、巴斯夫股份公司(德國)、BASF集團(美國)、索萊尼斯(美國)、凱米拉(芬蘭)、科萊恩(瑞士)、賽恩斯科(比利時)、栗田水務工業株式會社(日本)、威立雅集團(法國)和伊塔爾馬奇化學股份、市場佔有率(義大利市場佔有率)等主要戰略服務和市場成長。
目錄
第1章:引言
第2章執行摘要
第3章重要考察
第4章 市場概覽
- 市場動態
- 促進因素
- 抑制因子
- 機會
- 任務
- 未滿足的需求和未開發的領域
- 相互關聯的市場與跨產業機遇
- 新的經營模式和生態系統的變化
- 一級/二級/三級公司的策略性舉措
- 波特五力分析
- 價值鏈分析
- 生態系分析
- 價格分析
- 總體經濟指標
- 2025年美國關稅對除垢劑市場的影響
- 貿易分析
- 影響客戶業務的趨勢/顛覆性因素
- 投資和資金籌措場景
- 案例研究分析
- 重要會議和活動
第5章:技術進步、人工智慧的影響、專利、創新與未來應用
- 技術分析
- 技術/產品藍圖
- 專利分析
- 未來應用
- 人工智慧/生成式人工智慧對反擴展代理市場的影響
第6章:監理情勢與永續性舉措
- 當地法規和合規性
- 對永續性的承諾
- 監理政策和永續性舉措的影響
- 認證、標籤檢視和環境標準
第7章:顧客趨勢與購買行為
- 決策流程
- 主要相關人員和採購標準
- 實施障礙和內部挑戰
- 各個終端用戶產業中尚未滿足的需求
- 市場盈利
第8章:阻垢劑市場(按類型分類)
- 磷酸酯
- 羧酸鹽/碳酸鹽
- 磺酸鹽
- 氟化物
- 其他
第9章:阻垢劑市場(依製程類型分類)
- 閾值抑制劑
- 晶體結構的改變
- 分散
- 其他
第10章:阻垢劑市場(依應用領域分類)
- 電力與建築
- 礦業
- 石油和天然氣
- 市政水處理和海水淡化
- 食品/飲料
- 化學品和製藥
- 紙漿和造紙
- 其他
第11章:阻垢劑市場(依地區分類)
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 義大利
- 法國
- 英國
- 西班牙
- 其他
- 亞太地區
- 中國
- 日本
- 韓國
- 印度
- 其他
- 中東和非洲
- 海灣合作理事會國家
- 沙烏地阿拉伯
- 卡達
- 阿拉伯聯合大公國
- 其他海灣合作理事會國家
- 其他
- 南美洲
- 巴西
- 阿根廷
- 其他
第12章 競爭格局
- 主要參與企業的策略/優勢,2022-2026 年
- 2023-2025年收入分析
- 2025年市佔率分析
- 企業估值和財務指標
- 品牌/產品對比
- 企業估值矩陣:主要公司,2025 年
- 公司估值矩陣:新創企業/中小企業,2025 年
- 競爭格局
第13章:公司簡介
- 主要參與企業
- DOW
- BASF
- ECOLAB
- SOLENIS
- KEMIRA
- CLARIANT
- SYENSQO
- KURITA WATER INDUSTRIES LTD.
- VEOLIA GROUP
- ITALMATCH CHEMICALS SPA
- 其他公司
- BIOLAB ARABIA LTD. CO.
- DUBICHEM
- REZA INVESTMENT COMPANY LTD.
- ARIES CHEMICAL, INC.
- OVIVO
- AES ARABIA LTD.
- SNF GROUP
- ANGEL CHEMICALS PRIVATE LIMITED
- HYDROVIDA
- ACCEPTA WATER TREATMENT
- KING LEE TECHNOLOGIES
- AMERICAN WATER CHEMICALS, INC.
- SHANDONG KAIRUI CHEMISTRY CO., LTD.
- AXEON WATER
- ACURO ORGANICS LIMITED
第14章調查方法
第15章附錄
The antiscalants market is projected to grow from USD 5.02 billion in 2026 to USD 6.56 billion by 2031, at a CAGR of 5.4% during the forecast period.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2022-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million), Volume (Kilotons) |
| Segments | By Type, Process Type, Application, and Region |
| Regions covered | Europe, North America, Asia Pacific, Middle East & Africa, and South America |
The market will experience its second fastest-growing segment during the forecast period because Carboxylates/carbonates-based antiscalants demonstrate strong dispersion properties, which enable them to work effectively with modern water treatment systems. The polymer-based formulations are the primary choice for reverse osmosis, desalination, and municipal water treatment applications because they effectively control scale formation and prevent particle deposition. The product achieves better performance across different water chemistries while causing less environmental damage than conventional phosphonates, which drives stronger market demand. The growing demand for sustainable, environmentally friendly water treatment methods is driving industries to adopt carboxylate-based antiscalants.
''Based on type, crystal modification type is the second-fastest growing segment, in terms of value.''
The antiscalants market experiences its fastest growth through crystal modification, which generates increasing market value as the second most important process type. The mechanism operates through an efficient system that enables operators to eliminate deposits while maintaining system cleanliness and operational effectiveness. The growing use of crystal modification technology is seen in reverse osmosis systems, cooling systems, and industrial water treatment facilities because these systems require operational performance and reduced maintenance. The system expands its market reach because it can operate effectively across diverse water chemical compositions and various water treatment processes. The need for crystal-modification-based antiscalants is increasing as industries develop reliable, advanced methods to control scale formation.
"Based on application, municipal water treatment & desalination is the second-fastest growing market during the forecast period, in terms of value."
The antiscalants market experiences its second-most rapid growth in municipal water treatment and desalination due to rising global water shortages and increasing demand for potable drinking water. Governments and utilities make substantial financial commitments to build desalination plants and wastewater treatment facilities in areas experiencing water shortages. The reverse osmosis membranes receive essential protection from antiscalants, which also increase system performance while decreasing maintenance expenses. The strict water quality regulations, together with discharge standards, drive the implementation of superior treatment technologies. The antiscalants market experiences significant expansion because urbanization and population growth create rising demand for this market segment.
"Based on region, the Middle East & Africa is the second-fastest-growing market for antiscalants, in terms of value."
The Middle East and Africa region now ranks as the second most rapidly developing antiscalant market, which will generate revenue growth from water shortages and the region's dependence on desalination for drinking water. The countries in the region build substantial desalination facilities and water treatment plants, which create a need for advanced antiscalants that protect membranes and boost system performance. The oil and gas industry operates extensively in the region which increases the need for antiscalants that protect operational systems from scale buildup. The market expansion receives support from two main drivers which are increasing industrial activities and heightened public awareness about water preservation. The region has emerged as a significant developing market for antiscalants because of these factors.
This study has been validated through primary interviews with industry experts globally. These primary sources have been divided into the following three categories:
- By Company Type- Tier 1- 60%, Tier 2- 20%, and Tier 3- 20%
- By Designation- C Level- 33%, Director Level- 33%, and Managers- 34%
- By Region- North America- 20%, Europe- 25%, Asia Pacific- 25%, Middle East & Africa- 15%, and Latin America- 15%
The report provides a comprehensive analysis of several company profiles:
Prominent companies include Dow (US), BASF SE (Germany), Ecolab (US), Solenis (US), Kemira (Finland), Clariant (Switzerland), Syensqo (Belgium), Kurita Water Industries Ltd (Japan), Veolia Group (France), and Italmatch Chemicals SPA (Italy).
Research Coverage
This research report categorizes the antiscalants market by type, process type, application, and region. The scope of the report includes detailed information on the major factors influencing the growth of the antiscalants market, including drivers, restraints, challenges, and opportunities. A thorough examination of the key industry players has been conducted to provide insights into their business overview, solutions and services, key strategies, contracts, partnerships, and agreements. Product launches, mergers and acquisitions, and recent developments in the antiscalants market are all covered. This report includes a competitive analysis of upcoming startups in the antiscalants market ecosystem.
Reasons to buy this report:
The report will help market leaders/new entrants in this market by providing approximate revenue figures for the overall antiscalants market and its subsegments. This report will help stakeholders understand the competitive landscape and gain more insights to position their businesses better and plan suitable go-to-market strategies. The report also helps stakeholders understand the pulse of the market and provides them with information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following pointers:
- Analysis of key drivers (Rising demand for water treatment solutions, Growth of membrane-based technologies), restraints (Environmental concerns over chemical discharge, Availability of alternative technologies), opportunities (Development of eco-friendly formulations, Expansion in emerging markets), and challenges (Fluctuating raw material prices, Performance variability with water chemistry)
- Product Development/Innovation: Detailed insights on upcoming technologies, research & development activities, and service launches in the antiscalants market.
- Market Development: Comprehensive information about lucrative markets-the report analyses the antiscalants market across varied regions.
- Market Diversification: Exhaustive information about services, untapped geographies, recent developments, and investments in the antiscalants market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and service offerings of leading players like Dow (US), BASF SE (Germany), Ecolab (US), Solenis (US), Kemira (Finland), Clariant (Switzerland), Syensqo (Belgium), Kurita Water Industries Ltd (Japan), Veolia Group (France), and Italmatch Chemicals SPA (Italy), among others.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKETS COVERED AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 UNIT CONSIDERED
- 1.6 STAKEHOLDERS
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN ANTISCALANTS MARKET
- 2.4 HIGH GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN ANTISCALANTS MARKET
- 3.2 ANTISCALANTS MARKET, BY TYPE
- 3.3 ANTISCALANTS MARKET, BY PROCESS TYPE
- 3.4 ANTISCALANTS MARKET, BY APPLICATION
- 3.5 ANTISCALANTS MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Increasing water scarcity and growing adoption of desalination and reverse osmosis (RO) technologies
- 4.2.1.2 Increasing wastewater reuse and reclamation projects
- 4.2.1.3 Declining global availability of water, along with increasing demand for clean water
- 4.2.1.4 Stringent water treatment regulations
- 4.2.2 RESTRAINTS
- 4.2.2.1 Volatility in costs of raw materials
- 4.2.2.2 Chemical discharge risks from desalination concentrates
- 4.2.2.3 Growing shift toward green chemistry
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Increasing use of antiscalants in oil & gas applications
- 4.2.3.2 Development of green and biodegradable antiscalants
- 4.2.3.3 Expansion of antiscalants in developing countries
- 4.2.4 CHALLENGES
- 4.2.4.1 Membrane fouling caused by antiscalants
- 4.2.4.2 High-silica and complex water chemistries
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN ANTISCALANTS MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 EMERGING BUSINESS MODELS AND ECOSYSTEM SHIFTS
- 4.5.1 EMERGING BUSINESS MODELS
- 4.5.2 ECOSYSTEM SHIFTS
- 4.6 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
- 4.6.1 KEY MOVES AND STRATEGIC FOCUS
- 4.7 PORTER'S FIVE FORCES ANALYSIS
- 4.7.1 THREAT OF NEW ENTRANTS
- 4.7.2 THREAT OF SUBSTITUTES
- 4.7.3 BARGAINING POWER OF SUPPLIERS
- 4.7.4 BARGAINING POWER OF BUYERS
- 4.7.5 INTENSITY OF COMPETITIVE RIVALRY
- 4.8 VALUE CHAIN ANALYSIS
- 4.8.1 RAW MATERIAL SUPPLIERS
- 4.8.2 MANUFACTURERS
- 4.8.3 DISTRIBUTORS
- 4.8.4 END USERS
- 4.9 ECOSYSTEM ANALYSIS
- 4.10 PRICING ANALYSIS
- 4.10.1 AVERAGE SELLING PRICE OF ANTISCALANTS, BY REGION
- 4.10.2 AVERAGE SELLING PRICE OF ANTISCALANTS, BY KEY PLAYERS
- 4.10.3 AVERAGE SELLING PRICE OF ANTISCALANTS, BY TYPE
- 4.11 MACROECONOMIC INDICATORS
- 4.11.1 GLOBAL GDP TRENDS
- 4.12 IMPACT OF 2025 US TARIFFS ON ANTISCALANTS MARKET
- 4.12.1 INTRODUCTION
- 4.12.2 KEY TARIFF RATES
- 4.12.3 PRICE IMPACT ANALYSIS
- 4.12.4 IMPACT ON COUNTRIES/REGIONS
- 4.12.4.1 North America
- 4.12.4.2 Europe
- 4.12.4.3 Asia Pacific
- 4.12.5 IMPACT ON END-USE INDUSTRIES
- 4.13 TRADE ANALYSIS
- 4.13.1 IMPORT SCENARIO (HS CODE 382499)
- 4.13.2 EXPORT SCENARIO (HS CODE 382499)
- 4.14 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 4.15 INVESTMENT AND FUNDING SCENARIO
- 4.16 CASE STUDY ANALYSIS
- 4.16.1 HUBER GROUP'S USE OF TORAY RUPER ANTISCALANT
- 4.16.2 COMBATING IRON FOULING IN BRACKISH WATER RO SYSTEMS
- 4.16.3 IMPACT OF ROPUR RPI ANTISCALANT AT LOHNEN WATER PLANT
- 4.17 KEY CONFERENCES & EVENTS
5 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 5.1 TECHNOLOGY ANALYSIS
- 5.1.1 KEY TECHNOLOGIES
- 5.1.1.1 Squeeze treatment for antiscalants
- 5.1.1.2 Continuous injection systems
- 5.1.2 COMPLEMENTARY TECHNOLOGIES
- 5.1.2.1 Extended-release scale inhibitor technology
- 5.1.2.2 Biodegradable antiscalant technology
- 5.1.2.3 Dendrimer-based antiscalant technology
- 5.1.3 ADJACENT TECHNOLOGIES
- 5.1.3.1 Electrolytic technology
- 5.1.3.2 Electrochemical technology for scale inhibition
- 5.1.1 KEY TECHNOLOGIES
- 5.2 TECHNOLOGY/PRODUCT ROADMAP
- 5.2.1 SHORT-TERM (2026-2027) | FOUNDATION & EARLY COMMERCIALIZATION
- 5.2.2 MID-TERM (2027-2030) | EXPANSION & STANDARDIZATION
- 5.2.3 LONG-TERM (2030-2035+) | MASS COMMERCIALIZATION & DISRUPTION
- 5.3 PATENT ANALYSIS
- 5.3.1 LEGAL STATUS OF PATENTS
- 5.3.2 JURISDICTION ANALYSIS
- 5.4 FUTURE APPLICATIONS
- 5.4.1 ADVANCED DESALINATION PLANTS
- 5.4.2 WASTEWATER RECYCLING AND REUSE SYSTEMS
- 5.4.3 ZERO LIQUID DISCHARGE (ZLD) SYSTEMS
- 5.4.4 SMART INDUSTRIAL WATER TREATMENT
- 5.4.5 RENEWABLE ENERGY AND GREEN HYDROGEN PLANTS
- 5.5 IMPACT OF AI/GENERATIVE AI ON ANTISCALANTS MARKET
- 5.5.1 TOP USE CASES AND MARKET POTENTIAL
- 5.5.2 BEST PRACTICES IN ANTISCALANTS PROCESSING
- 5.5.3 CASE STUDIES OF AI IMPLEMENTATION IN ANTISCALANTS MARKET
- 5.5.4 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 5.5.5 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN ANTISCALANTS MARKET
6 REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
- 6.1 REGIONAL REGULATIONS AND COMPLIANCE
- 6.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 6.1.2 INDUSTRY STANDARDS
- 6.2 SUSTAINABILITY INITIATIVES
- 6.3 IMPACT OF REGULATORY POLICIES AND SUSTAINABILITY INITIATIVES
- 6.4 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
7 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 7.1 INTRODUCTION
- 7.2 DECISION-MAKING PROCESS
- 7.3 KEY STAKEHOLDERS AND BUYING CRITERIA
- 7.3.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 7.3.2 BUYING CRITERIA
- 7.4 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 7.5 UNMET NEEDS IN VARIOUS END-USE INDUSTRIES
- 7.6 MARKET PROFITABILITY
- 7.6.1 REVENUE POTENTIAL
- 7.6.2 COST DYNAMICS
- 7.6.3 MARGIN OPPORTUNITIES IN KEY END-USE SECTORS
8 ANTISCALANTS MARKET, BY TYPE
- 8.1 INTRODUCTION
- 8.2 PHOSPHONATES
- 8.2.1 EXTENSIVE UTILIZATION OF PHOSPHONATES IN WATER TREATMENT AND DESALINATION INDUSTRY TO DRIVE MARKET
- 8.3 CARBOXYLATES/CARBONATES
- 8.3.1 CONTROL OF SCALE BUILDUP IN HIGH-TEMPERATURE OIL FIELDS AND MINING OPERATIONS TO PROPEL MARKET
- 8.4 SULFONATES
- 8.4.1 USE IN OIL & GAS SECTOR FOR DOWNHOLE CHEMICAL INJECTION AND SQUEEZE OPERATION TO DRIVE MARKET
- 8.5 FLUORIDES
- 8.5.1 REMOVAL OF CHALLENGING SILICATE DEPOSITS IN INDUSTRIAL WATER SYSTEMS TO BOOST MARKET
- 8.6 OTHER TYPES
9 ANTISCALANTS MARKET, BY PROCESS TYPE
- 9.1 INTRODUCTION
- 9.2 THRESHOLD INHIBITOR
- 9.2.1 ECONOMIC ATTRACTIVENESS DUE TO LOW COST TO BOOST MARKET
- 9.3 CRYSTAL MODIFICATION
- 9.3.1 DEMAND FOR ADVANCED SOLUTIONS IN OIL & GAS, POWER GENERATION, WATER TREATMENT, AND MINING SECTORS TO DRIVE MARKET
- 9.4 DISPERSION
- 9.4.1 COMPATIBILITY WITH OTHER WATER TREATMENT CHEMICALS ENABLING INTEGRATED SOLUTIONS TO PROPEL MARKET
- 9.5 OTHER PROCESS TYPES
10 ANTISCALANTS MARKET, BY APPLICATION
- 10.1 INTRODUCTION
- 10.2 POWER & CONSTRUCTION
- 10.2.1 MAINTAINING EQUIPMENT EFFICIENCY AND LIFETIME TO DRIVE MARKET
- 10.3 MINING
- 10.3.1 MITIGATION OF SCALE DEPOSITION IN PIPELINES, DRILLING EQUIPMENT, AND PROCESSING FACILITIES TO BOOST MARKET
- 10.4 OIL & GAS
- 10.4.1 CONTINUOUS PRODUCTION AT OPTIMUM PERFORMANCE AND EFFICIENCY TO PROPEL MARKET GROWTH
- 10.5 MUNICIPAL WATER TREATMENT & DESALINATION
- 10.5.1 REDUCTION IN REQUIREMENT FOR MEMBRANE CLEANING AND OPERATIONAL COSTS TO DRIVE MARKET
- 10.6 FOOD & BEVERAGE
- 10.6.1 EFFICIENCY OF BOILERS, COOLERS, AND SINGLE- AND MULTIPLE-EFFECT EVAPORATORS TO BOOST MARKET
- 10.7 CHEMICAL & PHARMACEUTICAL
- 10.7.1 ACHIEVING OPTIMUM FLOW RATES TO ENABLE PRODUCTIVITY AND HEAT TRANSFER EFFICIENCY TO PROPEL MARKET
- 10.8 PULP & PAPER
- 10.8.1 IMPROVED PAPER QUALITY TO DRIVE MARKET
- 10.9 OTHER APPLICATIONS
- 10.9.1 TEXTILE
- 10.9.2 LEATHER TANNING
- 10.9.3 INDUSTRIAL & INSTITUTIONAL CLEANING
- 10.9.4 HOME CARE
- 10.9.5 ETHANOL PRODUCTION
- 10.9.6 AGRICULTURE
11 ANTISCALANTS MARKET, BY REGION
- 11.1 INTRODUCTION
- 11.2 NORTH AMERICA
- 11.2.1 US
- 11.2.1.1 Increase in oil production activities and rising demand for potable drinking water to drive market
- 11.2.2 CANADA
- 11.2.2.1 Increase in food processing establishments to drive market
- 11.2.3 MEXICO
- 11.2.3.1 Growth of manufacturing sector to boost market
- 11.2.1 US
- 11.3 EUROPE
- 11.3.1 GERMANY
- 11.3.1.1 Maintenance of high treatment standards and environmental integrity to fuel market growth
- 11.3.2 ITALY
- 11.3.2.1 Demand from water-intensive industries to drive market
- 11.3.3 FRANCE
- 11.3.3.1 Well-developed industrial infrastructure to lead to market growth
- 11.3.4 UK
- 11.3.4.1 Government focus on sustainability to support market
- 11.3.5 SPAIN
- 11.3.5.1 Surge in demand for desalinated water to drive market
- 11.3.6 REST OF EUROPE
- 11.3.1 GERMANY
- 11.4 ASIA PACIFIC
- 11.4.1 CHINA
- 11.4.1.1 Demand from oil & gas and mining sectors to drive market
- 11.4.2 JAPAN
- 11.4.2.1 Growth of chemical & pharmaceutical industries to boost demand.
- 11.4.3 SOUTH KOREA
- 11.4.3.1 Government initiatives to promote developments in technology and manufacturing activities to boost market
- 11.4.4 INDIA
- 11.4.4.1 Consistently increasing manufacturing output to fuel market growth
- 11.4.5 REST OF ASIA PACIFIC
- 11.4.1 CHINA
- 11.5 MIDDLE EAST & AFRICA
- 11.5.1 GCC COUNTRIES
- 11.5.2 SAUDI ARABIA
- 11.5.2.1 Government initiatives for desalinated water to boost consumption
- 11.5.3 QATAR
- 11.5.3.1 Reverse osmosis desalination for seawater to contribute to significant demand
- 11.5.4 UAE
- 11.5.4.1 Increasing demand from end-use industries to lead to significant growth
- 11.5.5 REST OF GCC COUNTRIES
- 11.5.6 REST OF MIDDLE EAST & AFRICA
- 11.6 SOUTH AMERICA
- 11.6.1 BRAZIL
- 11.6.1.1 Expanding textile industry and oil & gas exploration to drive market
- 11.6.2 ARGENTINA
- 11.6.2.1 Growing construction sector to propel market
- 11.6.3 REST OF SOUTH AMERICA
- 11.6.1 BRAZIL
12 COMPETITIVE LANDSCAPE
- 12.1 INTRODUCTION
- 12.2 KEY PLAYERS' STRATEGIES/RIGHT TO WIN, 2022-2026
- 12.3 REVENUE ANALYSIS, 2023-2025
- 12.4 MARKET SHARE ANALYSIS, 2025
- 12.4.1 DOW
- 12.4.2 BASF
- 12.4.3 ECOLAB
- 12.4.4 SOLENIS
- 12.4.5 KEMIRA
- 12.5 COMPANY VALUATION AND FINANCIAL METRICS
- 12.6 BRAND/PRODUCT COMPARISON
- 12.7 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 12.7.1 STARS
- 12.7.2 EMERGING LEADERS
- 12.7.3 PERVASIVE PLAYERS
- 12.7.4 PARTICIPANTS
- 12.7.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 12.7.5.1 Company footprint
- 12.7.5.2 Region footprint
- 12.7.5.3 Type footprint
- 12.7.5.4 Application footprint
- 12.7.5.5 Process type footprint
- 12.8 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 12.8.1 PROGRESSIVE COMPANIES
- 12.8.2 RESPONSIVE COMPANIES
- 12.8.3 DYNAMIC COMPANIES
- 12.8.4 STARTING BLOCKS
- 12.8.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 12.8.5.1 Detailed list of key startups/SMEs
- 12.8.5.2 Competitive benchmarking of start-ups/SMEs
- 12.9 COMPETITIVE SCENARIO
- 12.9.1 PRODUCT LAUNCHES
- 12.9.2 DEALS
- 12.9.3 EXPANSIONS
13 COMPANY PROFILES
- 13.1 KEY PLAYERS
- 13.1.1 DOW
- 13.1.1.1 Business overview
- 13.1.1.2 Products/Solutions/Services offered
- 13.1.1.3 MnM view
- 13.1.1.3.1 Right to win
- 13.1.1.3.2 Strategic choices
- 13.1.1.3.3 Weaknesses and competitive threats
- 13.1.2 BASF
- 13.1.2.1 Business overview
- 13.1.2.2 Products/Solutions/Services offered
- 13.1.2.3 MnM view
- 13.1.2.3.1 Right to win
- 13.1.2.3.2 Strategic choices
- 13.1.2.3.3 Weaknesses and competitive threats
- 13.1.3 ECOLAB
- 13.1.3.1 Business overview
- 13.1.3.2 Products/Solutions/Services offered
- 13.1.3.3 MnM view
- 13.1.3.3.1 Right to win
- 13.1.3.3.2 Strategic choices
- 13.1.3.3.3 Weaknesses and competitive threats
- 13.1.4 SOLENIS
- 13.1.4.1 Business overview
- 13.1.4.2 Products/Solutions/Services offered
- 13.1.4.3 Recent developments
- 13.1.4.3.1 Deals
- 13.1.4.4 MnM view
- 13.1.4.4.1 Right to win
- 13.1.4.4.2 Strategic choices
- 13.1.4.4.3 Weaknesses and competitive threats
- 13.1.5 KEMIRA
- 13.1.5.1 Business overview
- 13.1.5.2 Products/Solutions/Services offered
- 13.1.5.3 Recent developments
- 13.1.5.3.1 Deals
- 13.1.5.3.2 Expansions
- 13.1.5.4 MnM view
- 13.1.5.4.1 Right to win
- 13.1.5.4.2 Strategic choices
- 13.1.5.4.3 Weaknesses and competitive threats
- 13.1.6 CLARIANT
- 13.1.6.1 Business overview
- 13.1.6.2 Products/Solutions/Services offered
- 13.1.6.3 Recent developments
- 13.1.6.3.1 Expansions
- 13.1.6.4 MnM view
- 13.1.7 SYENSQO
- 13.1.7.1 Business overview
- 13.1.7.2 Products/Solutions/Services offered
- 13.1.7.3 Recent developments
- 13.1.7.3.1 Deals
- 13.1.7.4 MnM view
- 13.1.8 KURITA WATER INDUSTRIES LTD.
- 13.1.8.1 Business overview
- 13.1.8.2 Products/Solutions/Services offered
- 13.1.8.3 Recent developments
- 13.1.8.3.1 Expansions
- 13.1.8.4 MnM view
- 13.1.9 VEOLIA GROUP
- 13.1.9.1 Business overview
- 13.1.9.2 Products/Solutions/Services offered
- 13.1.9.3 Recent developments
- 13.1.9.3.1 Deals
- 13.1.9.4 MnM view
- 13.1.10 ITALMATCH CHEMICALS S.P.A.
- 13.1.10.1 Business overview
- 13.1.10.2 Products/Solutions/Services offered
- 13.1.10.3 Recent developments
- 13.1.10.3.1 Product launches
- 13.1.10.4 MnM view
- 13.1.1 DOW
- 13.2 OTHER PLAYERS
- 13.2.1 BIOLAB ARABIA LTD. CO.
- 13.2.2 DUBICHEM
- 13.2.3 REZA INVESTMENT COMPANY LTD.
- 13.2.4 ARIES CHEMICAL, INC.
- 13.2.5 OVIVO
- 13.2.6 AES ARABIA LTD.
- 13.2.7 SNF GROUP
- 13.2.8 ANGEL CHEMICALS PRIVATE LIMITED
- 13.2.9 HYDROVIDA
- 13.2.10 ACCEPTA WATER TREATMENT
- 13.2.11 KING LEE TECHNOLOGIES
- 13.2.12 AMERICAN WATER CHEMICALS, INC.
- 13.2.13 SHANDONG KAIRUI CHEMISTRY CO., LTD.
- 13.2.14 AXEON WATER
- 13.2.15 ACURO ORGANICS LIMITED
14 RESEARCH METHODOLOGY
- 14.1 RESEARCH DATA
- 14.1.1 SECONDARY DATA
- 14.1.1.1 List of secondary sources
- 14.1.1.2 Key data from secondary sources
- 14.1.2 PRIMARY DATA
- 14.1.2.1 List of primary interview participants-demand and supply sides
- 14.1.2.2 Key data from primary sources
- 14.1.2.3 Breakdown of primary interviews
- 14.1.2.4 Insights from industry experts
- 14.1.1 SECONDARY DATA
- 14.2 MARKET SIZE ESTIMATION
- 14.2.1 BOTTOM-UP APPROACH
- 14.2.2 TOP-DOWN APPROACH
- 14.3 FORECAST NUMBER CALCULATION
- 14.4 DATA TRIANGULATION
- 14.5 FACTOR ANALYSIS
- 14.6 RESEARCH ASSUMPTIONS
- 14.7 RESEARCH LIMITATIONS AND RISK ASSESSMENT
15 APPENDIX
- 15.1 DISCUSSION GUIDE
- 15.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 15.3 CUSTOMIZATION OPTIONS
- 15.4 RELATED REPORTS
- 15.5 AUTHOR DETAILS
List of Tables
- TABLE 1 ANTISCALANTS MARKET: IMPACT OF PORTER'S FIVE FORCES
- TABLE 2 ANTISCALANTS MARKET: ROLE OF COMPANIES IN ECOSYSTEM
- TABLE 3 AVERAGE SELLING PRICE TREND OF ANTISCALANTS, BY REGION, 2023-2025 (USD/KG)
- TABLE 4 AVERAGE SELLING PRICE OF ANTISCALANTS, OFFERED BY KEY PLAYERS, BY KEY APPLICATIONS, 2025 (USD/KG)
- TABLE 5 AVERAGE SELLING PRICE TREND OF ANTISCALANTS, BY TYPE, 2023-2025 (USD/KG)
- TABLE 6 PROJECTED REAL GDP GROWTH (ANNUAL PERCENT CHANGE) OF KEY COUNTRIES, 2021-2030
- TABLE 7 US-ADJUSTED RECIPROCAL TARIFF RATES
- TABLE 8 IMPORT SCENARIO FOR HS CODE 382499 -COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 9 EXPORT SCENARIO FOR HS CODE 382499 -COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD MILLION)
- TABLE 10 ANTISCALANTS MARKET: CONFERENCES & EVENTS, 2026-2027
- TABLE 11 TOP USE CASES AND MARKET POTENTIAL
- TABLE 12 BEST PRACTICES: NOTABLE INDUSTRY PRACTICES BY LEADING COMPANIES
- TABLE 13 ANTISCALANTS MARKET: CASE STUDIES RELATED TO AI IMPLEMENTATION
- TABLE 14 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- TABLE 15 NORTH AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 16 ASIA PACIFIC: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 17 EUROPE: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 18 MIDDLE EAST & AFRICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 19 SOUTH AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 20 GLOBAL STANDARDS IN ANTISCALANTS MARKET
- TABLE 21 CERTIFICATIONS, LABELING, AND ECO-STANDARDS IN ANTISCALANTS MARKET
- TABLE 22 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR KEY APPLICATIONS (%)
- TABLE 23 KEY BUYING CRITERIA FOR KEY APPLICATIONS
- TABLE 24 ANTISCALANTS MARKET: UNMET NEEDS IN KEY END-USE SECTORS
- TABLE 25 ANTISCALANTS MARKET, BY TYPE, 2022-2025 (KILOTON)
- TABLE 26 ANTISCALANTS MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 27 ANTISCALANTS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 28 ANTISCALANTS MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 29 ANTISCALANTS MARKET, BY PROCESS TYPE, 2022-2025 (KILOTON)
- TABLE 30 ANTISCALANTS MARKET, BY PROCESS TYPE, 2026-2031 (KILOTON)
- TABLE 31 ANTISCALANTS MARKET, BY PROCESS TYPE, 2022-2025 (USD MILLION)
- TABLE 32 ANTISCALANTS MARKET, BY PROCESS TYPE, 2026-2031 (USD MILLION)
- TABLE 33 ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 34 ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 35 ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 36 ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 37 ANTISCALANTS MARKET, BY REGION, 2022-2025 (KILOTON)
- TABLE 38 ANTISCALANTS MARKET, BY REGION, 2026-2031 (KILOTON)
- TABLE 39 ANTISCALANTS MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 40 ANTISCALANTS MARKET, BY REGION, 2026-2031 (USD MILLION)
- TABLE 41 NORTH AMERICA: ANTISCALANTS MARKET, BY COUNTRY, 2022-2025 (KILOTON)
- TABLE 42 NORTH AMERICA: ANTISCALANTS MARKET, BY COUNTRY, 2026-2031 (KILOTON)
- TABLE 43 NORTH AMERICA: ANTISCALANTS MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 44 NORTH AMERICA: ANTISCALANTS MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 45 NORTH AMERICA ANTISCALANTS MARKET, BY TYPE, 2022-2025 (KILOTON)
- TABLE 46 NORTH AMERICA ANTISCALANTS MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 47 NORTH AMERICA ANTISCALANTS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 48 NORTH AMERICA ANTISCALANTS MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 49 NORTH AMERICA ANTISCALANTS MARKET, BY PROCESS TYPE, 2022-2025 (KILOTON)
- TABLE 50 NORTH AMERICA ANTISCALANTS MARKET, BY PROCESS TYPE, 2026-2031 (KILOTON)
- TABLE 51 NORTH AMERICA ANTISCALANTS MARKET, BY PROCESS TYPE, 2022-2025 (USD MILLION)
- TABLE 52 NORTH AMERICA ANTISCALANTS MARKET, BY PROCESS TYPE, 2026-2031 (USD MILLION)
- TABLE 53 NORTH AMERICA: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 54 NORTH AMERICA: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 55 NORTH AMERICA: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 56 NORTH AMERICA: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 57 US: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 58 US: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 59 US: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 60 US: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 61 CANADA: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 62 CANADA: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 63 CANADA: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 64 CANADA: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 65 MEXICO: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 66 MEXICO: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 67 MEXICO: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 68 MEXICO: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 69 EUROPE: ANTISCALANTS MARKET, BY COUNTRY, 2022-2025 (KILOTON)
- TABLE 70 EUROPE: ANTISCALANTS MARKET, BY COUNTRY, 2026-2031 (KILOTON)
- TABLE 71 EUROPE: ANTISCALANTS MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 72 EUROPE: ANTISCALANTS MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 73 EUROPE: ANTISCALANTS MARKET, BY TYPE, 2022-2025 (KILOTON)
- TABLE 74 EUROPE: ANTISCALANTS MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 75 EUROPE: ANTISCALANTS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 76 EUROPE: ANTISCALANTS MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 77 EUROPE: ANTISCALANTS MARKET, BY PROCESS TYPE, 2022-2025 (KILOTON)
- TABLE 78 EUROPE: ANTISCALANTS MARKET, BY PROCESS TYPE, 2026-2031 (KILOTON)
- TABLE 79 EUROPE: ANTISCALANTS MARKET, BY PROCESS TYPE, 2022-2025 (USD MILLION)
- TABLE 80 EUROPE: ANTISCALANTS MARKET, BY PROCESS TYPE, 2026-2031 (USD MILLION)
- TABLE 81 EUROPE: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 82 EUROPE: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 83 EUROPE: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 84 EUROPE: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 85 GERMANY: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 86 GERMANY: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 87 GERMANY: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 88 GERMANY: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 89 ITALY: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 90 ITALY: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 91 ITALY: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 92 ITALY: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 93 FRANCE: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 94 FRANCE: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 95 FRANCE: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 96 FRANCE: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 97 UK: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 98 UK: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 99 UK: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 100 UK: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 101 SPAIN: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 102 SPAIN: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 103 SPAIN: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 104 SPAIN: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 105 REST OF EUROPE: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 106 REST OF EUROPE: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 107 REST OF EUROPE: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 108 REST OF EUROPE: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 109 ASIA PACIFIC: ANTISCALANTS MARKET, BY COUNTRY, 2022-2025 (KILOTON)
- TABLE 110 ASIA PACIFIC: ANTISCALANTS MARKET, BY COUNTRY, 2026-2031 (KILOTON)
- TABLE 111 ASIA PACIFIC: ANTISCALANTS MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 112 ASIA PACIFIC: ANTISCALANTS MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 113 ASIA PACIFIC: ANTISCALANTS MARKET, BY TYPE, 2022-2025 (KILOTON)
- TABLE 114 ASIA PACIFIC: ANTISCALANTS MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 115 ASIA PACIFIC: ANTISCALANTS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 116 ASIA PACIFIC: ANTISCALANTS MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 117 ASIA PACIFIC: ANTISCALANTS MARKET, BY PROCESS TYPE, 2022-2025 (KILOTON)
- TABLE 118 ASIA PACIFIC: ANTISCALANTS MARKET, BY PROCESS TYPE, 2026-2031 (KILOTON)
- TABLE 119 ASIA PACIFIC: ANTISCALANTS MARKET, BY PROCESS TYPE, 2022-2025 (USD MILLION)
- TABLE 120 ASIA PACIFIC: ANTISCALANTS MARKET, BY PROCESS TYPE, 2026-2031 (USD MILLION)
- TABLE 121 ASIA PACIFIC: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 122 ASIA PACIFIC: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 123 ASIA PACIFIC: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 124 ASIA PACIFIC: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 125 CHINA: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 126 CHINA: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 127 CHINA: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 128 CHINA: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 129 JAPAN: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 130 JAPAN: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 131 JAPAN: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 132 JAPAN: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 133 SOUTH KOREA: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 134 SOUTH KOREA: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 135 SOUTH KOREA: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 136 SOUTH KOREA: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 137 INDIA: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 138 INDIA: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 139 INDIA: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 140 INDIA: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 141 REST OF ASIA PACIFIC: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 142 REST OF ASIA PACIFIC: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 143 REST OF ASIA PACIFIC: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 144 REST OF ASIA PACIFIC: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 145 MIDDLE EAST & AFRICA: ANTISCALANTS MARKET, BY COUNTRY, 2022-2025 (KILOTON)
- TABLE 146 MIDDLE EAST & AFRICA: ANTISCALANTS MARKET, BY COUNTRY, 2026-2031 (KILOTON)
- TABLE 147 MIDDLE EAST & AFRICA: ANTISCALANTS MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 148 MIDDLE EAST & AFRICA: ANTISCALANTS MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 149 MIDDLE EAST & AFRICA: ANTISCALANTS MARKET, BY TYPE, 2022-2025 (KILOTON)
- TABLE 150 MIDDLE EAST & AFRICA: ANTISCALANTS MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 151 MIDDLE EAST & AFRICA: ANTISCALANTS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 152 MIDDLE EAST & AFRICA: ANTISCALANTS MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 153 MIDDLE EAST & AFRICA: ANTISCALANTS MARKET, BY PROCESS TYPE, 2022-2025 (KILOTON)
- TABLE 154 MIDDLE EAST & AFRICA: ANTISCALANTS MARKET, BY PROCESS TYPE, 2026-2031 (KILOTON)
- TABLE 155 MIDDLE EAST & AFRICA: ANTISCALANTS MARKET, BY PROCESS TYPE, 2022-2025 (USD MILLION)
- TABLE 156 MIDDLE EAST & AFRICA: ANTISCALANTS MARKET, BY PROCESS TYPE, 2026-2031 (USD MILLION)
- TABLE 157 MIDDLE EAST & AFRICA: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 158 MIDDLE EAST & AFRICA: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 159 MIDDLE EAST & AFRICA: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 160 MIDDLE EAST & AFRICA: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 161 SAUDI ARABIA: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 162 SAUDI ARABIA: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 163 SAUDI ARABIA: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 164 SAUDI ARABIA: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 165 QATAR: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 166 QATAR: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 167 QATAR: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 168 QATAR: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 169 UAE: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 170 UAE: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 171 UAE: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 172 UAE: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 173 REST OF GCC COUNTRIES: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 174 REST OF GCC COUNTRIES: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 175 REST OF GCC COUNTRIES: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 176 REST OF GCC COUNTRIES: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 177 REST OF MIDDLE EAST & AFRICA: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 178 REST OF MIDDLE EAST & AFRICA: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 179 REST OF MIDDLE EAST & AFRICA: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 180 REST OF MIDDLE EAST & AFRICA: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 181 SOUTH AMERICA: ANTISCALANTS MARKET, BY COUNTRY, 2022-2025 (KILOTON)
- TABLE 182 SOUTH AMERICA: ANTISCALANTS MARKET, BY COUNTRY, 2026-2031 (KILOTON)
- TABLE 183 SOUTH AMERICA: ANTISCALANTS MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 184 SOUTH AMERICA: ANTISCALANTS MARKET, BY COUNTRY, 2026-2031 (USD MILLION)
- TABLE 185 SOUTH AMERICA: ANTISCALANTS MARKET, BY TYPE, 2022-2025 (KILOTON)
- TABLE 186 SOUTH AMERICA: ANTISCALANTS MARKET, BY TYPE, 2026-2031 (KILOTON)
- TABLE 187 SOUTH AMERICA: ANTISCALANTS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 188 SOUTH AMERICA: ANTISCALANTS MARKET, BY TYPE, 2026-2031 (USD MILLION)
- TABLE 189 SOUTH AMERICA: ANTISCALANTS MARKET, BY PROCESS TYPE, 2022-2025 (KILOTON)
- TABLE 190 SOUTH AMERICA: ANTISCALANTS MARKET, BY PROCESS TYPE, 2026-2031 (KILOTON)
- TABLE 191 SOUTH AMERICA: ANTISCALANTS MARKET, BY PROCESS TYPE, 2022-2025 (USD MILLION)
- TABLE 192 SOUTH AMERICA: ANTISCALANTS MARKET, BY PROCESS TYPE, 2026-2031 (USD MILLION)
- TABLE 193 SOUTH AMERICA: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 194 SOUTH AMERICA: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 195 SOUTH AMERICA: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 196 SOUTH AMERICA: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 197 BRAZIL: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 198 BRAZIL: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 199 BRAZIL: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 200 BRAZIL: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 201 ARGENTINA: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 202 ARGENTINA: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 203 ARGENTINA: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 204 ARGENTINA: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 205 REST OF SOUTH AMERICA: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (KILOTON)
- TABLE 206 REST OF SOUTH AMERICA: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (KILOTON)
- TABLE 207 REST OF SOUTH AMERICA: ANTISCALANTS MARKET, BY APPLICATION, 2022-2025 (USD MILLION)
- TABLE 208 REST OF SOUTH AMERICA: ANTISCALANTS MARKET, BY APPLICATION, 2026-2031 (USD MILLION)
- TABLE 209 KEY PLAYER STRATEGIES/RIGHT TO WIN, 2022-2026
- TABLE 210 ANTISCALANTS MARKET: DEGREE OF COMPETITION
- TABLE 211 ANTISCALANTS MARKET: REGION FOOTPRINT
- TABLE 212 ANTISCALANTS MARKET: TYPE FOOTPRINT
- TABLE 213 ANTISCALANTS MARKET: APPLICATION FOOTPRINT
- TABLE 214 ANTISCALANTS MARKET: PROCESS TYPE FOOTPRINT
- TABLE 215 ANTISCALANTS MARKET: DETAILED LIST OF KEY STARTUPS/SMES
- TABLE 216 ANTISCALANTS MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES (1/2)
- TABLE 217 ANTISCALANTS MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES (2/2)
- TABLE 218 ANTISCALANTS MARKET: PRODUCT LAUNCHES, JANUARY 2022- MAY 2026
- TABLE 219 ANTISCALANTS MARKET: DEALS, JANUARY 2022- MAY 2026
- TABLE 220 ANTISCALANTS MARKET: EXPANSIONS, JANUARY 2022- MAY 2026
- TABLE 221 DOW: COMPANY OVERVIEW
- TABLE 222 DOW: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 223 BASF: COMPANY OVERVIEW
- TABLE 224 BASF: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 225 ECOLAB: COMPANY OVERVIEW
- TABLE 226 ECOLAB: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 227 SOLENIS: COMPANY OVERVIEW
- TABLE 228 SOLENIS: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 229 SOLENIS: DEALS, JANUARY 2022-MAY 2026
- TABLE 230 KEMIRA: COMPANY OVERVIEW
- TABLE 231 KEMIRA: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 232 KEMIRA: DEALS, JANUARY 2022-MAY 2026
- TABLE 233 KEMIRA: EXPANSIONS, JANUARY 2022-MAY 2026
- TABLE 234 CLARIANT: COMPANY OVERVIEW
- TABLE 235 CLARIANT: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 236 CLARIANT: EXPANSIONS, JANUARY 2022-MAY 2026
- TABLE 237 SYENSQO: COMPANY OVERVIEW
- TABLE 238 SYENSQO: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 239 SYENSQO: DEALS, JANUARY 2022-MAY 2026
- TABLE 240 KURITA WATER INDUSTRIES LTD.: COMPANY OVERVIEW
- TABLE 241 KURITA WATER INDUSTRIES LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 242 KURITA WATER INDUSTRIES LTD.: EXPANSIONS, JANUARY 2022-MAY 2026
- TABLE 243 VEOLIA GROUP: COMPANY OVERVIEW
- TABLE 244 VEOLIA GROUP: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 245 VEOLIA GROUP: DEALS, JANUARY 2022-MAY 2026
- TABLE 246 ITALMATCH CHEMICALS S.P.A.: COMPANY OVERVIEW
- TABLE 247 ITALMATCH CHEMICALS S.P.A.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 248 ITALMATCH CHEMICALS S.P.A.: PRODUCT LAUNCHES, JANUARY 2022-MAY 2026
- TABLE 249 BIOLAB ARABIA LTD. CO.: COMPANY OVERVIEW
- TABLE 250 DUBICHEM: COMPANY OVERVIEW
- TABLE 251 REZA INVESTMENT COMPANY LTD.: COMPANY OVERVIEW
- TABLE 252 ARIES CHEMICAL, INC.: COMPANY OVERVIEW
- TABLE 253 OVIVO: COMPANY OVERVIEW
- TABLE 254 AES ARABIA LTD.: COMPANY OVERVIEW
- TABLE 255 SNF GROUP: COMPANY OVERVIEW
- TABLE 256 ANGEL CHEMICALS PRIVATE LIMITED: COMPANY OVERVIEW
- TABLE 257 HYDROVIDA: COMPANY OVERVIEW
- TABLE 258 ACCEPTA WATER TREATMENT: COMPANY OVERVIEW
- TABLE 259 KING LEE TECHNOLOGIES: COMPANY OVERVIEW
- TABLE 260 AMERICAN WATER CHEMICALS, INC.: COMPANY OVERVIEW
- TABLE 261 SHANDONG KAIRUI CHEMISTRY CO., LTD.: COMPANY OVERVIEW
- TABLE 262 AXEON WATER: COMPANY OVERVIEW
- TABLE 263 ACURO ORGANICS LIMITED: COMPANY OVERVIEW
List of Figures
- FIGURE 1 ANTISCALANTS MARKET SEGMENTATION
- FIGURE 2 KEY INSIGHTS AND MARKET HIGHLIGHTS
- FIGURE 3 ANTISCALANTS MARKET, 2026-2031
- FIGURE 4 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN ANTISCALANTS MARKET, 2022-2026
- FIGURE 5 DISRUPTIONS INFLUENCING GROWTH OF ANTISCALANTS MARKET
- FIGURE 6 HIGH-GROWTH SEGMENTS IN ANTISCALANTS MARKET, 2026-2031
- FIGURE 7 ASIA PACIFIC TO REGISTER HIGHEST CAGR IN ANTISCALANTS MARKET DURING FORECAST PERIOD
- FIGURE 8 ASIA PACIFIC TO OFFER ATTRACTIVE OPPORTUNITIES DURING FORECAST PERIOD
- FIGURE 9 PHOSPHONATES SEGMENT TO LEAD MARKET DURING FORECAST PERIOD
- FIGURE 10 THRESHOLD INHIBITORS SEGMENT TO HOLD MAJOR SHARE DURING FORECAST PERIOD
- FIGURE 11 OIL & GAS TO LEAD MARKET DURING FORECAST PERIOD
- FIGURE 12 INDIA TO WITNESS HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 13 DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES IN ANTISCALANTS MARKET
- FIGURE 14 FRESHWATER AVAILABILITY IN TOP COUNTRIES
- FIGURE 15 ANTISCALANTS MARKET: PORTER'S FIVE FORCES ANALYSIS
- FIGURE 16 ANTISCALANTS MARKET: VALUE CHAIN ANALYSIS
- FIGURE 17 ANTISCALANTS MARKET ECOSYSTEM
- FIGURE 18 AVERAGE SELLING PRICE TREND OF ANTISCALANTS, BY REGION, 2023-2025, USD/KG
- FIGURE 19 AVERAGE SELLING PRICE TREND, BY TYPE, 2023-2025
- FIGURE 20 IMPORT SCENARIO FOR HS CODE 382499 -COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025
- FIGURE 21 EXPORT SCENARIO FOR HS CODE 382499 -COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025
- FIGURE 22 INCREASING DEMAND FOR WATER TREATMENT SOLUTIONS TO DRIVE MARKET
- FIGURE 23 ANTISCALANTS MARKET: INVESTMENT AND FUNDING SCENARIO, 2022-2025
- FIGURE 24 PATENTS APPLIED AND GRANTED, 2016-2025
- FIGURE 25 PATENT ANALYSIS, BY LEGAL STATUS
- FIGURE 26 TOP JURISDICTION, BY DOCUMENT
- FIGURE 27 ANTISCALANTS MARKET: DECISION-MAKING FACTORS
- FIGURE 28 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR KEY APPLICATIONS
- FIGURE 29 KEY BUYING CRITERIA FOR TOP 3 APPLICATIONS
- FIGURE 30 ADOPTION BARRIERS & INTERNAL CHALLENGES
- FIGURE 31 PHOSPHONATES SEGMENT TO LEAD MARKET DURING FORECAST PERIOD
- FIGURE 32 THRESHOLD INHIBITOR SEGMENT TO BE FASTEST-GROWING SEGMENT DURING FORECAST PERIOD
- FIGURE 33 OIL & GAS TO BE LARGEST APPLICATION DURING FORECAST PERIOD
- FIGURE 34 INDIA TO BE FASTEST-GROWING MARKET DURING FORECAST PERIOD
- FIGURE 35 NORTH AMERICA: ANTISCALANTS MARKET SNAPSHOT
- FIGURE 36 EUROPE: ANTISCALANTS MARKET SNAPSHOT
- FIGURE 37 ASIA PACIFIC: ANTISCALANTS MARKET SNAPSHOT
- FIGURE 38 REVENUE ANALYSIS OF TOP LISTED/PUBLIC PLAYERS, 2023-2025
- FIGURE 39 MARKET SHARE ANALYSIS OF KEY PLAYERS, 2025
- FIGURE 40 COMPANY VALUATION
- FIGURE 41 FINANCIAL METRICS (EV/EBITDA)
- FIGURE 42 BRAND/PRODUCT COMPARISON
- FIGURE 43 ANTISCALANTS MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- FIGURE 44 ANTISCALANTS MARKET: COMPANY FOOTPRINT
- FIGURE 45 ANTISCALANTS MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
- FIGURE 46 DOW: COMPANY SNAPSHOT
- FIGURE 47 BASF: COMPANY SNAPSHOT
- FIGURE 48 ECOLAB: COMPANY SNAPSHOT
- FIGURE 49 SOLENIS: COMPANY SNAPSHOT
- FIGURE 50 KEMIRA: COMPANY SNAPSHOT
- FIGURE 51 CLARIANT: COMPANY SNAPSHOT
- FIGURE 52 SYENSQO: COMPANY SNAPSHOT
- FIGURE 53 KURITA WATER INDUSTRIES LTD.: COMPANY SNAPSHOT
- FIGURE 54 VEOLIA GROUP: COMPANY SNAPSHOT
- FIGURE 55 ITALMATCH CHEMICALS S.P.A.: COMPANY SNAPSHOT
- FIGURE 56 RESEARCH DESIGN
- FIGURE 57 BOTTOM-UP APPROACH
- FIGURE 58 TOP-DOWN APPROACH
- FIGURE 59 MARKET SIZE ESTIMATION NOTES
- FIGURE 60 DEMAND-SIDE FORECAST PROJECTIONS
- FIGURE 61 DATA TRIANGULATION

 聚磷酸鹽基阻垢劑市場:全球市場預測(2026-2032年)高效率灰水阻垢劑市場:全球市場預測,2026-2032年
 除垢劑:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)
 阻垢劑和除垢劑市場規模、佔有率和趨勢分析報告:按產品、應用、最終用途、地區和細分市場預測(2026-2033 年)
 除垢閥市場規模、佔有率和成長分析:按閥門類型、材料、壓力等級、最終用途產業、操作方式、分銷管道和地區分類-2026-2033年產業預測
 阻垢劑市場:依類型、製程、應用、技術、形態、國家及地區分類-全球產業分析、市場規模、市場佔有率及2026年至2033年預測
 阻垢劑和分散劑市場規模、佔有率和成長分析:按產品化學、製劑形式、目標系統、最終用途產業和地區分類-2026-2033年產業預測
 阻垢劑和防污劑市場規模、佔有率和成長分析:按化學分類、系統運作、最終用途產業和地區分類-2026-2033年產業預測
 全球阻垢劑市場規模、佔有率、趨勢和成長分析報告(2026-2034年)水垢去除劑市場規模、佔有率和趨勢分析報告:按產品、形式、應用、最終用途、地區和細分市場分類(2026-2033 年)