


 |
市場調查報告書
商品編碼
2121187
2026 年至 2035 年人工智慧驅動工業機器人的市場機會、成長要素、產業趨勢和預測。AI-Powered Industrial Robot Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球人工智慧驅動的工業機器人市場預計到 2025 年將達到 79 億美元,到 2035 年將以 12.2% 的複合年成長率成長,達到 279 億美元。
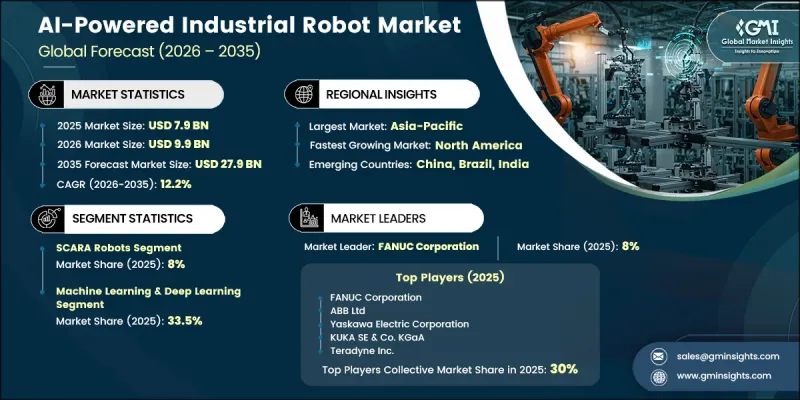
隨著製造商擴大採用軟體定義自動化來提高生產效率和營運柔軟性,市場持續成長。對智慧自動化解決方案的投資增加,正推動企業採用先進的人工智慧驅動的工業機器人,以支援更快、更靈活的製造環境。機器人產業的併購,也加速了技術發展,使企業能夠擴展產品系列併增強競爭力。因此,人工智慧驅動的工業機器人正逐步取代傳統的自動化技術,成為能夠提供更高精度、擴充性和更佳營運效能的智慧系統。先進的人工智慧功能使這些機器人能夠分析生產數據並即時持續最佳化製造工作流程,從而滿足日益成長的客製化、多品種、小批量生產需求。對智慧工廠的投資增加、歐洲和亞太地區自動化預算的擴大,以及製造業活動持續回流北美,都進一步提升了人工智慧驅動的工業機器人的商業性可行性,並推動其在多個工業領域的長期市場擴張。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 79億美元 |
| 預測金額 | 279億美元 |
| 複合年成長率 | 12.2% |
搭載人工智慧的工業機器人,結合基於代理的人工智慧和生成式人工智慧模型,使製造商能夠持續監控生產狀態和營運數據,並透過智慧決策提升生產效率。這些先進的機器人系統支援即時流程最佳化,幫助生產設施更有效地應對不斷變化的生產需求。它們增強營運視覺性並加速生產最佳化的能力,與日益重視軟性製造的行業趨勢相契合,而人工智慧驅動的工業機器人正在推動整體市場成長,發揮著至關重要的作用。
預計到2035年,SCARA機器人細分市場將以8%的複合年成長率成長,反映出電子組裝和食品包裝應用領域的強勁需求。在這些領域,人工智慧驅動的工業機器人因其能夠在重複性生產任務中實現快速、精準和高效的操作,而得到越來越廣泛的應用。在需要高產量生產過程中保持性能穩定、智慧監控和提高生產效率的應用場景中,製造商越來越傾向於選擇人工智慧機器人系統。
預計到2025年,機器學習和深度學習領域將佔據33.5%的市場佔有率,市場規模將達到26億美元。隨著製造商擴大採用智慧演算法,以實現整體製造工廠的自主決策和預測性維護能力,該領域將佔據最大的市場佔有率。人工智慧驅動的分析技術的日益普及將繼續推動工業機器人應用領域對機器學習和深度學習技術的需求。
預計到 2025 年,北美人工智慧工業機器人市場規模將達到 13 億美元。美國將佔該地區市場價值的 84% 以上,這得益於其成熟的製造業以及為加強供應鏈韌性和擴大國內製造能力而將生產活動遷回美國而增加的投資。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 每個階段增加的價值
- 影響價值鏈的因素
- 影響產業的因素
- 促進因素
- 青年和婦女的參與度提高
- 勞動力短缺和回流
- 生成式人工智慧與LLM的整合
- IT/OT整合
- 產業潛在風險與挑戰
- 高階整合的複雜性
- 資料隱私和網路安全
- 機會
- Robot-as-a-Service(RaaS)
- 人類通用機器人
- 促進因素
- 成長潛力分析
- 未來市場趨勢
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格趨勢
- 以機器人類型分類的全球平均售價 (ASP)
- 區域價格基準(亞太地區 vs. 北美地區 vs. 歐洲地區)
- 全球價格趨勢分析(2018-2025)
- 以業務類型分類的定價策略-全球(高階/價值/成本加成)和區域。
- 監理情勢
- 標準和合規要求
- 區域監理框架
- 認證標準
- 波特的分析
- PESTLE分析
- 貿易數據分析
- 主要進口國和成長市場
- 台灣機器人及零件的全球出口趨勢
- CPTPP貿易流量:台灣進入會員市場的優惠待遇
- RCEP對以中國為中心和以台灣為中心的供應鏈的影響
- 全球主要港口及物流樞紐分析
- 人工智慧和生成式人工智慧對中西部製造業的影響
- 人工智慧正在改變美國中西部製造業的經營模式
- 生成式人工智慧的應用案例與實施藍圖
- 大規模語言模型(LLM)的引入
- 先導計畫。
- 風險、限制和監管考量
- 生產能力和生產情況
- 各州製造業產能
- 各州運轉率及擴建計劃
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 企業矩陣分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃
第5章 市場估算與預測:機器人類型,2022-2035年
- 關節機器人
- SCARA機器人
- Delta機器人
- 其他
第6章 市場估計與預測:依技術分類,2022-2035年
- 機器學習和深度學習
- 電腦視覺和影像處理
- 自然語言處理(NLP)
- 其他
第7章 市場估計與預測:依應用領域分類,2022-2035年
- 組裝和物料輸送
- 焊接和機械加工
- 包裝和托盤堆垛
- 品質檢測和視覺系統
- 物流/倉儲
- 油漆和塗層
- 其他
第8章 市場估算與預測:依最終用戶分類,2022-2035年
- 車
- 電子電器設備
- 食品/飲料
- 藥品和醫療保健
- 消費品
- 物流/倉儲
- 其他
第9章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 亞太地區
- 中國
- 日本
- 印度
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第10章:公司簡介
- 世界公司
- ABB Ltd
- Agility Robotics, Inc.
- Boston Dynamics, Inc.
- FANUC Corporation
- Figure AI, Inc.
- Kawasaki Heavy Industries Ltd.
- 當地公司
- Keyence Corporation
- KUKA SE & Co. KGaA
- NVIDIA Corporation
- Omron Corporation
- Standard Bots
- Symbiotic Inc.
- 新興企業
- Teradyne, Inc.
- Tesla, Inc.
- Yaskawa Electric Corporation
- Epson America Inc.
- Neura Robotics
- Flexiv
The Global AI-Powered Industrial Robot Market was valued at USD 7.9 billion in 2025 and is estimated to grow at a CAGR of 12.2% to reach USD 27.9 billion by 2035.
The market continues to gain momentum as manufacturers increasingly adopt software-defined automation to improve production efficiency and operational flexibility. Growing investments in intelligent automation solutions are encouraging companies to deploy advanced AI-powered industrial robots capable of supporting faster and more adaptive manufacturing environments. Rising merger and acquisition activity across the robotics industry is also accelerating technology development, enabling companies to broaden their product portfolios and strengthen their competitive positions. As a result, AI-powered industrial robots are steadily replacing conventional automation technologies with more intelligent systems that deliver greater precision, scalability, and operational performance. Advanced AI capabilities enable these robots to analyze production data and continuously optimize manufacturing workflows in real time, supporting the growing demand for customized and high-mix production. Increasing investments in smart factories, expanding automation budgets across Europe and Asia-Pacific, and the continued reshoring of manufacturing activities in North America are further improving the commercial viability of AI-powered industrial robots and driving long-term market expansion across multiple industrial sectors.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $7.9 Billion |
| Forecast Value | $27.9 Billion |
| CAGR | 12.2% |
AI-powered industrial robots equipped with agentic AI and generative AI models enable manufacturers to monitor production conditions and operational data continuously while improving manufacturing efficiency through intelligent decision-making. These advanced robotic systems support real-time process optimization, helping production facilities respond more effectively to changing manufacturing requirements. Their ability to improve operational visibility and accelerate production optimization aligns with the industry's increasing emphasis on flexible manufacturing, making AI-powered industrial robots an important contributor to overall market growth.
The SCARA robots segment is expected to grow at a CAGR of 8% through 2035, reflecting steady demand from electronics assembly and food packaging applications. AI-powered industrial robots in these categories continue to gain wider adoption because they deliver fast, accurate, and highly efficient movement during repetitive production tasks. Manufacturers increasingly prefer AI-enabled robotic systems for applications requiring consistent performance, intelligent monitoring, and enhanced productivity throughout high-volume manufacturing operations.
The machine learning & deep learning segment accounted for 33.5% share in 2025, generating USD 2.6 billion. This segment represented the largest share of the market as manufacturers increasingly adopted intelligent algorithms to enable autonomous decision-making and predictive maintenance capabilities within modern manufacturing facilities. The growing implementation of AI-driven analytics continues to strengthen demand for machine learning and deep learning technologies across industrial robotics applications.
North America AI-Powered Industrial Robot Market generated USD 1.3 billion in 2025. The United States accounted for more than 84% of the regional market value, supported by a well-established manufacturing industry and increasing investments aimed at reshoring production activities to strengthen supply chain resilience and expand domestic manufacturing capabilities.
Major companies operating in the global AI-powered industrial robot market include ABB Ltd, Agility Robotics, Inc., Boston Dynamics, Inc., Epson America Inc., FANUC Corporation, Flexiv, Figure AI, Inc., Kawasaki Heavy Industries Ltd., Keyence Corporation, KUKA SE & Co. KGaA, Neura Robotics, NVIDIA Corporation, Omron Corporation, Standard Bots, Symbiotic Inc., Teradyne, Inc., Tesla, Inc., and Yaskawa Electric Corporation. Companies operating in the AI-powered industrial robot market are strengthening their market positions through continuous investments in artificial intelligence, robotics software, and intelligent automation technologies. Many organizations are expanding their product portfolios by developing advanced robotic platforms with enhanced autonomy, predictive capabilities, and flexible deployment options. Strategic mergers, acquisitions, and technology partnerships remain key approaches for accelerating innovation, improving engineering expertise, and expanding global market reach. Manufacturers are also increasing research and development spending to improve robot intelligence, software integration, and operational efficiency. In addition, companies are focusing on regional expansion, strengthening distribution networks, and collaborating with manufacturing customers to deliver customized automation solutions.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Robot Type
- 2.2.3 Technology
- 2.2.4 Application
- 2.2.5 End User
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising Participation Among Youth & Women
- 3.2.1.2 Labor shortages & reshoring
- 3.2.1.3 Generative AI & LLM Integration
- 3.2.1.4 IT/OT Convergence
- 3.2.2 Industry pitfalls & challenges
- 3.2.2.1 High Integration Complexity
- 3.2.2.2 Data Privacy & Cybersecurity
- 3.2.3 Opportunities
- 3.2.3.1 Robot-as-a-Service (RaaS)
- 3.2.3.2 Humanoid General-Purpose Robots
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Future market trends
- 3.5 Technology and innovation landscape
- 3.5.1 Current technological trends
- 3.5.2 Emerging technologies
- 3.6 Price trends
- 3.6.1 Global Average Selling Price (ASP) by Robot Type (Driven by Primary Research)
- 3.6.2 Regional Price Benchmarking (APAC vs. North America vs. Europe) (Driven by Primary Research)
- 3.6.3 Historical Global Price Trend Analysis (2018–2025) (Driven by Primary Research)
- 3.6.4 Pricing Strategy by Player Type — Global (Premium / Value / Cost-plus) (Driven by Primary Research)By region
- 3.7 Regulatory landscape
- 3.7.1 Standards and compliance requirements
- 3.7.2 Regional regulatory frameworks
- 3.7.3 Certification standards
- 3.8 Porter’s analysis
- 3.9 PESTEL analysis
- 3.10 Trade Data Analysis (Driven by Primary Research)
- 3.10.1 Key Importing Nations & Growth Markets (Driven by Primary Research)
- 3.10.2 Taiwan's Global Robot & Component Export Intelligence (Driven by Primary Research)
- 3.10.3 CPTPP Trade Flows Taiwan's Preferential Access to Member Markets (Driven by Primary Research)
- 3.10.4 RCEP Impact on China-Centered vs. Taiwan-Centered Supply Chains (Driven by Primary Research)
- 3.10.5 Key Global Port & Logistics Hub Analysis (Driven by Primary Research)
- 3.11 Impact of AI & Generative AI on Midwest Manufacturing
- 3.11.1 AI-Driven Disruption of Midwest Manufacturing Business Models
- 3.11.2 GenAI Use Cases & Adoption Roadmap
- 3.11.3 Large Language Model (LLM) Integration
- 3.11.4 Agentic AI Decision-Making Pilots
- 3.11.5 Risks, Limitations & Regulatory Considerations
- 3.12 Capacity & Production Landscape (Driven by Primary Research)
- 3.12.1 Manufacturing Capacity Installed by State (Driven by Primary Research)
- 3.12.2 Capacity Utilization Rates & Expansion Pipelines (State-Level) (Driven by Primary Research)
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East and Africa
- 4.2.1 By region
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates and Forecast, By Robot Type, 2022 – 2035 (USD Billion) (Thousand Units)
- 5.1 Key trends
- 5.2 Articulated Robots
- 5.3 SCARA Robots
- 5.4 Delta Robots
- 5.5 Others
Chapter 6 Market Estimates and Forecast, By Technology, 2022 – 2035 (USD Billion) (Thousand Units)
- 6.1 Key trends
- 6.2 Machine Learning & Deep Learning
- 6.3 Computer Vision & Imaging
- 6.4 Natural Language Processing (NLP)
- 6.5 Others
Chapter 7 Market Estimates and Forecast, By Application, 2022 – 2035 (USD Billion) (Thousand Units)
- 7.1 Key trends
- 7.2 Assembly & Material Handling
- 7.3 Welding & Machining
- 7.4 Packaging & Palletizing
- 7.5 Quality Inspection & Vision Systems
- 7.6 Logistics & Warehousing
- 7.7 Painting & Coating
- 7.8 Others
Chapter 8 Market Estimates and Forecast, By End User, 2022 – 2035 (USD Billion) (Thousand Units)
- 8.1 Key trends
- 8.2 Automotive
- 8.3 Electronics & Electrical
- 8.4 Food & Beverage
- 8.5 Pharmaceuticals & Healthcare
- 8.6 Consumer Goods
- 8.7 Logistics & Warehousing
- 8.8 Others
Chapter 9 Market Estimates and Forecast, By Region, 2022 – 2035 (USD Billion) (Thousand Units)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Italy
- 9.3.5 Spain
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 Japan
- 9.4.3 India
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.6 Middle East and Africa
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
Chapter 10 Company Profiles
- 10.1 Global players
- 10.1.1 ABB Ltd
- 10.1.2 Agility Robotics, Inc.
- 10.1.3 Boston Dynamics, Inc.
- 10.1.4 FANUC Corporation
- 10.1.5 Figure AI, Inc.
- 10.1.6 Kawasaki Heavy Industries Ltd.
- 10.2 Regional players
- 10.2.1 Keyence Corporation
- 10.2.2 KUKA SE & Co. KGaA
- 10.2.3 NVIDIA Corporation
- 10.2.4 Omron Corporation
- 10.2.5 Standard Bots
- 10.2.6 Symbiotic Inc.
- 10.3 Emerging players
- 10.3.1 Teradyne, Inc.
- 10.3.2 Tesla, Inc.
- 10.3.3 Yaskawa Electric Corporation
- 10.3.4 Epson America Inc.
- 10.3.5 Neura Robotics
- 10.3.6 Flexiv

 2026-2034年全球人工智慧工業機器人市場規模、佔有率、趨勢和成長分析報告
 全球自學習工業機器人平台市場預測(至2034年):按產品、產品類型、組件、學習方法、最終用戶和地區分類
 視覺檢測設備:市場佔有率分析、產業趨勢及統計、成長預測(2026-2031)
 表面視覺與檢測市場:2026-2032年全球市場預測(依產品類型、類別、組件、技術、應用、最終用戶產業和部署模式分類)
 表面成像與檢測市場規模、佔有率及成長分析:按組件、技術、應用、終端用戶產業和地區分類-2026-2033年產業預測人工智慧驅動的工業機器人市場預測至2034年——全球產品、機器人類型、部署模式、技術、最終用戶和區域分析
 表面檢測市場規模、佔有率、趨勢和預測:按組件類型、部署方式、系統類型、檢測表面、行業和地區分類,2026-2034 年
 表面影像處理與檢測市場:依系統類型、組件、應用、表面類型和區域分類
 2026年全球表面目視檢測市場報告
 表面視覺與檢測市場 - 全球產業規模、佔有率、趨勢、機會及預測(按組件、應用、地區和競爭格局分類,2021-2031年)