


 |
市場調查報告書
商品編碼
2121177
2026 年至 2035 年檢測機器人的市場機會、成長要素、產業趨勢和預測。Inspection Robot Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球檢測機器人市場預計到 2025 年將價值 30 億美元,預計到 2035 年將以 14.7% 的複合年成長率成長至 115 億美元。
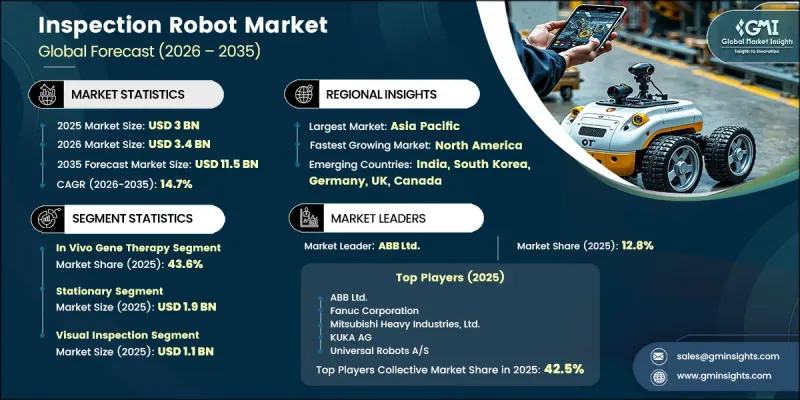
市場擴張的驅動力來自各行各業工業自動化技術的加速應用、日益嚴格的職場安全要求以及危險工作環境合規標準的加強。能源和公共產業網路中數位基礎設施的擴展為機器人檢測技術創造了更多機會。對人工智慧驅動的預測性維護投入的增加也促使企業採用能夠識別設備狀況並支援維護計畫的自動化系統。同時,各行業也擴大採用智慧化的資產、機械和基礎設施檢測方法。隨著企業尋求提高檢測效率、增強運作可靠性、減少人員暴露於危險環境的風險並支持持續的資產監控,能源和公共產業、建築、製造以及其他工業領域的需求正在不斷成長。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 初始市場規模 | 30億美元 |
| 預測金額 | 115億美元 |
| 複合年成長率 | 14.7% |
隨著製造商和工業營運商加速採用自動化和工業4.0技術,檢測機器人市場正蓬勃發展。數位轉型措施推動了機器人系統的應用,這些系統能夠在執行檢測任務的同時,保持生產連續性,並及早發現潛在的設備問題。自動化檢測有助於企業提高營運效率、減少意外停機時間並維持一致的監控標準。職場安全要求也是推動市場成長要素,因為法規日益要求限制工人直接接觸危險的工業環境。透過利用檢測機器人,操作人員可以執行遠端評估和維護相關任務,從而減少工人進入潛在危險區域的需要。
到2025年,半自動機器人將佔據43.6%的市場。半自動檢測機器人將自主導航和操作能力與人工監督相結合,從而在機器人效率和人類決策之間取得平衡。這種運作模式提高了檢測精度、運作可靠性以及與現有工業系統的兼容性。由於關鍵檢測決策中仍需人工參與,因此這些機器人適用於那些技術判斷和監管要求仍然至關重要的應用領域。半自動系統的需求主要來自製造業、石油天然氣、公共產業、採礦和基礎設施偵測等眾多產業的應用。
預計2025年,固定式機器人市場規模將達到19億美元。製造商對受控檢測環境下可靠自動化的需求不斷成長,推動了固定式機器人檢測系統的日益普及,鞏固了該細分市場的強勁地位。固定式機器人具有高精度、高一致性和高重複性,使企業能夠實現重複性檢測任務的自動化,並維持標準化的品質要求。在需要重複進行檢測且變異性最小的環境中,固定式機器人的優勢尤其突出。製造商正擴大將固定式機器人系統整合到自動化生產和測試流程中,以提高產品品質、最佳化生產流程並減少人工檢測的需求。
預計到2025年,北美檢測機器人市佔率將達到30.5%。這一區域成長主要得益於工業自動化的擴張、工業4.0技術的廣泛應用,以及製造業、能源公共產業和關鍵基礎設施等行業日益嚴格的職場安全要求。各組織機構正擴大考慮部署自動化檢測系統,以提高生產效率和檢測一致性,同時減少員工在危險工作環境中的風險。監管機構、能源機構和工業營運商都在鼓勵採用能夠提升職場安全性和改善營運績效的技術。該地區成熟的工業基礎、對自動化領域的持續投資以及對先進檢測技術的日益重視,都為機器人解決方案的推廣創造了有利環境。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 工業自動化的進步與工業4.0應用的擴展
- 更嚴格的工作場所安全法規以及對危險環境中遠端檢查日益成長的需求。
- 增加對預測性維護和數位資產管理的投資
- 擴大對老舊能源、公共產業和關鍵基礎設施資產的檢查要求。
- 人工智慧、自主導航、機器視覺和工業感測技術快速發展。
- 產業潛在風險與挑戰
- 初期實施和整合成本相對較高。
- 複雜和非結構化環境中的營運限制
- 市場機遇
- 人工智慧驅動的自主檢測和預測性維護的擴展
- 在能源、公共產業和關鍵基礎設施檢測領域擴大應用。
- 促進因素
- 成長潛力分析
- 監理情勢
- 波特的分析
- PESTLE分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格趨勢
- 按地區
- 依產品
- 定價策略
- 新興經營模式
- 合規要求
- 專利和智慧財產權分析
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 市場集中度分析
- 主要公司的競爭標竿分析
- 財務績效比較
- 收入
- 利潤率
- R&D
- 產品系列比較
- 產品線寬度
- 科技
- 創新
- 區域擴張比較
- 全球擴張分析
- 服務網路覆蓋
- 按地區分類的市場滲透率
- 競爭定位矩陣
- 領導者
- 挑戰者
- 追蹤者
- 小眾玩家
- 戰略展望矩陣
- 財務績效比較
- 主要進展
- 併購
- 夥伴關係和聯盟
- 技術進步
- 擴張和投資策略
- 數位轉型計劃
- 新興/新創競爭對手的發展趨勢
第5章 市場估計與預測:依類型分類,2022-2035年
- 非自主的
- 半自動
- 完全自主
第6章 市場估計與預測:依技術分類,2022-2035年
- 固定式
- 移動的
第7章 市場估計與預測:依應用領域分類,2022-2035年
- 目視檢查
- 超音波檢查
- 雷射掃描檢查
- 熱成像
- 品質檢驗
第8章 市場估算與預測:依最終用途產業分類,2022-2035年
- 石油和天然氣
- 電力/公共產業
- 石油化工
- 車
- 建造
- 食品/飲料
- 製造業
- 其他
第9章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第10章:公司簡介
- 全球主要公司
- ABB Ltd.
- FANUC CORPORATION
- Mitsubishi Heavy Industries, Ltd.
- KUKA AG
- Universal Robots A/S
- 該地區的主要公司
- 北美洲
- Cognex Corporation
- DSI Robotics
- Honeybee Robotics, Ltd.
- JH Robotics, Inc.
- Superdroid Robotics
- 亞太地區
- Denso Wave
- 歐洲
- Innok Robotics GmbH
- Robotnik Automation SL
- Staubli
- 北美洲
- 小眾玩家/顛覆者
- Energy Robotics GmbH
- Nexxis
The Global Inspection Robots Market was valued at USD 3 billion in 2025 and is estimated to grow at a CAGR of 14.7% to reach USD 11.5 billion by 2035.
Market expansion is supported by the accelerating adoption of industrial automation across multiple sectors, increasingly stringent workplace safety requirements, and stronger compliance standards for hazardous operating conditions. The expansion of digital infrastructure across energy and utility networks is creating additional opportunities for robotic inspection technologies. Growing investment in AI-enabled predictive maintenance is also encouraging organizations to deploy automated systems capable of identifying equipment conditions and supporting maintenance planning. At the same time, industries are increasingly adopting intelligent approaches to inspect assets, machinery, and infrastructure. Demand is developing across energy and utilities, construction, manufacturing, and other industrial environments as businesses seek to improve inspection efficiency, strengthen operational reliability, reduce human exposure to dangerous conditions, and support continuous asset monitoring.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $3 Billion |
| Forecast Value | $11.5 Billion |
| CAGR | 14.7% |
The inspection robots market is gaining momentum as manufacturers and industrial operators accelerate the adoption of automation and Industry 4.0 technologies. Digital transformation initiatives are encouraging businesses to deploy robotic systems that can perform inspection activities while supporting production continuity and identifying potential equipment issues at an earlier stage. Automated inspection can help organizations improve operational efficiency, reduce unplanned downtime, and maintain consistent monitoring standards. Workplace safety requirements are providing another important growth driver as regulations increasingly encourage businesses to limit direct worker exposure to dangerous industrial environments. Inspection robots allow operators to conduct remote assessments and maintenance-related activities while reducing the need for personnel to enter potentially hazardous locations.
The semi-autonomous segment accounted for a 43.6% share in 2025. Semi-autonomous inspection robots combine automated navigation and operational capabilities with human oversight, creating a balance between robotic efficiency and human decision-making. This operating model can improve inspection accuracy, operational dependability, and compatibility with existing industrial systems. The ability to retain human involvement in important inspection decisions makes these robots suitable for applications where technical judgment and regulatory requirements remain essential. Demand for semi-autonomous systems is supported by their use across manufacturing, oil and gas, utilities, mining, and infrastructure inspection.
The stationary segment generated USD 1.9 billion in 2025. Increasing adoption of fixed robotic inspection systems is supporting the segment's strong position as manufacturers seek reliable automation for controlled inspection environments. Stationary robots provide high levels of precision, consistency, and repeatability, allowing organizations to automate recurring inspection activities and maintain standardized quality requirements. Their capabilities are particularly valuable in environments where inspection tasks need to be performed repeatedly with minimal variation. Manufacturers are increasingly integrating stationary robotic systems into automated production and testing operations as they seek to improve product quality, optimize production workflows, and reduce manual inspection requirements.
North America Inspection Robots Market held a 30.5% share in 2025. Regional growth is being supported by expanding industrial automation, broader implementation of Industry 4.0 technologies, and strict workplace safety requirements across manufacturing, energy and utilities, and critical infrastructure. Organizations are increasingly evaluating automated inspection systems to reduce personnel exposure to dangerous operating conditions while improving productivity and inspection consistency. Regulatory agencies, energy organizations, and industrial operators are encouraging the adoption of technologies that can strengthen workplace safety and improve operational performance. The region's established industrial base, continued investment in automation, and increasing focus on advanced inspection technologies are creating favorable conditions for robotic solutions.
Prominent companies operating in the global inspection robots market include FANUC CORPORATION, ABB Ltd., Cognex Corporation, Denso Wave, DSI Robotics, Energy Robotics GmbH, Honeybee Robotics, Ltd., Innok Robotics GmbH, JH Robotics, Inc., KUKA AG, Mitsubishi Heavy Industries, Ltd., Nexxis, Robotnik Automation S.L., Staubli, SuperDroid Robotics, and Universal Robots A/S. Companies in the inspection robots market are strengthening their market presence by investing in robotics research and development, artificial intelligence, machine vision, autonomous navigation, and advanced sensing technologies. Participants are expanding product portfolios to address different inspection requirements across industrial environments and infrastructure applications. Strategic partnerships with technology providers, industrial operators, system integrators, and research organizations are helping companies accelerate product development and improve commercial reach. Businesses are also focusing on software enhancements that improve robotic perception, data analysis, remote operation, and predictive maintenance capabilities. Geographic expansion and stronger distribution networks are enabling suppliers to reach new customers and industrial markets.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 – 2035
- 2.2 Key market trends
- 2.2.1 Type trends
- 2.2.2 Technology trends
- 2.2.3 Application trends
- 2.2.4 End-use industry trends
- 2.2.5 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factors affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Increasing industrial automation and Industry 4.0 adoption
- 3.2.1.2 Rising worker safety regulations and demand for remote inspection in hazardous environments
- 3.2.1.3 Growing investments in predictive maintenance and digital asset management
- 3.2.1.4 Expanding inspection requirements for aging energy, utility, and critical infrastructure assets
- 3.2.1.5 Rapid advancements in AI, autonomous navigation, machine vision, and industrial sensing technologies
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High initial deployment and integration costs
- 3.2.2.2 Limited operation in complex and unstructured environments
- 3.2.3 Market opportunities
- 3.2.3.1 Expansion of AI-powered autonomous inspection and predictive maintenance
- 3.2.3.2 Growing adoption across energy, utilities, and critical infrastructure inspection
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter’s analysis
- 3.6 PESTEL analysis
- 3.7 Technology and Innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By product
- 3.9 Pricing Strategies
- 3.10 Emerging Business Models
- 3.11 Compliance Requirements
- 3.12 Patent and IP analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.2 Market concentration analysis
- 4.2.1 By region
- 4.3 Competitive benchmarking of key players
- 4.3.1 Financial performance comparison
- 4.3.1.1 Revenue
- 4.3.1.2 Profit margin
- 4.3.1.3 R&D
- 4.3.2 Product portfolio comparison
- 4.3.2.1 Product range breadth
- 4.3.2.2 Technology
- 4.3.2.3 Innovation
- 4.3.3 Geographic presence comparison
- 4.3.3.1 Global footprint analysis
- 4.3.3.2 Service network coverage
- 4.3.3.3 Market penetration by region
- 4.3.4 Competitive positioning matrix
- 4.3.4.1 Leaders
- 4.3.4.2 Challengers
- 4.3.4.3 Followers
- 4.3.4.4 Niche players
- 4.3.5 Strategic outlook matrix
- 4.3.1 Financial performance comparison
- 4.4 Key developments
- 4.4.1 Mergers and acquisitions
- 4.4.2 Partnerships and collaborations
- 4.4.3 Technological advancements
- 4.4.4 Expansion and investment strategies
- 4.4.5 Digital transformation initiatives
- 4.5 Emerging/Startup competitors landscape
Chapter 5 Market Estimates and Forecast, By Type, 2022 – 2035 (USD Million)
- 5.1 Key trends
- 5.2 Non-autonomous
- 5.3 Semi-autonomous
- 5.4 Fully Autonomous
Chapter 6 Market Estimates and Forecast, By Technology, 2022 – 2035 (USD Million)
- 6.1 Key trends
- 6.2 Stationary
- 6.3 Mobile
Chapter 7 Market Estimates and Forecast, By Application, 2022 – 2035 (USD Million)
- 7.1 Key trends
- 7.2 Visual inspection
- 7.3 Ultrasonic inspection
- 7.4 Laser scanning inspection
- 7.5 Thermal inspection
- 7.6 Quality inspection
Chapter 8 Market Estimates and Forecast, By End Use Industry, 2022 – 2035 (USD Million)
- 8.1 Key trends
- 8.2 Oil & gas
- 8.3 Power & utilities
- 8.4 Petrochemical
- 8.5 Automotive
- 8.6 Construction
- 8.7 Food & beverages
- 8.8 Manufacturing
- 8.9 Others
Chapter 9 Market Estimates and Forecast, By Region, 2022 – 2035 (USD Million)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Spain
- 9.3.5 Italy
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.6 Middle East and Africa
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
Chapter 10 Company Profiles
- 10.1 Global Key Players
- 10.1.1 ABB Ltd.
- 10.1.2 FANUC CORPORATION
- 10.1.3 Mitsubishi Heavy Industries, Ltd.
- 10.1.4 KUKA AG
- 10.1.5 Universal Robots A/S
- 10.2 Regional key players
- 10.2.1 North America
- 10.2.1.1 Cognex Corporation
- 10.2.1.2 DSI Robotics
- 10.2.1.3 Honeybee Robotics, Ltd.
- 10.2.1.4 JH Robotics, Inc.
- 10.2.1.5 Superdroid Robotics
- 10.2.2 Asia Pacific
- 10.2.2.1 Denso Wave
- 10.2.3 Europe
- 10.2.3.1 Innok Robotics GmbH
- 10.2.3.2 Robotnik Automation S.L.
- 10.2.3.3 Staubli
- 10.2.1 North America
- 10.3 Niche Players/Disruptors
- 10.3.1 Energy Robotics GmbH
- 10.3.2 Nexxis

 檢測機器人市場-全球市場預測(2026-2032年)
 自主橋樑檢測機器人市場分析與預測(至2035年):類型、產品類型、服務、技術、組件、應用、部署狀態、最終用戶、功能、解決方案
 下水道檢測機器人市場規模、佔有率和成長分析:按機器人類型、管道直徑、應用、組件、最終用戶、移動方式和地區分類-2026-2033年產業預測
 2026-2030年全球檢測機器人市場
 2026年全球污水檢測機器人市場報告
 檢測機器人市場規模、佔有率和成長分析:按類型、組件、行動系統、應用、最終用戶產業和地區分類-2026-2033年產業預測
 2034年檢測機器人市場預測-全球分析(按機器人類型、平台類型、組件、技術、應用、部署模式、最終用戶和地區分類)防爆檢測機器人市場:依檢測技術、機器人類型、工作模式、電源、應用、最終用戶分類,全球預測(2026-2032年)暖通空調偵測機器人市場:依技術、偵測類型、機器人移動性、偵測模式、應用、最終用戶和銷售管道,全球預測,2026-2032年核檢測機器人市場按技術、移動類型、有效載荷類型、導航系統、推進類型、應用和最終用戶分類-全球預測,2026-2032年