


 |
市場調查報告書
商品編碼
2121128
水質監測市場機會、成長促進因素、產業趨勢分析及2026-2035年預測Water Quality Monitoring Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球水質監測市場預計到 2025 年價值 59 億美元,年複合成長率為 6.7%,到 2035 年將達到 110 億美元。
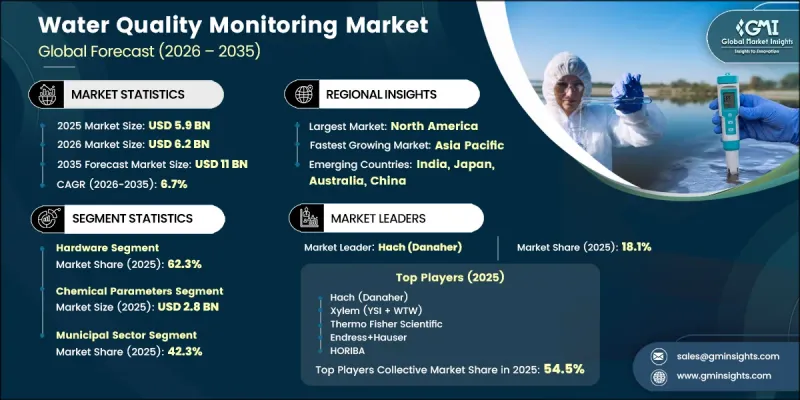
隨著各國政府、公共產業和產業組織持續重視有效的水資源管理和環境保護,水質監測市場正經歷持續成長。不斷完善的水安全法規結構,以及人們對水污染和新興污染物日益成長的擔憂,正在推動全球市場採用先進的監測解決方案。飲用水基礎設施和污水管理系統投資的增加,進一步促進了該產業的長期發展。此外,技術的快速進步正在變革水質監測產業,將互聯監測平台、智慧感測技術和自動化數據採集系統整合在一起,從而提高營運效率和決策能力。對持續環境監測、資源保護和公共衛生保護的日益重視,進一步催生了對可靠監測技術的需求。隨著監管合規要求的日益嚴格以及水資源管理營運數位轉型的加速推進,預計全球水質監測市場將在預測期內保持穩定成長。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 起始金額 | 59億美元 |
| 預測金額 | 110億美元 |
| 複合年成長率 | 6.7% |
水質監測市場持續受益於日益嚴格的監管政策,這些政策旨在保護水資源並維持高水質標準。政府加強支持力度,並持續致力於提升水安全,進一步加速了市政、工業和環境領域對先進監測技術的應用。不斷成長的多種水污染物監測監管要求,推動了對更精準、更有效率的分析解決方案的需求。同時,供水事業和工業營運商正將人工智慧 (AI)、雲端平台和預測分析技術融入其監測系統,以提升營運效率。這些先進的數位技術能夠實現持續資料收集、改善異常檢測、支援預測性維護並縮短回應時間,同時也能降低營運成本,提高系統整體效率。
預計到2025年,硬體部分將佔據62.3%的市場。該部分保持主導地位的原因在於,監測設備仍然是市政、工業設施、環保組織和污水處理企業進行水質評估的重要組成部分。對關鍵水質指標持續監測的更嚴格的監管要求,以及對智慧水資源管理基礎設施投資的增加,持續刺激對先進監測設備的需求。水系統的不斷現代化和自動化監測技術的日益普及,預計將在整個預測期內進一步提升硬體部分的成長機會。
預計到2025年,化學參數市場規模將達28億美元。該領域的成長持續受到飲用水、污水、工業製程和環境監測應用領域對關鍵水質指標進行全面分析的強勁需求的推動。日益嚴格的合規要求、不斷成長的工業污水排放量以及人們對水質問題的日益關注,正在推動全球對先進化學參數監測解決方案的投資,從而鞏固該領域的市場主導地位。
預計到2025年,北美水質監測市場佔有率將達到32.3%。該地區市場成長的持續驅動力來自日益嚴格的環境監管要求、對用水和污水基礎設施的持續投資,以及對改善長期水資源管理的日益關注。不斷提高的監管預期正促使市政當局、供水事業和行業組織採用先進的即時監測技術,以提高營運可靠性並確保符合不斷變化的水質標準。基礎設施的持續現代化以及對數位監測能力的重視預計將在整個預測期內維持該地區市場的擴張。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 成長促進因素
- 嚴格的水質法規和合規標準
- 增加對安全飲用水和污水處理基礎設施的投資
- 物聯網智慧水質監測系統的快速普及。
- 水污染日益嚴重,新的污染物不斷出現
- 加大力度監測環境並增強應對氣候變遷的能力
- 產業潛在風險與挑戰
- 先進水質監測系統高成本
- 與感測器污染、校準和數據可靠性相關的問題。
- 市場機遇
- 擴大智慧水網和數位化水資源管理
- 增加對水資源再利用、海水淡化和氣候變遷適應能力項目的投資。
- 成長促進因素
- 成長潛力分析
- 監理情勢
- 波特的分析
- PESTLE分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格趨勢
- 按地區
- 依產品
- 定價策略
- 新興經營模式
- 合規要求
- 專利和智慧財產權分析
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 市場集中度分析
- 主要公司的競爭標竿分析
- 財務績效比較
- 收入
- 利潤率
- R&D
- 產品系列比較
- 產品線寬度
- 科技
- 創新
- 區域擴張比較
- 全球擴張分析
- 服務網路覆蓋
- 按地區分類的市場滲透率
- 競爭定位矩陣
- 領導者
- 挑戰者
- 追蹤者
- 小眾玩家
- 戰略展望矩陣
- 財務績效比較
- 主要進展
- 併購
- 夥伴關係和聯盟
- 技術進步
- 擴張和投資策略
- 數位轉型計劃
- 新興企業競爭公司和新創企業的發展趨勢
第5章 市場估算與預測:依產品類型分類,2022-2035年
- 硬體
- 軟體
- 服務
第6章 市場估計與預測:依監測技術分類,2022-2035年
- 線上/連續監測系統
- 可攜式/現場監測系統
- 實驗室型監測系統
- 遠端/遙測監控系統
第7章 市場估計與預測:依參數類型分類,2022-2035年
- 物理參數
- 化學參數
- 生物參數
第8章 市場估計與預測:依應用領域分類,2022-2035年
- 飲用水監測
- 污水監測
- 地表水監測(河川、湖泊、水庫)
- 地下水監測
- 工業製程水監測
- 水產養殖監測
- 環境監測
- 休閒用水水質監測
第9章 市場估價與預測:依最終用戶分類,2022-2035年
- 地方政府部門
- 產業部門
- 環境與研究部門
- 商業領域
第10章 市場估價與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第11章:公司簡介
- 全球主要公司
- Hach(Danaher)
- Xylem(YSI+WTW)
- Thermo Fisher Scientific
- Endress+Hauser
- HORIBA
- 該地區的主要公司
- 北美洲
- Emerson
- Agilent
- Badger Meter
- Teledyne ISCO
- PerkinElmer
- 亞太地區
- Shimadzu
- Yokogawa
- Focused Photonics
- 歐洲
- ABB
- Mettler-Toledo
- Hanna Instruments
- KUNTZE Instruments
- 北美洲
- 小眾玩家/顛覆者
- In-Situ Inc.
The Global Water Quality Monitoring Market was valued at USD 5.9 billion in 2025 and is estimated to grow at a CAGR of 6.7% to reach USD 11 billion in 2035.
The market is experiencing sustained growth as governments, utilities, and industrial organizations continue to prioritize effective water resource management and environmental protection. Strengthening regulatory frameworks related to water safety, coupled with rising concerns surrounding water contamination and emerging pollutants, are driving broader adoption of advanced monitoring solutions across global markets. Increasing investment in drinking water infrastructure and wastewater management systems is further supporting long-term industry expansion. In addition, rapid technological progress is transforming the water quality monitoring industry by integrating connected monitoring platforms, smart sensing technologies, and automated data collection systems, thereby improving operational efficiency and decision-making. The growing emphasis on continuous environmental surveillance, resource conservation, and public health protection is creating additional demand for reliable monitoring technologies. As regulatory compliance requirements become more rigorous and digital transformation accelerates across water management operations, the global water quality monitoring market is expected to witness consistent growth throughout the forecast period.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $5.9 Billion |
| Forecast Value | $11 Billion |
| CAGR | 6.7% |
The water quality monitoring market continues to benefit from increasingly stringent regulatory policies aimed at protecting water resources and maintaining high water quality standards. Rising government support and ongoing initiatives focused on improving water safety are encouraging greater adoption of advanced monitoring technologies across municipal, industrial, and environmental applications. Expanding regulatory requirements for monitoring multiple categories of water contaminants are driving demand for more accurate and efficient analytical solutions. At the same time, water utilities and industrial operators are incorporating artificial intelligence, cloud-based platforms, and predictive analytics into monitoring systems to strengthen operational performance. These advanced digital technologies enable continuous data collection, improve anomaly detection, support predictive maintenance, and accelerate response times while reducing operating expenses and improving overall system efficiency.
The hardware segment held a 62.3% share in 2025. The segment maintains its leading position because monitoring equipment remains an essential component of water quality assessment across municipal utilities, industrial facilities, environmental organizations, and wastewater treatment operations. Growing regulatory requirements for continuous measurement of critical water quality indicators, combined with rising investment in intelligent water management infrastructure, continue to stimulate demand for advanced monitoring devices. Ongoing modernization of water systems and increased deployment of automated monitoring technologies are expected to further strengthen growth opportunities for the hardware segment over the forecast period.
The chemical parameters segment captured USD 2.8 billion in 2025. Strong demand for comprehensive analysis of essential water quality indicators across drinking water, wastewater, industrial processing, and environmental monitoring applications continues to support segment growth. Increasingly rigorous compliance requirements, expanding industrial wastewater generation, and heightened awareness regarding evolving water quality concerns are encouraging greater investment in advanced chemical parameter monitoring solutions worldwide, reinforcing the segment's dominant market position.
North America Water Quality Monitoring Market accounted for 32.3% share in 2025. Regional growth continues to be supported by stronger environmental compliance requirements, sustained investments in water and wastewater infrastructure, and increasing attention toward improving long-term water resource management. Rising regulatory expectations have encouraged municipalities, utility providers, and industrial organizations to deploy advanced real-time monitoring technologies to strengthen operational reliability and maintain compliance with evolving water quality standards. Continuous infrastructure modernization and greater emphasis on digital monitoring capabilities are expected to sustain regional market expansion throughout the forecast period.
Prominent companies operating in the global water quality monitoring market include ABB, Agilent, Badger Meter, Emerson, Endress+Hauser, Focused Photonics (FPI), Hach (Danaher), Hanna Instruments, HORIBA, In-Situ Inc., KUNTZE Instruments, Mettler-Toledo, PerkinElmer, Shimadzu, Teledyne ISCO, Thermo Fisher Scientific, Xylem (YSI + WTW), and Yokogawa. Companies participating in the water quality monitoring market are strengthening their market position by expanding product portfolios with advanced monitoring technologies, digital platforms, and intelligent sensing solutions. Many organizations are investing in research and development to improve measurement accuracy, system reliability, and operational efficiency while meeting evolving regulatory requirements. Strategic collaborations, distribution partnerships, and geographic expansion remain key approaches for increasing customer reach and strengthening regional presence. Manufacturers are also enhancing software capabilities through cloud connectivity, automation, and data analytics to provide greater value for utilities and industrial customers.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 – 2035
- 2.2 Key market trends
- 2.2.1 Offering trends
- 2.2.2 Monitoring technology trends
- 2.2.3 Parameter type trends
- 2.2.4 Application trends
- 2.2.5 End-user trends
- 2.2.6 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Stringent water quality regulations and compliance standards
- 3.2.1.2 Growing investments in safe drinking water and wastewater infrastructure
- 3.2.1.3 Rapid adoption of IoT-enabled smart water monitoring systems
- 3.2.1.4 Increasing water pollution and emergence of new contaminants
- 3.2.1.5 Expansion of environmental monitoring and climate resilience initiatives
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High cost of advanced water quality monitoring systems
- 3.2.2.2 Sensor fouling, calibration, and data reliability issues
- 3.2.3 Market opportunities
- 3.2.3.1 Expansion of smart water networks and digital water management
- 3.2.3.2 Increasing investments in water reuse, desalination, and climate resilience projects
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter’s analysis
- 3.6 PESTEL analysis
- 3.7 Technology and Innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By product
- 3.9 Pricing Strategies
- 3.10 Emerging Business Models
- 3.11 Compliance Requirements
- 3.12 Patent and IP analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.2 Market concentration analysis
- 4.2.1 By region
- 4.3 Competitive benchmarking of key players
- 4.3.1 Financial performance comparison
- 4.3.1.1 Revenue
- 4.3.1.2 Profit margin
- 4.3.1.3 R&D
- 4.3.2 Product portfolio comparison
- 4.3.2.1 Product range breadth
- 4.3.2.2 Technology
- 4.3.2.3 Innovation
- 4.3.3 Geographic presence comparison
- 4.3.3.1 Global footprint analysis
- 4.3.3.2 Service network coverage
- 4.3.3.3 Market penetration by region
- 4.3.4 Competitive positioning matrix
- 4.3.4.1 Leaders
- 4.3.4.2 Challengers
- 4.3.4.3 Followers
- 4.3.4.4 Niche players
- 4.3.5 Strategic outlook matrix
- 4.3.1 Financial performance comparison
- 4.4 Key developments
- 4.4.1 Mergers and acquisitions
- 4.4.2 Partnerships and collaborations
- 4.4.3 Technological advancements
- 4.4.4 Expansion and investment strategies
- 4.4.5 Digital transformation initiatives
- 4.5 Emerging/ startup competitors landscape
Chapter 5 Market Estimates and Forecast, By Offering Type, 2022 – 2035 (USD Million)
- 5.1 Key trends
- 5.2 Hardware
- 5.3 Software
- 5.4 Services
Chapter 6 Market Estimates and Forecast, By Monitoring Technology, 2022 – 2035 (USD Million)
- 6.1 Key trends
- 6.2 Online/continuous monitoring systems
- 6.3 Portable/field monitoring systems
- 6.4 Laboratory-based monitoring systems
- 6.5 Remote/telemetry monitoring systems
Chapter 7 Market Estimates and Forecast, By Parameter Type, 2022 – 2035 (USD Million)
- 7.1 Key trends
- 7.2 Physical parameters
- 7.3 Chemical parameters
- 7.4 Biological parameters
Chapter 8 Market Estimates and Forecast, By Application, 2022 – 2035 (USD Million)
- 8.1 Key trends
- 8.2 Drinking water monitoring
- 8.3 Wastewater monitoring
- 8.4 Surface water monitoring (rivers, lakes, reservoirs)
- 8.5 Groundwater monitoring
- 8.6 Industrial process water monitoring
- 8.7 Aquaculture monitoring
- 8.8 Environmental monitoring
- 8.9 Recreational water monitoring
Chapter 9 Market Estimates and Forecast, By End-User, 2022 – 2035 (USD Million)
- 9.1 Key trends
- 9.2 Municipal Sector
- 9.3 Industrial Sector
- 9.4 Environmental & Research Sector
- 9.5 Commercial Sector
Chapter 10 Market Estimates and Forecast, By Region, 2022 – 2035 (USD Million)
- 10.1 Key trends
- 10.2 North America
- 10.2.1 U.S.
- 10.2.2 Canada
- 10.3 Europe
- 10.3.1 Germany
- 10.3.2 UK
- 10.3.3 France
- 10.3.4 Spain
- 10.3.5 Italy
- 10.4 Asia Pacific
- 10.4.1 China
- 10.4.2 India
- 10.4.3 Japan
- 10.4.4 Australia
- 10.4.5 South Korea
- 10.5 Latin America
- 10.5.1 Brazil
- 10.5.2 Mexico
- 10.5.3 Argentina
- 10.6 Middle East and Africa
- 10.6.1 South Africa
- 10.6.2 Saudi Arabia
- 10.6.3 UAE
Chapter 11 Company Profiles
- 11.1 Global Key Players
- 11.1.1 Hach (Danaher)
- 11.1.2 Xylem (YSI + WTW)
- 11.1.3 Thermo Fisher Scientific
- 11.1.4 Endress+Hauser
- 11.1.5 HORIBA
- 11.2 Regional key players
- 11.2.1 North America
- 11.2.1.1 Emerson
- 11.2.1.2 Agilent
- 11.2.1.3 Badger Meter
- 11.2.1.4 Teledyne ISCO
- 11.2.1.5 PerkinElmer
- 11.2.2 Asia Pacific
- 11.2.2.1 Shimadzu
- 11.2.2.2 Yokogawa
- 11.2.2.3 Focused Photonics
- 11.2.3 Europe
- 11.2.3.1 ABB
- 11.2.3.2 Mettler-Toledo
- 11.2.3.3 Hanna Instruments
- 11.2.3.4 KUNTZE Instruments
- 11.2.1 North America
- 11.3 Niche Players/Disruptors
- 11.3.1 In-Situ Inc.

 線上水硬度分析儀市場:全球市場預測,2026-2032年
 水質監測市場預測至2034年:按產品類型、測量參數、採樣方法、應用、最終用戶和地區分類的全球分析水質感測器市場:2026-2032年全球市場預測(按感測器類型、產品類型、技術、連接方式、水類型、應用和最終用戶分類)
 水質分析儀市場規模、佔有率和成長分析:按產品組合、分析參數、終端用戶產業、分銷通路和地區分類-2026-2033年產業預測
 水質感測器市場:按類型、應用和地區分類(2026-2034 年)電導率感測器市場:按感測器類型、技術和終端用戶產業分類-2026-2032年全球市場預測
 水質分析儀市場機會、成長要素、產業趨勢分析及2026-2035年預測水質線上分析儀市場:按組件、安裝類型、技術、測量項目、應用和最終用戶分類 - 全球預測 2026-2032重金屬水質自動線上監測市場:按組件、水源、連接方式、待測金屬類型、技術、應用和最終用戶分類-2026-2032年全球預測按產品類型、技術、參數和最終用戶分類的自動化線上水質分析儀市場—全球預測,2026-2032年