


 |
市場調查報告書
商品編碼
2121122
PEM電解槽。PEM Electrolyzer Catalyst Materials Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球 PEM電解槽催化劑材料市場預計到 2025 年價值 1.455 億美元,預計到 2035 年將達到 17 億美元,複合年成長率為 25.3%。
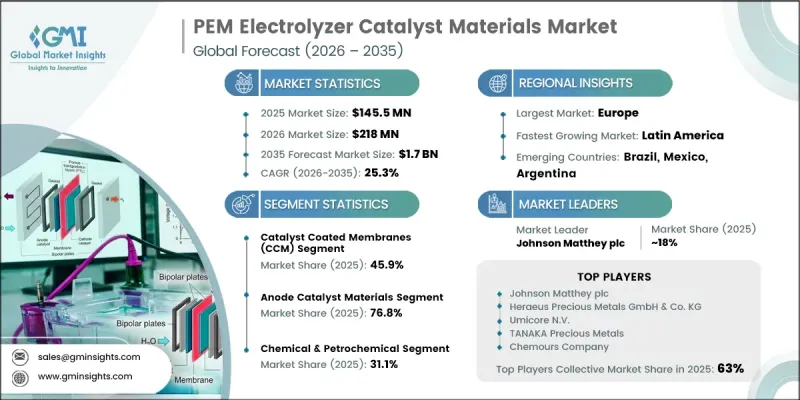
隨著各國和各產業加速向綠色氫能和低碳能源系統轉型,該市場正蓬勃發展。 PEM電解槽依靠催化材料來促進電化學反應,將水分解成氫氣和氧氣。隨著電解槽範圍的擴大,製造商持續專注於催化劑的性能、耐久性、效率和材料利用率。銥基材料繼續應用於陽極,而鉑基材料由於其催化性能、運行效率和在酸性環境中的穩定性,在陰極應用中仍然發揮著至關重要的作用。氫氣生產能力投資的增加、電解槽技術的進步以及減排力度的加大,為催化劑材料供應商創造了有利的環境。隨著氫能計畫走向大規模部署,全球PEM電解槽材料產業對可靠、高性能催化劑材料的需求將持續成長。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 起始金額 | 1.455億美元 |
| 預測金額 | 17億美元 |
| 複合年成長率 | 25.3% |
預計到2025年,催化劑塗層(CCM)將佔據45.9%的市場。市場參與企業不斷努力平衡大規模生產需求與催化劑的高效利用以及電解槽堆組裝的實際要求。由於原始設備製造商(OEM)的生產配置各不相同,供應商必須在催化劑供應形式、製造流程和整合方法方面保持柔軟性。這一趨勢持續影響整個催化劑供應形式領域的採購決策和競爭定位。
到2025年,化工和石化產業將佔據31.1%的市場。化學和石化行業的企業正擴大採用綠色氫能,以減少碳排放並推動永續性目標。隨著各行業尋求更清潔的生產方式並更好地契合脫碳目標,氫能在工業活動中的廣泛應用也推動了市場成長。對氫基工業流程投資的不斷增加,持續為PEM電解槽材料供應商創造新的機會。
2025年,北美PEM電解槽催化劑材料市佔率將達28%。該地區市場持續受益於綠色氫能基礎設施投資的增加以及政府支持的清潔能源舉措。人們對氫氣生產、乾淨科技應用和減排的日益關注,正在推動整個氫能價值鏈的投資。這些趨勢為尋求拓展北美市場的催化劑材料製造商和供應商創造了有利環境。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 成長促進因素
- 產業潛在風險與挑戰
- 市場機遇
- 成長潛力分析
- 監理情勢
- 波特的分析
- PESTLE分析
- 價格趨勢
- 按地區
- 按作物類型
- 未來市場趨勢
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 專利趨勢
- 貿易統計
- 主要進口國
- 主要出口國
- 永續性和環境方面
- 永續計劃
- 減少廢棄物策略
- 生產中的能源效率
- 具有環保意識的舉措
- 考慮碳足跡
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 按地區
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃
第5章 市場估算與預測:依催化劑材料分類,2022-2035年
- 陽極催化劑材料(OER)
- 銥基催化劑
- 釕基催化劑
- 非貴金屬陽極
- 陰極催化劑材料(析氫反應)
- 鉑催化劑
- 非貴金屬陰極
第6章 市場估算與預測:依產品分類,2022-2035年
- 無載體催化劑粉末
- 碳載催化劑粉末
- 催化劑油墨和分散體
- 催化劑塗層膜(CCM)
- 催化劑塗層基板/多孔傳輸電極(PTE)
第7章 市場估計與預測:依應用領域分類,2022-2035年
- 綠氫作為工業原料
- 電能轉氣及電網級儲能
- 移動出行和交通運輸領域的氫能供應
- 分散式和現場氫氣
第8章 市場估算與預測:依最終用戶產業分類,2022-2035年
- 能源和發電
- 化工/石油化工
- 石油煉製和鋼鐵生產
- 汽車與出行
- 調查、政府與國防
第9章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 其他亞太國家
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 其他拉丁美洲國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- UAE
- 其他中東和非洲國家
第10章:公司簡介
- Advent Technologies Holdings Inc.
- Chemours Company
- Clariant AG
- Elchemtech Co., Ltd.
- Greenerity GmbH
- Heraeus Precious Metals GmbH & Co. KG
- HyPlat(Pty)Ltd
- Johnson Matthey plc
- Magneto/Elicron
- Ningbo Zhongke Kechuang
- TANAKA Precious Metals
- Umicore NV
The Global PEM Electrolyzer Catalyst Materials Market was valued at USD 145.5 million in 2025 and is estimated to grow at a CAGR of 25.3% to reach USD 1.7 billion by 2035.
The market is gaining momentum as countries and industries accelerate the transition toward green hydrogen and low-carbon energy systems. PEM electrolyzers rely on catalyst materials to facilitate the electrochemical reaction that separates water into hydrogen and oxygen. Manufacturers continue to focus on catalyst performance, durability, efficiency, and material utilization as electrolyzer deployment expands. Iridium-based materials continue to support anode applications, while platinum-based materials remain important for cathode applications because of their catalytic performance, operational efficiency, and stability under acidic operating conditions. Growing investments in hydrogen production capacity, improvements in electrolyzer technology, and increasing efforts to reduce emissions are creating favorable conditions for catalyst material suppliers. As hydrogen projects move toward larger-scale deployment, demand for reliable and high-performance catalyst materials is expected to increase across the global PEM electrolyzer catalyst materials industry.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $145.5 Million |
| Forecast Value | $1.7 Billion |
| CAGR | 25.3% |
Catalyst coated membranes (CCM) held a 45.9% share in 2025. Market participants continue to balance large-scale manufacturing requirements with efficient catalyst utilization and the practical requirements associated with electrolyzer stack assembly. Different OEM production configurations require suppliers to maintain flexibility in catalyst delivery formats, manufacturing processes, and integration methods. This dynamic continues to influence purchasing decisions and competitive positioning across the catalyst delivery form segment.
The chemical & petrochemical segment captured 31.1% share in 2025. Companies across the chemical and petrochemical industries are increasingly adopting green hydrogen as part of their efforts to lower carbon emissions and advance sustainability targets. The expanding use of hydrogen in industrial operations is also supporting market growth as industries seek cleaner production pathways and greater alignment with decarbonization objectives. Rising investment in hydrogen-based industrial processes continues to create additional opportunities for PEM electrolyzer catalyst material suppliers.
North America PEM Electrolyzer Catalyst Materials Market captured 28% share in 2025. The regional market continues to benefit from increased investment in green hydrogen infrastructure and government-supported clean energy initiatives. Growing attention toward hydrogen production, clean technology deployment, and emissions reduction is encouraging investment throughout the hydrogen value chain. These developments are creating favorable conditions for catalyst material manufacturers and suppliers seeking to expand their presence in the North American market.
Prominent companies operating in the global PEM electrolyzer catalyst materials market include TANAKA Precious Metals, Umicore N.V., Advent Technologies Holdings Inc., Johnson Matthey plc, HyPlat (Pty) Ltd, Chemours Company, Heraeus Precious Metals GmbH & Co. KG, Magneto / Elicron, Clariant AG, Ningbo Zhongke Kechuang, Greenerity GmbH, and Elchemtech Co., Ltd. Companies in the global pem electrolyzer catalyst materials market are strengthening their market position by expanding catalyst production capabilities, improving material efficiency, and investing in research and development. Manufacturers are focusing on enhancing catalyst performance while reducing material requirements and improving operational durability. Strategic collaborations and technology development initiatives allow companies to address the evolving requirements of electrolyzer manufacturers. Market participants are also working to expand production capacity as demand for PEM electrolyzer systems increases globally. Regional expansion remains another important strategy, with companies seeking stronger access to emerging hydrogen markets and large-scale clean energy projects. Suppliers are also emphasizing product consistency, manufacturing scalability, and integration compatibility to build long-term relationships with electrolyzer and stack manufacturers. These strategies help companies improve their competitive position while supporting the broader commercialization and deployment of PEM electrolyzer technology.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Catalyst material
- 2.2.3 Product
- 2.2.4 Application
- 2.2.5 End user industry
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.1.5 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.2 Industry pitfalls and challenges
- 3.2.3 Market opportunities
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter’s analysis
- 3.6 PESTEL analysis
- 3.7 Price trends
- 3.7.1 By region
- 3.7.2 By crop type
- 3.8 Future market trends
- 3.9 Technology and innovation landscape
- 3.9.1 Current technological trends
- 3.9.2 Emerging technologies
- 3.10 Patent Landscape
- 3.11 Trade statistics (HS code)
- 3.11.1 Major importing countries
- 3.11.2 Major exporting countries
- 3.12 Sustainability and environmental aspects
- 3.12.1 Sustainable practices
- 3.12.2 Waste reduction strategies
- 3.12.3 Energy efficiency in production
- 3.12.4 Eco-friendly initiatives
- 3.13 Carbon footprint consideration
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 LATAM
- 4.2.1.5 MEA
- 4.2.1 By region
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New Product Launches
- 4.5.4 Expansion Plans
Chapter 5 Market Estimates and Forecast, By Catalyst Material, 2022–2035 (USD Billion) (Kilo Tons)
- 5.1 Key trends
- 5.2 Anode catalyst materials (OER)
- 5.2.1 Iridium-based catalysts
- 5.2.2 Ruthenium-based catalysts
- 5.2.3 Non-precious metal anode
- 5.3 Cathode catalyst materials (HER)
- 5.3.1 Platinum-based catalysts
- 5.3.2 Non-precious metal cathode
Chapter 6 Market Estimates and Forecast, By Product, 2022–2035 (USD Billion) (Kilo Tons)
- 6.1 Key trends
- 6.2 Unsupported catalyst powders
- 6.3 Carbon-supported catalyst powders
- 6.4 Catalyst inks & dispersions
- 6.5 Catalyst coated membranes (CCM)
- 6.6 Catalyst coated substrates / Porous transport electrodes (PTE)
Chapter 7 Market Estimates and Forecast, By Application, 2022–2035 (USD Billion) (Kilo Tons)
- 7.1 Key trends
- 7.2 Green H₂ for industrial feedstock
- 7.3 Power-to-gas & grid-scale energy storage
- 7.4 Mobility & transportation H₂ supply
- 7.5 Distributed & on-site H₂ generation
Chapter 8 Market Estimates and Forecast, By End User Industry, 2022–2035 (USD Billion) (Kilo Tons)
- 8.1 Key trends
- 8.2 Energy & power generation
- 8.3 Chemical & petrochemical
- 8.4 Oil refining & steel production
- 8.5 Automotive & mobility
- 8.6 Research, government & defense
Chapter 9 Market Estimates and Forecast, By Region, 2022–2035 (USD Billion) (Kilo Tons)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Spain
- 9.3.5 Italy
- 9.3.6 Rest of Europe
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.4.6 Rest of Asia Pacific
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.5.4 Rest of Latin America
- 9.6 Middle East and Africa
- 9.6.1 Saudi Arabia
- 9.6.2 South Africa
- 9.6.3 UAE
- 9.6.4 Rest of Middle East and Africa
Chapter 10 Company Profiles
- 10.1 Advent Technologies Holdings Inc.
- 10.2 Chemours Company
- 10.3 Clariant AG
- 10.4 Elchemtech Co., Ltd.
- 10.5 Greenerity GmbH
- 10.6 Heraeus Precious Metals GmbH & Co. KG
- 10.7 HyPlat (Pty) Ltd
- 10.8 Johnson Matthey plc
- 10.9 Magneto / Elicron
- 10.10 Ningbo Zhongke Kechuang
- 10.11 TANAKA Precious Metals
- 10.12 Umicore N.V.

 PEM電解槽材料市場規模、佔有率、成長、全球產業分析、區域趨勢及2026年至2034年預測。
 電解槽材料及製造市場預測至2034年-全球分析(依電解槽類型、關鍵材料、製造流程、供應鏈階段、應用、最終用戶及地區分類)2026-2034年全球PEM電解槽材料市場規模、佔有率、趨勢與成長分析報告
 PEM水電解槽市場-全球產業規模、佔有率、趨勢、機會、預測:按類型、應用、地區和競爭格局分類,2021-2031年
 PEM電解槽市場:2026-2032年全球市場預測(按堆疊尺寸、運作模式、催化劑類型、應用和最終用戶分類)
 PEM電解市場規模、佔有率和成長分析(按應用、容量範圍、安裝類型和地區分類)-2026-2033年產業預測
 PEM 電解器市場機會、成長動力、產業趨勢分析及 2025 - 2034 年預測2032 年 PEM電解槽市場預測:按組件、容量、應用、最終用戶和地區進行的全球分析
 PEM電解槽市場 - 全球和區域分析:按最終用戶、材料類型和區域 - 分析和預測(2025-2034)