

 |
市場調查報告書
商品編碼
2121103
折疊式OLED顯示器市場機會、成長促進因素、產業趨勢分析及2026-2035年預測Foldable OLED Display Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

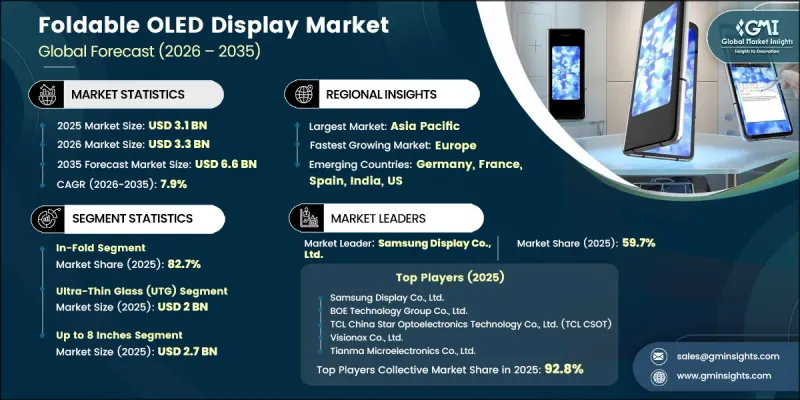
全球折疊式OLED 顯示器市場預計到 2025 年將達到 31 億美元,到 2035 年將以 7.9% 的複合年成長率成長至 66 億美元。
隨著高階消費性電子產品和折疊式設備應用領域對軟性顯示器技術的需求持續旺盛,市場規模不斷擴大。隨著新一代軟性OLED和UHG面板的研發,折疊式顯示器解決方案的性能和商業性潛力也不斷提升。製造商正致力於提高亮度、能源效率、耐用性、柔軟性和良率,以滿足不斷變化的產品需求。此外,隨著折疊式顯示面板的日益普及,顯示器製造商正積極提升產能並最佳化生產流程。政府推出的利多政策支持下一代顯示器製造,為產業相關人員創造了更多機會;同時,對先進生產設施的持續投資也加速了商業化進程。顯示材料、製造精度、保護技術和軟性面板設計的改進,正幫助製造商克服折疊式顯示器在性能和耐用性方面面臨的挑戰。消費者對高階設備日益成長的需求以及對顯示器研發的持續投入,預計將進一步推動市場擴張。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 起始金額 | 31億美元 |
| 預測金額 | 66億美元 |
| 複合年成長率 | 7.9% |
預計到2025年,內折疊顯示器將佔據82.7%的市場。內折疊顯示器結構因其在設備閉合時能更好地保護軟性顯示器表面而日益普及。這種結構最大限度地減少了顯示器暴露於外部刮擦、物理接觸和其他可能導致顯示器損壞的因素的風險。憑藉其防護性、可靠性和耐用性,內折疊顯示器在製造商和用戶中的應用持續成長。軟性面板結構、鉸鏈機制、保護層和顯示材料的不斷改進,進一步提升了內折疊設計的整體性能。隨著各方不斷努力提高產品耐用性和延長顯示器運作,預計在整個預測期內,該細分市場將更加強勁成長。
預計到2025年,超薄玻璃(UTG)市場規模將達20億美元。 UTG技術憑藉其耐刮擦性、光學清晰度、耐用性和媲美玻璃的高級表面觸感,保持著強勁的市場地位。與傳統的塑膠基底保護材質相比,超薄玻璃在提供更優異表面性能的同時,還能維持折疊式顯示器應用所需的柔軟性。玻璃加工、厚度控制、柔軟性和耐用性方面的持續進步,推動了製造商不斷提升UTG解決方案的性能。隨著人們對顯示器保護和高階設備品質的日益重視,預計在整個預測期內,對超薄玻璃的需求將持續成長。
預計到2025年,北美折疊式OLED顯示器市場佔有率將達到17.5%。推動該地區市場成長的主要因素是消費者對高階電子產品的強勁需求,以及折疊式設備在消費和企業應用中的日益普及。對先進顯示器和半導體技術的持續研發投入也促進了該地區的成長。製造商和科技公司正加大對顯示技術的創新投入,以提升產品的柔軟性、耐用性、能源效率和整體性能。對先進顯示體驗日益成長的需求,以及技術的不斷進步,正在推動折疊式OLED技術在全部區域得到更廣泛的應用。預計對下一代顯示技術及相關技術的持續投入,將為參與企業創造更多商機。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 成長促進因素
- 折疊式智慧型手機和高階消費性電子產品的日益普及。
- 軟性OLED材料和超薄玻璃(UTG)技術的不斷進步
- OLED顯示器在汽車和智慧運輸領域的廣泛應用。
- 政府對先進半導體和顯示器製造生態系統的支持
- 擴大對下一代OLED製造能力和生產效率的投資
- 產業潛在風險與挑戰
- 折疊式OLED面板和先進材料的高製造成本
- 人們對折疊式顯示器的耐用性和可靠性存在擔憂
- 市場機遇
- 折疊式OLED在汽車、筆記型電腦和智慧型裝置的應用不斷擴展。
- 下一代OLED材料和可擴展製造技術的開發
- 成長促進因素
- 成長潛力分析
- 監理情勢
- 波特的分析
- PESTLE分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格趨勢
- 按地區
- 依產品
- 定價策略
- 新興經營模式
- 合規要求
- 專利和智慧財產權分析
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 市場集中度分析
- 主要公司的競爭標竿分析
- 財務績效比較
- 收入
- 利潤率
- R&D
- 產品系列比較
- 產品線寬度
- 科技
- 創新
- 區域擴張比較
- 全球擴張分析
- 服務網路覆蓋
- 按地區分類的市場滲透率
- 競爭定位矩陣
- 領導者
- 挑戰者
- 追蹤者
- 小眾玩家
- 戰略展望矩陣
- 財務績效比較
- 主要進展
- 併購
- 夥伴關係和聯盟
- 技術進步
- 擴張和投資策略
- 數位轉型計劃
- 新興企業競爭公司和新創企業的趨勢
第5章 市場估算與預測:依折疊式架構分類,2022-2035年
- 訊息-rd
- 外折疊
- 多折
第6章 市場估計與預測:依材質分類的蓋窗市場,2022-2035年
- 超薄玻璃(UTG)
- 無色聚醯亞胺(CPI)/塑膠薄膜
第7章 市場估計與預測:依樣本規模分類,2022-2035年
- 8英吋或更小
- 8英寸至13英寸
- 13吋或更大
第8章 市場估計與預測:依應用領域分類,2022-2035年
- 智慧型手機
- 藥片
- 筆記型電腦
- 汽車顯示器
- 其他
第9章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第10章:公司簡介
- 全球主要公司
- Samsung Display Co., Ltd.
- BOE Technology Group Co., Ltd.
- TCL China Star Optoelectronics Technology Co., Ltd.(TCL CSOT)
- Visionox Co., Ltd.
- Tianma Microelectronics Co., Ltd.
- 該地區的主要公司
- 亞太地區
- LG Display Co., Ltd.
- Everdisplay Optronics(EDO)
- 亞太地區
The Global Foldable OLED Display Market was valued at USD 3.1 billion in 2025 and is estimated to grow at a CAGR of 7.9% to reach USD 6.6 billion by 2035.
The market is advancing as demand for flexible display technologies continues to increase across premium consumer electronics and foldable device applications. Ongoing development of next-generation flexible OLED panels and UHG panels is improving the performance and commercial potential of foldable display solutions. Manufacturers are focusing on enhancing brightness, energy efficiency, durability, flexibility, and production yields to address evolving product requirements. The broader adoption of foldable display panels is also encouraging display manufacturers to increase production capabilities and optimize manufacturing processes. Favorable government initiatives supporting next-generation display manufacturing are creating additional opportunities for industry participants, while increasing investments in advanced production facilities are accelerating commercialization. Improvements in display materials, manufacturing precision, protective technologies, and flexible panel design are helping manufacturers overcome performance and durability challenges associated with foldable displays. Growing consumer interest in premium devices and continuous investment in display research and development are expected to support further market expansion.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $3.1 Billion |
| Forecast Value | $6.6 Billion |
| CAGR | 7.9% |
The in-fold segment accounted for an 82.7% share in 2025. In-fold display architecture is gaining preference because its inward-folding structure provides greater protection for the flexible display surface when the device is closed. The configuration can help minimize exposure to external scratches, physical contact, and other potential sources of display damage. Its combination of protection, reliability, and durability is supporting continued adoption among manufacturers and users. Ongoing improvements in flexible panel construction, hinge mechanisms, protective layers, and display materials are further enhancing the overall performance of in-fold designs. Increasing efforts to improve product durability and extend display operating life are expected to reinforce the segment's position throughout the forecast period.
The Ultra-Thin Glass (UTG) segment held USD 2 billion in 2025. UTG technology maintains a strong market position because it provides a combination of scratch resistance, optical clarity, durability, and a premium glass-like surface experience. Compared with conventional plastic-based protective materials, ultra-thin glass can provide enhanced surface characteristics while maintaining the flexibility required for foldable display applications. Continued advances in glass processing, thickness control, flexibility, and durability are helping manufacturers improve the performance of UTG solutions. Increasing emphasis on display protection and premium device quality is expected to sustain demand for ultra-thin glass throughout the forecast period.
North America Foldable OLED Display Market recorded a 17.5% share in 2025. The regional market is supported by strong consumer interest in premium electronic products and increasing acceptance of foldable devices across consumer and enterprise applications. Continued research and development spending in advanced display and semiconductor technologies is also contributing to regional growth. Manufacturers and technology companies are investing in display innovation to improve flexibility, durability, energy efficiency, and overall product performance. Growing demand for advanced display experiences, combined with ongoing technological development, is encouraging further adoption of foldable OLED technology across the region. Continued investments in next-generation display capabilities and supporting technologies are expected to create additional opportunities for market participants in North America.
Prominent companies operating in the global foldable OLED display market include Samsung Display Co., Ltd., BOE Technology Group Co., Ltd., LG Display Co., Ltd., TCL China Star Optoelectronics Technology Co., Ltd. (TCL CSOT), Tianma Microelectronics Co., Ltd., Everdisplay Optronics (EDO), and Visionox Co., Ltd. Companies in the global foldable OLED display market are strengthening their market positions through research and development, manufacturing expansion, technology optimization, strategic partnerships, and continuous product innovation. Leading manufacturers are investing in flexible OLED panel technologies to improve brightness, durability, power efficiency, optical performance, and production yields. Businesses are also increasing manufacturing capabilities and optimizing production processes to support growing demand and improve cost efficiency. Strategic collaborations across the display technology ecosystem are helping companies accelerate innovation and strengthen supply capabilities. Manufacturers are focusing on advanced protective materials, flexible substrates, ultra-thin glass, and improved panel structures to enhance product reliability. Expanding technology portfolios allows companies to address changing requirements across different applications and product categories. Companies are also strengthening their global manufacturing networks and investing in advanced production facilities to improve scalability. These strategies are helping industry participants enhance technological capabilities, expand customer relationships, improve manufacturing efficiency, and reinforce their competitive foothold in the global foldable OLED display market.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 – 2035
- 2.2 Key market trends
- 2.2.1 Folding architecture trends
- 2.2.2 Cover window material trends
- 2.2.3 Panel size trends
- 2.2.4 Application trends
- 2.2.5 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising adoption of foldable smartphones and premium consumer electronics
- 3.2.1.2 Continuous advancements in flexible OLED materials and ultra-thin glass (UTG) technologies
- 3.2.1.3 Expansion of OLED displays into automotive and smart mobility applications
- 3.2.1.4 Government support for advanced semiconductor and display manufacturing ecosystems
- 3.2.1.5 Increasing investments in next-generation OLED manufacturing capacity and production efficiency
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High manufacturing costs of foldable OLED panels and advanced materials
- 3.2.2.2 Durability and reliability concerns associated with foldable displays
- 3.2.3 Market opportunities
- 3.2.3.1 Increasing foldable OLED applications in automotive, laptops, and smart devices
- 3.2.3.2 Development of next-generation OLED materials and scalable manufacturing technologies
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter’s analysis
- 3.6 PESTEL analysis
- 3.7 Technology and Innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By product
- 3.9 Pricing Strategies
- 3.10 Emerging Business Models
- 3.11 Compliance Requirements
- 3.12 Patent and IP analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.2 Market concentration analysis
- 4.2.1 By region
- 4.3 Competitive benchmarking of key players
- 4.3.1 Financial performance comparison
- 4.3.1.1 Revenue
- 4.3.1.2 Profit margin
- 4.3.1.3 R&D
- 4.3.2 Product portfolio comparison
- 4.3.2.1 Product range breadth
- 4.3.2.2 Technology
- 4.3.2.3 Innovation
- 4.3.3 Geographic presence comparison
- 4.3.3.1 Global footprint analysis
- 4.3.3.2 Service network coverage
- 4.3.3.3 Market penetration by region
- 4.3.4 Competitive positioning matrix
- 4.3.4.1 Leaders
- 4.3.4.2 Challengers
- 4.3.4.3 Followers
- 4.3.4.4 Niche players
- 4.3.5 Strategic outlook matrix
- 4.3.1 Financial performance comparison
- 4.4 Key developments
- 4.4.1 Mergers and acquisitions
- 4.4.2 Partnerships and collaborations
- 4.4.3 Technological advancements
- 4.4.4 Expansion and investment strategies
- 4.4.5 Digital transformation initiatives
- 4.5 Emerging/ startup competitors landscape
Chapter 5 Market Estimates and Forecast, By Folding Architecture, 2022 – 2035 (USD Million)
- 5.1 Key trends
- 5.2 In-fold
- 5.3 Out-fold
- 5.4 Multi-fold
Chapter 6 Market Estimates and Forecast, By Cover Window Material, 2022 – 2035 (USD Million)
- 6.1 Key trends
- 6.2 Ultra-thin glass (UTG)
- 6.3 Colorless polyimide (CPI) / plastic film
Chapter 7 Market Estimates and Forecast, By Panel Size, 2022 – 2035 (USD Million)
- 7.1 Key trends
- 7.2 Up to 8 inches
- 7.3 Above 8 inches to 13 inches
- 7.4 Above 13 inches
Chapter 8 Market Estimates and Forecast, By Application, 2022 – 2035 (USD Million)
- 8.1 Key trends
- 8.2 Smartphones
- 8.3 Tablets
- 8.4 Laptops
- 8.5 Automotive displays
- 8.6 Others
Chapter 9 Market Estimates and Forecast, By Region, 2022 – 2035 (USD Million)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Spain
- 9.3.5 Italy
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.6 Middle East and Africa
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
Chapter 10 Company Profiles
- 10.1 Global Key Players
- 10.1.1 Samsung Display Co., Ltd.
- 10.1.2 BOE Technology Group Co., Ltd.
- 10.1.3 TCL China Star Optoelectronics Technology Co., Ltd. (TCL CSOT)
- 10.1.4 Visionox Co., Ltd.
- 10.1.5 Tianma Microelectronics Co., Ltd.
- 10.2 Regional key players
- 10.2.1 Asia Pacific
- 10.2.1.1 LG Display Co., Ltd.
- 10.2.1.2 Everdisplay Optronics (EDO)
- 10.2.1 Asia Pacific

 OLED照明市場:全球市場預測(2026-2032年)OLED市場-2026-2032年全球市場預測
 OLED:市場佔有率分析、產業趨勢和統計數據、成長預測(2026-2031)
 有機發光二極體(OLED)市場規模、佔有率和成長分析:按產品類型、技術、應用和地區分類-2026-2033年產業預測
 軟性OLED全球市場規模、佔有率、趨勢和成長分析報告(2026-2034年)OLED面板:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031年)有機發光二極體市場:按產品類型、技術和最終用戶分類-2026-2032年全球市場預測
 OLED面板市場規模、佔有率、趨勢和預測:按類型、技術、尺寸、最終用戶和地區分類,2026-2034年有機發光二極體(OLED)市場規模:按產品類型、技術、應用、最終用途領域和地區分類(2026-2034 年)
 折疊式OLED顯示器市場報告:趨勢、預測與競爭分析(至2035年)