


 |
市場調查報告書
商品編碼
2109245
智慧農業市場機會、成長要素、產業趨勢分析及2026-2035年預測Smart Agriculture Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球智慧農業市場預計到 2025 年將達到 232 億美元,年複合成長率為 9.7%,到 2035 年將達到 596 億美元。
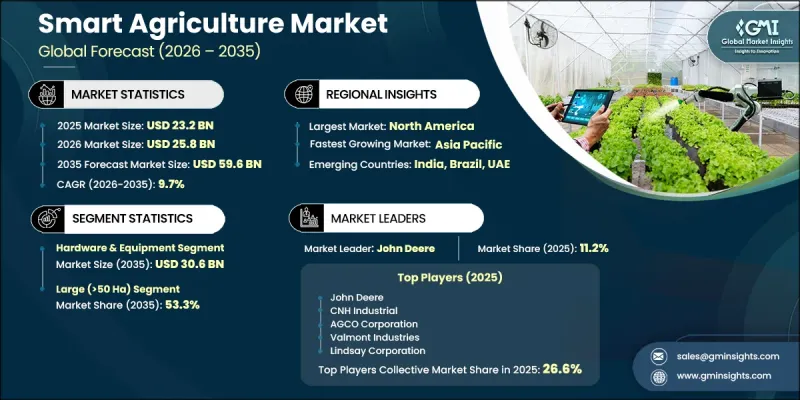
有利的監管政策持續推動主要農業經濟體採用先進農業技術,從而支撐了市場成長。公共部門推出的促進精密農業和數位農業的舉措,使技術投資更容易獲得,幫助更多農民實現生產方式的現代化。全球糧食安全、人口成長和耕地面積減少等問題日益受到關注,也推動了對智慧農業解決方案的需求,這些方案旨在提高生產力並最佳化農業資源利用。農民擴大採用精準技術,以更有效率地施用肥料、農藥和灌溉用水,從而最大限度地提高產量,同時減少不必要的資源消耗。同時,連網型設備、自動化、數據分析和數位農場管理平台的快速發展正在變革農場管理,並提升決策品質。這些趨勢進一步鞏固了智慧農業市場的長期前景,先進農業技術正成為提升全球農業營運效率、永續性和生產力的重要工具。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 232億美元 |
| 預測金額 | 596億美元 |
| 複合年成長率 | 9.7% |
隨著生產者加大對數位技術的投資,以改善農場管理、營運效率和長期生產力,智慧農業產業持續擴張。互聯設備、精準監測系統、自動化和先進分析技術的應用,正幫助農業企業最佳化資源利用,並支援更明智的營運決策。對數位基礎設施和互聯農業技術的投資增加,進一步推動了智慧農業解決方案在商業農業企業中的應用。精密農業技術的持續進步,可望透過提高生產力、降低營運成本和加強永續農業實踐,進一步加速市場成長。
預計到2025年,硬體和設備市場規模將達到135億美元,到2035年將達到306億美元。這是因為物理技術對於支持數位化農場運作至關重要。精密農業所使用的設備能夠收集田間數據、實現農業活動的自動化,並實施智慧管理系統,進而提升農場的整體績效。對先進農業設備的需求持續推動市場擴張,因為通常需要先部署硬體基礎設施才能充分利用軟體平台和數位服務。預計在整個預測期內,對現代農業技術的投資增加將進一步加速該領域的成長。
到2025年,大型農場(超過50公頃)將佔據53.3%的市場佔有率,成為以農場規模分類的最大類別。大型農業企業擁有更雄厚的財力投資先進設備和數位化農業解決方案,因此持續推動技術的應用。隨著農場規模的擴大,精密農業技術的經濟效益也愈發顯著,大型農場可以透過提高效率和生產力獲得更高的技術投資回報。隨著人們越來越重視在降低資源消耗的同時實現產量最大化,預計大規模商業農業企業對智慧農業技術的需求將保持強勁。
預計到2025年,美國智慧農業市佔率將達到73.8%。市場成長主要得益於高度發展的農業部門、精密農業技術的廣泛應用以及對先進數位農業解決方案的大力投資。公共和私人部門持續投資於互聯農業基礎設施、數位化農場管理系統和精密農業技術,正在加速商業化農業生產中技術的普及應用。此外,美國擁有完善的農業機械製造商、技術開發商和創新農業技術公司生態系統,進一步鞏固了主導地位。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 每個階段增加的價值
- 影響價值鏈的因素
- 影響產業的因素
- 促進因素
- 人工智慧/機器學習和精密農業技術的普及
- 農業勞動成本上升和結構性勞動力短缺
- 政府補貼和數位農業政策計劃
- 產業潛在風險與挑戰
- 前期資本投入龐大,且投資報酬率需要較長時間才能回收。
- 農業部門存在數位素養差距和熟練勞動力短缺的問題
- 機會
- 排碳權與環境服務市場
- 自主農業系統的發展
- 促進因素
- 成長潛力分析
- 監理框架
- 關鍵市場趨勢與顛覆性因素
- 技術與創新展望
- 當前趨勢
- 新進展
- 價格分析
- 對過去價格趨勢的分析
- 依球員類型分類的定價策略(高級球員、超值球員、成本加成球員)
- 未來市場趨勢
- 貿易數據分析
- 進出口量及進口額趨勢
- 主要貿易路線及關稅的影響
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 波特的分析
- PESTLE分析
- 基礎架構和部署狀態
- 按地區和購買者群體分類的採用率和滲透率
- 基礎設施投資的可擴展性限制和趨勢
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 企業矩陣分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃
第5章 市場估算與預測:依產品分類,2022-2035年
- 硬體和設備
- 無人機和無人駕駛飛行器(UAV)
- 精準灌溉系統
- GPS/GNSS 導航與自動駕駛系統
- 物聯網感測器和聯網現場設備
- 自動化和機器人農業機械
- 人工智慧整合智慧農業機械
- 軟體和農場管理平台
- 農場管理資訊系統(FMIS)
- 精密農業分析平台
- 人工智慧驅動的作物諮詢和決策支援軟體
- 連線和服務
- 遠端監控和遠端資訊處理服務
- 維護和售後服務平台
- 資料即服務 (DaaS) 與訂閱模式
第6章 市場估計與預測:依技術分類,2022-2035年
- 精密農業技術
- 可變費率應用技術(VRT)
- 基於GPS/GNSS的精密導引系統
- 用於實地分析的遙感探測和衛星影像
- 人工智慧(AI)和機器學習
- 人工智慧驅動的作物產量預測模型
- 電腦視覺在作物病蟲害檢測的應用
- 機器學習在自主農業機械導航的應用
- 農業諮詢平台中的生成式人工智慧
- 物聯網 (IoT) 和連接
- 農業物聯網感測器網路
- 5G 和 LPWAN 連結輔助智慧農業設備
- 邊緣運算在農場物聯網資料處理的應用
- 機器人與自動化
- 野外機器人
- 溫室自動化系統
- 群體機器人技術在大規模作物生產的應用
- 遙感探測和航空航太技術
- 利用無人機進行遙感探測—多波長和熱成像
- 基於衛星的作物監測平台
- LiDAR在農業地形測繪的應用
- 區塊鏈和數據管理技術
- 區塊鏈技術可提高農業供應鏈的透明度
- 農業數據所有權和互通性標準
第7章 市場估計與預測:依農場規模分類,2022-2035年
- 大型農場(超過50公頃)
- 中型農場(5-50公頃)
- 小規模農場(小於5公頃)
第8章 市場估計與預測:依應用領域分類,2022-2035年
- 農作物生產
- 穀物和穀類作物
- 水果和蔬菜
- 油籽和豆類
- 特色作物和高價值作物
- 牲畜監測
- 精準畜牧業
- 酪農自動化
- 水產養殖
- 林業和土地管理
第9章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 荷蘭
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 印尼
- 菲律賓
- 其他亞太國家
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 其他拉丁美洲國家
- 中東和非洲
- 南非
- 土耳其
- 以色列
- 其他中東和非洲國家
第10章:公司簡介
- 世界公司
- AGCO Corporation
- CLAAS KGaA mbH
- CNH Industrial
- DeLaval
- GEA Group
- John Deere
- Kubota Corporation
- Lely Industries
- Lindsay Corporation
- METER Group
- Netafim
- Topcon Agriculture
- Trimble Agriculture
- Valmont Industries
- Yanmar Holdings
- 當地公司
- Ag Leader Technology
- Hemisphere GNSS
- Pessl Instruments
- Sentek Technologies
- 新興企業
- AgEagle Aerial Systems
- Carbon Robotics
- Delair
- FarmDroid
- Saga Robotics
The Global Smart Agriculture Market was valued at USD 23.2 billion in 2025 and is estimated to grow at a CAGR of 9.7% to reach USD 59.6 billion by 2035.
Market growth is supported by favorable regulatory policies that continue to encourage the adoption of advanced farming technologies across major agricultural economies. Public-sector initiatives promoting precision farming and digital agriculture are making technology investments more accessible, enabling a greater number of agricultural operations to modernize production practices. Rising concerns regarding global food security, population growth, and declining arable land availability are also strengthening demand for smart farming solutions that improve productivity while optimizing the use of agricultural resources. Farmers are increasingly adopting precision technologies that enable more efficient application of fertilizers, crop protection products, and irrigation, helping maximize yields while reducing unnecessary resource consumption. At the same time, rapid advancements in connected devices, automation, data analytics, and digital farm management platforms are transforming agricultural operations and improving decision-making. These trends continue to reinforce the long-term outlook for the smart farming market, positioning advanced agricultural technologies as essential tools for improving operational efficiency, sustainability, and productivity across the global agricultural sector.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $23.2 Billion |
| Forecast Value | $59.6 Billion |
| CAGR | 9.7% |
The smart agriculture industry continues to expand as producers increasingly invest in digital technologies that improve farm management, operational efficiency, and long-term productivity. The adoption of connected equipment, precision monitoring systems, automation, and advanced analytics is helping agricultural businesses optimize resource utilization while supporting more informed operational decisions. Growing investment in digital infrastructure and connected farming technologies is enabling wider adoption of smart agriculture solutions across commercial farming operations. Continued advancements in precision farming technologies are expected to further strengthen market growth by improving productivity, reducing operational costs, and enhancing sustainable agricultural practices.
The hardware & equipment segment generated USD 13.5 billion in 2025 and is expected to reach USD 30.6 billion by 2035, as physical technologies are essential for supporting digital farming operations. Equipment used for precision agriculture enables the collection of field data, automation of farming activities, and implementation of intelligent management systems that improve overall farm performance. Since hardware infrastructure is typically installed before software platforms and digital services can be fully utilized, demand for advanced agricultural equipment continues to lead market expansion. Increasing investments in modern farming technologies are expected to further strengthen the segment throughout the forecast period.
The large farm (>50 Ha) segment accounted for a 53.3% share in 2025, making it the largest farm-size category. Large-scale agricultural operations continue to lead technology adoption because they have greater financial capacity to invest in advanced equipment and digital farming solutions. The economic benefits of precision agriculture technologies become more significant as operational scale increases, allowing larger farms to achieve stronger returns on technology investments through improved efficiency and productivity. Growing emphasis on maximizing output while reducing resource consumption is expected to sustain demand for smart agriculture technologies across large commercial farming operations.
United States Smart Agriculture Market held a 73.8% share in 2025. Market growth is supported by a highly developed agricultural sector, widespread adoption of precision farming technologies, and strong investment in advanced digital agriculture solutions. Continued public and private investment in connected farming infrastructure, digital farm management systems, and precision agriculture technologies is accelerating technology adoption across commercial farming operations. The country also benefits from a well-established ecosystem of agricultural equipment manufacturers, technology developers, and innovative agritech companies, reinforcing its leadership position within the regional market.
Major companies operating in the global smart agriculture market include Ag Leader Technology, AGCO Corporation, AgEagle Aerial Systems, Carbon Robotics, CLAAS KGaA mbH, CNH Industrial, Delair, DeLaval, FarmDroid, GEA Group, Hemisphere GNSS, John Deere, Kubota Corporation, Lely Industries, Lindsay Corporation, METER Group, Netafim, Pessl Instruments, Saga Robotics, Sentek Technologies, Topcon Agriculture, Trimble Agriculture, Valmont Industries, and Yanmar Holdings. Companies participating in the smart agriculture market are strengthening their competitive position by expanding precision farming technologies, developing connected equipment, and investing in advanced automation solutions. Manufacturers are increasing research and development efforts to improve data analytics, artificial intelligence, remote monitoring, and autonomous farming capabilities that enhance productivity and resource efficiency. Strategic collaborations with technology providers, agricultural organizations, and distribution partners are helping companies broaden their market presence and accelerate product adoption. Many businesses are also expanding their digital platforms by integrating farm management software, sensor technologies, connectivity solutions, and cloud-based analytics into comprehensive agricultural ecosystems.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Product
- 2.2.3 Technology
- 2.2.4 Farm Size
- 2.2.5 Application
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 AI/ML & precision agriculture technology proliferation
- 3.2.1.2 Rising agricultural labor costs & structural workforce shortages
- 3.2.1.3 Government subsidies & digital agriculture policy programs
- 3.2.2 Industry pitfalls & challenges
- 3.2.2.1 High upfront capital expenditure & extended ROI horizon
- 3.2.2.2 Digital literacy gap & skilled workforce deficit in agriculture
- 3.2.3 Opportunities
- 3.2.3.1 Carbon credit & environmental service markets
- 3.2.3.2 Autonomous farming systems development
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory framework
- 3.5 Major market trends and disruptions
- 3.6 Technology/innovation landscape
- 3.6.1 Current trends
- 3.6.2 Emerging trends
- 3.7 Pricing Analysis (driven by primary research)
- 3.7.1 Historical price trend analysis (driven by primary research)
- 3.7.2 Pricing strategy by player type (premium / value / cost-plus) (driven by primary research)
- 3.8 Future market trends
- 3.9 Trade data analysis (driven by paid database) (HS Code- 8806, 8701, 8432, 8433, 9015, 8424, 8517)
- 3.9.1 Import/export volume & value trends (driven by primary research)
- 3.9.2 Key trade corridors & tariff impact (driven by primary research)
- 3.10 Impact of AI & Generative AI on the Market
- 3.10.1 AI-driven disruption of existing business models
- 3.10.2 Gen-AI use cases & adoption roadmap by segment
- 3.10.3 Risks, limitations & regulatory considerations
- 3.11 Porter’s analysis
- 3.12 PESTEL analysis
- 3.13 Infrastructure & deployment landscape(driven by primary research)
- 3.13.1 Deployment penetration by region & buyer segment (driven by primary research)
- 3.13.2 Scalability constraints & infrastructure investment trends (driven by primary research)
Chapter 4 Competitive landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East and Africa
- 4.2.1 By region
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates and Forecast, By Product, 2022 - 2035 (USD Billion)
- 5.1 Key trends
- 5.2 Hardware & Equipment
- 5.2.1 Drones & Unmanned Aerial Vehicles (UAVs)
- 5.2.2 Precision Irrigation Systems
- 5.2.3 GPS/GNSS Guidance & Auto-Steering Systems
- 5.2.4 IoT Sensors & Connected Field Devices
- 5.2.5 Automated & Robotic Farm Machinery
- 5.2.6 AI-Integrated Intelligent Farm Equipment
- 5.3 Software & Farm Management Platforms
- 5.3.1 Farm Management Information Systems (FMIS)
- 5.3.2 Precision Agriculture Analytics Platforms
- 5.3.3 AI-Driven Crop Advisory & Decision Support Software
- 5.4 Connectivity & Services
- 5.4.1 Remote Monitoring & Telematics Services
- 5.4.2 Maintenance & After-Sales Service Platforms
- 5.4.3 Data-as-a-Service (DaaS) & Subscription Models
Chapter 6 Market Estimates and Forecast, By Technology, 2022 - 2035 (USD Billion)
- 6.1 Key trends
- 6.2 Precision Farming Technology
- 6.2.1 Variable Rate Technology (VRT)
- 6.2.2 GPS/GNSS-Based Precision Guidance Systems
- 6.2.3 Remote Sensing & Satellite Imagery for Field Analytics
- 6.3 Artificial Intelligence & Machine Learning
- 6.3.1 AI-Powered Crop Yield Prediction Models
- 6.3.2 Computer Vision for Crop Disease & Pest Detection
- 6.3.3 Machine Learning in Autonomous Farm Equipment Navigation
- 6.3.4 Generative AI in Agricultural Advisory Platforms
- 6.4 Internet of Things (IoT) & Connectivity
- 6.4.1 Agricultural IoT Sensor Networks
- 6.4.2 5G & LPWAN Connectivity for Smart Farm Devices
- 6.4.3 Edge Computing in On-Farm IoT Data Processing
- 6.5 Robotics & Automation
- 6.5.1 Field Robotics
- 6.5.2 Greenhouse Automation Systems
- 6.5.3 Swarm Robotics in Large-Scale Crop Production
- 6.6 Remote Sensing & Aerial Technology
- 6.6.1 UAV/Drone-Based Remote Sensing- Multispectral & Thermal Imaging
- 6.6.2 Satellite-Based Crop Monitoring Platforms
- 6.6.3 LiDAR Applications in Agricultural Terrain Mapping
- 6.7 Blockchain & Data Management Technology
- 6.7.1 Blockchain for Agricultural Supply Chain Transparency
- 6.7.2 Farm Data Ownership & Interoperability Standards
Chapter 7 Market Estimates and Forecast, By Farm Size, 2022 - 2035 (USD Billion)
- 7.1 Key trends
- 7.2 Large Farms (>50 Hectares)
- 7.3 Medium Farms (5-50 Hectares)
- 7.4 Small Farms (<5 Hectares)
Chapter 8 Market Estimates and Forecast, By Application, 2022 - 2035 (USD Billion)
- 8.1 Key trends
- 8.2 Crop Production
- 8.2.1 Cereal & Grain Crops
- 8.2.2 Fruits & Vegetables
- 8.2.3 Oilseeds & Pulses
- 8.2.4 Specialty & High-Value Crops
- 8.3 Livestock Monitoring
- 8.3.1 Precision Livestock Farming
- 8.3.2 Dairy Farm Automation
- 8.4 Aquaculture
- 8.5 Forestry & Land Management
Chapter 9 Market Estimates and Forecast, By Region, 2022 - 2035 (USD Billion)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 US
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Italy
- 9.3.5 Spain
- 9.3.6 Netherlands
- 9.3.7 Rest of Europe
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.4.6 Indonesia
- 9.4.7 Philippines
- 9.4.8 Rest of Asia Pacific
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.5.4 Rest of Latin America
- 9.6 Middle East and Africa
- 9.6.1 South Africa
- 9.6.2 Turkey
- 9.6.3 Israel
- 9.6.4 Rest of MEA
Chapter 10 Company Profiles
- 10.1 Global Companies
- 10.1.1 AGCO Corporation
- 10.1.2 CLAAS KGaA mbH
- 10.1.3 CNH Industrial
- 10.1.4 DeLaval
- 10.1.5 GEA Group
- 10.1.6 John Deere
- 10.1.7 Kubota Corporation
- 10.1.8 Lely Industries
- 10.1.9 Lindsay Corporation
- 10.1.10 METER Group
- 10.1.11 Netafim
- 10.1.12 Topcon Agriculture
- 10.1.13 Trimble Agriculture
- 10.1.14 Valmont Industries
- 10.1.15 Yanmar Holdings
- 10.2 Regional Companies
- 10.2.1 Ag Leader Technology
- 10.2.2 Hemisphere GNSS
- 10.2.3 Pessl Instruments
- 10.2.4 Sentek Technologies
- 10.3 Emerging Companies
- 10.3.1 AgEagle Aerial Systems
- 10.3.2 Carbon Robotics
- 10.3.3 Delair
- 10.3.4 FarmDroid
- 10.3.5 Saga Robotics

 2026年全球智慧農業解決方案市場報告
 2034年農業物聯網感測器市場預測-按感測器類型、連接技術、應用、最終用戶和地區分類的全球分析智慧農業設備監控市場預測至2034年—全球連接方式、設備類型、農場類型、應用、最終用戶和區域分析
 精準養豬市場:全球市場預測,2026-2032年2034年氣候變遷適應種子市場預測:按作物類型、性狀、育種技術、分銷管道、最終用戶和地區分類的全球分析氣候智慧型農業材料市場預測至 2034 年—按材料類型、作物類型、分銷管道、應用方法、最終用戶和地區進行全球分析。全球智慧農業市場:機會與策略展望(至2035年)物聯網在智慧農業市場的應用:2026-2032年全球市場預測(以交付方式、連結方式、農場類型、整合程度、應用和部署架構分類)智慧農業市場:2026-2032年全球市場預測(依產品、連接方式、技術、部署模式、農場規模、使用者類型和應用分類)智慧農業市場:2026-2032年全球市場預測(按組件、作物類型、連接技術、自動化程度、農場規模、部署類型和應用分類)