


 |
市場調查報告書
商品編碼
2109201
高純度特種氣體市場機會、成長促進因素、產業趨勢分析及2026-2035年預測High-Purity Specialty Gases Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球超高純度特種氣體市場預計到 2025 年將達到 121 億美元,年複合成長率為 7%,到 2035 年將達到 238 億美元。
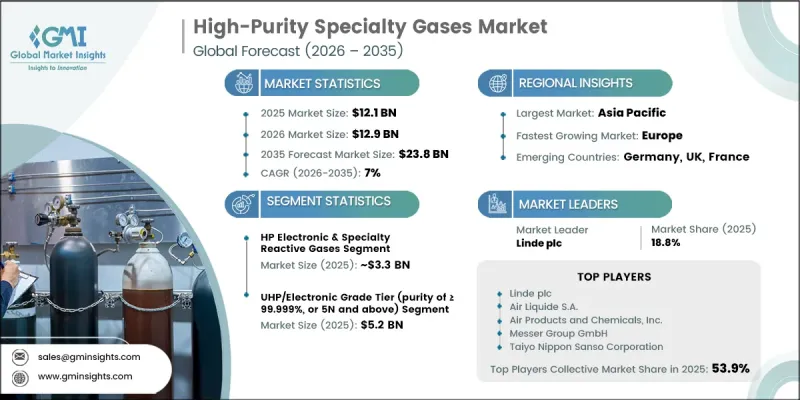
由於先進工業流程對高性能氣體的需求日益成長,且這些流程對氣體的純度、均勻性和可靠性要求極高,因此該市場正經歷持續成長。半導體製造領域的投資增加、醫療基礎設施的擴張以及清潔能源技術的快速發展,持續推動對超高純度氣體的強勁需求。此外,精密製造流程的日益複雜以及受監管行業品質標準的日益嚴格,正促使製造商從傳統工業氣體轉向高度精煉的特種氣體解決方案。電子製造、製藥生產、實驗室研究和分析測試領域的不斷進步,進一步強化了市場需求。為了滿足客戶日益嚴格的規格要求,各公司也正在投資先進的精煉技術、品質保證系統和特殊氣體加工基礎設施。先進製造設施的擴張,以及對製程效率、產品品質和運作可靠性的日益重視,預計將為行業相關人員創造長期的商業機會。隨著各行業持續將精度、安全性和合規性放在首位,預計高純度特種氣體市場將在整個預測期內保持強勁的成長勢頭。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 初始市場規模 | 121億美元 |
| 預計金額 | 238億美元 |
| 複合年成長率 | 7% |
惠普電子及特殊反應氣體業務部門預計到2025年銷售額將達到33億美元,並在2035年之前以27.5%的複合年成長率成長。該業務部門持續受益於對高度專業化氣體的需求不斷成長,這些氣體能夠支持對極高一致性和製程控制要求極高的精密製造製程。對先進電子產品生產、微加工技術和下一代工業製造的投資增加也推動了該業務部門的成長。製造商正致力於提供具有更高純度和穩定化學性能的氣體,以提高生產效率、降低污染風險並提高產品良率。
預計到2025年,超高純度/電子級氣體市佔率將達到43.8%。此細分市場保持主導地位的原因在於,在對製程精度要求極高的產業中,性能穩定、污染極低的高品質氣體產品始終是首選。高純度氣體產品具有更高的市場價值,這得益於先進的精煉技術、嚴格的品管程序、先進的分析測試以及為達到和維持這些規格而配備的專用生產基礎設施。對品質保證、法規遵循和高精度製造的投入不斷增加,正在推動對超高純氣體解決方案的需求持續成長。隨著各行業擴大採用先進的生產技術,預計在整個預測期內,對符合最高純度標準的氣體的需求將保持強勁。
預計到2025年,北美高純度特種氣體市佔率將達到29.2%。該地區憑藉其強大的工業基礎、對先進製造業的持續投資以及技術密集型產業的持續擴張,將繼續保持主導地位。先進電子元件產量的增加、製藥產能的擴張以及高性能工業流程的日益普及,將繼續推動該地區市場的成長。積極的研發活動、完善的生產基礎設施以及對產品品質和法規遵從性的日益重視,進一步提升了北美對高純度特種氣體的需求。預計在整個預測期內,對創新和先進工業能力的持續投資將進一步鞏固該地區的市場主導地位。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 產業潛在風險與挑戰
- 市場機遇
- 成長潛力分析
- 監理情勢
- 波特的分析
- PESTLE分析
- 價格趨勢
- 按地區
- 按類型
- 未來市場趨勢
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 專利趨勢
- 貿易統計
- 主要進口國
- 主要出口國
- 永續性和環境方面
- 永續計劃
- 減少廢棄物策略
- 生產中的能源效率
- 具有環保意識的舉措
- 考慮碳足跡
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 北美洲
- 歐洲
- 亞太地區
- LATAM
- 中東和非洲
- 按地區
- 企業矩陣分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃
第5章 市場估算與預測:依天然氣類型分類,2022-2035年
- 高純度氣氛
- 氮氣(N2)
- 氧氣(O2)
- 氬氣(Ar)
- 高純度稀有氣體和稀有氣體
- 氦(He)
- 氖(Ne)
- 氪(Kr)
- 氙(Xe)
- 高純度碳氣
- 二氧化碳(CO2)
- 一氧化碳(CO)
- 甲烷(CH4)
- 高純度氫氣(H2)
- 高純度電子級氣體及特殊反應氣體
- 含氟氣體
- 矽氫化物和鍺氫化物
- 鹵素氣體和酸性氣體
- 氮和磷化合物
- 其他
第6章 市場估計與預測:依純度分類,2022-2035年
- 超高純度(UHP)/電子級 99.999% 或更高(5N+)
- 高純度 (HP) 99.99% 至 99.999% (4N)
- 標準/研究級 99.9% 至 99.99% (3N)
第7章 市場估計與預測:依最終用戶產業分類,2022-2035年
- 電子和半導體
- 醫療和藥品
- 化工/石油化工
- 食品/飲料/農業
- 能源與電力
- 汽車和航太
- 學術和研究機構
- 其他
第8章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 其他亞太國家
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 其他拉丁美洲國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- UAE
- 其他中東和非洲國家
第9章:公司簡介
- Linde plc
- Air Liquide SA
- Air Products and Chemicals, Inc.
- Messer Group GmbH
- Taiyo Nippon Sanso Corporation
- Iwatani Corporation
- Resonac Holdings Corporation(formerly Showa Denko)
- Yingde Gases Group Company
- SOL SpA
- Gulf Cryo
- Ellenbarrie Industrial Gases Ltd.
- Huate Gas Co., Ltd.(Guangdong Huate)
- Chengdu Taiyu Industrial Gases Co., Ltd.
- MESA Specialty Gases & Equipment
- Samator Gas
- Stella Chemifa Corporation
The Global High-Purity Specialty Gases Market was valued at USD 12.1 billion in 2025 and is estimated to grow at a CAGR of 7% to reach USD 23.8 billion by 2035.
The market is witnessing sustained expansion due to the increasing adoption of high-performance gases across advanced industrial processes that require exceptional purity, consistency, and reliability. Growing investments in semiconductor manufacturing, expanding healthcare infrastructure, and the rapid development of clean energy technologies continue to create strong demand for gases with ultra-high purity levels. In addition, the rising complexity of precision manufacturing processes and stricter quality standards across regulated industries are encouraging manufacturers to transition from conventional industrial gases to highly refined specialty gas solutions. Continuous advancements in electronics manufacturing, pharmaceutical production, laboratory research, and analytical testing are further strengthening market demand. Companies are also investing in advanced purification technologies, quality assurance systems, and specialized gas handling infrastructure to meet increasingly demanding customer specifications. The expansion of advanced manufacturing facilities, coupled with growing emphasis on process efficiency, product quality, and operational reliability, is expected to create long-term opportunities for industry participants. As industries continue to prioritize precision, safety, and regulatory compliance, the high-purity specialty gases market is expected to maintain a strong growth trajectory throughout the forecast period.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $12.1 Billion |
| Forecast Value | $23.8 Billion |
| CAGR | 7% |
The HP electronic & specialty reactive gases segment generated a USD 3.3 billion in 2025 and is forecast to grow at a 27.5% CAGR through 2035. The segment continues to benefit from increasing demand for highly specialized gases that support precision manufacturing processes requiring exceptional consistency and process control. Rising investments in advanced electronics production, microfabrication technologies, and next-generation industrial manufacturing are contributing to the segment's expansion. Manufacturers are focusing on delivering gases with superior purity and stable chemical performance to improve production efficiency, reduce contamination risks, and enhance manufacturing yields.
The UHP/Electronic Grade segment held 43.8% share in 2025. The segment maintains its leading position because industries requiring the highest levels of process accuracy continue to prioritize premium-quality gas products that deliver consistent performance and minimal contamination. Higher purity grades command greater market value due to the sophisticated purification technologies, stringent quality control procedures, advanced analytical testing, and specialized production infrastructure required to achieve and maintain these specifications. Growing investments in quality assurance, regulatory compliance, and high-precision manufacturing continue to accelerate demand for ultra-high-purity gas solutions. As industries increasingly adopt advanced production technologies, demand for gases meeting the highest purity standards is expected to remain strong throughout the forecast period.
North America High-Purity Specialty Gases Market held a 29.2% share in 2025. The region continues to maintain a leading position due to its strong industrial base, ongoing investments in advanced manufacturing, and continuous expansion of technology-intensive industries. Increasing production of sophisticated electronic components, growing pharmaceutical manufacturing capacity, and rising adoption of high-performance industrial processes continue to support regional market growth. Strong research and development activities, well-established production infrastructure, and increasing emphasis on product quality and regulatory compliance are further enhancing demand for high-purity specialty gases across North America. Continued investment in innovation and advanced industrial capabilities is expected to reinforce the region's dominant position over the forecast period.
Major companies operating in the Global High-Purity Specialty Gases Market include Air Products and Chemicals, Inc., Messer Group GmbH, Air Liquide S.A., Taiyo Nippon Sanso Corporation, and Linde plc. Companies operating in the global high-purity specialty gases market are strengthening their market position through continuous investment in advanced purification technologies, production capacity expansion, and product innovation. Manufacturers are prioritizing research and development to enhance gas purity, improve production efficiency, and meet increasingly stringent quality standards across high-value industries. Strategic partnerships, long-term supply agreements, and expansion of global distribution networks are helping companies improve customer reach and secure recurring business. Market participants are also investing in specialized packaging, storage, and delivery systems to maintain product integrity throughout the supply chain. In addition, businesses are expanding regional manufacturing facilities, improving technical support services, and developing customized gas solutions tailored to specific industrial applications.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Gas type
- 2.2.2 Purity level
- 2.2.3 End-user industry
- 2.2.4 Regional
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
- 2.4.1 Executive decision points
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.1.5 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.2 Industry pitfalls and challenges
- 3.2.3 Market opportunities
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter’s analysis
- 3.6 PESTEL analysis
- 3.7 Price trends
- 3.7.1 By region
- 3.7.2 By type
- 3.8 Future market trends
- 3.9 Technology and Innovation landscape
- 3.9.1 Current technological trends
- 3.9.2 Emerging technologies
- 3.10 Patent Landscape
- 3.11 Trade statistics (HS code)
- 3.11.1 Major importing countries
- 3.11.2 Major exporting countries
- 3.12 Sustainability and environmental aspects
- 3.12.1 Sustainable practices
- 3.12.2 Waste reduction strategies
- 3.12.3 Energy efficiency in production
- 3.12.4 Eco-friendly initiatives
- 3.13 Carbon footprint consideration
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 LATAM
- 4.2.1.5 MEA
- 4.2.1 By region
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New Product Launches
- 4.6.4 Expansion Plans
Chapter 5 Market Estimates and Forecast, By Gas Type, 2022–2035 (USD Billion) (Kilo Tons)
- 5.1 Key trends
- 5.2 High-purity atmospheric gases
- 5.2.1 Nitrogen (N₂)
- 5.2.2 Oxygen (O₂)
- 5.2.3 Argon (Ar)
- 5.3 High-purity rare & noble gases
- 5.3.1 Helium (He)
- 5.3.2 Neon (Ne)
- 5.3.3 Krypton (Kr)
- 5.3.4 Xenon (Xe)
- 5.4 High-purity carbon gases
- 5.4.1 Carbon Dioxide (CO₂)
- 5.4.2 Carbon Monoxide (CO)
- 5.4.3 Methane (CH₄)
- 5.5 High-purity hydrogen (H₂)
- 5.6 High-purity electronic & specialty reactive gases
- 5.6.1 Fluorine-based Gases
- 5.6.2 Silicon & Germanium Hydrides
- 5.6.3 Halogen & Acid Gases
- 5.6.4 Nitrogen & Phosphorus Compounds
- 5.7 Others
Chapter 6 Market Estimates and Forecast, By Purity Level, 2022–2035 (USD Billion) (Kilo Tons)
- 6.1 Key trends
- 6.2 Ultra High Purity (UHP) / electronic grade ≥99.999% (5N+)
- 6.3 High Purity (HP) 99.99% to <99.999% (4N)
- 6.4 Standard / research grade 99.9% to <99.99% (3N)
Chapter 7 Market Estimates and Forecast, By End-User Industry, 2022–2035 (USD Billion) (Kilo Tons)
- 7.1 Key trends
- 7.2 Electronics & semiconductor
- 7.3 Healthcare & pharmaceutical
- 7.4 Chemical & petrochemical
- 7.5 Food, beverage & agriculture
- 7.6 Energy & power
- 7.7 Automotive & aerospace
- 7.8 Academic & research institutions
- 7.9 Others
Chapter 8 Market Estimates and Forecast, By Region, 2022–2035 (USD Billion) (Kilo Tons)
- 8.1 Key trends
- 8.2 North America
- 8.2.1 U.S.
- 8.2.2 Canada
- 8.3 Europe
- 8.3.1 Germany
- 8.3.2 UK
- 8.3.3 France
- 8.3.4 Spain
- 8.3.5 Italy
- 8.3.6 Rest of Europe
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 India
- 8.4.3 Japan
- 8.4.4 Australia
- 8.4.5 South Korea
- 8.4.6 Rest of Asia Pacific
- 8.5 Latin America
- 8.5.1 Brazil
- 8.5.2 Mexico
- 8.5.3 Argentina
- 8.5.4 Rest of Latin America
- 8.6 Middle East and Africa
- 8.6.1 Saudi Arabia
- 8.6.2 South Africa
- 8.6.3 UAE
- 8.6.4 Rest of Middle East and Africa
Chapter 9 Company Profiles
- 9.1 Linde plc
- 9.2 Air Liquide S.A.
- 9.3 Air Products and Chemicals, Inc.
- 9.4 Messer Group GmbH
- 9.5 Taiyo Nippon Sanso Corporation
- 9.6 Iwatani Corporation
- 9.7 Resonac Holdings Corporation (formerly Showa Denko)
- 9.8 Yingde Gases Group Company
- 9.9 SOL S.p.A.
- 9.10 Gulf Cryo
- 9.11 Ellenbarrie Industrial Gases Ltd.
- 9.12 Huate Gas Co., Ltd. (Guangdong Huate)
- 9.13 Chengdu Taiyu Industrial Gases Co., Ltd.
- 9.14 MESA Specialty Gases & Equipment
- 9.15 Samator Gas
- 9.16 Stella Chemifa Corporation

 特種氣體:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)
 電子特種氣體市場預測至2034年—按氣體類型、應用、最終用戶、銷售管道和地區分類的全球分析DRAM製造工廠專用氣體:市佔率分析、產業趨勢與統計及成長預測(2026-2031年)
 特種氣體市場:2026-2032年全球市場預測(依氣體類型、純度等級、供應形式、包裝形式、應用及最終用戶產業分類)
 特種電子氣體市場-全球產業規模、佔有率、趨勢、機會、預測:按類型、應用、最終用途、分銷方式、地區和競爭格局分類,2021-2031年
 特種氣體市場規模、佔有率、趨勢和預測:按類型、元素、應用、包裝類型、銷售形式和地區分類,2026-2034年
 散裝特殊氣體系統 (BSGS) 市場規模、佔有率和成長分析:按系統組件、氣體類型、產業、企業規模和地區分類-2026 年至 2033 年產業預測
 特種氣體市場規模、佔有率、成長及全球產業分析:按類型、應用和地區分類,並預測至2026-2034年全球半導體製造特種氣體市場預測至2034年:依氣體類型、純度等級、形態、應用、最終用戶及地區分類
 2026年全球特種氣體市場報告