


 |
市場調查報告書
商品編碼
2109189
遠端監控市場機會、成長要素、產業趨勢分析及2026-2035年預測。Remote Monitoring and Control Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

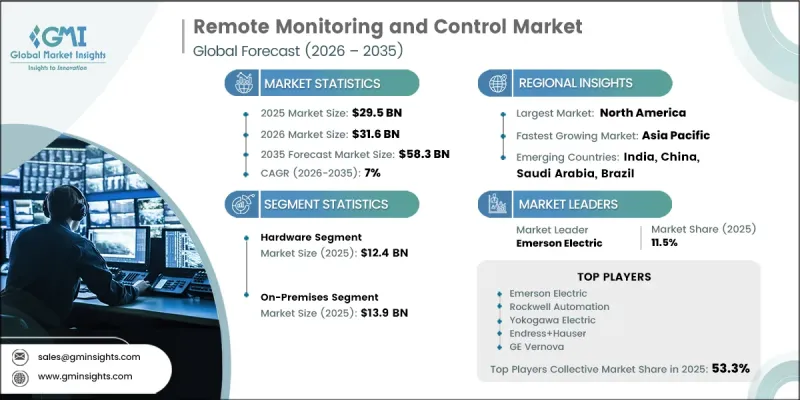
全球遠端監控市場預計到 2025 年將價值 295 億美元,預計到 2035 年將以 7% 的複合年成長率成長至 583 億美元。
隨著企業不斷採用先進的數位平台來提升營運視覺、實現流程自動化並最佳化資產效能,遠端監控產業正經歷持續成長。從傳統監控架構轉向整合式雲端平台的轉變,推高了部署成本,不僅包括硬體投資,還包括軟體平台、網路安全解決方案、分析功能和託管服務。對智慧基礎設施、互聯工業環境和數位轉型 (DX) 的投資不斷增加,正在各個行業創造強勁的長期需求。以互聯設備、自動化流程管理和數據驅動決策為特徵的智慧製造系統的持續應用,進一步加速了市場擴張。企業擴大採用遠端監控技術來提高生產力、提升營運效率、增強系統可靠性並支援預測性維護策略。對工業數位化、基礎設施現代化和先進自動化技術的長期投資,進一步鞏固了全球遠端監控市場的積極前景,並在整個預測期內創造了持續成長的機會。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 初始市場規模 | 295億美元 |
| 預測金額 | 583億美元 |
| 複合年成長率 | 7% |
預計到2025年,硬體領域市場規模將達到124億美元,市佔率將維持在42%。硬體類別包括直接連接監控系統和工業運營的關鍵組件,可實現即時數據採集、設備間通訊和製程控制。對自動化技術和互聯工業基礎設施的持續投資,正在推動各應用領域對先進硬體解決方案的強勁需求。
預計2025年,本地部署市場規模將達到139億美元。由於傳統工業控制系統在現有生產設施中的廣泛應用,該市場將繼續保持強勁的市場地位。許多企業仍然傾向於本地部署,因為這種方式能夠更好地管理營運數據,支援符合監管和網路安全要求,即使在網路連接受限、無法進行雲端操作的環境下,也能確保可靠的效能。
預計到2035年,北美遠端監控市場規模將達到194億美元。這一區域成長主要得益於工業自動化應用的日益普及、基礎設施現代化建設的持續推進以及對先進數位技術的持續投資。智慧監控系統和流程自動化解決方案在各工業領域的廣泛應用將進一步增強區域需求,並持續推動市場長期擴張。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 成本結構
- 利潤率
- 每個階段增加的價值
- 垂直整合趨勢
- 顛覆者
- 影響產業的因素
- 促進因素
- 工業自動化和工業4.0計劃正變得越來越普及。
- 關鍵基礎設施擴建和公共產業現代化
- 人們對預測性維護和資產可靠性越來越感興趣。
- 對遠距辦公和勞動力最佳化的需求日益成長
- 產業潛在風險與挑戰
- 與互聯工業系統相關的網路安全風險
- 實施和整合相關的成本相對較高。
- 與舊有系統的互通性和相容性
- 市場機遇
- 工業IoT(IIoT) 和邊緣運算的日益普及
- 擴展基於雲端的遠端監控平台
- 增加對智慧基礎設施和數位公用事業的投資
- 人工智慧驅動的預測分析與自主運營
- 促進因素
- 成長潛力分析
- 技術與創新展望
- 最新技術
- 利用工業IoT(IIoT)的遠端監控平台
- 基於雲端的監控功能和整合式SCADA系統
- 用於即時監控的邊緣運算
- 新興技術
- 人工智慧驅動的預測性維護與自主運作
- 用於遠端資產監控的數位孿生整合
- 面向關鍵工業連接的專用 5G 網路
- 最新技術
- 價格分析
- 對過去價格趨勢的分析
- 依球員類型分類的定價策略(高級球員、超值球員、成本加成球員)
- 監理情勢
- 北美洲
- 美國國家標準與技術研究院網路安全框架
- NERC關鍵基礎設施保護(CIP)標準(美國)
- ISA/IEC 62443 工業網路安全標準(美國)
- 美國聯邦通訊委員會(FCC)設備認證與射頻法規
- 歐洲
- NIS2 指令
- 一般資料保護規則(GDPR)
- 網路彈性法案 (CRA)
- IEC 62443 工業通訊網路 -IT安全
- 亞太地區
- 網路安全法(中國)
- 中國資料安全法
- 工業標準化法(日本)
- 《數位個人資料保護法》(DPDP)(印度)
- 關鍵基礎設施安全法(SOCI 法案)(澳洲)
- 拉丁美洲
- Lei Geral de Protecao de Dados (LGPD)(巴西)
- 墨西哥關於保護私人企業所持有個人資料的聯邦法律
- 中東和非洲
- 阿拉伯聯合大公國資訊安全標準
- 沙烏地阿拉伯基本網路安全措施 (ECC)
- 南非個人資料保護法 (POPIA)
- 北美洲
- 波特的分析
- PESTLE分析
- 專利分析
- 成本細分分析
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 永續性和環境方面
- 透過遠端監控和最佳化提高能源效率
- 延長資產使用壽命和預測性維護
- 遠端操作和減少二氧化碳排放
- 智慧資源管理
- ESG 與永續發展合規性
- 預測假設和情境分析
- 基本案例下推動複合年成長率的關鍵宏觀經濟和產業變量
- 樂觀情境:宏觀經濟與產業的順風
- 悲觀情景:宏觀經濟放緩或產業逆風
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 排名分類標準與遴選標準
- 按銷售額、地區和創新能力分類的層級定位矩陣。
第5章 市場估計與預測:依組件分類,2022-2035年
- 硬體
- 感應器
- 執行器
- 可程式邏輯控制器(PLC)
- 遠端終端單元(RTU)
- 其他
- 軟體
- SCADA軟體
- 資產績效管理 (APM) 軟體
- 遠端資產監控軟體
- 其他
- 服務
- 諮詢服務
- 系統整合與部署
- 維護和支援服務
- 託管服務
第6章 市場估算與預測:依通訊技術分類,2022-2035年
- 有線
- 無線的
第7章 市場估算與預測:依部署模式分類,2022-2035年
- 現場
- 基於雲端的
- 混合
第8章 市場估算與預測:依最終用途分類,2022-2035年
- 工業自動化
- 公用事業
- 石油和天然氣
- 智慧基礎設施
- 衛生保健
- 農業
- 運輸/物流
- 其他
第9章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 比利時
- 荷蘭
- 瑞典
- 俄羅斯
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 新加坡
- 韓國
- 越南
- 印尼
- 泰國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
- 土耳其
第10章:公司簡介
- 世界公司
- ABB
- Cisco
- Emerson
- GE Vernova
- Honeywell
- Rockwell Automation
- Schneider Electric
- Siemens
- 該地區的領先企業
- Advantech
- Endress+Hauser
- Fuji Electric
- Hitachi
- Mitsubishi Electric
- Yokogawa Electric
- 新興企業
- KROHNE
- Atlas Copco
- AVEVA
- Huawei
- John Wood
- PTC
The Global Remote Monitoring and Control Market was estimated at USD 29.5 billion in 2025 and is estimated to grow at a CAGR of 7% to reach USD 58.3 billion by 2035.
The remote monitoring and control industry is experiencing sustained expansion as organizations increasingly adopt advanced digital platforms to improve operational visibility, automate processes, and optimize asset performance. The shift from conventional monitoring architectures toward integrated and cloud-enabled platforms is increasing deployment spending by combining hardware investments with software platforms, cybersecurity solutions, analytics capabilities, and managed services. Growing investments in smart infrastructure, connected industrial environments, and digital transformation initiatives are creating strong long-term demand across multiple industries. The continued adoption of intelligent manufacturing systems featuring connected equipment, automated process management, and data-driven decision-making is further accelerating market expansion. Organizations are increasingly implementing remote monitoring and control technologies to improve productivity, strengthen operational efficiency, enhance system reliability, and support predictive maintenance strategies. Long-term investments in industrial digitalization, infrastructure modernization, and advanced automation technologies continue to reinforce the favorable outlook for the global remote monitoring and control market, creating sustained growth opportunities throughout the forecast period.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $29.5 Billion |
| Forecast Value | $58.3 Billion |
| CAGR | 7% |
The hardware segment accounted for USD 12.4 billion in 2025, holding 42% share. The hardware category includes essential components that directly connect monitoring systems with industrial operations, enabling real-time data collection, equipment communication, and process control. Continued investments in automation technologies and connected industrial infrastructure are supporting strong demand for advanced hardware solutions across a wide range of applications.
The on-premises deployment segment reached USD 13.9 billion in 2025. The segment continues to maintain a strong market position due to the extensive installed base of traditional industrial control systems across established production facilities. Many organizations continue to prefer on-premises deployments because they provide greater control over operational data, support compliance with regulatory and cybersecurity requirements, and ensure reliable performance in environments where network connectivity limitations may restrict cloud-based operations.
North America Remote Monitoring and Control Market is expected to reach USD 19.4 billion by 2035. Regional growth is supported by widespread industrial automation, ongoing infrastructure modernization initiatives, and continued investments in advanced digital technologies. Increasing adoption of intelligent monitoring systems and process automation solutions across industrial sectors continues to strengthen regional demand while supporting long-term market expansion.
Leading companies operating in the global remote monitoring and control market include Emerson Electric Co., Rockwell Automation, Yokogawa Electric Corporation, Endress+Hauser, GE Vernova, Siemens AG, and Schneider Electric. Companies participating in the remote monitoring and control market are strengthening their market position by investing in advanced automation technologies, cloud-enabled monitoring platforms, and intelligent analytics solutions that improve operational efficiency and asset performance. Manufacturers are expanding their software capabilities by integrating artificial intelligence, predictive analytics, and enhanced cybersecurity features into their product portfolios. Strategic partnerships, acquisitions, and collaborations with industrial customers and technology providers are helping companies broaden their market reach and accelerate digital transformation initiatives.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Component
- 2.2.2 Communication Technology
- 2.2.3 Deployment Mode
- 2.2.4 End Use
- 2.2.5 Regional
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Cost structure
- 3.1.3 Profit margin
- 3.1.4 Value addition at each stage
- 3.1.5 Vertical integration trends
- 3.1.6 Disruptors
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising adoption of industrial automation and Industry 4.0 initiatives
- 3.2.1.2 Expansion of critical infrastructure and utility modernization
- 3.2.1.3 Increasing focus on predictive maintenance and asset reliability
- 3.2.1.4 Growing demand for remote operations and workforce optimization
- 3.2.2 Industry pitfalls & challenges
- 3.2.2.1 Cybersecurity risks associated with connected industrial systems
- 3.2.2.2 High implementation and integration costs
- 3.2.2.3 Interoperability and legacy system compatibility
- 3.2.3 Market opportunities
- 3.2.3.1 Increasing adoption of Industrial IoT (IIoT) and edge computing
- 3.2.3.2 Expansion of cloud-based remote monitoring platforms
- 3.2.3.3 Growing investments in smart infrastructure and digital utilities
- 3.2.3.4 AI-powered predictive analytics and autonomous operations
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Technology and Innovation landscape
- 3.4.1 Current technologies
- 3.4.1.1 Industrial IoT (IIoT)-Enabled Remote Monitoring Platforms
- 3.4.1.2 SCADA Systems Integrated with Cloud-Based Monitoring
- 3.4.1.3 Edge Computing for Real-Time Monitoring and Control
- 3.4.2 Emerging technologies
- 3.4.2.1 AI-Driven Predictive Maintenance and Autonomous Operations
- 3.4.2.2 Digital Twin Integration for Remote Asset Monitoring
- 3.4.2.3 Private 5G Networks for Mission-Critical Industrial Connectivity
- 3.4.1 Current technologies
- 3.5 Pricing Analysis (Driven by Primary Research)
- 3.5.1 Historical Price Trend Analysis
- 3.5.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
- 3.6 Regulatory landscape
- 3.6.1 North America
- 3.6.1.1 NIST Cybersecurity Framework (US)
- 3.6.1.2 NERC Critical Infrastructure Protection (CIP) Standards (US)
- 3.6.1.3 ISA/IEC 62443 Industrial Cybersecurity Standards (US)
- 3.6.1.4 FCC Equipment Authorization & Radio Frequency Regulations (US)
- 3.6.2 Europe
- 3.6.2.1 NIS2 Directive
- 3.6.2.2 General Data Protection Regulation (GDPR)
- 3.6.2.3 Cyber Resilience Act (CRA)
- 3.6.2.4 IEC 62443 Industrial Communication Networks - IT Security
- 3.6.3 Asia-Pacific
- 3.6.3.1 Cybersecurity Law (China)
- 3.6.3.2 Data Security Law (China)
- 3.6.3.3 Industrial Standardization Act (Japan)
- 3.6.3.4 Digital Personal Data Protection (DPDP) Act (India)
- 3.6.3.5 Security of Critical Infrastructure (SOCI) Act (Australia)
- 3.6.4 Latin America
- 3.6.4.1 Lei Geral de Protecao de Dados (LGPD) (Brazil)
- 3.6.4.2 Federal Law on Protection of Personal Data Held by Private Parties (Mexico)
- 3.6.5 Middle East & Africa
- 3.6.5.1 UAE Information Assurance Standards
- 3.6.5.2 Essential Cybersecurity Controls (ECC) (Saudi Arabia)
- 3.6.5.3 Protection of Personal Information Act (POPIA) (South Africa)
- 3.6.1 North America
- 3.7 Porter's analysis
- 3.8 PESTEL analysis
- 3.9 Patent analysis (Driven by Primary Research)
- 3.10 Cost breakdown analysis
- 3.11 Impact of AI & generative AI on the market
- 3.11.1 AI Driven Disruption of Existing Business Models
- 3.11.2 GenAI Use Cases and Adoption Roadmap by Segment
- 3.11.3 Risks Limitations and Regulatory Considerations
- 3.12 Sustainability and environmental aspects
- 3.12.1 Energy Efficiency through Remote Monitoring & Optimization
- 3.12.2 Asset Life Extension & Predictive Maintenance
- 3.12.3 Remote Operations & Reduced Carbon Emissions
- 3.12.4 Smart Resource Management
- 3.12.5 ESG & Sustainability Compliance
- 3.13 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.13.1 Base Case key macro & industry variables driving CAGR
- 3.13.2 Optimistic Scenarios Favorable Macro and Industry Tailwinds
- 3.13.3 Pessimistic Scenario Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia-Pacific
- 4.2.4 Latin America
- 4.2.5 Middle East & Africa
- 4.3 Competitive positioning matrix
- 4.4 Key developments
- 4.4.1 Mergers & acquisitions
- 4.4.2 Partnerships & collaborations
- 4.4.3 New product launches
- 4.4.4 Expansion plans and funding
- 4.5 Company tier benchmarking
- 4.5.1 Tier classification criteria & qualifying thresholds
- 4.5.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates & Forecast, By Component, 2022 - 2035 ($Mn)
- 5.1 Key trends
- 5.2 Hardware
- 5.2.1 Sensors
- 5.2.2 Actuators
- 5.2.3 Programmable Logic Controllers (PLCs)
- 5.2.4 Remote Terminal Units (RTUs)
- 5.2.5 Others
- 5.3 Software
- 5.3.1 SCADA Software
- 5.3.2 Asset Performance Management (APM) Software
- 5.3.3 Remote Asset Monitoring Software
- 5.3.4 Others
- 5.4 Services
- 5.4.1 Consulting Services
- 5.4.2 System Integration & Deployment
- 5.4.3 Maintenance & Support Services
- 5.4.4 Managed Services
Chapter 6 Market Estimates & Forecast, By Communication Technology, 2022 - 2035 ($Mn)
- 6.1 Key trends
- 6.2 Wired
- 6.3 Wireless
Chapter 7 Market Estimates & Forecast, By Deployment Mode, 2022 - 2035 ($Mn)
- 7.1 Key trends
- 7.2 On-Premises
- 7.3 Cloud-Based
- 7.4 Hybrid
Chapter 8 Market Estimates & Forecast, By End Use, 2022 - 2035 ($Mn)
- 8.1 Key trends
- 8.2 Industrial Automation
- 8.3 Utilities
- 8.4 Oil & Gas
- 8.5 Smart Infrastructure
- 8.6 Healthcare
- 8.7 Agriculture
- 8.8 Transportation & Logistics
- 8.9 Others
Chapter 9 Market Estimates & Forecast, By Region, 2022 - 2035 ($Mn)
- 9.1 North America
- 9.1.1 US
- 9.1.2 Canada
- 9.2 Europe
- 9.2.1 UK
- 9.2.2 Germany
- 9.2.3 France
- 9.2.4 Italy
- 9.2.5 Spain
- 9.2.6 Belgium
- 9.2.7 Netherlands
- 9.2.8 Sweden
- 9.2.9 Russia
- 9.3 Asia Pacific
- 9.3.1 China
- 9.3.2 India
- 9.3.3 Japan
- 9.3.4 Australia
- 9.3.5 Singapore
- 9.3.6 South Korea
- 9.3.7 Vietnam
- 9.3.8 Indonesia
- 9.3.9 Thailand
- 9.4 Latin America
- 9.4.1 Brazil
- 9.4.2 Mexico
- 9.4.3 Argentina
- 9.5 MEA
- 9.5.1 South Africa
- 9.5.2 Saudi Arabia
- 9.5.3 UAE
- 9.5.4 Turkey
Chapter 10 Company Profiles
- 10.1 Global Players
- 10.1.1 ABB
- 10.1.2 Cisco
- 10.1.3 Emerson
- 10.1.4 GE Vernova
- 10.1.5 Honeywell
- 10.1.6 Rockwell Automation
- 10.1.7 Schneider Electric
- 10.1.8 Siemens
- 10.2 Regional Champions
- 10.2.1 Advantech
- 10.2.2 Endress+Hauser
- 10.2.3 Fuji Electric
- 10.2.4 Hitachi
- 10.2.5 Mitsubishi Electric
- 10.2.6 Yokogawa Electric
- 10.3 Emerging Players
- 10.3.1 KROHNE
- 10.3.2 Atlas Copco
- 10.3.3 AVEVA
- 10.3.4 Huawei
- 10.3.5 John Wood
- 10.3.6 PTC

 全球遠端監控市場規模、佔有率、趨勢及成長分析報告(2026-2034)
 遠端監控與控制:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 遠端監控市場:全球市場預測,2026-2032年遠端儲罐液位監測市場:按組件、技術、通訊方式、部署模式、儲槽類型、應用、產業分類,全球預測(2026-2032年)遠端儲罐監控市場按產品類型、儲罐類型、監控類型、部署方式和最終用戶分類,全球預測(2026-2032年)
 2026年全球遠端監控市場報告
 遠端監控市場-全球產業規模、佔有率、趨勢、機會和預測:按行為、類型、最終用戶、地區和競爭格局分類,2021-2031年油氣遠端監控市場-全球產業規模、佔有率、趨勢、機會和預測,按類型、產業、地區和競爭格局分類,2021-2031年預測
 遠端監控市場規模、佔有率及成長分析(按組件、最終用戶產業及地區分類)-2026-2033年產業預測
 全球遠端儲罐監控市場報告 - 第八版