


 |
市場調查報告書
商品編碼
2109167
防霧膜及片材市場商機、成長要素、產業趨勢分析及2026-2035年預測。Antifog Films and Sheets Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

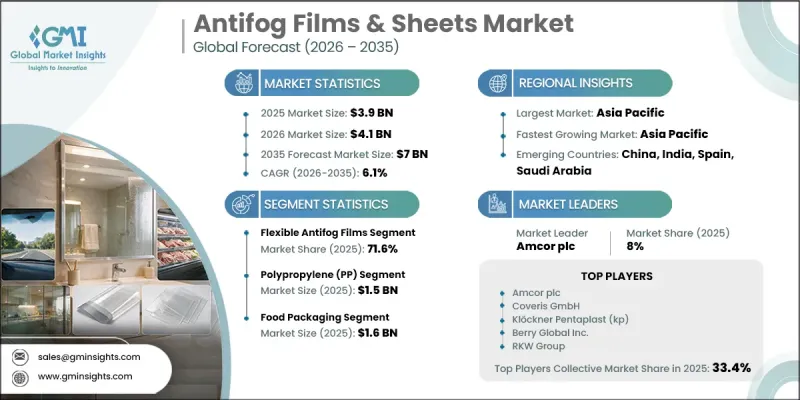
全球防霧薄膜和片材市場預計到 2025 年將達到 39 億美元,年複合成長率為 6.1%,到 2035 年將達到 70 億美元。
由於各行業對既能防止冷凝又能保持產品可見性的包裝材料的需求不斷成長,市場持續擴張。對透明包裝解決方案的需求日益成長、對食品品質和安全的日益重視、低溫運輸基礎設施的擴展以及永續包裝材料的日益普及,都支撐著市場的長期成長。防霧塗層配方技術的不斷進步,進一步提升了產品在包括食品包裝、醫療、農業和工業應用在內的多個終端應用領域的性能。為了維持產品新鮮度、提升展示效果並最大限度地減少冷凝造成的品質問題,製造商正積極採用先進的防霧薄膜和片材。同時,對保護性栽培和現代農業實踐的日益重視,也增強了對專用溫室薄膜的需求。這些因素共同提升了防霧片材和薄膜市場的商業性重要性,隨著製造商持續投資於能夠提高耐用性、透明度和運行效率的高性能材料,該市場正處於永續成長的軌道上。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 初始市場規模 | 39億美元 |
| 預測金額 | 70億美元 |
| 複合年成長率 | 6.1% |
隨著透明包裝在保持生鮮食品品質和外觀方面越來越受歡迎,對防霧薄膜和片材的需求也日益成長。這些材料能有效抑製冷凝,使包裝產品清晰可見,同時有助於在儲存和運輸過程中保持新鮮。對保護性農業投資的增加也推動了對溫室薄膜的需求,這些薄膜能夠提高透光性、抑制內部水分積聚,並有助於提高作物產量。此外,對永續農業實踐和資源高效生產方式的持續重視,也促使先進的防霧技術在溫室應用中整體應用。隨著各行業不斷優先考慮產品保護、營運效率和包裝性能,預計食品包裝和農業領域對防霧薄膜和片材的需求將進一步成長。
預計到2025年,軟性防霧膜將成為領先產品類型,佔71.6%的市佔率。食品包裝、農業應用、醫療包裝和消費品彈性包裝領域的強勁需求持續支撐著該細分市場的主導地位。軟性防霧膜具有優異的光學透明度、有效的防冷凝性能、輕巧的結構以及與可回收包裝形式的兼容性,使其適用於廣泛的商業應用。其提升產品外觀並延長保存期限的能力,促使產品品質和包裝性能至關重要的各行業對其應用顯著成長。
預計2025年,聚丙烯(PP)市場規模將達15億美元。聚丙烯憑藉其卓越的透明度、防潮性、熱封性、成本效益以及與高性能防霧塗層的兼容性,仍然是應用最廣泛的材料之一。這些特性使其成為包裝應用的理想材料,既能確保可靠的可見度和濕度控制,又能保持加工效率。隨著製造商越來越重視永續包裝解決方案,聚丙烯與可回收材料系統的兼容性進一步鞏固了其市場地位。預計在預測期內,食品、飲料、醫療保健、醫藥和消費品包裝應用領域不斷成長的需求將繼續推動聚丙烯防霧薄膜的應用。
預計到2025年,北美防霧薄膜和片材市場將佔據22.2%的市場。該地區市場擴張的驅動力主要來自對永續食品包裝日益成長的需求以及醫療保健行業對先進包裝的廣泛應用。監管機構對食品接觸材料安全性和包裝性能的日益重視,促使製造商開發更高品質的防霧產品,以滿足不斷變化的行業需求。包裝食品消費量的成長、溫室種植的擴張以及醫療保健、醫藥和汽車製造業的持續創新,預計將推動該地區市場在2035年之前保持強勁成長,進一步鞏固北美作為先進防霧薄膜技術領先市場的地位。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 延長生鮮食品包裝和保存期限的需求日益成長
- 擴大保護性農業和溫室種植
- 汽車生產規模擴大及先進玻璃製品的應用
- 來自醫療保健和醫療包裝應用領域的需求不斷成長。
- 在光學、家用電子電器和顯示器保護應用領域中得到更廣泛的應用。
- 產業潛在風險與挑戰
- 由於採用了先進的防霧塗層和特殊聚合物,高成本。
- 惡劣條件下的性能耐久性和塗層劣化。
- 市場機遇
- 開發永續且可回收的防霧膜技術
- 在電動車、智慧顯示器和醫療保健領域不斷擴大應用。
- 促進因素
- 成長潛力分析
- 監理情勢
- 波特的分析
- PESTLE分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格趨勢
- 按地區
- 依產品
- 定價策略
- 新興經營模式
- 合規要求
- 專利和智慧財產權分析
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 市場集中度分析
- 主要公司的競爭標竿分析
- 財務績效比較
- 收入
- 利潤率
- R&D
- 產品系列比較
- 產品線寬度
- 科技
- 創新
- 區域擴張比較
- 全球擴張分析
- 服務網路覆蓋
- 按地區分類的市場滲透率
- 競爭定位矩陣
- 領導者
- 挑戰者
- 追蹤者
- 小眾玩家
- 戰略展望矩陣
- 財務績效比較
- 主要進展
- 併購
- 夥伴關係和聯盟
- 技術進步
- 擴張和投資策略
- 數位轉型計劃
- 新興企業和新創企業領域競爭公司的趨勢
第5章 市場估算與預測:依產品類型分類,2022-2035年
- 柔軟性防霧膜
- 硬質防霧片
第6章 市場估計與預測:依材料分類,2022-2035年
- 聚丙烯(PP)
- 聚乙烯(PE)
- 聚對苯二甲酸乙二醇酯(PET)
- 聚碳酸酯(PC)
- 其他
第7章 市場估計與預測:依應用領域分類,2022-2035年
- 食品包裝
- 農業和園藝
- 醫療保健
- 汽車和運輸業
- 建築/施工
- 消費品
- 其他
第8章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第9章:公司簡介
- 全球主要公司
- Amcor plc
- Coveris GmbH
- Klockner Pentaplast(kp)
- Berry Global Inc.
- RKW Group
- 該地區的主要公司
- 北美洲
- 3M Company
- FSI Coating Technologies, Inc.
- Sealed Air Corporation(Cryovac)
- 亞太地區
- Cosmo First Ltd.(Cosmo Films)
- Jindal Poly Films Ltd.
- Polyplex Corporation Ltd.
- Garware Hi-Tech Films Ltd.
- Toray Industries, Inc.
- Mitsubishi Chemical Group Corp.
- JPFL Films Pvt. Ltd.
- Chiripal Poly Films Ltd.
- Vacmet India Ltd.
- Ester Industries Ltd.
- SABIC
- Sumitomo Bakelite Co., Ltd.
- 歐洲
- Taghleef Industries
- SUDPACK Holding GmbH
- 北美洲
- 小眾玩家/顛覆者
- UFlex Limited
The Global Antifog Films & Sheets Market was valued at USD 3.9 billion in 2025 and is estimated to grow at a CAGR of 6.1% to reach USD 7 billion by 2035.
The market continues to expand as industries increasingly seek packaging materials that preserve product visibility while preventing moisture accumulation. Rising demand for transparent packaging solutions, greater emphasis on food quality and safety, expanding cold chain infrastructure, and the growing adoption of sustainable packaging materials are supporting long-term market growth. Continuous technological improvements in antifog coating formulations are further enhancing product performance across multiple end-use sectors, including food packaging, healthcare, agriculture, and industrial applications. The increasing need to maintain product freshness, improve shelf appeal, and minimize condensation-related quality issues is encouraging manufacturers to adopt advanced antifog films and sheets. At the same time, the growing focus on protected cultivation and modern agricultural practices is strengthening demand for specialized greenhouse films. These combined factors are reinforcing the commercial importance of the antifog sheets & films market, positioning it for sustained growth as manufacturers continue investing in high-performance materials that improve durability, transparency, and operational efficiency.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $3.9 Billion |
| Forecast Value | $7 Billion |
| CAGR | 6.1% |
The antifog films and sheets industry is experiencing increasing demand as transparent packaging becomes a preferred solution for preserving the quality and appearance of perishable products. These materials effectively reduce condensation, allowing packaged products to remain clearly visible while helping extend product freshness throughout storage and transportation. Growing investments in protected agriculture are also driving demand for greenhouse films that improve light transmission, reduce internal moisture buildup, and support better crop productivity. In addition, ongoing emphasis on sustainable agricultural practices and resource-efficient production methods is encouraging wider adoption of advanced antifog technologies across greenhouse applications. As industries continue to prioritize product protection, operational efficiency, and packaging performance, demand for antifog films and sheets is expected to strengthen across both food packaging and agricultural sectors.
The flexible antifog films segment accounted for 71.6% share in 2025, making it the leading product category. Strong demand across food packaging, agricultural applications, healthcare packaging, and flexible consumer packaging continues to support its market leadership. Flexible antifog films offer excellent optical clarity, effective condensation resistance, lightweight construction, and compatibility with recyclable packaging formats, making them suitable for a wide range of commercial applications. Their ability to improve product presentation while supporting longer shelf life has significantly increased adoption across industries where product quality and packaging performance remain essential.
The polypropylene (PP) segment reached USD 1.5 billion in 2025. Polypropylene remains one of the most widely used materials because of its excellent transparency, moisture resistance, heat-sealing capability, cost efficiency, and compatibility with high-performance antifog coatings. These characteristics make it an ideal material for packaging applications requiring reliable visibility and moisture control while maintaining processing efficiency. Its compatibility with recyclable material systems further strengthens its position as manufacturers increasingly prioritize sustainable packaging solutions. Growing demand across food, beverage, healthcare, medical, and consumer packaging applications is expected to continue supporting polypropylene-based antifog film adoption during the forecast period.
North America Antifog Films & Sheets Market held a 22.2% share in 2025. Market expansion across the region is being driven by increasing demand for sustainable food packaging and the growing use of advanced packaging materials within the healthcare sector. Strong regulatory emphasis on safe food-contact materials and improved packaging performance is encouraging manufacturers to develop higher-quality antifog products that meet evolving industry requirements. Rising consumption of packaged food, expanding greenhouse cultivation activities, and continued innovation across healthcare, medical, and automotive manufacturing are expected to support healthy regional growth through 2035, reinforcing North America's position as a key market for advanced antifog film technologies.
Prominent companies operating in the global antifog films & sheets market include 3M Company, Amcor plc, Berry Global Inc., Chiripal Poly Films Ltd., Cosmo First Ltd. (Cosmo Films), Coveris GmbH, Ester Industries Ltd., FSI Coating Technologies, Inc., Garware Hi-Tech Films Ltd., Jindal Poly Films Ltd., JPFL Films Pvt. Ltd., Klockner Pentaplast (kp), Mitsubishi Chemical Group Corp., Polyplex Corporation Ltd., RKW Group, SABIC, Sealed Air Corporation (Cryovac), Sumitomo Bakelite Co., Ltd., SUDPACK Holding GmbH, Taghleef Industries, Toray Industries, Inc., UFlex Limited, and Vacmet India Ltd. Companies participating in the antifog films & sheets market are strengthening their market position by investing in advanced coating technologies, expanding production capacity, and developing high-performance films with improved transparency and moisture-control capabilities. Manufacturers are focusing on sustainable product innovation by introducing recyclable and environmentally responsible packaging materials that align with evolving regulatory and customer requirements. Many companies are broadening their application portfolio to serve food packaging, healthcare, agriculture, industrial, and consumer packaging industries while increasing investments in research and development to enhance product functionality. Strategic partnerships, distribution network expansion, and long-term supply agreements are helping manufacturers strengthen customer relationships and improve market reach.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 – 2035
- 2.2 Key market trends
- 2.2.1 Product type trends
- 2.2.2 Material type trends
- 2.2.3 Application trends
- 2.2.4 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Increasing demand for fresh food packaging and shelf-life extension
- 3.2.1.2 Expansion of protected agriculture and greenhouse cultivation
- 3.2.1.3 Growing automotive production and advanced glazing applications
- 3.2.1.4 Increasing demand from healthcare and medical packaging applications
- 3.2.1.5 Rising adoption of optical, consumer electronics, and protective display applications
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High cost of advanced antifog coatings and specialty polymers
- 3.2.2.2 Performance durability and coating degradation under harsh conditions
- 3.2.3 Market opportunities
- 3.2.3.1 Development of sustainable and recyclable antifog film technologies
- 3.2.3.2 Growing adoption in electric vehicles, smart displays, and healthcare applications
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter’s analysis
- 3.6 PESTEL analysis
- 3.7 Technology and Innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By product
- 3.9 Pricing Strategies
- 3.10 Emerging Business Models
- 3.11 Compliance Requirements
- 3.12 Patent and IP analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.2 Market concentration analysis
- 4.2.1 By region
- 4.3 Competitive benchmarking of key players
- 4.3.1 Financial performance comparison
- 4.3.1.1 Revenue
- 4.3.1.2 Profit margin
- 4.3.1.3 R&D
- 4.3.2 Product portfolio comparison
- 4.3.2.1 Product range breadth
- 4.3.2.2 Technology
- 4.3.2.3 Innovation
- 4.3.3 Geographic presence comparison
- 4.3.3.1 Global footprint analysis
- 4.3.3.2 Service network coverage
- 4.3.3.3 Market penetration by region
- 4.3.4 Competitive positioning matrix
- 4.3.4.1 Leaders
- 4.3.4.2 Challengers
- 4.3.4.3 Followers
- 4.3.4.4 Niche players
- 4.3.5 Strategic outlook matrix
- 4.3.1 Financial performance comparison
- 4.4 Key developments
- 4.4.1 Mergers and acquisitions
- 4.4.2 Partnerships and collaborations
- 4.4.3 Technological advancements
- 4.4.4 Expansion and investment strategies
- 4.4.5 Digital transformation initiatives
- 4.5 Emerging/ startup competitors landscape
Chapter 5 Market Estimates and Forecast, By Product Type, 2022 – 2035 (USD Million)
- 5.1 Key trends
- 5.2 Flexible antifog films
- 5.3 Rigid antifog sheets
Chapter 6 Market Estimates and Forecast, By Material Type, 2022 – 2035 (USD Million)
- 6.1 Key trends
- 6.2 Polypropylene (PP)
- 6.3 Polyethylene (PE)
- 6.4 Polyethylene terephthalate (PET)
- 6.5 Polycarbonate (PC)
- 6.6 Others
Chapter 7 Market Estimates and Forecast, By Application, 2022 – 2035 (USD Million)
- 7.1 Key trends
- 7.2 Food packaging
- 7.3 Agriculture & horticulture
- 7.4 Medical & healthcare
- 7.5 Automotive & transportation
- 7.6 Building & construction
- 7.7 Consumer products
- 7.8 Others
Chapter 8 Market Estimates and Forecast, By Region, 2022 – 2035 (USD Million)
- 8.1 Key trends
- 8.2 North America
- 8.2.1 U.S.
- 8.2.2 Canada
- 8.3 Europe
- 8.3.1 Germany
- 8.3.2 UK
- 8.3.3 France
- 8.3.4 Spain
- 8.3.5 Italy
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 India
- 8.4.3 Japan
- 8.4.4 Australia
- 8.4.5 South Korea
- 8.5 Latin America
- 8.5.1 Brazil
- 8.5.2 Mexico
- 8.5.3 Argentina
- 8.6 Middle East and Africa
- 8.6.1 South Africa
- 8.6.2 Saudi Arabia
- 8.6.3 UAE
Chapter 9 Company Profiles
- 9.1 Global Key Players
- 9.1.1 Amcor plc
- 9.1.2 Coveris GmbH
- 9.1.3 Klockner Pentaplast (kp)
- 9.1.4 Berry Global Inc.
- 9.1.5 RKW Group
- 9.2 Regional key players
- 9.2.1 North America
- 9.2.1.1 3M Company
- 9.2.1.2 FSI Coating Technologies, Inc.
- 9.2.1.3 Sealed Air Corporation (Cryovac)
- 9.2.2 Asia Pacific
- 9.2.2.1 Cosmo First Ltd. (Cosmo Films)
- 9.2.2.2 Jindal Poly Films Ltd.
- 9.2.2.3 Polyplex Corporation Ltd.
- 9.2.2.4 Garware Hi-Tech Films Ltd.
- 9.2.2.5 Toray Industries, Inc.
- 9.2.2.6 Mitsubishi Chemical Group Corp.
- 9.2.2.7 JPFL Films Pvt. Ltd.
- 9.2.2.8 Chiripal Poly Films Ltd.
- 9.2.2.9 Vacmet India Ltd.
- 9.2.2.10 Ester Industries Ltd.
- 9.2.2.11 SABIC
- 9.2.2.12 Sumitomo Bakelite Co., Ltd.
- 9.2.3 Europe
- 9.2.3.1 Taghleef Industries
- 9.2.3.2 SUDPACK Holding GmbH
- 9.2.1 North America
- 9.3 Niche Players/Disruptors
- 9.3.1 UFlex Limited

 全球溫室防霧膜市場報告:2021-2032年歷史表現及預測
 全球防霧添加劑市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 防霧膜和片材市場規模、佔有率和成長分析:按產品類型、材料、應用、最終用戶和地區分類-2026-2033年產業預測
 汽車除霧系統市場-2026-2032年全球市場預測
 農業噴霧及霧化系統市場:商業機會、成長要素、產業趨勢分析及2026-2035年預測防霧添加劑市場:按類型、形態、應用流程、應用領域、最終用戶和銷售管道分類-2026-2032年全球市場預測
 防霧添加劑:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)防霧添加劑市場規模、佔有率、成長和全球產業分析:按類型和應用、區域的洞察,2026-2034年的預測防霧膜及片材市場:依材料、塗層技術、厚度、終端用戶及通路分類-2026-2032年全球市場預測
 汽車除霧系統市場:依類型、組件、銷售管道、技術、應用、國家及地區分類-全球產業分析、市場規模、市場佔有率及2026年至2033年預測