


 |
市場調查報告書
商品編碼
2109159
魚油濃縮及精煉市場機會、成長要素、產業趨勢分析及 2026-2035 年預測。Fish Oil Concentration and Refinement Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球魚油濃縮物和精煉市場預計到 2025 年將價值 26 億美元,並將以 6.8% 的複合年成長率成長,到 2035 年將達到 50 億美元。
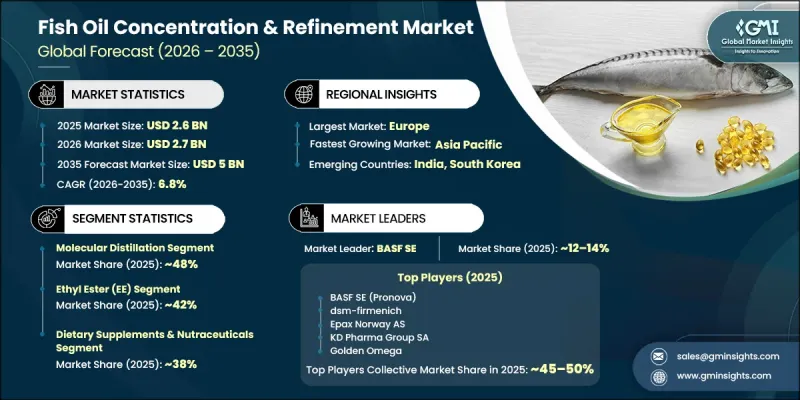
全球對預防醫學日益成長的關注、消費者對有益於心血管和認知健康的產品的偏好不斷增強,以及對用於藥品和嬰幼兒營養品的ω-3原料品質要求日益嚴格,共同推動了市場擴張。此外,該產業正經歷從傳統通用乙酯(EE)濃縮物向優質再酯化三酸甘油酯(rTG)和藥用級活性成分(API)的逐步轉型,為生產商創造了高價值的商機。精煉技術的不斷進步、對高品質ω-3製劑需求的成長、精煉產能投資的增加以及對監管合規性的日益重視,都進一步支撐了該行業的長期成長。隨著生產商持續優先考慮高純度生產和高價值製劑,預計魚油濃縮物和精煉市場將在整個預測期內保持穩定成長。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 初始市場規模 | 26億美元 |
| 預測金額 | 50億美元 |
| 複合年成長率 | 6.8% |
預計到2025年,分子蒸餾技術將佔據48%的市場佔有率,複合年成長率(CAGR)為6.2%。此製程持續引領市場,因為它能夠以商業化規模穩定供應超高純度的ω-3濃縮物,同時滿足製藥和特種營養品應用領域嚴格的品質要求。憑藉其可靠的純化效率和產品均一性,分子蒸餾已成為高階產品生產流程中首選的純化技術。
預計到2025年,營養補充品和營養保健品產業將佔據38%的市場佔有率,並在2035年之前以6.5%的複合年成長率成長,這主要得益於消費者對心血管健康、預防保健、免疫支持和整體健康管理應用的強勁需求。消費者對預防保健意識的提高以及對營養解決方案的偏好,正在推動含有功能性成分的補充劑的普及。此外,消費者對維護心臟健康、改善文明病以及解決營養缺乏問題的日益關注,也進一步推動了產品需求。同時,個人化營養產品、潔淨標示配方和創新補充劑形式的日益普及,預計將在預測期內促進該細分市場的成長。
預計到2025年,北美魚油濃縮物和精煉產品的市場佔有率將達到22%,這得益於成熟的膳食補充劑行業(包括零售)以及完善的omega-3藥品和優質營養成分監管法規環境。消費者對魚油產品的高度關注、先進的生產能力以及對高品質精煉魚油產品的持續需求,將繼續鞏固該地區的市場地位。
全球魚油濃縮物及精煉市場的競爭格局包括巴斯夫公司(BASF SE)、帝斯曼-芬美意公司 (dsm-firmenich)、挪威Epax公司、KD製藥集團公司 (KD Pharma Group SA)、金歐米茄公司 (Golden Omega)、GC RieberoMega公司、VW Vivk、OL International)、金歐米茄生物製藥公司 (KinOmega Biopharm)、中美生物技術工程有限公司 (Sinomega Biotech Engineering Co., Ltd.)、Wiley Companies/AlaskOmega公司、Aker BioMarine Antarctic公司和日水製藥株式會社 (Nissui Pharmaceutical Co., Ltd.)。這些公司業務涵蓋醫藥級、高階膳食補充劑和通用級魚油濃縮物等多個細分市場,滿足全球價值鏈中不同客戶的多元化需求。全球魚油濃縮物及精煉市場的企業正透過擴大產能、改進精煉技術以及投資於能夠提供更高品質ω-3原料的先進濃縮製程來鞏固其市場地位。製造商正專注於醫藥級和高階膳食補充劑產品系列,以滿足市場對高純度配方日益成長的需求。此外,許多公司正在加強合規體系建設,並獲得國際認可的品質認證,以增強客戶信心並擴大其在受監管市場的佔有率。與原物料供應商建立策略夥伴關係、簽訂長期採購合約以及投資建設可靠的原物料採購基礎設施,都有助於提高供應鏈的穩定性。同時,各公司正透過專注於研發、製程最佳化、專有純化技術和產品創新,實現產品差異化,增強競爭力,提高營運效率,並在全球醫藥和營養品市場創造永續的長期成長機會。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 產業潛在風險與挑戰
- 市場機遇
- 成長潛力分析
- 監理情勢
- 波特的分析
- PESTLE分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格趨勢
- 按地區
- 透過濃縮/提純技術
- 未來市場趨勢
- 專利趨勢
- 貿易統計
- 主要進口國
- 主要出口國
- 永續性和環境方面
- 永續計劃
- 減少廢棄物策略
- 生產中的能源效率
- 具有環保意識的舉措
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 北美洲
- 歐洲
- 亞太地區
- LATAM
- 中東和非洲
- 按地區
- 企業矩陣分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃
第5章 市場估算與預測:依集中度與精煉技術分類,2022-2035年
- 分子蒸餾
- 短程分子蒸餾
- 擦拭巾膜分子蒸餾
- 酵素處理
- 酶促酯交換反應(EE)
- 酵素再酯化 (rTG)
- 酶水解(FFA)
- 尿素錯合的形成
- 超臨界流體萃取(SFE)
- 薄膜過濾
- 越冬和分步結晶
- 其他方法(層析法、混合方法)
第6章 市場估算與預測:依生產類型分類,2022-2035年
- 乙酯(EE)
- 標準濃縮液(30-50%)
- 高濃度(50-70%)
- 超高純度/醫藥級(>70%)
- 再酯化三酸甘油酯(rTG)
- 標準rTG
- 優質rTG(TG含量90%或以上)
- 天然三酸甘油酯(TG)
- 磷脂
- 其他
第7章 市場估計與預測:依應用領域分類,2022-2035年
- 膳食補充品和營養保健品
- 心血管健康
- 認知功能與大腦健康
- 關節和發炎支持
- 整體健康狀況
- 藥物與臨床營養
- 處方原料藥Omega-3
- 臨床、腸內及腸外給藥。
- 食品和飲料的營養強化
- 機能性食品
- 營養強化飲料
- 烘焙食品和乳製品的營養強化
- 嬰兒、幼兒及孕婦/哺乳婦女的營養食品
- 嬰兒配方奶粉
- 懷孕和產後補充劑
- 飼料和水產養殖
- 水產飼料
- 牲畜和家禽飼料
- 寵物食品和獸用營養補充品
- 其他
第8章 市場估算與預測:依原料分類,2022-2035年
- 鳳尾魚/鳳尾魚
- 沙丁魚/鯡魚
- 鯖魚
- 鮭魚和鮭科魚類
- 鯡魚
- 鮪魚
- 其他(鱈魚、美洲黑鱈、阿拉斯加鱈魚)
第9章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 其他亞太國家
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 其他拉丁美洲國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- UAE
- 其他中東和非洲國家
第10章:公司簡介
- BASF SE
- dsm-firmenich
- Epax Norway AS
- KD Pharma Group SA
- Golden Omega
- GC Rieber VivoMega AS
- Polaris
- OLVEA Fish Oils
- Lysi hf
- Croda International
- KinOmega Biopharm
- Sinomega Biotech Engineering Co., Ltd.
- Wiley Companies/AlaskOmega
- Aker BioMarine Antarctic AS
- Nissui Pharmaceutical Co., Ltd.
The Global Fish Oil Concentration & Refinement Market was valued at USD 2.6 billion in 2025 and is estimated to grow at a CAGR of 6.8% to reach USD 5 billion by 2035.
Market expansion is driven by the growing global focus on preventive healthcare, increasing consumer preference for products that support cardiovascular and cognitive wellness, and stricter quality requirements governing omega-3 ingredients used across pharmaceutical and infant nutrition applications. The industry is also witnessing a gradual shift from conventional commodity-grade ethyl ester (EE) concentrates toward premium re-esterified triglyceride (rTG) and pharmaceutical-grade active pharmaceutical ingredient (API) formats, creating higher-value opportunities for manufacturers. Continuous improvements in purification technologies, expanding demand for premium-quality omega-3 formulations, rising investments in refining capabilities, and increasing emphasis on regulatory compliance are further supporting long-term industry growth. As manufacturers continue to prioritize higher-purity production and value-added formulations, the fish oil concentration & refinement market is expected to maintain steady momentum throughout the forecast period.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $2.6 Billion |
| Forecast Value | $5 Billion |
| CAGR | 6.8% |
The molecular distillation segment captured a 48% share in 2025 and is forecast to grow at a 6.2% CAGR. The process continues to lead the market because it consistently delivers ultra-high-purity omega-3 concentrates at commercial production scale while meeting stringent quality requirements established for pharmaceutical and specialized nutrition applications. Its proven ability to achieve reliable purification efficiency and product consistency makes molecular distillation the preferred refining technology across premium manufacturing operations.
The dietary supplements & nutraceuticals segment accounted for a 38% share in 2025 and is projected to grow at a CAGR of 6.5% through 2035, supported by strong demand across cardiovascular health, preventive wellness, immune support, and overall health management applications. Increasing consumer awareness regarding proactive healthcare and the growing preference for nutrition-based solutions are encouraging the adoption of supplements containing functional ingredients. Rising interest in maintaining heart health, improving lifestyle-related health outcomes, and addressing nutritional deficiencies is further driving product demand. In addition, expanding availability of personalized nutrition products, clean-label formulations, and innovative supplement formats is expected to strengthen segment growth over the forecast period.
North America Fish Oil Concentration & Refinement market held a 22% share in 2025, supported by a well-established dietary supplement industry with retail sales, along with a mature regulatory environment governing omega-3 pharmaceutical products and premium nutritional ingredients. Strong consumer awareness, advanced manufacturing capabilities, and sustained demand for high-quality refined fish oil products continue to reinforce the region's market position.
The competitive landscape of the Global Fish Oil Concentration & Refinement Market includes BASF SE, dsm-firmenich, Epax Norway AS, KD Pharma Group SA, Golden Omega, GC Rieber VivoMega AS, Polaris, OLVEA Fish Oils, Lysi hf, Croda International, KinOmega Biopharm, Sinomega Biotech Engineering Co., Ltd., Wiley Companies / AlaskOmega, Aker BioMarine Antarctic AS, and Nissui Pharmaceutical Co., Ltd. These companies operate across pharmaceutical-grade, premium nutraceutical, and commodity-grade fish oil concentration segments, serving diverse customer requirements throughout the global value chain. Companies participating in the Global Fish Oil Concentration & Refinement Market are strengthening their market position by expanding production capacity, improving purification technologies, and investing in advanced concentration processes that deliver higher-quality omega-3 ingredients. Manufacturers are increasing their focus on pharmaceutical-grade and premium nutraceutical product portfolios to address growing demand for high-purity formulations. Many companies are also enhancing regulatory compliance capabilities and obtaining internationally recognized quality certifications to improve customer confidence and expand access to regulated markets. Strategic partnerships with raw material suppliers, long-term sourcing agreements, and investments in reliable feedstock procurement infrastructure are helping improve supply chain stability. In addition, businesses are emphasizing research and development, process optimization, proprietary refining technologies, and product innovation to differentiate their offerings, strengthen competitive positioning, increase operational efficiency, and create sustainable long-term growth opportunities across global pharmaceutical and nutrition markets.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Concentration & Refinement Technology
- 2.2.2 Output Product Form
- 2.2.3 Application
- 2.2.4 Source Species
- 2.2.5 Regional
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
- 2.5 Future outlook and strategic recommendations
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.1.5 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.2 Industry pitfalls and challenges
- 3.2.3 Market opportunities
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter’s analysis
- 3.6 PESTEL analysis
- 3.7 Technology and innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By Concentration & Refinement Technology
- 3.9 Future market trends
- 3.10 Patent landscape
- 3.11 Trade statistics (HS code)
- 3.11.1 Major importing countries
- 3.11.2 Major exporting countries
- 3.12 Sustainability and environmental aspects
- 3.12.1 Sustainable practices
- 3.12.2 Waste reduction strategies
- 3.12.3 Energy efficiency in production
- 3.12.4 Eco-friendly initiatives
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 LATAM
- 4.2.1.5 MEA
- 4.2.1 By region
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates and Forecast, By Concentration & Refinement Technology, 2022–2035 (USD Million) (Kilo Tons)
- 5.1 Key trends
- 5.2 Molecular Distillation
- 5.2.1 Short-Path Molecular Distillation
- 5.2.2 Wiped-Film Molecular Distillation
- 5.3 Enzymatic Processing
- 5.3.1 Enzymatic Transesterification (EE)
- 5.3.2 Enzymatic Re-esterification (rTG)
- 5.3.3 Enzymatic Hydrolysis (FFA)
- 5.4 Urea Complexation
- 5.5 Supercritical Fluid Extraction (SFE)
- 5.6 Membrane-Based Filtration
- 5.7 Winterization & Fractional Crystallization
- 5.8 Others (Chromatographic, Hybrid)
Chapter 6 Market Estimates and Forecast, By Output Product Form, 2022–2035 (USD Million) (Kilo Tons)
- 6.1 Key trends
- 6.2 Ethyl Ester (EE)
- 6.2.1 Standard Concentrate (30–50%)
- 6.2.2 High Concentrate (50–70%)
- 6.2.3 Ultra-High/Pharma Grade (>70%)
- 6.3 Re-esterified Triglyceride (rTG)
- 6.3.1 Standard rTG
- 6.3.2 Premium rTG (>90% TG)
- 6.4 Natural Triglyceride (TG)
- 6.5 Phospholipid
- 6.6 Others
Chapter 7 Market Estimates and Forecast, By Application, 2022–2035 (USD Million) (Kilo Tons)
- 7.1 Key trends
- 7.2 Dietary Supplements & Nutraceuticals
- 7.2.1 Cardiovascular Health
- 7.2.2 Cognitive & Brain Health
- 7.2.3 Joint & Inflammation Support
- 7.2.4 General Wellness
- 7.3 Pharmaceuticals & Clinical Nutrition
- 7.3.1 Prescription Omega-3 APIs
- 7.3.2 Clinical/Enteral/Parenteral
- 7.4 Food & Beverage Fortification
- 7.4.1 Functional Foods
- 7.4.2 Fortified Beverages
- 7.4.3 Bakery & Dairy Fortification
- 7.5 Infant & Maternal Nutrition
- 7.5.1 Infant Formula
- 7.5.2 Prenatal & Maternal Supplements
- 7.6 Animal Feed & Aquaculture
- 7.6.1 Aquaculture Feed
- 7.6.2 Livestock & Poultry Feed
- 7.7 Pet Food & Veterinary Nutrition
- 7.8 Others
Chapter 8 Market Estimates and Forecast, By Source Species, 2022–2035 (USD Million) (Kilo Tons)
- 8.1 Key trends
- 8.2 Anchovy/Anchoveta
- 8.3 Sardine/Pilchard
- 8.4 Mackerel
- 8.5 Salmon & Salmonids
- 8.6 Herring
- 8.7 Tuna
- 8.8 Others (Cod, Menhaden, Pollock)
Chapter 9 Market Estimates and Forecast, By Region, 2022–2035 (USD Million) (Kilo Tons)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Spain
- 9.3.5 Italy
- 9.3.6 Rest of Europe
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.4.6 Rest of Asia Pacific
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.5.4 Rest of Latin America
- 9.6 Middle East and Africa
- 9.6.1 Saudi Arabia
- 9.6.2 South Africa
- 9.6.3 UAE
- 9.6.4 Rest of Middle East and Africa
Chapter 10 Company Profiles
- 10.1 BASF SE
- 10.2 dsm-firmenich
- 10.3 Epax Norway AS
- 10.4 KD Pharma Group SA
- 10.5 Golden Omega
- 10.6 GC Rieber VivoMega AS
- 10.7 Polaris
- 10.8 OLVEA Fish Oils
- 10.9 Lysi hf
- 10.10 Croda International
- 10.11 KinOmega Biopharm
- 10.12 Sinomega Biotech Engineering Co., Ltd.
- 10.13 Wiley Companies / AlaskOmega
- 10.14 Aker BioMarine Antarctic AS
- 10.15 Nissui Pharmaceutical Co., Ltd.

 食用油替代品市場規模、佔有率、成長、全球產業分析、區域趨勢及2026-2034年預測。魚粉和魚油市場規模、佔有率、成長、全球產業分析、區域趨勢以及 2026 年至 2034 年的預測。全球魚粉和魚油市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 全球魚油產品市場
 魚油市場:依應用、魚類、地區分類
 魚油市場-全球產業規模、佔有率、趨勢、機會、預測:按應用、類型、地區和競爭格局分類,2021-2031年
 鱈魚市場規模、佔有率及成長分析(依品種、供應來源、產品類型、通路及地區分類)-2026-2033年產業預測全球魚油替代品市場
 2032 年鱈魚市場預測:按產品類型、包裝類型、品種、分銷管道、應用、最終用戶和地區進行的全球分析魚油市場至2030年的預測:按產品類型、應用和地區分類的全球分析