

 |
市場調查報告書
商品編碼
2101994
電流感測器市場機會、成長要素、產業趨勢分析及2026-2035年預測Current Sensor Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球電流感測器市場預計到 2025 年將達到 36 億美元,並以 10.4% 的複合年成長率成長,到 2035 年將達到 95 億美元。
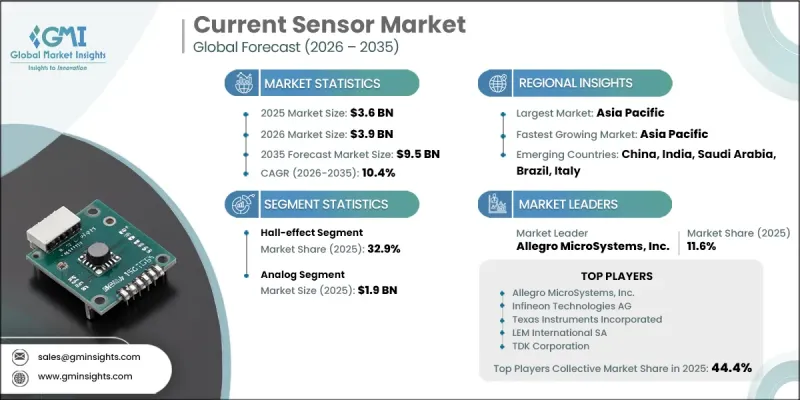
全球交通運輸系統的快速電氣化、可再生能源基礎設施的整合、工業自動化的普及以及智慧電網的現代化,共同推動了市場擴張。汽車系統、工業設備和能源平台對精確功率測量和能源最佳化的需求日益成長,進一步促進了電流感測器的應用。世界各國政府都在支持電氣化和可再生能源部署,加速先進感測技術的整合。電力公司也在大力投資智慧電網升級、數位化變電站和先進測量系統,以提高電網可靠性並應對可再生能源供應的波動。電動車生態系統、電池能源儲存系統和高效電力電子產品的擴展,持續推動對精確即時電流監測解決方案的需求。隨著各產業向更智慧、更互聯、更節能的營運模式轉型,電流感測器正成為確保系統效能、安全性和能源最佳化的關鍵元件,廣泛應用於各個領域。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 36億美元 |
| 預計金額 | 95億美元 |
| 複合年成長率 | 10.4% |
2025年,霍爾效應感測器市佔率達到32.9%,憑藉在電動車、工業自動化、可再生能源系統和家用電子電器等眾多領域的廣泛應用,持續保持主導地位。其高測量精度、成本效益、非接觸式感測和電氣隔離等優勢,使其廣受歡迎,並適用於監控電源轉換單元、馬達驅動器和電池管理架構等關鍵系統中的交流和直流電流。
預計到2025年,類比電路市場規模將達到19億美元。由於其在汽車系統、工業自動化平台、電源單元和可再生能源應用領域的廣泛應用,該市場將繼續保持領先地位。模擬電流感測技術因其可靠性高、響應速度快、成本效益高以及能夠提供連續即時電流測量而備受青睞。它易於整合到馬達控制系統、儲能解決方案和逆變器應用中,從而滿足了高產量生產環境中的強勁需求。
預計到2025年,北美電流感測器市場佔有率將達到31.1%,這主要得益於電動車的日益普及、清潔能源項目的擴張以及智慧電網現代化舉措的持續推進。電池管理系統、電動車充電基礎設施、工業自動化和儲能應用領域日益成長的需求,也持續加速該地區的市場成長。此外,公共和私人部門對先進製造能力、電網現代化項目和半導體創新領域的持續投資,進一步鞏固了該地區的市場地位。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 交通途徑的快速電氣化
- 可再生能源和能源儲存系統系統的擴展
- 工業自動化和智慧製造的擴展
- 智慧電網基礎設施現代化
- 節能電子系統的需求日益成長
- 產業潛在風險與挑戰
- 先進電流偵測技術高成本
- 惡劣工作條件下的精度限制
- 市場機遇
- 電動車和電池能源儲存系統系統的普及
- 智慧電網和工業4.0的廣泛應用
- 促進因素
- 成長潛力分析
- 價格分析
- 對過去價格趨勢的分析
- 依球員類型分類的定價策略(高級球員、超值球員、成本加成球員)
- 監理情勢
- 波特的分析
- PESTLE分析
- 貿易數據分析
- 進出口量及進口額趨勢
- 主要貿易路線及關稅的影響
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 生產能力和生產情況
- 主要生產商的生產能力
- 運轉率和擴張計劃
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 市場集中度分析
- 按地區
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 排名分類標準與選擇標準
- 按銷售額、地區和創新能力分類的層級定位矩陣。
第5章 市場估計與預測:依技術分類,2022-2035年
- 霍爾效應
- 分路電阻器
- 磁通門
- 磁阻型
- 羅戈夫斯基線圈
- 其他
第6章 市場估計與預測:依 Loop 分類,2022-2035 年
- 開放回路
- 閉合迴路
第7章 市場估計與預測:依產量分類,2022-2035年
- 模擬
- 數位的
第8章 市場估計與預測:依應用領域分類,2022-2035年
- 馬達驅動與控制
- 電源和直流-直流轉換器
- 逆變器系統
- 電池管理系統(BMS)
- 電動車充電系統
- 智慧電網和配電
- 不斷電系統(UPS)
- 其他
第9章 市場估計與預測:依最終用途產業分類,2022-2035年
- 車
- 通訊和資料中心
- 衛生保健
- 能源和電力業務
- 家用電子產品
- 其他
第10章 市場估價與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第11章:公司簡介
- 全球主要公司
- Allegro MicroSystems, Inc.
- Infineon Technologies AG
- Texas Instruments Incorporated
- LEM International SA
- TDK Corporation
- 該地區的主要公司
- 北美洲
- Honeywell International Inc.
- Littelfuse, Inc.(US)
- TE Connectivity
- Vishay Intertechnology, Inc
- 亞太地區
- Asahi Kasei Microdevices Corporation
- KOHSHIN ELECTRIC CORPORATION
- Omron Corporation
- ROHM Co., Ltd.
- TAMURA Corporation
- 歐洲
- Melexis
- Sensitec GmbH
- 北美洲
- 小眾玩家/顛覆者
- Aceinna
- NVE Corporation
- VACUUMSCHMELZE GmbH & Co. KG
The Global Current Sensor Market was valued at USD 3.6 billion in 2025 and is estimated to grow at a CAGR of 10.4% to reach USD 9.5 billion by 2035.
Market expansion is driven by the rapid electrification of transportation systems, increasing integration of renewable energy infrastructure, growing industrial automation, and the modernization of smart grid networks across global economies. Rising demand for precise power measurement and energy optimization in automotive systems, industrial equipment, and energy platforms is further reinforcing adoption. Governments worldwide are supporting electrification initiatives and renewable energy deployment, which is accelerating the integration of advanced sensing technologies. Utilities are also investing heavily in smart grid upgrades, digital substations, and advanced metering systems to improve grid reliability and accommodate variable renewable energy inputs. The expansion of electric vehicle ecosystems, battery energy storage systems, and high-efficiency power electronics continues to strengthen demand for accurate real-time current monitoring solutions. As industries transition toward smarter, more connected, and energy-efficient operations, current sensors are becoming essential components for ensuring system performance, safety, and energy optimization across multiple applications.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $3.6 Billion |
| Forecast Value | $9.5 Billion |
| CAGR | 10.4% |
The hall-effect segment accounted for 32.9% share in 2025, maintaining a leading position due to its widespread use across electric mobility, industrial automation, renewable energy systems, and consumer electronics. Its popularity is driven by advantages such as high measurement accuracy, cost efficiency, non-contact sensing, and electrical isolation, making it suitable for monitoring both AC and DC currents in critical systems such as power conversion units, motor drives, and battery management architectures.
The analog segment reached USD 1.9 billion in 2025. This segment continues to dominate due to its extensive deployment across automotive systems, industrial automation platforms, power supply units, and renewable energy applications. Analog current sensing technology is widely valued for its reliability, fast response, cost-effectiveness, and ability to deliver continuous real-time current measurements. Its straightforward integration into motor control systems, energy storage solutions, and inverter applications supports strong demand across high-volume manufacturing environments.
North America Current Sensor Market held 31.1% share in 2025, driven by rising adoption of electric vehicles, expansion of clean energy projects, and ongoing smart grid modernization initiatives. Increasing demand from battery management systems, EV charging infrastructure, industrial automation, and energy storage applications continues to accelerate regional growth. Continuous investments from both public and private sectors in advanced manufacturing capabilities, grid modernization programs, and semiconductor innovation are further strengthening the region's market position.
Major companies operating in the global current sensor market include Allegro MicroSystems, Inc., Infineon Technologies AG, Texas Instruments Incorporated, LEM International SA, Honeywell International Inc., TE Connectivity, Vishay Intertechnology, Inc., Littelfuse, Inc., Omron Corporation, TDK Corporation, Melexis, Asahi Kasei Microdevices Corporation, Sensitec GmbH, VACUUMSCHMELZE GmbH & Co. KG, TAMURA Corporation, NVE Corporation, Kohshin Electric Corporation, Aceinna, and ROHM Co., Ltd. Companies in the current sensor market are strengthening their competitive positioning through continuous innovation in sensing accuracy, miniaturization, and energy-efficient designs. Manufacturers are heavily investing in research and development to improve sensor precision, temperature stability, and integration capabilities for next-generation electronics. Strategic collaborations with automotive OEMs, renewable energy developers, and industrial automation providers are accelerating product adoption across high-growth applications. Firms are also expanding manufacturing capacity and enhancing supply chain resilience to meet rising global demand.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Technology trends
- 2.2.2 Loop trends
- 2.2.3 Output trends
- 2.2.4 Application trends
- 2.2.5 End-use industry trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rapid electrification of transportation
- 3.2.1.2 Expansion of renewable energy and energy storage systems
- 3.2.1.3 Growing industrial automation and smart manufacturing
- 3.2.1.4 Modernization of smart grid infrastructure
- 3.2.1.5 Increasing demand for energy-efficient electronic systems
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High cost of advanced current sensing technologies
- 3.2.2.2 Accuracy limitations under harsh operating conditions
- 3.2.3 Market opportunities
- 3.2.3.1 Expansion of electric vehicles and battery energy storage systems
- 3.2.3.2 Growing adoption of smart grids and Industry 4.0
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Pricing Analysis (Driven by Primary Research)
- 3.4.1 Historical Price Trend Analysis
- 3.4.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
- 3.5 Regulatory landscape
- 3.5.1 North America
- 3.5.2 Europe
- 3.5.3 Asia Pacific
- 3.5.4 Latin America
- 3.5.5 Middle East & Africa
- 3.6 Porter's analysis
- 3.7 PESTEL analysis
- 3.8 Trade Data Analysis (Based on Paid Database)
- 3.8.1 Import/Export Volume & Value Trends
- 3.8.2 Key Trade Corridors & Tariff Impact
- 3.9 Impact of AI & Generative AI on the Market (Driven by Primary Research)
- 3.9.1 AI-Driven Disruption of Existing Business Models
- 3.9.2 GenAI Use Cases & Adoption Roadmap by Segment
- 3.10 Capacity & Production Landscape (Driven by Primary Research)
- 3.10.1 Production Capacity by Key Producer
- 3.10.2 Capacity Utilization Rates & Expansion Pipelines
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis, 2025
- 4.2.1 By Region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia-Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East and Africa
- 4.2.2 Market Concentration Analysis
- 4.2.1 By Region
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New product launches
- 4.5.4 Expansion plans and funding
- 4.6 Company tier benchmarking
- 4.6.1 Tier classification criteria & qualifying thresholds
- 4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates and Forecast, By Technology, 2022 - 2035 (USD Million)
- 5.1 Key trends
- 5.2 Hall-effect
- 5.3 Shunt Resistor
- 5.4 Fluxgate
- 5.5 Magneto-resistive
- 5.6 Rogowski Coil
- 5.7 Others
Chapter 6 Market Estimates and Forecast, By Loop, 2022 - 2035 (USD Million)
- 6.1 Key trends
- 6.2 Open Loop
- 6.3 Closed Loop
Chapter 7 Market Estimates and Forecast, By Output, 2022 - 2035 (USD Million)
- 7.1 Key trends
- 7.2 Analog
- 7.3 Digital
Chapter 8 Market Estimates and Forecast, By Application, 2022 - 2035 (USD Million)
- 8.1 Key trends
- 8.2 Motor Drive & Control
- 8.3 Power Supply & DC-DC Conversion
- 8.4 Inverter Systems
- 8.5 Battery Management System (BMS)
- 8.6 Electric Vehicle Charging Systems
- 8.7 Smart Grid & Power Distribution
- 8.8 Uninterruptible Power Supply (UPS)
- 8.9 Others
Chapter 9 Market Estimates and Forecast, By End-use Industry, 2022 - 2035 (USD Million)
- 9.1 Key trends
- 9.2 Automotive
- 9.3 Telecommunication & Data Centers
- 9.4 Healthcare
- 9.5 Energy & Power Utilities
- 9.6 Consumer Electronics
- 9.7 Others
Chapter 10 Market Estimates and Forecast, By Region, 2022 - 2035 (USD Million)
- 10.1 Key trends
- 10.2 North America
- 10.2.1 U.S.
- 10.2.2 Canada
- 10.3 Europe
- 10.3.1 Germany
- 10.3.2 UK
- 10.3.3 France
- 10.3.4 Spain
- 10.3.5 Italy
- 10.4 Asia Pacific
- 10.4.1 China
- 10.4.2 India
- 10.4.3 Japan
- 10.4.4 Australia
- 10.4.5 South Korea
- 10.5 Latin America
- 10.5.1 Brazil
- 10.5.2 Mexico
- 10.5.3 Argentina
- 10.6 Middle East and Africa
- 10.6.1 South Africa
- 10.6.2 Saudi Arabia
- 10.6.3 UAE
Chapter 11 Company Profiles
- 11.1 Global Key Players
- 11.1.1 Allegro MicroSystems, Inc.
- 11.1.2 Infineon Technologies AG
- 11.1.3 Texas Instruments Incorporated
- 11.1.4 LEM International SA
- 11.1.5 TDK Corporation
- 11.2 Regional key players
- 11.2.1 North America
- 11.2.1.1 Honeywell International Inc.
- 11.2.1.2 Littelfuse, Inc. (U.S.)
- 11.2.1.3 TE Connectivity
- 11.2.1.4 Vishay Intertechnology, Inc
- 11.2.2 Asia Pacific
- 11.2.2.1 Asahi Kasei Microdevices Corporation
- 11.2.2.2 KOHSHIN ELECTRIC CORPORATION
- 11.2.2.3 Omron Corporation
- 11.2.2.4 ROHM Co., Ltd.
- 11.2.2.5 TAMURA Corporation
- 11.2.3 Europe
- 11.2.3.1 Melexis
- 11.2.3.2 Sensitec GmbH
- 11.2.1 North America
- 11.3 Niche Players/Disruptors
- 11.3.1 Aceinna
- 11.3.2 NVE Corporation
- 11.3.3 VACUUMSCHMELZE GmbH & Co. KG

 無芯磁電流感測器市場:全球市場預測,2026-2032年
 電流感測器:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)
 接地指示器市場規模、佔有率和成長分析:按產品類型、電壓範圍、應用、最終用戶、安裝方式和地區分類-2026-2033年產業預測電流感測器市場-2026-2032年全球市場預測
 全球高壓電流感測器市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 電流感測器市場-全球產業規模、佔有率、趨勢、機會、預測:按類型、技術、應用、最終用戶、地區和競爭格局分類,2021-2031年
 全球高壓電流感測器市場:按產品類型、技術、最終用途和地區分類-預測至2032年
 2026年全球電網感測器市場報告
 電流感測器市場規模、佔有率和成長分析:按感測器類型、迴路類型、電流偵測方法、輸出、應用和地區分類-2026-2033年產業預測
 電流感測器市場規模、佔有率、趨勢和預測:按類型、電流檢測技術、檢測方法、應用、最終用途和地區分類,2026-2034年