

 |
市場調查報告書
商品編碼
2101903
資料中心基礎設施市場:成長機會、成長要素、產業趨勢分析及2026-2035年預測Data Center Infrastructure Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球資料中心基礎設施市場預計到 2025 年將達到 2,342 億美元,並以 12.1% 的複合年成長率成長,到 2035 年將達到 7,898 億美元。
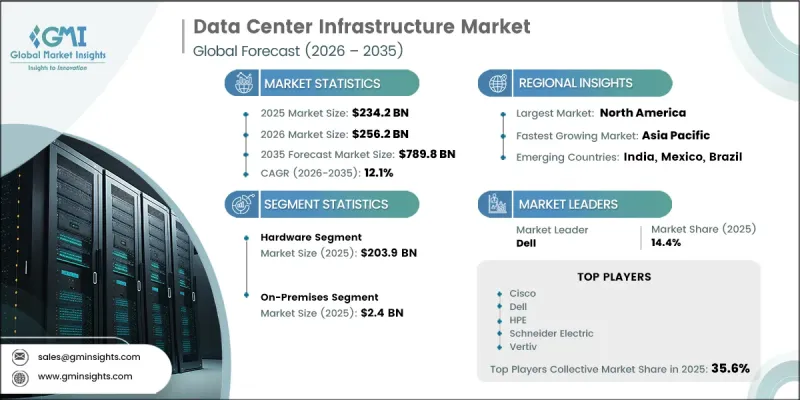
市場成長主要受人工智慧工作負載的快速成長、對超大規模運算的需求以及雲端邊緣基礎設施的快速擴張所驅動。隨著企業和雲端服務供應商加大對高密度運算環境的投資,市場正經歷根本性的變革,而這些環境需要先進的電力、冷卻和網路系統。生成式人工智慧、機器學習和高效能運算工作負載的激增導致機架密度顯著提高,基礎設施需求從傳統的每機架 10-15 千瓦躍升至 100 千瓦以上。這種轉變正在加速對液冷技術、高容量電源系統和新一代網路架構的投資。此外,超大規模資料中心建置和邊緣部署的激增也持續推動對模組化、擴充性和節能型基礎架構解決方案的需求。政府和企業也在優先考慮永續性和能源效率,進一步推動了先進冷卻系統和資料中心基礎設施管理 (DCIM) 解決方案的採用,以最佳化電源使用效率 (PUE) 並減少碳排放。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 2342億美元 |
| 預測金額 | 7898億美元 |
| 複合年成長率 | 12.1% |
持續的雲端遷移、不斷擴展的數位轉型計劃以及跨區域日益成長的數據主權需求,進一步推動了這個市場的發展。企業正在對其傳統IT基礎設施進行現代化改造,並向混合雲和雲端部署轉型,這需要強大且靈活的資料中心基礎架構。即時資料處理、物聯網和5G網路的重要性日益凸顯,也推動了邊緣資料中心的普及,從而擴大了全球基礎設施的部署規模。此外,有關能源效率和碳排放的監管要求迫使營運商採用創新解決方案,例如浸沒式冷卻、可再生能源整合和人工智慧驅動的基礎設施管理系統。這些進步不僅提高了營運效率,還降低了整體擁有成本 (TCO),並增強了資料中心基礎設施的彈性和擴充性,以滿足未來的數位化需求。
硬體產業在資料中心的電力分配、冷卻和網路建設中發揮至關重要的作用,預計到2025年,其市場規模將達到2039億美元。伺服器、機架、冷卻系統和電力基礎設施等硬體組件構成了資料中心營運的基礎,對於支援高效能工作負載至關重要。超大規模和託管資料中心的日益普及顯著推動了對先進硬體解決方案的需求,尤其是高效能電源系統和液冷技術。對持續運作和可靠性的需求也推動了對冗餘和容錯硬體系統的投資,進一步鞏固了該領域的市場主導地位。
預計到2025年,本地資料中心基礎設施市場規模將達到24億美元,佔市場佔有率的15%。儘管雲端環境正在不斷發展,但對本地基礎設施的需求仍然相對穩定。這種持續的投資主要源自於高度監管產業和政府機構嚴格的資料主權法規,這些法規要求企業直接控制敏感資訊。
預計2025年,北美資料中心基礎設施市場規模將達到981億美元,佔38.3%的市佔率。該地區的主導地位得益於超大規模雲端服務供應商的強大實力、企業對先進技術的廣泛應用,以及幾個關鍵資料中心樞紐歷來較低的電力成本,所有這些因素都促進了持續的投資和市場擴張。
目錄
第1章:調查方法
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 雲端運算和超大規模應用呈現爆炸性成長
- 人工智慧和機器學習工作負載的擴展正在推動對GPU密集型基礎設施的需求。
- 銀行、金融服務和保險 (BFSI)、醫療保健和政府部門的數位轉型。
- 5G 的部署和邊緣運算的普及正在推動分散式基礎設施的建設。
- 數據主權法規要求投資國內基礎設施
- 產業潛在風險與挑戰
- 電力供應受限和能源成本上升
- 基礎建設項目需要大量資本投資,且投資回收期較長。
- 市場機遇
- 在高密度人工智慧機架中引入液冷和浸沒式冷卻技術
- 綠色資料中心與可再生能源(太陽能、風能、核能)的整合
- 新興市場邊緣資料中心的擴張
- 促進因素
- 技術與創新展望
- 最新科技趨勢
- 液冷和浸沒式冷卻技術的進步
- 軟體定義資料中心 (SDDC) 和融合式基礎架構(HCI)
- 新興技術
- 模組化和預製資料中心技術
- 可再生能源併網與綠色基礎設施
- 最新科技趨勢
- 成長潛力分析
- 價格分析,2022-2025年
- 監理情勢
- 北美洲
- 美國 - 聯邦能源管理委員會 (FERC)
- 美國 -美國能源局(DOE)
- 美國 - 美國環保署 (EPA)
- 加拿大 - 創新、科學和經濟發展部 (ISED)
- 歐洲
- 歐盟 - 歐洲委員會 (EC) - 能源效率指令 (EED)
- 歐盟-歐洲綠色新政與歐盟永續金融分類法
- 德國 - 聯邦網路局 (Bundesnetzagentur)
- 愛爾蘭 -公共產業監理委員會 (CRU)
- 亞太地區
- 中國 - 工業及資訊化部(工信部)
- 印度 - 電子資訊技術部 (MeitY)
- 新加坡 - 資訊通訊媒體發展局 (IMDA)
- 澳洲 - 澳洲能源監管局 (AER)
- LATAM
- 巴西 - 國家電訊管理局 (ANATEL)
- 智利 -電訊副部長 (SUBTEL)
- 中東和非洲
- 阿拉伯聯合大公國 - 通訊和數位政府監管局 (TDRA)
- 沙烏地阿拉伯 - 通訊、太空和技術委員會 (CST)
- 南非 - 通訊與數位技術部 (DCDT)
- 北美洲
- 波特的分析
- PESTLE分析
- 專利分析
- 2025年成本細分分析
- 資料中心容量和現有基礎設施
- 各國裝置容量(兆瓦),2025年
- 2026-2030年擴張計劃
- 運轉率及供需狀況
- 能源和電力基礎設施分析
- 併網挑戰及與電力公司的合作
- 電錶側發電解決方案(太陽能發電、燃氣發電、小型模組化爐(SMR))
- 超大規模資料中心業者購電協定 (PPA) 的發展趨勢
- 資料中心電池儲能系統(BESS)的實施
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 預測假設和情境分析
- 基本案例:驅動複合年成長率的關鍵宏觀經濟與產業變量
- 樂觀情境:宏觀經濟與產業的順風
- 悲觀情景:宏觀經濟放緩或產業逆風
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 北美洲
- 歐洲
- 亞太地區
- LATAM
- 中東和非洲
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 排名分類標準與遴選標準
- 按銷售額、地區和創新能力分類的層級定位矩陣。
第5章 市場估計與預測:依組件分類,2022-2035年
- 硬體
- IT基礎設施
- 伺服器
- 機架式伺服器
- 刀鋒伺服器
- 塔式伺服器
- 貯存
- 儲存區域網路(SAN)
- 網路附加儲存 (NAS)
- 物件儲存陣列
- 網路裝置
- 交換器和路由器
- 負載平衡器
- 光連接模組和收發器
- 伺服器
- 電力基礎設施
- 不斷電系統(UPS)
- 發電機和傳輸開關
- 配電單元 (PDU) 和開關設備
- 電力和能源管理系統
- 冷卻基礎設施
- 電腦房空調/空氣處理系統(CRAC/CRAH)
- 冷卻器和冷卻塔系統
- 液冷和浸沒式冷卻系統
- 絕熱冷卻和自然冷卻系統
- 支援基礎設施
- 機架和機櫃
- 結構化佈線和電纜管理
- 實體安全系統
- 建築管理系統(BMS)
- IT基礎設施
- 軟體
- 資料中心基礎設施管理 (DCIM) 軟體
- IT基礎設施管理和自動化軟體
- 安全與合規軟體
- 人工智慧驅動的基礎設施最佳化軟體
- 服務
- 專業服務
- 諮詢和顧問服務
- 設計與工程
- 安裝與整合
- 測試和試運行
- 託管服務
- 專業服務
第6章 市場估算與預測:依部署類型分類,2022-2035年
- 現場
- 雲
- 混合
第7章 市場估計與預測:依層級分類,2022-2035年
- 一級
- 二級
- 三級
- 第四級
第8章 市場估算與預測:依資料中心分類,2022-2035年
- 企業資料中心
- 託管資料中心
- 超大規模資料中心
- 邊緣資料中心
第9章 市場估計與預測:依最終用途產業分類,2022-2035年
- BFSI
- 搭配
- 能源
- 政府
- 衛生保健
- 製造業
- IT/通訊
- 零售與電子商務
- 媒體與娛樂
- 其他
第10章 市場估價與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 荷蘭
- 比利時
- 瑞典
- 波蘭
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 澳洲
- 新加坡
- 泰國
- 印尼
- 馬來西亞
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 智利
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第11章:公司簡介
- 世界公司
- Schneider Electric SE
- Vertiv Group Co.
- Dell Technologies
- Cisco Systems
- Hewlett Packard Enterprise
- Eaton Corporation
- Juniper Networks
- ABB Ltd.
- Siemens AG
- Honeywell International
- 當地公司
- Coherent Corp.
- Rittal GmbH & Co. KG
- NetApp Inc.
- Arista Networks
- Pure Storage
- Legrand SA
- Cummins Inc.
- Ciena Corporation
- Hyperview
- LiquidStack
The Global Data Center Infrastructure Market was valued at USD 234.2 billion in 2025 and is estimated to grow at a CAGR of 12.1% to reach USD 789.8 billion by 2035.
Market growth is driven by the exponential rise in AI workloads, hyperscale computing demand, and the rapid expansion of cloud and edge infrastructure. The market is undergoing a fundamental transformation as enterprises and cloud providers increasingly invest in high-density computing environments that require advanced power, cooling, and networking systems. The proliferation of generative AI, machine learning, and high-performance computing workloads is significantly increasing rack densities, pushing infrastructure requirements from traditional 10-15 kW to over 100 kW per rack. This shift is accelerating investments in liquid cooling technologies, high-capacity power systems, and next-generation networking fabrics. Additionally, the surge in hyperscale data center construction and edge deployments is creating sustained demand for modular, scalable, and energy-efficient infrastructure solutions. Governments and enterprises are also prioritizing sustainability and energy efficiency, further driving adoption of advanced cooling systems and DCIM solutions to optimize power usage effectiveness (PUE) and reduce carbon footprints.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $234.2 Billion |
| Forecast Value | $789.8 Billion |
| CAGR | 12.1% |
The market is further supported by continuous cloud migration, rising digital transformation initiatives, and the increasing need for data sovereignty across regions. Enterprises are modernizing legacy IT infrastructure and shifting toward hybrid and cloud-based deployments, which necessitate robust and flexible data center infrastructure. The growing importance of real-time data processing, IoT, and 5G networks is also fueling the deployment of edge data centers, thereby expanding the infrastructure footprint globally. Moreover, regulatory mandates on energy efficiency and carbon emissions are pushing operators to adopt innovative solutions such as immersion cooling, renewable energy integration, and AI-driven infrastructure management systems. These advancements are not only improving operational efficiency but also reducing the total cost of ownership, making data center infrastructure more resilient and scalable for future digital demands.
The hardware segment generated USD 203.9 billion in 2025 owing to its critical role in enabling power distribution, cooling, and networking within data centers. Hardware components such as servers, racks, cooling systems, and power infrastructure form the backbone of data center operations, making them indispensable for supporting high-performance workloads. The increasing deployment of hyperscale and colocation facilities is significantly boosting demand for advanced hardware solutions, particularly high-efficiency power systems and liquid cooling technologies. The need for continuous uptime and reliability is also driving investments in redundant and fault-tolerant hardware systems, further strengthening this segment's dominance.
The on-premises data center infrastructure segment captured USD 2.4 billion in 2025, accounting for 15% share. Despite the ongoing transition toward cloud-based environments, demand for on-premises infrastructure has remained relatively stable. This sustained investment is primarily driven by strict data sovereignty regulations across highly regulated industries and government organizations that require sensitive information to remain under direct organizational control.
North America Data Center Infrastructure Market generated USD 98.1 billion, accounting for 38.3% share in 2025. The region's leadership is supported by a strong presence of hyperscale cloud providers, widespread enterprise adoption of advanced technologies, and historically favorable electricity costs across several major data center hubs, contributing to continued investment and market expansion.
Key players operating in the Global Data Center Infrastructure Market include ABB, Cisco Systems, Dell Technologies, Eaton Corporation, Hewlett Packard Enterprise (HPE), IBM, Lenovo Group Limited, NetApp, Schneider Electric, Vertiv Holdings Co., Fujitsu, Huawei, Inspur, Legrand, and Rittal. Companies in the Data Center Infrastructure Market are focusing on strategic partnerships, mergers and acquisitions, and large-scale capacity expansions to strengthen their market presence. Collaborations with cloud providers and AI firms enable vendors to co-develop high-density infrastructure solutions tailored for next-generation workloads. Investments in liquid cooling and energy-efficient technologies are a major priority, helping companies align with sustainability goals and regulatory requirements. Additionally, firms are expanding manufacturing capabilities and global supply chains to reduce lead times and meet growing demand. Product innovation, particularly in AI-driven DCIM, modular infrastructure, and high-speed networking, is another key strategy. Companies are also entering emerging markets and edge data center segments to capture new growth opportunities and diversify revenue streams.
Table of Contents
Chapter 1 Methodology
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Component
- 2.2.3 Deployment Mode
- 2.2.4 Tier
- 2.2.5 Data Center
- 2.2.6 End Use Industry
- 2.3 TAM analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Explosive growth of cloud computing & hyperscale deployments
- 3.2.1.2 AI & machine learning workload expansion driving GPU-dense infrastructure demand
- 3.2.1.3 Digital transformation across BFSI, healthcare & government verticals
- 3.2.1.4 5G rollout & edge computing proliferation fueling distributed infrastructure build-out
- 3.2.1.5 Data sovereignty regulations mandating in-country infrastructure investment
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 Power supply constraints & escalating energy costs
- 3.2.2.2 High capital expenditure & long payback periods for infrastructure projects infrastructure
- 3.2.3 Market opportunities
- 3.2.3.1 Liquid & immersion cooling adoption for high-density ai racks
- 3.2.3.2 Green data centers & renewable energy integration (solar, wind, nuclear)
- 3.2.3.3 Edge data center expansion in emerging markets
- 3.2.1 Growth drivers
- 3.3 Technology and innovation landscape
- 3.3.1 Current technological trends
- 3.3.1.1 Liquid & immersion cooling technology advances
- 3.3.1.2 Software-defined data center (SDDC) & hyperconverged infrastructure (HCI)
- 3.3.2 Emerging technologies
- 3.3.2.1 Modular & prefabricated data center technology
- 3.3.2.2 Renewable energy integration & green infrastructure
- 3.3.1 Current technological trends
- 3.4 Growth potential analysis
- 3.5 Pricing analysis, 2022-2025 (Driven by Primary Research)
- 3.6 Regulatory landscape
- 3.6.1 North America
- 3.6.1.1 US — Federal Energy Regulatory Commission (FERC)
- 3.6.1.2 US — U.S. Department of Energy (DOE)
- 3.6.1.3 US — U.S. Environmental Protection Agency (EPA)
- 3.6.1.4 Canada — Innovation, Science and Economic Development Canada (ISED)
- 3.6.2 Europe
- 3.6.2.1 EU — European Commission (EC) — Energy Efficiency Directive (EED)
- 3.6.2.2 EU — European Green Deal & EU Taxonomy for Sustainable Finance
- 3.6.2.3 Germany — Federal Network Agency (Bundesnetzagentur)
- 3.6.2.4 Ireland — Commission for Regulation of Utilities (CRU)
- 3.6.3 Asia Pacific
- 3.6.3.1 China — Ministry of Industry and Information Technology (MIIT)
- 3.6.3.2 India — Ministry of Electronics and Information Technology (MeitY)
- 3.6.3.3 Singapore — Infocomm Media Development Authority (IMDA)
- 3.6.3.4 Australia — Australian Energy Regulator (AER)
- 3.6.4 LATAM
- 3.6.4.1 Brazil — Agencia Nacional de Telecomunicacoes (ANATEL)
- 3.6.4.2 Chile — Subsecretaria de Telecomunicaciones (SUBTEL)
- 3.6.5 MEA
- 3.6.5.1 UAE — Telecommunications and Digital Government Regulatory Authority (TDRA)
- 3.6.5.2 Saudi Arabia — Communications, Space & Technology Commission (CST)
- 3.6.5.3 South Africa — Department of Communications and Digital Technologies (DCDT)
- 3.6.1 North America
- 3.7 Porter’s analysis
- 3.8 PESTEL analysis
- 3.9 Patent analysis (Driven by Primary Research)
- 3.10 Cost breakdown analysis, 2025
- 3.11 Data center capacity & infrastructure landscape
- 3.11.1 Installed capacity (MW) by country, 2025
- 3.11.2 Expansion pipeline, 2026-2030
- 3.11.3 Utilization rates & supply-demand
- 3.12 Energy & power infrastructure analysis
- 3.12.1 Grid interconnection challenges & utility partnerships
- 3.12.2 Behind-the-meter power generation solutions (solar, gas, nuclear SMRs)
- 3.12.3 Power Purchase Agreement (PPA) trends among hyperscalers
- 3.12.4 Battery energy storage system (BESS) adoption in data centers
- 3.13 Impact of AI & generative AI on the market
- 3.13.1 AI-driven disruption of existing business models
- 3.13.2 GenAI use cases & adoption roadmap by segment
- 3.13.3 Risks, limitations & regulatory considerations
- 3.14 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.14.1 Base Case- Key macro & industry variables driving CAGR
- 3.14.2 Optimistic Scenarios- Favorable macro and industry tailwinds
- 3.14.3 Pessimistic Scenario - Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 LATAM
- 4.2.5 MEA
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New product launches
- 4.5.4 Expansion plans and funding
- 4.6 Company tier benchmarking
- 4.6.1 Tier classification criteria & qualifying thresholds
- 4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates and Forecast, By Component, 2022 – 2035 ($ Bn)
- 5.1 Key trends
- 5.2 Hardware
- 5.2.1 IT infrastructure
- 5.2.1.1 Servers
- 5.2.1.1.1 Rack servers
- 5.2.1.1.2 Blade servers
- 5.2.1.1.3 Tower servers
- 5.2.1.2 Storage
- 5.2.1.2.1 Storage area network (SAN)
- 5.2.1.2.2 Network-attached storage (NAS)
- 5.2.1.2.3 Object storage arrays
- 5.2.1.3 Networking equipment
- 5.2.1.3.1 Switches & routers
- 5.2.1.3.2 Load balancers
- 5.2.1.3.3 Optical interconnects & transceivers
- 5.2.1.1 Servers
- 5.2.2 Power infrastructure
- 5.2.2.1 Uninterruptible power supplies (UPS)
- 5.2.2.2 Generators & transfer switches
- 5.2.2.3 Power distribution units (PDUs) & switchgear
- 5.2.2.4 Power & energy management systems
- 5.2.3 Cooling infrastructure
- 5.2.3.1 Computer room air conditioning/air handling (CRAC/CRAH)
- 5.2.3.2 Chiller & cooling tower systems
- 5.2.3.3 Liquid & immersion cooling systems
- 5.2.3.4 Adiabatic & free cooling systems
- 5.2.4 Support infrastructure
- 5.2.4.1 Racks & enclosures
- 5.2.4.2 Structured cabling & cable management
- 5.2.4.3 Physical security systems
- 5.2.4.4 Building management systems (BMS)
- 5.2.1 IT infrastructure
- 5.3 Software
- 5.3.1 Data center infrastructure management (DCIM) software
- 5.3.2 IT infrastructure management & automation software
- 5.3.3 Security & compliance software
- 5.3.4 AI-driven infrastructure optimization software
- 5.4 Services
- 5.4.1 Professional services
- 5.4.1.1 Consulting & advisory
- 5.4.1.2 Design & engineering
- 5.4.1.3 Installation & integration
- 5.4.1.4 Testing & commissioning
- 5.4.2 Managed services
- 5.4.1 Professional services
Chapter 6 Market Estimates and Forecast, By Deployment Mode, 2022 – 2035 ($ Bn)
- 6.1 Key trends
- 6.2 On-Premises
- 6.3 Cloud
- 6.4 Hybrid
Chapter 7 Market Estimates and Forecast, By Tier, 2022 – 2035 ($ Bn, GW)
- 7.1 Key trends
- 7.2 Tier 1
- 7.3 Tier 2
- 7.4 Tier 3
- 7.5 Tier 4
Chapter 8 Market Estimates and Forecast, By Data Center, 2022 – 2035 ($ Bn, GW)
- 8.1 Key trends
- 8.2 Enterprise Data Centers
- 8.3 Colocation Data Centers
- 8.4 Hyperscale Data Centers
- 8.5 Edge Data Centers
Chapter 9 Market Estimates and Forecast, By End Use Industry, 2022 – 2035 ($ Bn)
- 9.1 Key trends
- 9.2 BFSI
- 9.3 Colocation
- 9.4 Energy
- 9.5 Government
- 9.6 Healthcare
- 9.7 Manufacturing
- 9.8 IT & Telecom
- 9.9 Retail & E-commerce
- 9.10 Media & Entertainment
- 9.11 Others
Chapter 10 Market Estimates & Forecast, By Region, 2022 - 2035 ($ Mn)
- 10.1 Key trends
- 10.2 North America
- 10.2.1 US
- 10.2.2 Canada
- 10.3 Europe
- 10.3.1 Germany
- 10.3.2 UK
- 10.3.3 France
- 10.3.4 Italy
- 10.3.5 Spain
- 10.3.6 Netherlands
- 10.3.7 Belgium
- 10.3.8 Sweden
- 10.3.9 Poland
- 10.4 Asia Pacific
- 10.4.1 China
- 10.4.2 India
- 10.4.3 Japan
- 10.4.4 South Korea
- 10.4.5 Australia
- 10.4.6 Singapore
- 10.4.7 Thailand
- 10.4.8 Indonesia
- 10.4.9 Malaysia
- 10.5 Latin America
- 10.5.1 Brazil
- 10.5.2 Mexico
- 10.5.3 Argentina
- 10.5.4 Chile
- 10.6 MEA
- 10.6.1 South Africa
- 10.6.2 Saudi Arabia
- 10.6.3 UAE
Chapter 11 Company Profiles
- 11.1 Global Players
- 11.1.1 Schneider Electric SE
- 11.1.2 Vertiv Group Co.
- 11.1.3 Dell Technologies
- 11.1.4 Cisco Systems
- 11.1.5 Hewlett Packard Enterprise
- 11.1.6 Eaton Corporation
- 11.1.7 Juniper Networks
- 11.1.8 ABB Ltd.
- 11.1.9 Siemens AG
- 11.1.10 Honeywell International
- 11.2 Regional Players
- 11.2.1 Coherent Corp.
- 11.2.2 Rittal GmbH & Co. KG
- 11.2.3 NetApp Inc.
- 11.2.4 Arista Networks
- 11.2.5 Pure Storage
- 11.2.6 Legrand SA
- 11.2.7 Cummins Inc.
- 11.2.8 Ciena Corporation
- 11.2.9 Hyperview
- 11.2.10 LiquidStack

 全球資料中心IT基礎設施市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 資料中心基礎設施管理市場機會、成長要素、產業趨勢分析及2026-2035年預測2026 年資料中心基礎設施十大成長機遇
 該報告分析了資料中心基礎設施市場的規模和預測、全球和區域佔有率、趨勢和成長機會。分析範圍:依提供的服務、資料中心規模、層級類型、最終使用者和地區分類。
 2026-2030年全球資料中心IT基礎設施市場
 2026年全球資料中心(DCIM)服務市場報告
 資料中心基礎設施市場:按組件、資料中心類型、產業和地區分類
 資料中心基礎設施管理(DCIM):市場佔有率分析、產業趨勢與統計資料、成長預測(2026-2031)
 全球資料中心基礎設施管理 (DCIM) 市場預測至 2034 年:按元件、功能、部署類型、資料中心類型、應用程式、最終用戶和地區分類全球資料中心電氣基礎設施服務市場預測(至2034年),依電氣系統類型、等級分類、電力容量、資料中心類別、最終使用者和地區分類