

 |
市場調查報告書
商品編碼
2101893
人工智慧管治市場機會、成長要素、產業趨勢分析及2026-2035年預測AI Governance Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

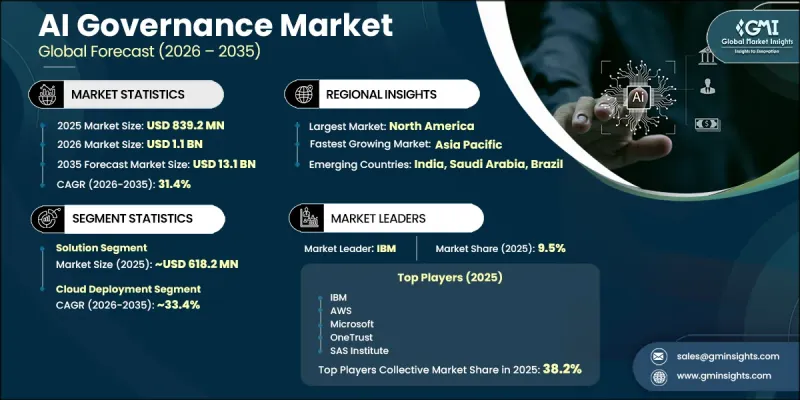
全球人工智慧管治市場預計到 2025 年將價值 8.392 億美元,並將以 31.4% 的複合年成長率成長,到 2035 年達到 131 億美元。
該市場的成長本質上是結構性的,其驅動力在於人工智慧應用與管治框架發展之間日益擴大的差距。隨著企業在信用評估、醫療診斷、物流最佳化和人才分析等高影響力領域部署機器學習系統,人工智慧的應用日益普及,管治框架的需求。由於潛在罰款高達3500萬美元(相當於全球銷售額的7%),對人工智慧的監管已成為在受監管司法管轄區運營的跨國公司董事會層面的優先事項。同時,人工智慧的應用發展速度超過了內部控制系統的成熟度,企業正迅速制定人工智慧管治方案。產業研究表明,絕大多數企業,尤其是那些已經大規模部署人工智慧的企業,都在積極建立管治能力。隨著人工智慧被整合到關鍵管治系統中,如果企業缺乏系統性的治理框架,將面臨監管、營運和聲譽風險增加的挑戰。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 8.392億美元 |
| 預測金額 | 131億美元 |
| 複合年成長率 | 31.4% |
累計到2025年,解決方案業務部門的收入將達到6.182億美元,市佔率高達74%。這一主導地位反映出企業越來越傾向於採用技術主導的管治系統,這些系統能夠對人工智慧模型進行持續的即時監控,並確保監管能夠跟上模型快速管治的步伐。各組織機構正逐步從人工的、週期性的審查流程轉向自動化的、始終線上運作基礎設施,並將這些基礎設施直接整合到其人工智慧開發平臺中。
預計到2025年,雲端採用市場規模將達到4.544億美元,佔市場佔有率的54.1%。雲端採用市場主導地位的主要驅動力在於其整合效率,因為大多數企業人工智慧工作負載已在雲端生態系中開發和部署。因此,嵌入雲端原生環境的管治平台能夠降低營運複雜性,實現與機器學習工作流程的無縫整合,並加速分散式人工智慧系統的合規性執行。
預計到2025年,北美人工智慧管治市場規模將達到3.929億美元。該地區的市場領先地位得益於其多層法律規範,該結構結合了聯邦指令和快速發展的州級立法。這種不斷演變的管治環境正在形成一個跨司法管轄區的治理格局,並顯著提升了各行業企業對標準化人工智慧監管框架的需求。
目錄
第1章:調查方法
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 人工智慧相關法規的快速擴展正在推動強制合規趨勢。
- 人工智慧在企業中的快速應用,正在各行業造成嚴重的管治漏洞。
- 與人工智慧相關的事件、偏見問題以及日益增加的監管制裁正在加速對預防性管治的投資。
- 生成式人工智慧的普及增加了對專為LLM設計的管治和防護工具的需求。
- 產業潛在風險與挑戰
- 實施的複雜性和較高的總體擁有成本阻礙了中型企業採用該技術。
- 人工智慧管治專業知識和認證專業人員的嚴重短缺限制了其部署速度。
- 市場機遇
- 中小企業 (SME) 細分市場滲透率較低,在高度擴充性的基於 SaaS 的管治存在成長機會。
- 產業擴張至製造業、零售業及電信業。
- 基於代理的人工智慧的普及催生了對下一代自主人工智慧管治功能的需求。
- 促進因素
- 技術與創新展望
- 最新科技趨勢
- 模型風險管理(MRM)平台
- 偏見檢測和公平性監測
- 新興技術
- 人工智慧管治平台
- 人工智慧政策自動執行系統
- 最新科技趨勢
- 成長潛力分析
- 監理情勢
- 北美洲
- 美國國家標準與技術研究院人工智慧安全研究所
- 美國聯邦貿易委員會(FTC)
- 加拿大 - 人工智慧和數據法案 (AIDA)
- 歐洲
- 歐盟-歐洲人工智慧秘書處
- 歐盟-歐洲人工智慧委員會(EU)
- 英國- 人工智慧安全研究所 (AISI)
- 亞太地區
- 中國 - 中國國家網際網路資訊辦公室(網信辦)
- 新加坡 - 資訊通訊媒體發展局 (IMDA)
- 日本 - 個人資訊保護委員會(PPC)
- 拉丁美洲
- 巴西 - 資料保護局 (ANPD)
- 哥倫比亞 - 工業和商業監管局 (SIC)
- 中東和非洲
- 沙烏地阿拉伯 - 沙烏地阿拉伯資料與人工智慧機構
- 阿拉伯聯合大公國人工智慧與先進技術委員會(AIATC)
- 北美洲
- 波特的分析
- PESTLE分析
- 專利分析
- 基於代理的人工智慧管治
- 自主與多智慧體人工智慧系統的管治框架
- 部署基於代理的人工智慧時所面臨的風險、課責和法律責任的挑戰。
- 針對基於代理的人工智慧管治的新標準和產業計劃
- 案例研究
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 預測假設和情境分析
- 基本案例:驅動複合年成長率的關鍵宏觀經濟與產業變量
- 樂觀情境:宏觀經濟與產業的順風
- 悲觀情景:宏觀經濟放緩或產業逆風
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 排名分類標準與遴選標準
- 按銷售額、地區和創新能力分類的層級定位矩陣。
第5章 市場估算與預測:以交付方式分類,2022-2035年
- 解決方案
- 人工智慧風險與合規管理軟體
- 人工智慧審計和保證軟體
- AI模型監控與可觀測軟體
- 人工智慧可解釋性和偏見管理軟體
- 生成式人工智慧和LLM管治軟體
- 服務
- 專業服務
- 諮詢和顧問服務
- 系統整合
- 培訓和教育項目
- 監管和審計服務
- 託管服務
- 專業服務
第6章 市場估算與預測:依部署類型分類,2022-2035年
- 雲
- 現場
- 混合
第7章 市場估計與預測:依組織規模分類,2022-2035年
- 大公司
- 小型企業
第8章 市場估算與預測:依最終用途分類,2022-2035年
- BFSI
- 銀行業
- 金融服務
- 保險
- 醫療保健和生命科學
- 政府/國防
- 零售和消費品
- 車
- 電訊
- 製造業
- 其他
第9章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 荷蘭
- 瑞典
- 瑞士
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 新加坡
- 印尼
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第10章:公司簡介
- 世界公司
- IBM
- Microsoft
- Amazon Web Services
- SAP
- Salesforce
- ServiceNow
- OneTrust
- SAS Institute
- Oracle
- Collibra
- Optro
- 本地公司
- 2021.AI
- Saidot Oy
- Modulos
- ValidMind
- NTT DATA
- 新興企業
- Credo
- Holistic AI
- Trustible
The Global AI Governance Market was valued at USD 839.2 million in 2025 and is estimated to grow at a CAGR of 31.4% to reach USD 13.1 billion by 2035.
Growth in this market is fundamentally structural, driven by the widening gap between AI adoption and governance readiness as organizations embed machine learning systems into high-impact domains such as credit assessment, medical diagnostics, logistics optimization, and workforce analytics. Regulatory enforcement has transitioned from optional guidelines to enforceable compliance mandates, significantly increasing enterprise demand for governance frameworks. Financial penalties reaching up to USD 35 million or 7% of global turnover have made AI oversight a board-level priority for multinational organizations operating in regulated jurisdictions. At the same time, enterprises are rapidly formalizing AI governance programs as adoption scales faster than internal control systems can mature. Industry surveys indicate that a large majority of organizations are actively building governance capabilities, particularly among those already deploying AI at scale. As AI becomes embedded in critical decision-making systems, organizations face rising exposure to regulatory, operational, and reputational risks without structured governance mechanisms in place.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $839.2 Million |
| Forecast Value | $13.1 Billion |
| CAGR | 31.4% |
The solutions segment generated USD 618.2 million in 2025, representing 74% share. This strong dominance reflects enterprise preference for technology-driven governance systems capable of continuously monitoring AI models in real time, ensuring oversight keeps pace with rapid model deployment cycles. Organizations are increasingly shifting away from manual and periodic review processes toward automated, always-on governance infrastructures that integrate directly into AI development pipelines.
The cloud deployment segment accounted for USD 454.4 million in 2025, capturing 54.1% share. Cloud-based dominance is primarily driven by integration efficiency, as most enterprise AI workloads are already developed and deployed within cloud ecosystems. As a result, governance platforms embedded within cloud-native environments reduce operational complexity, enable seamless integration with machine learning workflows, and accelerate compliance implementation across distributed AI systems.
North America AI Governance Market reached USD 392.9 million in 2025. The region's leadership is supported by a layered regulatory structure combining federal directives and rapidly expanding state-level legislation. This evolving compliance landscape has created a multi-jurisdiction governance environment that significantly increases enterprise demand for standardized AI oversight frameworks across industries.
Major players operating in the global AI governance market include Microsoft, IBM, Amazon Web Services, Google, Oracle, SAP, Salesforce, ServiceNow, SAS Institute, Collibra, OneTrust, NTT DATA, Optro, Credo AI, Holistic AI, Trustible, ValidMind, Saidot Oy, Modulos, and 2021.AI. Companies in the AI governance market are prioritizing platform unification strategies that consolidate model monitoring, compliance tracking, and risk assessment into single integrated solutions. Many vendors are strengthening partnerships with cloud service providers to ensure seamless embedding of governance tools within AI development environments. Product innovation is focused on automated explainability, bias detection, and real-time audit capabilities that reduce manual intervention. Firms are also expanding their regulatory intelligence features to adapt quickly to evolving global AI laws. Strategic acquisitions are being used to broaden capability stacks, while enterprise-focused customization and API-first architectures are improving integration flexibility.
Table of Contents
Chapter 1 Methodology
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Offering
- 2.2.3 Deployment Mode
- 2.2.4 Organization Size
- 2.2.5 End-Use
- 2.3 TAM analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rapid Global Expansion of AI-Specific Regulations Driving Mandatory Compliance Adoption
- 3.2.1.2 Surging Enterprise AI Deployment Creating Critical Governance Gaps Across Industries
- 3.2.1.3 Rising AI-Related Incidents, Bias Events & Regulatory Penalties Accelerating Proactive Governance Investment
- 3.2.1.4 Generative AI Proliferation Amplifying Demand for LLM-Specific Governance & Guardrail Tools
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High Implementation Complexity & Total Cost of Ownership Limiting Adoption Among Mid-Market Organizations
- 3.2.2.2 Critical Shortage of AI Governance Expertise & Certified Professionals Constraining Deployment Speed
- 3.2.3 Market opportunities
- 3.2.3.1 Underpenetrated SME Segment Presenting Scalable SaaS-Based Governance Growth Opportunity
- 3.2.3.2 Industry Expansion into Manufacturing, Retail & Telecommunications
- 3.2.3.3 Agentic AI Proliferation Creating Demand for Next-Generation Autonomous AI Governance Capabilities
- 3.2.1 Growth drivers
- 3.3 Technology and innovation landscape
- 3.3.1 Current technological trends
- 3.3.1.1 Model Risk Management (MRM) Platforms
- 3.3.1.2 Bias Detection & Fairness Monitoring
- 3.3.2 Emerging technologies
- 3.3.2.1 Generative AI Governance Platforms
- 3.3.2.2 Automated AI Policy Enforcement Systems
- 3.3.1 Current technological trends
- 3.4 Growth potential analysis
- 3.5 Regulatory landscape
- 3.5.1 North America
- 3.5.1.1 US - NIST AI Safety Institute
- 3.5.1.2 US - Federal Trade Commission (FTC)
- 3.5.1.3 Canada - Artificial Intelligence and Data Act (AIDA)
- 3.5.2 Europe
- 3.5.2.1 EU - European AI Office
- 3.5.2.2 EU - European Artificial Intelligence Board (EU)
- 3.5.2.3 UK - AI Security Institute (AISI)
- 3.5.3 Asia Pacific
- 3.5.3.1 China - Cyberspace Administration of China (CAC)
- 3.5.3.2 Singapore - Infocomm Media Development Authority (IMDA)
- 3.5.3.3 Japan - Personal Information Protection Commission (PPC)
- 3.5.4 LATAM
- 3.5.4.1 Brazil - Data Protection Authority (ANPD)
- 3.5.4.2 Colombia - Superintendency of Industry and Commerce (SIC)
- 3.5.5 MEA
- 3.5.5.1 Saudi Arabia - Saudi Data and AI Authority
- 3.5.5.2 UAE - Artificial Intelligence and Advanced Technology Council (AIATC)
- 3.5.1 North America
- 3.6 Porter’s analysis
- 3.7 PESTEL analysis
- 3.8 Patent analysis (Driven by Primary Research)
- 3.9 Agentic AI Governance
- 3.9.1 Governance Frameworks for Autonomous & Multi-Agent AI Systems
- 3.9.2 Risk, Accountability & Liability Challenges in Agentic AI Deployments
- 3.9.3 Emerging Standards & Industry Approaches for Agentic AI Oversight
- 3.10 Case studies
- 3.11 Impact of AI & generative AI on the market
- 3.11.1 AI-driven disruption of existing business models
- 3.11.2 GenAI use cases & adoption roadmap by segment
- 3.11.3 Risks, limitations & regulatory considerations
- 3.12 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.12.1 Base Case- Key Macro & Industry Variables Driving CAGR
- 3.12.2 Optimistic Scenarios- Favorable macro and industry tailwinds
- 3.12.3 Pessimistic Scenario - Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 LATAM
- 4.2.5 MEA
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New product launches
- 4.5.4 Expansion plans and funding
- 4.6 Company tier benchmarking
- 4.6.1 Tier classification criteria & qualifying thresholds
- 4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates and Forecast, By Offering, 2022 – 2035 ($ Mn)
- 5.1 Key trends
- 5.2 Solution
- 5.2.1 AI Risk & Compliance Management Software
- 5.2.2 AI Audit & Assurance Software
- 5.2.3 AI Model Monitoring & Observability Software
- 5.2.4 AI Explainability & Bias Management Software
- 5.2.5 Generative AI & LLM Governance Software
- 5.3 Service
- 5.3.1 Professional Services
- 5.3.1.1 Consulting & Advisory
- 5.3.1.2 System Integration
- 5.3.1.3 Training & Education Programs
- 5.3.1.4 Regulatory & Audit Services
- 5.3.2 Managed Services
- 5.3.1 Professional Services
Chapter 6 Market Estimates and Forecast, By Deployment Mode, 2022 – 2035 ($ Mn)
- 6.1 Key trends
- 6.2 Cloud
- 6.3 On-Premises
- 6.4 Hybrid
Chapter 7 Market Estimates and Forecast, By Organization Size, 2022 – 2035 ($ Mn)
- 7.1 Key trends
- 7.2 Large Enterprises
- 7.3 SMEs
Chapter 8 Market Estimates and Forecast, By End-Use, 2022 – 2035 ($ Mn)
- 8.1 Key trends
- 8.2 BFSI
- 8.2.1 Banking
- 8.2.2 Financial Services
- 8.2.3 Insurance
- 8.3 Healthcare & Life Sciences
- 8.4 Government & Defense
- 8.5 Retail & Consumer Goods
- 8.6 Automotive
- 8.7 Telecommunications
- 8.8 Manufacturing
- 8.9 Others
Chapter 9 Market Estimates & Forecast, By Region, 2022 - 2035 ($ Mn)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 US
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Italy
- 9.3.5 Spain
- 9.3.6 Netherlands
- 9.3.7 Sweden
- 9.3.8 Switzerland
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.4.6 Singapore
- 9.4.7 Indonesia
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.6 MEA
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
Chapter 10 Company Profiles
- 10.1 Global players
- 10.1.1 IBM
- 10.1.2 Microsoft
- 10.1.3 Google
- 10.1.4 Amazon Web Services
- 10.1.5 SAP
- 10.1.6 Salesforce
- 10.1.7 ServiceNow
- 10.1.8 OneTrust
- 10.1.9 SAS Institute
- 10.1.10 Oracle
- 10.1.11 Collibra
- 10.1.12 Optro
- 10.2 Regional players
- 10.2.1 2021.AI
- 10.2.2 Saidot Oy
- 10.2.3 Modulos
- 10.2.4 ValidMind
- 10.2.5 NTT DATA
- 10.3 Emerging players
- 10.3.1 Credo
- 10.3.2 Holistic AI
- 10.3.3 Trustible

 AI驅動的Nudge市場規模、佔有率和成長分析:按解決方案類型、部署模式、應用、企業規模、最終用戶產業、最終用戶和地區分類-2026-2033年產業預測
 人工智慧管治全球市場規模、佔有率、趨勢和成長分析報告(2026-2034)
 人工智慧管治:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 功能商店市場預測至 2034 年—按功能類型、部署模式、組件、企業功能、應用程式、最終用戶和地區分類的全球分析
 人工智慧管治市場-2026-2032年全球市場預測
 全球人工智慧管治平台市場:按產品/服務、部署方式、功能、組織規模、應用領域和最終用戶產業分類-市場規模、產業動態、機會分析和預測(2026-2035 年)人工智慧驅動的運算管治市場預測至2034年:按管治功能、部署模式、技術、應用、最終用戶和地區分類的全球分析
 2026年全球藝術捐贈諮詢市場報告
 2026-2030年全球人工智慧倫理與管治解決方案市場
 2026-2030年全球人工智慧政策與標準市場