


 |
市場調查報告書
商品編碼
2101661
汽車USB供電系統市場機會、成長促進因素、產業趨勢分析及2026-2035年預測Automotive USB Power Delivery System Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球汽車 USB 電源傳輸系統市場預計到 2025 年將達到 20 億美元,年複合成長率為 9.7%,到 2035 年將達到 51 億美元。
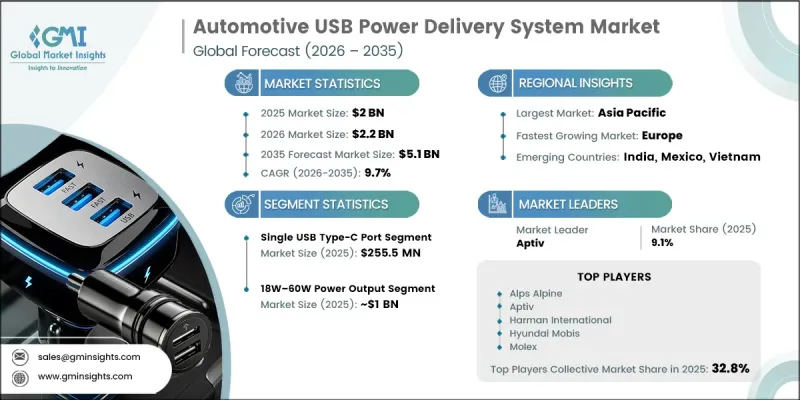
這一成長主要得益於全球向電池式電動車(BEV) 和插電混合動力汽車(PHEV) 的轉型,從而持續推動了車內高功率USB 充電架構的需求。隨著電動車在主要汽車市場的滲透率接近 20-25%,汽車製造商 (OEM) 擴大採用符合 USB Power Delivery (PD) 3.1 標準的多端口系統,這些系統每個端口可支援 60W-140W 的輸出功率,從而加速了 60W-100W 及以上高功率段的需求。電動車平台的擴展以及先進 USB PD 技術的整合是市場成長的主要驅動力。同時,消費者對車載快速充電的期望也與智慧型手機充電標準趨於一致。現代設備需要 45W-65W 的功率才能實現高效的行動快速充電。這促使一級供應商將 USB PD 控制器 IC 整合到其資訊娛樂系統架構中,從而實現多個設備穩定充電,避免熱功率限制,並提高整體車載電源分配效率。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 起始金額 | 20億美元 |
| 預測金額 | 51億美元 |
| 複合年成長率 | 9.7% |
預計到2025年,單USB Type-C介面市場規模將達到2.555億美元。這一成長反映了高階汽車和電動車架構中Type-C介面的早期應用,在這些領域,Type-C介面擴大被用作前排座椅配置中的主要充電介面。在許多設計中,有線高功率充電被用作無線充電系統的補充而非替代,這進一步提升了Type-C介面在現代車載生態系統中的重要性。
預計到 2025 年,60W–100W 功率段的市場規模將達到 2.669 億美元,到 2035 年的複合年成長率將達到 18.4%。這一成長的驅動力是 OEM 廠商在高階汽車、車載使用時間更長的電動汽車以及旨在為長途旅行提供舒適性和連接性的後座娛樂系統中率先採用中高功率USB 充電系統。
預計到2025年,北美汽車USB供電系統市場規模將達到4.59億美元,並在2026年至2035年間以10.5%的複合年成長率成長,到2035年達到12.4億美元。該地區市場成長的主要促進因素包括電動車的快速普及、每輛車USB介面密度的增加,以及電動車在共享出行、物流和商務傳輸等領域的日益廣泛應用。這些結構性因素正在推動乘用車和商用車對先進車載供電系統的持續需求。
目錄
第1章:調查方法
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 成長促進因素
- 電動車的日益普及推動了對高功率 USB PD 系統的需求。
- 消費者對車載設備的連接性和快速充電功能的需求日益成長
- 關於 USB-C 標準化的監管義務(歐盟通用充電器指令)
- 隨著車載資訊娛樂系統和ADAS系統整合度的提高,需要高頻寬的USB介面。
- 產業潛在風險與挑戰
- USB PD控制器IC和溫度控管組件成本高。
- 現有車輛中傳統USB標準相容性碎片化
- 市場機遇
- 車輛到負載 (V2L) 功能的擴展將創造對 100W 或更高功率的 USB PD 連接埠的需求。
- 新興市場對老舊車隊售後改裝的需求
- USB4 和 USB PD 3.1 的廣泛應用正在創造一個高階產品升級週期。
- 成長促進因素
- 技術與創新展望
- 最新科技趨勢
- USB Power Delivery 3.0
- 可程式電源(PPS)技術
- 12V/24V 直流-直流降壓轉換器
- 新興技術
- USB Power Delivery 3.1
- 雙向 USB 電源傳輸
- 最新科技趨勢
- 成長潛力分析
- 價格分析
- 對過去價格趨勢的分析
- 依球員類型分類的定價策略(高級球員、超值球員、成本加成球員)
- 監理情勢
- 北美洲
- 美國 - NHTSA(國家公路交通安全管理局)
- 加拿大 - ISED(創新、科學和經濟發展部)
- 歐洲
- 歐盟-歐洲委員會(EC)
- 德國 - KBA(聯邦機動車輛管理局)
- 亞太地區
- 中國工信部
- 印度 - BIS(印度標準局/運輸部)
- LATAM
- 巴西 - INMETRO
- 巴西 - ANATEL
- 中東和非洲
- 南非 - 南非標準局
- 沙烏地阿拉伯 - SASO(沙烏地阿拉伯標準、計量和品質組織)
- 北美洲
- 波特的分析
- PESTLE分析
- 貿易數據分析
- 進出口量及進口額趨勢
- 主要貿易路線及關稅的影響
- 生產能力和生產情況
- 設備產能:按地區和主要生產商分類
- 運轉率和擴張計劃
- 成本細分分析
- 專利分析
- 連接器和介面演變分析
- 汽車平台從 USB 2.0 過渡到 USB 4的藍圖
- 從 USB PD 3.0 遷移到 3.1 (EPR)
- 可靠性和失效模式分析
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 預測假設和情境分析
- 基本案例:驅動複合年成長率的關鍵宏觀經濟與產業變量
- 樂觀情境:宏觀經濟與產業的順風
- 悲觀情景:宏觀經濟放緩或產業逆風
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 排名分類標準與選擇標準
- 按銷售額、地區和創新能力分類的層級定位矩陣。
第5章 市場估算與預測:依連接器類型分類,2022-2035年
- USB Type A 連接埠 (1)
- 一個 USB Type-C 連接埠
- 組合式(A型+C型多埠)
- 其他
第6章 市場估計與預測:依產量分類,2022-2035年
- 小於18瓦
- 18W~60W
- 60W~100W
- 100瓦或以上
第7章 市場估計與預測:依應用領域分類,2022-2035年
- 主機/資訊娛樂系統整合
- 後座娛樂系統
- 後座充電器/車載充電端口
- 其他
第8章 市場估價與預測:依車輛類型分類,2022-2035年
- 搭乘用車
- 轎車
- SUV/跨界車
- 掀背車
- 其他
- 商用車輛
- LCV
- MCV
- HCV
- 摩托車
第9章 市場估價與預測:依車輛類型分類,2022-2035年
- ICE
- 電的
- 混合
第10章 市場估價與預測:依通路分類,2022-2035年
- 原廠/工廠標準配備
- 售後市場
- 線上售後市場
- 離線售後市場
第11章 市場估價與預測:按地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 荷蘭
- 瑞士
- 波蘭
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 泰國
- 越南
- 印尼
- 馬來西亞
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 智利
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第12章:公司簡介
- 世界公司
- Molex
- Aptiv
- Harman International
- Monolithic Power Systems
- Alps Alpine
- Hyundai Mobis
- Diodes Incorporated
- Panasonic
- Casco
- Texas Instruments
- LTSCT
- 當地公司
- Alfatronix
- PRO CAR
- MD ELEKTRONIK
- Wieson Automotive
- Keboda
- MinebeaMitsumi
- 新興企業
- Zhejiang Teme Science and Technology
- Hebei First Light
- Aerpro
The Global Automotive USB Power Delivery System Market was valued at USD 2 billion in 2025 and estimated to grow at a CAGR of 9.7% to reach USD 5.1 billion by 2035.
Growth is reinforced by the global shift toward battery electric vehicles (BEVs) and plug-in hybrid electric vehicles (PHEVs), which is creating sustained demand for high-output USB charging architectures within vehicle cabins. As EV penetration approaches the 20-25% range in major automotive markets, OEMs are increasingly adopting USB Power Delivery (PD) 3.1-compliant multi-port systems capable of supporting 60W-140W output per port, accelerating demand in higher wattage segments such as 60W-100W and above 100W categories. The alignment between EV platform expansion and advanced USB PD integration is a primary growth catalyst for the market. At the same time, consumer expectations for fast in-vehicle charging are converging with smartphone charging standards, where modern devices require 45W-65W for efficient fast charging during travel. This is prompting Tier-1 suppliers to embed USB PD controller ICs into infotainment architectures, enabling stable multi-device charging without thermal power limitations and improving overall cabin power distribution efficiency.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $2 Billion |
| Forecast Value | $5.1 Billion |
| CAGR | 9.7% |
The single USB Type-C port segment generated USD 255.5 million in 2025. Its growth reflects early adoption in premium vehicle platforms and electric vehicle architectures, where Type-C interfaces are increasingly used as primary charging points in front-row seating configurations. In many designs, wired high-power delivery is being complemented by wireless charging systems rather than replaced, reinforcing the relevance of Type-C deployment in modern cabin ecosystems.
The 60W-100W power output segment captured USD 266.9 million in 2025, reflecting a CAGR of 18.4% through 2035. This performance is driven by early OEM integration of mid-to-high power USB charging systems in premium vehicles, electric vehicles with extended in-cabin usage time, and enhanced rear-seat entertainment configurations designed for long-distance travel comfort and connectivity.
North America Automotive USB Power Delivery System Market reached USD 459 million in 2025 and is expected to grow at a CAGR of 10.5% through 2026-2035, reaching USD 1.24 billion by 2035. Market growth in the region is supported by rapid EV adoption, higher USB port density per vehicle, and increasing deployment of electrified fleet vehicles across ride-hailing, logistics, and commercial transport applications. These structural factors continue to reinforce demand for advanced in-vehicle power delivery systems across both passenger and commercial vehicle categories.
Key companies operating in the global automotive USB power delivery system market include Aptiv, Molex, Hyundai Mobis, Harman International, Alps Alpine, Texas Instruments, Monolithic Power Systems, Diodes Incorporated, Panasonic, Casco, LTSCT, MD ELEKTRONIK, Alfatronix, PRO CAR, Wieson Automotive, Keboda, MinebeaMitsumi, Zhejiang Teme Science and Technology, Hebei First Light, and Aerpro. Companies operating in the automotive USB power delivery system market are focusing on enhancing product performance through higher wattage output capabilities, improved thermal management, and compact integrated circuit designs. Many firms are investing in advanced USB Power Delivery controller technologies to support multi-port high-speed charging architectures in electric and connected vehicles. Strategic partnerships with automotive OEMs and Tier-1 suppliers are being used to ensure early integration into next-generation vehicle platforms. Companies are also prioritizing semiconductor innovation to improve power efficiency and reduce energy loss during high-load charging cycles.
Table of Contents
Chapter 1 Methodology
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Connector
- 2.2.3 Power Output
- 2.2.4 Application
- 2.2.5 Vehicle
- 2.2.6 Vehicle Propulsion
- 2.2.7 Distribution Channel
- 2.3 TAM analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising EV Adoption Driving Demand for High-Wattage USB PD Systems
- 3.2.1.2 Increasing Consumer Demand for In-Vehicle Device Connectivity & Fast Charging
- 3.2.1.3 Regulatory Mandates for USB-C Standardization (EU Common Charger Directive)
- 3.2.1.4 Growing Integration of Infotainment & ADAS Systems Requiring High-Bandwidth USB Interfaces
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High Cost of USB PD Controller ICs & Thermal Management Components
- 3.2.2.2 Compatibility Fragmentation Across Legacy USB Standards in Existing Vehicle Fleets
- 3.2.3 Market opportunities
- 3.2.3.1 Vehicle-to-Load (V2L) Capability Expansion Creating Demand for 100W+ USB PD Ports
- 3.2.3.2 Aftermarket Retrofit Demand in Aging Vehicle Fleets Across Emerging Markets
- 3.2.3.3 USB4 & USB PD 3.1 Adoption Creating Premium Upgrade Cycles
- 3.2.1 Growth drivers
- 3.3 Technology and innovation landscape
- 3.3.1 Current technological trends
- 3.3.1.1 USB Power Delivery 3.0
- 3.3.1.2 Programmable Power Supply (PPS) Technology
- 3.3.1.3 12V/24V DC-DC Step-Down Converters
- 3.3.2 Emerging technologies
- 3.3.2.1 USB Power Delivery 3.1
- 3.3.2.2 Bidirectional USB Power Delivery
- 3.3.1 Current technological trends
- 3.4 Growth potential analysis
- 3.5 Pricing Analysis (Driven by Primary Research)
- 3.5.1 Historical Price Trend Analysis
- 3.5.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
- 3.6 Regulatory landscape
- 3.6.1 North America
- 3.6.1.1 US - NHTSA (National Highway Traffic Safety Administration)
- 3.6.1.2 Canada - ISED (Innovation, Science and Economic Development)
- 3.6.2 Europe
- 3.6.2.1 EU - European Commission (EC)
- 3.6.2.2 Germany - KBA (Kraftfahrt-Bundesamt)
- 3.6.3 Asia Pacific
- 3.6.3.1 China - MIIT (Ministry of Industry and Information Technology)
- 3.6.3.2 India - BIS (Bureau of Indian Standards / Department of Transport)
- 3.6.4 LATAM
- 3.6.4.1 Brazil - INMETRO
- 3.6.4.2 Brazil - ANATEL
- 3.6.5 MEA
- 3.6.5.1 South Africa - South African Bureau of Standards
- 3.6.5.2 Saudi Arabia - SASO (Saudi Standards, Metrology and Quality Organization)
- 3.6.1 North America
- 3.7 Porter's analysis
- 3.8 PESTEL analysis
- 3.9 Trade Data Analysis (Driven by Paid Database)
- 3.9.1 Import/Export Volume & Value Trends
- 3.9.2 Key Trade Corridors & Tariff Impact
- 3.10 Capacity & Production Landscape (Driven by Primary Research)
- 3.10.1 Installed Capacity by Region & Key Producer
- 3.10.2 Capacity Utilization Rates & Expansion Pipelines
- 3.11 Cost breakdown analysis
- 3.12 Patent analysis (Driven by Primary Research)
- 3.13 Connector & Interface Evolution Analysis
- 3.13.1 USB 2.0 to USB4 Migration Roadmap in Automotive Platforms
- 3.13.2 USB PD 3.0 to 3.1 (EPR) Transition
- 3.14 Reliability & Failure Mode Analysis
- 3.15 Impact of AI & generative AI on the market
- 3.15.1 AI-driven disruption of existing business models
- 3.15.2 GenAI use cases & adoption roadmap by segment
- 3.15.3 Risks, limitations & regulatory considerations
- 3.16 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.16.1 Base Case- Key Macro & Industry Variables Driving CAGR
- 3.16.2 Optimistic Scenarios- Favorable macro and industry tailwinds
- 3.16.3 Pessimistic Scenario - Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 LATAM
- 4.2.5 MEA
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New product launches
- 4.5.4 Expansion plans and funding
- 4.6 Company tier benchmarking
- 4.6.1 Tier classification criteria & qualifying thresholds
- 4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates and Forecast, By Connector, 2022 - 2035 ($ Mn, Thousand Units)
- 5.1 Key trends
- 5.2 Single USB Type-A Port
- 5.3 Single USB Type-C Port
- 5.4 Combination (Type-A + Type-C Multi-Port)
- 5.5 Others
Chapter 6 Market Estimates and Forecast, By Power Output, 2022 - 2035 ($ Mn, Thousand Units)
- 6.1 Key trends
- 6.2 Up to 18W
- 6.3 18W-60W
- 6.4 60W-100W
- 6.5 Above 100W
Chapter 7 Market Estimates and Forecast, By Application, 2022 - 2035 ($ Mn, Thousand Units)
- 7.1 Key trends
- 7.2 Head Units / Infotainment Integration
- 7.3 Rear-Seat Entertainment Systems
- 7.4 Rear-Seat Chargers / Car Charger Ports
- 7.5 Others
Chapter 8 Market Estimates and Forecast, By Vehicle, 2022 - 2035 ($ Mn, Thousand Units)
- 8.1 Key trends
- 8.2 Passenger cars
- 8.2.1 Sedan
- 8.2.2 SUV & Crossover
- 8.2.3 Hatchback
- 8.2.4 Others
- 8.3 Commercial vehicles
- 8.3.1 LCV
- 8.3.2 MCV
- 8.3.3 HCV
- 8.4 Two-Wheelers
Chapter 9 Market Estimates and Forecast, By Vehicle Propulsion, 2022 - 2035 ($ Mn, Thousand Units)
- 9.1 Key trends
- 9.2 ICE
- 9.3 Electric
- 9.4 Hybrid
Chapter 10 Market Estimates and Forecast, By Distribution Channel, 2022 - 2035 ($ Mn, Thousand Units)
- 10.1 Key trends
- 10.2 OEM/Factory Installed
- 10.3 Aftermarket
- 10.3.1 Online Aftermarket
- 10.3.2 Offline Aftermarket
Chapter 11 Market Estimates & Forecast, By Region, 2022 - 2035 ($ Mn, Thousand Units)
- 11.1 Key trends
- 11.2 North America
- 11.2.1 US
- 11.2.2 Canada
- 11.3 Europe
- 11.3.1 Germany
- 11.3.2 UK
- 11.3.3 France
- 11.3.4 Italy
- 11.3.5 Spain
- 11.3.6 Netherlands
- 11.3.7 Switzerland
- 11.3.8 Poland
- 11.4 Asia Pacific
- 11.4.1 China
- 11.4.2 India
- 11.4.3 Japan
- 11.4.4 South Korea
- 11.4.5 Thailand
- 11.4.6 Vietnam
- 11.4.7 Indonesia
- 11.4.8 Malaysia
- 11.5 Latin America
- 11.5.1 Brazil
- 11.5.2 Mexico
- 11.5.3 Argentina
- 11.5.4 Chile
- 11.6 MEA
- 11.6.1 South Africa
- 11.6.2 Saudi Arabia
- 11.6.3 UAE
Chapter 12 Company Profiles
- 12.1 Global players
- 12.1.1 Molex
- 12.1.2 Aptiv
- 12.1.3 Harman International
- 12.1.4 Monolithic Power Systems
- 12.1.5 Alps Alpine
- 12.1.6 Hyundai Mobis
- 12.1.7 Diodes Incorporated
- 12.1.8 Panasonic
- 12.1.9 Casco
- 12.1.10 Texas Instruments
- 12.1.11 LTSCT
- 12.2 Regional players
- 12.2.1 Alfatronix
- 12.2.2 PRO CAR
- 12.2.3 MD ELEKTRONIK
- 12.2.4 Wieson Automotive
- 12.2.5 Keboda
- 12.2.6 MinebeaMitsumi
- 12.3 Emerging players
- 12.3.1 Zhejiang Teme Science and Technology
- 12.3.2 Hebei First Light
- 12.3.3 Aerpro

 汽車USB供電系統全球市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 2026年全球數據卡和USB加密狗市場報告2026年全球手排汽車充電器市場報告2026年全球資料產品市場中心市場報告
 USB車用充電器市場機會、成長要素、產業趨勢分析及2026年至2035年預測
 汽車USB供電系統市場規模、佔有率和成長分析(按資訊類型、應用、車輛類型、分銷管道和地區分類)-產業預測(2026-2033年)
 汽車USB供電系統市場-全球產業規模、佔有率、趨勢、機會和預測,按類型、應用、分銷管道、地區和競爭格局分類,2020-2030年預測汽車香氛輸送系統市場機會、成長促進因素、產業趨勢分析及預測(2025-2034年)
 汽車USB充電模組:全球市佔率及排名、總收入及需求預測(2025-2031年)可攜式交流充電槍:全球市場佔有率和排名、總收入和需求預測(2025-2031 年)