

 |
市場調查報告書
商品編碼
2083360
物聯網感測器市場機會、成長要素、產業趨勢分析及2026-2035年預測IOT Sensors Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球物聯網感測器市場價值 239 億美元,預計將以 37.6% 的複合年成長率成長,到 2035 年達到 5,492 億美元。
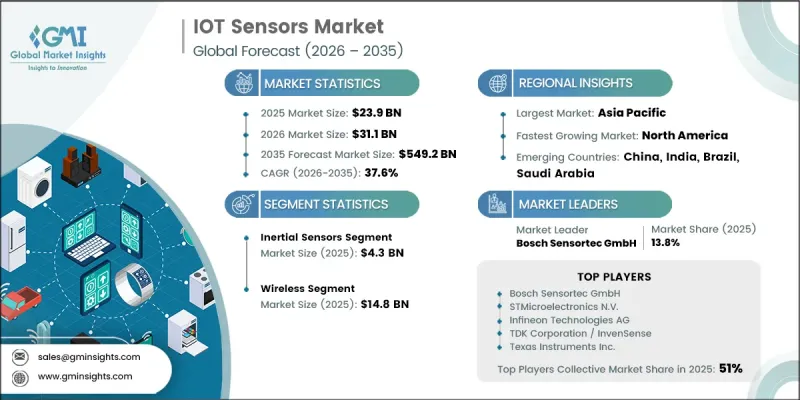
物聯網感測器市場正經歷快速成長,這主要得益於跨產業數位轉型的快速推進和互聯技術的廣泛應用。工業4.0框架的日益普及正在將製造環境轉變為高度自動化、數據驅動的生態系統。智慧城市基礎設施專案的擴展進一步推動了感測器在交通運輸、公共產業和公共安全系統中的部署。預測性維護解決方案的廣泛應用使企業能夠減少運作並提高資產效率。對互聯醫療應用日益成長的需求也透過實現即時患者監測和遠距離診斷來推動市場擴張。全球連網型設備數量的持續成長進一步凸顯了物聯網感測器作為核心基礎技術的重要性,它支援工業、商業和公共部門的即時數據採集、自動化和智慧決策。雲端運算、邊緣分析和人工智慧(AI)技術的進步正在進一步提升物聯網感測器網路的功能和擴充性,從而促進其與複雜數位生態系統的整合。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 239億美元 |
| 預計金額 | 5492億美元 |
| 複合年成長率 | 37.6% |
預計2025年,慣性感測器市場規模將達到43億美元,並持續維持其在物聯網感測器市場的強勁地位。此領域涵蓋加速計、陀螺儀和磁力計等感測器,廣泛應用於家用電子電器、工業系統、汽車平台、穿戴式裝置和無人機等領域。這些感測器能夠實現運動追蹤、導航、方向檢測和資產監控等關鍵功能。工業自動化和汽車系統中基於MEMS的慣性技術的日益普及,進一步鞏固了該領域的市場地位。
預計到2025年,無線通訊市場規模將達到148億美元。這一市場主導地位主要得益於智慧家庭、工業IoT生態系統、連線健診設備、智慧基礎設施專案以及穿戴式技術的快速發展。無線感測器系統具有成本效益高、安裝柔軟性以及與雲端運算和邊緣運算平台無縫整合等優勢。 Wi-Fi、低功耗藍牙、Zigbee、LoRaWAN、NB-IoT和5G等連接技術的日益普及,進一步加速了無線技術在多個應用領域的應用。
預計到2025年,北美物聯網感測器市場佔有率將達到25.5%,這主要得益於工業自動化技術的早期應用以及關鍵產業對物聯網解決方案的積極部署。該地區正受益於製造業、醫療保健、交通運輸和公共產業領域對智慧基礎設施和數位轉型的巨額投資。由半導體製造商、技術供應商和雲端服務公司組成的強大生態系統進一步推動了區域成長,並加速了先進感測技術的應用。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 智慧製造與工業4.0簡介
- 智慧城市基礎設施的擴展
- 擴大預測性維護解決方案的應用
- 互聯醫療和遠端患者監護的成長
- 全球物聯網連接設備數量激增
- 產業潛在風險與挑戰
- 資料安全和隱私問題
- 互通性和連接性挑戰
- 市場機遇
- 人工智慧賦能的智慧感測器與邊緣運算
- 工業IoT(IIoT) 和智慧基礎設施的擴展
- 促進因素
- 成長潛力分析
- 價格分析[刊登於第32頁]
- 對過去價格趨勢的分析
- 依球員類型分類的定價策略(高級球員、超值球員、成本加成球員)
- 監理情勢
- 波特的分析
- PESTLE分析
- 貿易數據分析
- 進出口量及進口額趨勢
- 主要貿易路線及關稅的影響
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 生產能力和生產情況
- 主要製造商的生產能力
- 運轉率和擴張計劃
第4章 競爭情勢
- 介紹
- 按地區
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 市場集中度分析
- 按地區
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 排名分類標準與遴選標準
- 按銷售額、地區和創新能力分類的層級定位矩陣。
第5章 市場估算與預測:依感測器類型分類,2022-2035年
- 溫度感測器
- 壓力感測器
- 濕度感測器
- 流量感測器
- 慣性感測器(加速計、陀螺儀、磁力計)
- 影像感測器
- 觸摸感應器
- 接近感測器
- 聲學和超音波感測器
- 氣體和化學感測器
- 其他
第6章 市場估價與預測:依網路類型分類,2022-2035年
- 有線
- 無線的
第7章 市場估計與預測:依最終用途產業分類,2022-2035年
- 工業和製造業
- 汽車和運輸業
- 醫療保健和醫療設備
- 家用電子電器和穿戴式裝置
- 智慧建築(住宅、商業和公共設施)
- 農業和環境監測
- 能源公用事業
- 智慧城市與公共基礎設施
- 零售、倉儲和物流
第8章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第9章:公司簡介
- 全球主要公司
- Bosch Sensortec GmbH
- STMicroelectronics NV
- Infineon Technologies AG
- Texas Instruments Inc.
- TDK Corporation/InvenSense
- 該地區的主要公司
- 北美洲
- Analog Devices, Inc.(ADI)
- Vishay Intertechnology Inc.
- MEMSIC Semiconductor Co., Ltd.
- 亞太地區
- Murata Manufacturing Co., Ltd.
- ROHM Co., Ltd.
- Seiko Epson Corporation
- Panasonic Corporation
- 歐洲
- Sensirion AG
- Melexis NV
- 北美洲
- 小眾玩家/顛覆者
- PixArt Imaging Inc.
The Global IoT Sensors Market was valued at USD 23.9 billion and is estimated to grow at a CAGR of 37.6% to reach USD 549.2 billion by 2035.
The IoT sensors market is witnessing exponential growth driven by the rapid acceleration of digital transformation across industries and the widespread integration of connected technologies. Increasing adoption of Industry 4.0 frameworks is transforming manufacturing environments into highly automated and data-driven ecosystems. Expanding smart city infrastructure projects are further boosting sensor deployment across transportation, utilities, and public safety systems. The growing use of predictive maintenance solutions is enabling enterprises to reduce operational downtime and improve asset efficiency. Rising demand for connected healthcare applications is also strengthening market expansion by enabling real-time patient monitoring and remote diagnostics. The continuous increase in connected devices globally is reinforcing the importance of IoT sensors as a core enabling technology for real-time data collection, automation, and intelligent decision-making across industrial, commercial, and public sectors. Advancements in cloud computing, edge analytics, and artificial intelligence are further enhancing the functionality and scalability of IoT sensor networks, supporting their integration into complex digital ecosystems.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $23.9 Billion |
| Forecast Value | $549.2 Billion |
| CAGR | 37.6% |
The inertial sensors segment accounted for USD 4.3 billion in 2025, maintaining a strong position within the IoT sensors market. This segment includes accelerometers, gyroscopes, and magnetometers that are widely used across consumer electronics, industrial systems, automotive platforms, wearables, and drones. These sensors enable critical functions such as motion tracking, navigation, orientation detection, and asset monitoring. Growing adoption of MEMS-based inertial technologies in industrial automation and automotive systems continues to strengthen the segment's market presence.
The wireless segment captured USD 14.8 billion in 2025. This dominance is supported by the rapid expansion of smart homes, industrial IoT ecosystems, connected healthcare devices, smart infrastructure projects, and wearable technologies. Wireless sensor systems offer cost efficiency, installation flexibility, and seamless integration with cloud and edge computing platforms. Increasing deployment of connectivity technologies such as Wi-Fi, Bluetooth Low Energy, Zigbee, LoRaWAN, NB-IoT, and 5G is further accelerating adoption across multiple application areas.
North America IoT Sensors Market held 25.5% share in 2025, driven by early adoption of industrial automation technologies and strong implementation of IoT-enabled solutions across key industries. The region benefits from significant investments in smart infrastructure and digital transformation initiatives across manufacturing, healthcare, transportation, and utilities. A strong ecosystem of semiconductor manufacturers, technology providers, and cloud service companies is further supporting regional growth and accelerating the adoption of advanced sensing technologies.
Major companies operating in the global IoT sensors market include STMicroelectronics N.V., Bosch Sensortec GmbH, Texas Instruments Inc., Infineon Technologies AG, Analog Devices, Inc. (ADI), Murata Manufacturing Co., Ltd., TDK Corporation / InvenSense, ROHM Co., Ltd., Sensirion AG, Melexis NV, Vishay Intertechnology Inc., Panasonic Corporation, PixArt Imaging Inc., Seiko Epson Corporation, and MEMSIC Semiconductor Co., Ltd. Companies operating in the IoT sensors market are strengthening their market position through continuous innovation in sensor miniaturization, energy efficiency, and multi-functional integration. Market participants are increasingly investing in MEMS technology advancements and next-generation sensing platforms to enhance accuracy, durability, and performance across diverse applications. Strategic partnerships with semiconductor firms, cloud service providers, and industrial automation companies are enabling faster integration of sensor data into advanced analytics ecosystems. Companies are also expanding production capacities to support rising demand from automotive, industrial, and consumer electronics sectors.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Sensor type trends
- 2.2.2 Network type trends
- 2.2.3 End-use trends
- 2.2.4 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Adoption of Smart Manufacturing and Industry 4.0
- 3.2.1.2 Expansion of Smart City Infrastructure
- 3.2.1.3 Rising Adoption of Predictive Maintenance Solutions
- 3.2.1.4 Growth of Connected Healthcare and Remote Patient Monitoring
- 3.2.1.5 Rapid Increase in Connected IoT Devices Worldwide
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 Data Security and Privacy Concerns
- 3.2.2.2 Interoperability and Connectivity Challenges
- 3.2.3 Market opportunities
- 3.2.3.1 AI-Enabled Smart Sensors and Edge Computing
- 3.2.3.2 Expansion of Industrial IoT (IIoT) and Smart Infrastructure
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Pricing Analysis (Driven by Primary Research) [Representation on page no. 32]
- 3.4.1 Historical Price Trend Analysis
- 3.4.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
- 3.5 Regulatory landscape
- 3.5.1 North America
- 3.5.2 Europe
- 3.5.3 Asia Pacific
- 3.5.4 Latin America
- 3.5.5 Middle East & Africa
- 3.6 Porter's analysis
- 3.7 PESTEL analysis
- 3.8 Trade Data Analysis (Based on Paid Database)
- 3.8.1 Import/Export Volume & Value Trends
- 3.8.2 Key Trade Corridors & Tariff Impact
- 3.9 Impact of AI & Generative AI on the Market (Driven by Primary Research)
- 3.9.1 AI-Driven Disruption of Existing Business Models
- 3.9.2 GenAI Use Cases & Adoption Roadmap by Segment
- 3.10 Capacity & Production Landscape (Driven by Primary Research)
- 3.10.1 Production Capacity by Key Producer
- 3.10.2 Capacity Utilization Rates & Expansion Pipelines
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.1.1 By Region
- 4.1.1.1 North America
- 4.1.1.2 Europe
- 4.1.1.3 Asia-Pacific
- 4.1.1.4 Latin America
- 4.1.1.5 Middle East and Africa
- 4.1.2 Market Concentration Analysis
- 4.1.1 By Region
- 4.2 Competitive analysis of major market players
- 4.3 Competitive positioning matrix
- 4.4 Key developments
- 4.4.1 Mergers & acquisitions
- 4.4.2 Partnerships & collaborations
- 4.4.3 New product launches
- 4.4.4 Expansion plans and funding
- 4.5 Company tier benchmarking
- 4.5.1 Tier classification criteria & qualifying thresholds
- 4.5.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates and Forecast, By Sensor Type, 2022 - 2035 (USD Billion)
- 5.1 Key trends
- 5.2 Temperature Sensors
- 5.3 Pressure Sensors
- 5.4 Humidity Sensors
- 5.5 Flow Sensors
- 5.6 Inertial Sensors (Accelerometers, Gyroscopes & Magnetometers)
- 5.7 Image Sensors
- 5.8 Touch Sensors
- 5.9 Proximity Sensors
- 5.10 Acoustic & Ultrasonic Sensors
- 5.11 Gas & Chemical Sensors
- 5.12 Others
Chapter 6 Market Estimates and Forecast, By Network Type, 2022 - 2035 (USD Billion)
- 6.1 Key trends
- 6.2 Wired
- 6.3 Wireless
Chapter 7 Market Estimates and Forecast, By End-Use Industry, 2022 - 2035 (USD Billion)
- 7.1 Key trends
- 7.2 Industrial & Manufacturing
- 7.3 Automotive & Transportation
- 7.4 Healthcare & Medical Devices
- 7.5 Consumer Electronics & Wearables
- 7.6 Smart Buildings (Residential, Commercial & Institutional)
- 7.7 Agriculture & Environmental Monitoring
- 7.8 Energy & Utilities
- 7.9 Smart Cities & Public Infrastructure
- 7.10 Retail, Warehousing & Logistics
Chapter 8 Market Estimates and Forecast, By Region, 2022 - 2035 (USD Billion)
- 8.1 Key trends
- 8.2 North America
- 8.2.1 U.S.
- 8.2.2 Canada
- 8.3 Europe
- 8.3.1 Germany
- 8.3.2 UK
- 8.3.3 France
- 8.3.4 Spain
- 8.3.5 Italy
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 India
- 8.4.3 Japan
- 8.4.4 Australia
- 8.4.5 South Korea
- 8.5 Latin America
- 8.5.1 Brazil
- 8.5.2 Mexico
- 8.5.3 Argentina
- 8.6 Middle East and Africa
- 8.6.1 South Africa
- 8.6.2 Saudi Arabia
- 8.6.3 UAE
Chapter 9 Company Profiles
- 9.1 Global Key Players
- 9.1.1 Bosch Sensortec GmbH
- 9.1.2 STMicroelectronics N.V.
- 9.1.3 Infineon Technologies AG
- 9.1.4 Texas Instruments Inc.
- 9.1.5 TDK Corporation / InvenSense
- 9.2 Regional key players
- 9.2.1 North America
- 9.2.1.1 Analog Devices, Inc. (ADI)
- 9.2.1.2 Vishay Intertechnology Inc.
- 9.2.1.3 MEMSIC Semiconductor Co., Ltd.
- 9.2.2 Asia Pacific
- 9.2.2.1 Murata Manufacturing Co., Ltd.
- 9.2.2.2 ROHM Co., Ltd.
- 9.2.2.3 Seiko Epson Corporation
- 9.2.2.4 Panasonic Corporation
- 9.2.3 Europe
- 9.2.3.1 Sensirion AG
- 9.2.3.2 Melexis NV
- 9.2.1 North America
- 9.3 Niche Players/Disruptors
- 9.3.1 PixArt Imaging Inc.

 全球物聯網感測器市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 物聯網感測器:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 物聯網感測器市場-2026-2032年全球市場預測
 物聯網感測器模組市場報告:趨勢、預測和競爭分析(至2035年)
 全球物聯網感測器市場(至2035年):產業趨勢與預測
 物聯網感測器市場分析與預測(至2035年):類型、產品類型、技術、組件、應用、最終用戶、功能、安裝模式、解決方案
 物聯網感測器市場:按感測器類型、網路技術和地區分類
 日本物聯網感測器市場規模、佔有率、趨勢和預測:按類型、應用和地區分類,2026-2034年
 2026年全球物聯網感測器市場報告
 無線物聯網感測器市場 - 全球產業規模、佔有率、趨勢、機會及預測(按組件、類型、技術、垂直產業、地區和競爭格局分類,2021-2031年)