


 |
市場調查報告書
商品編碼
2083254
氣管市場商機、成長要素、產業趨勢分析及2026-2035年預測。Air Hoses Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

預計到 2025 年,全球氣管市場規模將達到 25 億美元,並預計以 6.7% 的複合年成長率成長,到 2035 年達到 48 億美元。
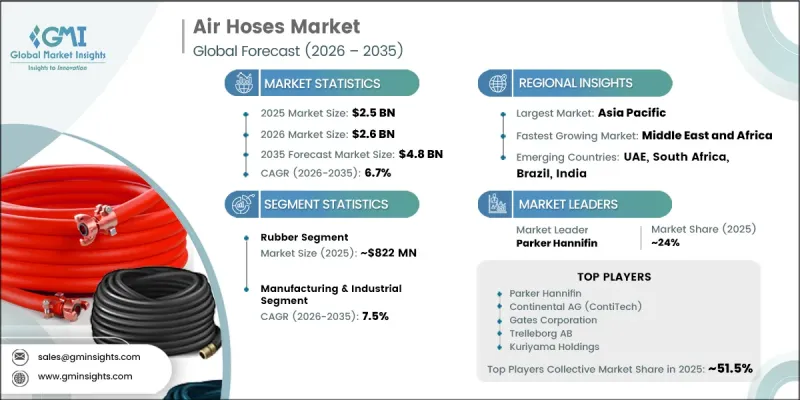
受工業活動擴張和各終端用戶產業對壓縮空氣系統日益成長的依賴性推動,氣管市場正經歷穩定持續的成長。製造業、汽車業、建築業、採礦業和維護業對氣壓工具和設備的日益普及,推動了對耐用、高性能氣管解決方案的需求。生產環境的自動化進一步加速了市場成長,因為壓縮空氣管道系統仍然是氣壓機械和組裝作業的重要動力來源。機器人技術和先進製造技術的興起顯著增加了對高效供氣基礎設施的需求,直接促進了氣管的消費。此外,對工業基礎設施和設施擴建的持續投資增加了壓縮機的安裝數量,進一步提升了對氣管的需求。隨著各行業現代化進程的推進以及自動化在核心運營中的不斷融合,在效率提升和工業生產率提高的支撐下,氣管市場預計將保持長期穩定的成長。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 初始市場規模 | 25億美元 |
| 預測金額 | 48億美元 |
| 複合年成長率 | 6.7% |
預計到2025年,橡膠製品市場銷售額將達到8.22億美元,並在2035年之前以5.7%的複合年成長率成長,這主要得益於其卓越的耐用性、柔軟性和成本效益,使其在整體中得到廣泛應用。橡膠製品能夠承受高壓、耐磨損,並在嚴苛的運作條件下保持性能,使其成為製造工廠、建築工地和礦業設施的理想選擇。此外,橡膠軟管在各種溫度條件下都能提供可靠的效能,確保在不同地區和工業環境中都能穩定運作。
預計到2025年,製造業和工業領域將佔據33.6%的市場佔有率,並在2035年之前以7.5%的複合年成長率成長。該領域是推動市場成長的主要力量,因為壓縮空氣系統是大多數生產設施的必備設備。氣管廣泛應用於氣壓工具、自動化機械、組裝和物料輸送系統,已成為現代工業活動中不可或缺的組成部分。隨著自動化、智慧製造系統和高效生產技術的進步,整個工業環境對可靠的空氣管道解決方案的需求正在進一步成長。
預計到2025年,北美氣管市場佔有率將達到28.5%,這主要得益於其先進的工業基礎和關鍵產業的高度自動化。該地區製造業、汽車業、航太、石油天然氣業和建築業的需求持續強勁,氣壓系統在這些產業中發揮著至關重要的作用。氣管廣泛應用於對可靠性和安全性要求極高的維護工作以及嚴苛的工業應用。製造設施的持續現代化改造和老舊氣動系統的更新換代,將繼續推動全部區域市場的穩定成長。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 每個階段增加的價值
- 影響價值鏈的因素
- 影響產業的因素
- 促進因素
- 工業自動化和機器人技術的加速整合正在推動對氣壓元件的需求。
- 全球製造業基礎建設投資增加
- 嚴格的職業安全法規要求使用高性能軟管組件。
- 汽車和建築業氣動工具的應用日益廣泛。
- 產業潛在風險與挑戰
- 原料成本(橡膠、聚合物、鋼絲)的劇烈波動對利潤率造成了壓力。
- 電動和電池驅動工具取代傳統工具的威脅。
- 由於產品使用壽命長、耐用性高,更換週期也越來越長。
- 機會
- 市場對內建壓力感測器的智慧物聯網氣管的需求日益成長。
- 對環保、可回收、不含PVC的軟管材料的需求日益成長。
- 拓展電子商務和線上分銷管道,以直接觸達消費者。
- 新興市場農業和食品加工領域尚未開發的需求
- 促進因素
- 成長潛力分析
- 供應鏈分析
- 原料採購與價格波動(橡膠、聚合物、鋼鐵)
- 製造業集中化與外包的趨勢
- 供應鏈中斷風險評估
- 未來市場趨勢
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 監理情勢
- 標準和合規要求
- 區域監理框架
- 認證標準
- 貿易數據分析
- 進出口量及進口額趨勢
- 主要貿易路線及關稅的影響
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 價格分析
- 對過去價格趨勢的分析
- 依球員類型分類的定價策略(高級球員、超值球員、成本加成球員)
- 波特的分析
- PESTLE分析
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 企業矩陣分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃
第5章 市場估算與預測:依材料類型分類,2022-2035年
- 主要趨勢
- 橡膠氣管
- EPDM橡膠
- SBR橡膠
- 丁腈橡膠(NBR)
- PVC氣管
- 標準PVC
- 增強型聚氯乙烯
- 聚氨酯(PU)氣管
- 標準聚氨酯
- 優質PU(彈簧型/伸縮型)
- 混合氣管
- 其他材料(矽膠、TPE、特殊複合材料)
第6章 市場估計與預測:依壓力等級分類,2022-2035年
- 主要趨勢
- 低壓(10 巴或以下)
- 中壓(10-20 巴)
- 高壓(20 巴或以上)
第7章 市場估計與預測:依價格區間分類,2022-2035年
- 主要趨勢
- 經濟
- 中階
- 優質的
第8章 市場估算與預測:依直徑分類,2022-2035年
- 主要趨勢
- 小於 1/4 英寸
- 1/4英寸至1/2英寸
- 1/2英寸至1英寸
- 超過1英寸
第9章 市場估計與預測:基於強化法,2022-2035年
- 主要趨勢
- 單層(未加固)
- 雙層/編織
- 螺旋/鋼絲增強型
第10章 市場估價與預測:依最終用戶產業分類,2022-2035年
- 主要趨勢
- 製造業和工業
- 通用製造和組裝
- 電子和半導體組裝
- 紡織服裝製造
- 車
- OEM組裝廠
- 售後維修店
- 建造
- 住宅
- 商業和基礎設施項目
- 石油和天然氣
- 上游部門(探勘和鑽井)
- 下游產業(煉油/加工)
- 礦業
- 農業
- 食品/飲料
- 其他(船舶、航太、化學加工)
第11章 市場估價與預測:依通路分類,2022-2035年
- 主要趨勢
- 工業經銷商/直銷
- OEM商品搭售銷售給重點客戶
- MRO(維護、修理和營運)採購
- 零售(線下)
- 金屬製品和家居裝修商店
- 專業工具設備零售商
- 汽車售後市場鏈
- 電子商務(線上)
- 第三方市場(Amazon、阿里巴巴、Indiamart)
- 製造商(面向消費者的數位平台)
第12章 市場估計與預測:依地區分類,2022-2035年
- 主要趨勢
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 法國
- 英國
- 義大利
- 西班牙
- 亞太地區
- 中國
- 日本
- 印度
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 沙烏地阿拉伯
- UAE
- 南非
第13章:公司簡介
- Parker Hannifin Corporation
- Gates Corporation
- Continental AG(ContiTech)
- Trelleborg AB
- Kuriyama Holdings Corporation
- Coilhose Pneumatics
- Legacy Manufacturing Co.(Flexzilla(R))
- Prevost SAS
- Milton Industries Inc.
- Semperit AG
- Toyox Co., Ltd.
- Novaflex Group
- Alfagomma SpA
- Festo SE & Co. KG
- SMC Corporation
- Sumitomo Riko Hosetex, Ltd.
- Dayco
- Eaton Corporation
- Dixon Valve & Coupling Company
- Teknor Apex(Apex Hose Division)
- Kanaflex Corporation
- Nitta Corporation
The Global Air Hoses Market was valued at USD 2.5 billion in 2025 and is estimated to grow at a CAGR of 6.7% to reach USD 4.8 billion by 2035.
The air hoses market is experiencing steady and sustained growth driven by the expansion of industrial operations and the increasing reliance on compressed air systems across multiple end-use sectors. Growing adoption of pneumatic tools and equipment in manufacturing, automotive, construction, mining, and maintenance applications is reinforcing demand for durable and high-performance air hose solutions. Automation in production environments is further strengthening market growth, as compressed air distribution systems remain essential for powering pneumatic machinery and assembly operations. The rise of robotics and advanced manufacturing technologies has significantly increased the need for efficient air delivery infrastructure, directly supporting air hose consumption. In addition, ongoing investments in industrial infrastructure and facility expansion are contributing to higher compressor installations, which further drives demand for air hoses. As industries continue to modernize and integrate automation into core operations, the air hoses market is expected to maintain stable long-term growth supported by efficiency requirements and industrial productivity improvements.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $2.5 Billion |
| Forecast Value | $4.8 Billion |
| CAGR | 6.7% |
The rubber segment generated USD 822 million in 2025 and is projected to grow at a CAGR of 5.7% through 2035, owing to its strong durability, flexibility, and cost-effectiveness across industrial applications. Its ability to withstand high-pressure conditions, resist abrasion, and maintain performance under demanding operating environments makes it highly suitable for use in manufacturing plants, construction activities, and mining operations. In addition, rubber hoses offer reliable performance across varying temperature conditions, enabling consistent functionality across different geographic regions and industrial settings.
The manufacturing and industrial segment accounted for 33.6% share in 2025 and is expected to grow at a CAGR of 7.5% through 2035. This segment leads the market because compressed air systems are a fundamental utility across most production facilities. Air hoses are extensively used in pneumatic tools, automated machinery, assembly lines, and material handling systems, making them an essential component of modern industrial operations. Increasing adoption of automation, smart manufacturing systems, and high-efficiency production technologies is further driving demand for reliable air distribution solutions across industrial environments.
North America Air Hoses Market held 28.5% share in 2025, supported by its advanced industrial base and high level of automation across key sectors. The region continues to demonstrate strong demand across manufacturing, automotive, aerospace, oil and gas, and construction industries, where pneumatic systems play a vital operational role. Air hoses are widely used in maintenance activities and heavy-duty industrial applications that require high reliability and safety performance. Ongoing modernization of manufacturing facilities and replacement of outdated pneumatic systems continue to support steady market growth across the region.
Major companies operating in the global air hoses market include Festo SE & Co. KG, Eaton Corporation, Trelleborg AB, Gates Corporation, Parker Hannifin Corporation, Kuriyama Holdings Corporation, Alfagomma S.p.A., Continental AG (ContiTech), SMC Corporation, Novaflex Group, Milton Industries Inc., Semperit AG, Dixon Valve & Coupling Company, Toyox Co., Ltd., Prevost SAS, Legacy Manufacturing Co. (Flexzilla(R)), Kanaflex Corporation, Sumitomo Riko Hosetex, Ltd., Coilhose Pneumatics, Nitta Corporation, Teknor Apex (Apex Hose Division), and Dayco. Companies operating in the air hoses market are strengthening their competitive position by investing in advanced material technologies, high-performance elastomer development, and enhanced product durability to meet demanding industrial requirements. Many manufacturers are expanding their production capacities and optimizing supply chains to support rising global demand. Strategic partnerships with industrial equipment providers and automation solution companies are helping broaden application reach and improve market penetration. Businesses are also focusing on product innovation, including lightweight designs, higher pressure resistance, and improved flexibility to enhance operational efficiency.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Region
- 2.2.2 Material Type
- 2.2.3 Pressure Rating
- 2.2.4 Pricing Range
- 2.2.5 Diameter
- 2.2.6 Reinforcement Type
- 2.2.7 End-user Industry
- 2.2.8 Distribution channel
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Accelerating industrial automation & robotics integration driving pneumatic component demand
- 3.2.1.2 Rising global manufacturing infrastructure investment
- 3.2.1.3 Stringent workplace safety regulations mandating high-performance hose assemblies
- 3.2.1.4 Growing adoption of air-powered tools in automotive & construction sectors
- 3.2.2 Industry pitfalls & challenges
- 3.2.2.1 High volatility in raw material costs (rubber, polymers, steel wire) squeezing margins
- 3.2.2.2 Threat of substitution from all-electric & battery-powered tools
- 3.2.2.3 Long product lifecycles & high durability elongating replacement cycles
- 3.2.3 Opportunities
- 3.2.3.1 Growing demand for smart & IoT-enabled air hoses with embedded pressure sensors
- 3.2.3.2 Rising preference for eco-friendly, recyclable & PVC-free hose materials
- 3.2.3.3 Expanding e-commerce & online distribution channels for direct-to-consumer reach
- 3.2.3.4 Untapped demand in agriculture & food processing sectors in emerging markets
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Supply Chain Analysis
- 3.4.1 Raw material sourcing & price volatility (rubber, polymers, steel)
- 3.4.2 Manufacturing concentration & outsourcing trends
- 3.4.3 Supply chain disruption risk assessment
- 3.5 Future market trends
- 3.6 Technology and innovation landscape
- 3.6.1 Current technological trends
- 3.6.2 Emerging technologies
- 3.7 Regulatory landscape
- 3.7.1 Standards and compliance requirements
- 3.7.2 Regional regulatory frameworks
- 3.7.3 Certification standards
- 3.8 Trade data analysis (HS Code - 4009.12)
- 3.8.1 Import/Export Volume & Value Trends (Driven by Primary Research)
- 3.8.2 Key Trade Corridors & Tariff Impact (Driven by Primary Research)
- 3.9 Impact of AI & generative AI on the market
- 3.9.1 AI-Driven Disruption of Existing Business Models
- 3.9.2 GenAI Use Cases & Adoption Roadmap by Segment
- 3.9.3 Risks, Limitations & Regulatory Considerations
- 3.10 Pricing Analysis
- 3.11 Historical Price Trend Analysis (Driven by Primary Research)
- 3.12 Pricing Strategy by Player Type (Premium / Value / Cost-plus) (Driven by Primary Research)
- 3.13 Porter's analysis
- 3.14 PESTEL analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates & Forecast, By Material Type, 2022 - 2035, (USD Billion) (Million Units)
- 5.1 Key Trends
- 5.2 Rubber Air Hoses
- 5.2.1 EPDM Rubber
- 5.2.2 SBR Rubber
- 5.2.3 NBR (Nitrile) Rubber
- 5.3 PVC Air Hoses
- 5.3.1 Standard PVC
- 5.3.2 Reinforced PVC
- 5.4 Polyurethane (PU) Air Hoses
- 5.4.1 Standard PU
- 5.4.2 Premium PU (Coiled / Retractable)
- 5.5 Hybrid Air Hoses
- 5.6 Others (Silicone, TPE, Specialty Composites)
Chapter 6 Market Estimates & Forecast, By Pressure Rating, 2022 - 2035, (USD Billion) (Million Units)
- 6.1 Key Trends
- 6.2 Low Pressure (Up to 10 bar)
- 6.3 Medium Pressure (10-20 bar)
- 6.4 High Pressure (Above 20 bar)
Chapter 7 Market Estimates & Forecast, By Price Range, 2022 - 2035, (USD Billion) (Million Units)
- 7.1 Key Trends
- 7.2 Economy
- 7.3 Mid-Range
- 7.4 Premium
Chapter 8 Market Estimates & Forecast, By Diameter, 2022 - 2035, (USD Billion) (Million Units)
- 8.1 Key Trends
- 8.2 Less than 1/4 inch
- 8.3 1/4 inch to 1/2 inch
- 8.4 1/2 inch to 1 inch
- 8.5 Greater than 1 inch
Chapter 9 Market Estimates & Forecast, By Reinforcement Type, 2022 - 2035, (USD Billion) (Million Units)
- 9.1 Key Trends
- 9.2 Single Layer (Unreinforced)
- 9.3 Double Layer / Braided
- 9.4 Spiral / Wire Reinforced
Chapter 10 Market Estimates & Forecast, By End-user Industry, 2022 - 2035, (USD Billion) (Million Units)
- 10.1 Key Trends
- 10.2 Manufacturing & Industrial
- 10.2.1 General Manufacturing & Assembly Lines
- 10.2.2 Electronics & Semiconductor Assembly
- 10.2.3 Textile & Apparel Manufacturing
- 10.3 Automotive
- 10.3.1 OEM Assembly Plants
- 10.3.2 Aftermarket Repair Workshops
- 10.4 Construction
- 10.4.1 Residential Construction
- 10.4.2 Commercial & Infrastructure Projects
- 10.5 Oil & Gas
- 10.5.1 Upstream (Exploration & Drilling)
- 10.5.2 Downstream (Refining & Processing)
- 10.6 Mining
- 10.7 Agriculture
- 10.8 Food & Beverage
- 10.9 Others (Marine, Aerospace, Chemical Processing)
Chapter 11 Market Estimates & Forecast, By Distribution Channel, 2022 - 2035, (USD Billion) (Million Units)
- 11.1 Key Trends
- 11.2 Industrial Distributors / Direct Sales
- 11.2.1 OEM Bundling & Key Account Sales
- 11.2.2 MRO (Maintenance, Repair & Operations) Procurement
- 11.3 Retail (Offline)
- 11.3.1 Hardware & Home Improvement Stores
- 11.3.2 Specialty Tool & Equipment Retailers
- 11.3.3 Automotive Aftermarket Chains
- 11.4 E-Commerce (Online)
- 11.4.1 Third-Party Marketplaces (Amazon, Alibaba, Indiamart)
- 11.4.2 Manufacturer (Direct-to-Consumer Digital Platforms)
Chapter 12 Market Estimates & Forecast, By Region, 2022 - 2035, (USD Billion) (Million Units)
- 12.1 Key Trends
- 12.2 North America
- 12.2.1 U.S.
- 12.2.2 Canada
- 12.3 Europe
- 12.3.1 Germany
- 12.3.2 France
- 12.3.3 UK
- 12.3.4 Italy
- 12.3.5 Spain
- 12.4 Asia Pacific
- 12.4.1 China
- 12.4.2 Japan
- 12.4.3 India
- 12.4.4 Australia
- 12.4.5 South Korea
- 12.5 Latin America
- 12.5.1 Brazil
- 12.5.2 Mexico
- 12.5.3 Argentina
- 12.6 MEA
- 12.6.1 Saudi Arabia
- 12.6.2 UAE
- 12.6.3 South Africa
Chapter 13 Company Profiles
- 13.1 Parker Hannifin Corporation
- 13.2 Gates Corporation
- 13.3 Continental AG (ContiTech)
- 13.4 Trelleborg AB
- 13.5 Kuriyama Holdings Corporation
- 13.6 Coilhose Pneumatics
- 13.7 Legacy Manufacturing Co. (Flexzilla®)
- 13.8 Prevost SAS
- 13.9 Milton Industries Inc.
- 13.10 Semperit AG
- 13.11 Toyox Co., Ltd.
- 13.12 Novaflex Group
- 13.13 Alfagomma S.p.A.
- 13.14 Festo SE & Co. KG
- 13.15 SMC Corporation
- 13.16 Sumitomo Riko Hosetex, Ltd.
- 13.17 Dayco
- 13.18 Eaton Corporation
- 13.19 Dixon Valve & Coupling Company
- 13.20 Teknor Apex (Apex Hose Division)
- 13.21 Kanaflex Corporation
- 13.22 Nitta Corporation

 全球氣管市場規模、佔有率、趨勢及成長分析報告(2026-2034)
 大型航空貨運市場:2026-2032年全球市場預測(依服務、飛機類型、載貨能力、貨物類型、裝卸通道及最終用途產業分類)航空貨運市場:2026-2032年全球市場預測(按貨物類型、服務類型、飛機類型、應用和最終用戶分類)
 呼吸空氣軟管市場:按類型、應用和地區分類
 2026-2030年全球航空貨運市場
 對 2026 年至 2035 年海運和空運物流市場的商業機會、成長要素、產業趨勢和預測進行分析。
 飛機貨物運輸系統市場報告:趨勢、預測與競爭分析(至2035年)
 2026年全球航空貨運和物流市場報告2026年全球航空貨運服務市場報告全球航空貨運市場規模、佔有率、趨勢和成長分析報告(2026-2034)