


 |
市場調查報告書
商品編碼
2038689
對 2026 年至 2035 年海運和空運物流市場的商業機會、成長要素、產業趨勢和預測進行分析。Sea Air Logistics Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

2025年全球海空聯運市場價值為92億美元,預計2035年將以5.7%的複合年成長率成長至163億美元。
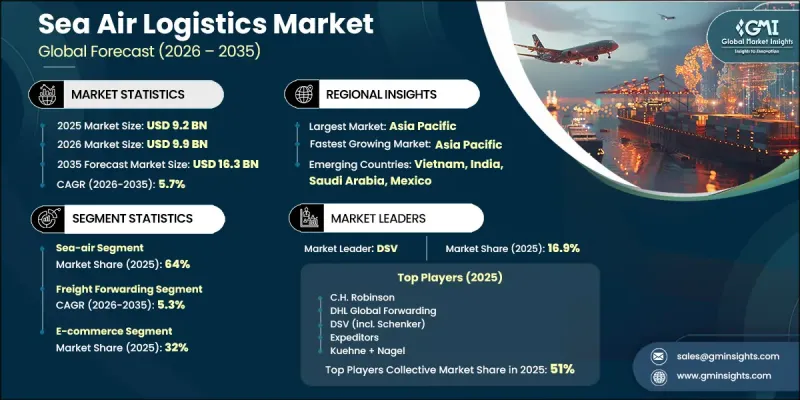
市場擴張的驅動力在於全球貿易網路日益複雜,這反過來又推動了對兼顧速度和成本效益的綜合運輸模式的需求。隨著企業尋求更可靠的長途貨運替代方案,海空聯運的混合物流解決方案正日益受到關注。主要海上航線供應鏈中斷和不確定性的增加,進一步加速了多模態策略的採用。這些中斷促使企業重新評估其運輸路線決策,並在物流規劃中優先考慮柔軟性。對於高價值、時效性強的貨物,企業越來越依賴多式聯運系統,確保更快、更可預測的交貨時間。此外,隨著國際貿易活動的擴展,企業擴大採用成本最佳化的運輸模式,以減少對單一運輸方式的依賴。隨著全球商業的日益動態化,海空多式聯運物流正成為增強韌性、提高運輸效率並支持各行業不斷變化的供應鏈需求的策略解決方案。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 92億美元 |
| 預測金額 | 163億美元 |
| 複合年成長率 | 5.7% |
預計到2025年,海空多式聯運將佔據64%的市場佔有率,並在2026年至2035年間以6.3%的複合年成長率成長。此模式仍然是最佳化主要國際貿易航線運輸時間和成本的首選物流方式。它結合了海運的高效性和空運的速度,為國際貨運提供了一個均衡的解決方案。這種模式尤其適用於既需要合理交貨時間又需要保持成本效益的貨運,並鞏固了其在全球物流市場的領先地位。
預計到2025年,貨運代理市佔率將達到50.7%,並在2035年之前以5.3%的複合年成長率成長。該領域在端到端貨運管理中發揮著至關重要的作用,包括協調運輸方式、選擇承運商和處理相關文件。透過簡化複雜的物流需求,貨運代理能夠實現無縫的國際貿易運作。隨著企業尋求提高效率、降低運輸成本和最佳化全球供應鏈管理,對綜合運輸解決方案的依賴性日益增強,從而推動了對貨運代理服務的需求。
在強勁的出口主導製造業活動和廣泛的國際貿易網路的推動下,預計到2025年,中國海運和空運物流市場將佔據全球49%的市場佔有率。中國先進的港口基礎設施和完善的航空貨運設備建構了高效率的多模態網路。沿海物流樞紐進一步提升了貨物配送效率,鞏固了中國作為國際物流中心的重要地位。此外,跨境電子商務的蓬勃發展也持續推動對更快捷、更靈活的配送解決方案的需求。
目錄
第1章:調查方法
第2章執行摘要
第3章業界考察
- 生態系分析
- 供應商情況
- 利潤率分析
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 地緣政治因素導致海上運輸中斷和改道
- 「中國+1」政策導致製造地轉移
- 跨境電子商務的快速成長
- 庫存策略轉變
- 產業潛在風險與挑戰
- 機票價格波動劇烈,運輸能力有限
- 交通樞紐的基礎設施瓶頸
- 市場機遇
- CEIV Pharma 和低溫運輸物流的擴張
- 海關清關業務中的數位化和人工智慧
- 對新興中東和非洲中心的投資
- 促進因素
- 成長潛力分析
- 監理情勢
- 北美洲
- 美國貨運和貨物安全法規
- 美國海關和邊境管制合規框架
- 加拿大貨運和海關法規
- 歐洲
- 歐盟關稅和貿易合規框架
- 歐盟航空和海事安全法規
- 有關貨運的環境法規
- 亞太地區
- 中國的貿易和關稅規定
- 印度物流與海關合規標準
- 日本有關貨物安全和運輸的法規
- 澳洲生物安全和進出口法規
- 東協貿易與物流框架
- 拉丁美洲
- 巴西海關和貨運法規
- 阿根廷的貿易和物流合規
- 墨西哥運輸和海關法規
- 中東和非洲
- 阿拉伯聯合大公國的物流與自由區法規
- 沙烏地阿拉伯貨物運輸和檢驗條例
- 遵守南非海關和運輸法規
- 北美洲
- 波特五力分析
- PESTEL 分析
- 科技與創新趨勢
- 當前技術趨勢
- 新興技術
- 價格分析(基於初步調查)
- 對過去價格趨勢的分析
- 按玩家類型分類的定價策略
- 成本細分分析
- 永續性和環境方面
- 永續計劃
- 減少廢棄物策略
- 生產中的能源效率
- 具有環保意識的舉措
- 關於碳足跡的考量
- 貿易流量分析(基於付費資料庫)
- 世界主要貿易走廊
- 主要出發和到達樞紐
- 區域貨運模式
- 合約和定價模式分析
- 長期合約與現貨價格的比較
- 路線特定價格決定因素
- 不同服務類型的利潤率波動
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 針對特定領域的生成式人工智慧應用案例和實施藍圖
- 風險、限制和監管考量
- 預測假設和情境分析(基於初步研究)
- 基本案例-驅動複合年成長率的關鍵宏觀經濟與產業變量
- 樂觀情境-宏觀經濟與產業的順風
- 悲觀情景-宏觀經濟放緩或產業逆風
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲(MEA)
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係與合作
- 新產品發布
- 業務拓展計劃及資金籌措
第5章 市場估計與預測:依運輸方式分類,2022-2035年
- 海空聯運
- 天海
- 其他
第6章 市場估計與預測:依服務業分類,2022-2035年
- 轉發
- 倉儲/物流
- 報關
- 附加價值服務
第7章 市場估計與預測:依產業分類,2022-2035年
- 電子商務
- 車
- 機械和設備
- 製藥
- 消費品
- 其他
第8章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 挪威
- 荷蘭
- 瑞典
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 新加坡
- 泰國
- 印尼
- 越南
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲(MEA)
- 南非
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
第9章:公司簡介
- 世界公司
- CEVA Logistics
- DHL Global Forwarding
- DSV
- Expeditors
- Kuehne+Nagel
- Nippon Express
- Sinotrans
- UPS Supply Chain Solutions
- 本地球員
- Aramex
- Dachser
- Dimerco Express
- GWC(Gulf Warehousing Company)
- Hellmann Worldwide Logistics
- Kerry Logistics
- Toll
- 新興企業/顛覆者
- Beacon
- Flexport
- Forto
- OVRSEA
- Zencargo
The Global Sea Air Logistics Market was valued at USD 9.2 billion in 2025 and is estimated to grow at a CAGR of 5.7% to reach USD 16.3 billion by 2035.
Market expansion is driven by increasing complexity in global trade networks, which is pushing demand for integrated transportation models that balance speed and cost efficiency. Hybrid logistics solutions that combine sea and air transport are gaining traction as businesses seek more reliable alternatives for long-distance cargo movement. Rising supply chain disruptions and uncertainties across key maritime routes are further accelerating the adoption of multimodal strategies. These disruptions are prompting companies to reassess routing decisions and prioritize flexibility in logistics planning. High-value and time-sensitive goods are increasingly relying on combined transport systems to ensure faster and more predictable delivery timelines. Growing international trade activity is also encouraging businesses to adopt cost-optimized shipping models that reduce dependency on single-mode transport. As global commerce becomes more dynamic, sea-air logistics is emerging as a strategic solution that enhances resilience, improves transit efficiency, and supports evolving supply chain requirements across industries.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $9.2 Billion |
| Forecast Value | $16.3 Billion |
| CAGR | 5.7% |
The sea-air segment accounted for a 64% share in 2025 and is projected to grow at a CAGR of 6.3% from 2026 to 2035. This segment remains a preferred logistics approach for optimizing both transit time and shipping costs across major global trade routes. By combining ocean freight efficiency with air transport speed, it delivers a balanced solution for international cargo movement. The model is particularly effective for shipments requiring moderate delivery timelines while maintaining cost efficiency, supporting its strong position in the global logistics landscape.
The freight forwarding segment held a 50.7% share in 2025 and is expected to grow at a CAGR of 5.3% through 2035. This segment plays a critical role in managing end-to-end cargo movement by coordinating transport modes, selecting carriers, and handling documentation processes. It enables seamless international trade operations by simplifying complex logistics requirements. Increasing reliance on integrated shipping solutions is driving demand for freight forwarding services, as businesses seek improved efficiency, reduced transit costs, and streamlined global supply chain management.
China Sea Air Logistics Market accounted for 49% share in 2025 supported by strong export-driven manufacturing activity and extensive global trade connectivity. The country's advanced port infrastructure and well-developed air cargo facilities enable efficient multimodal transportation networks. Coastal logistics hubs further enhance cargo flow efficiency, strengthening China's role as a key center for international logistics operations. Rising cross-border e-commerce activity is also contributing to sustained demand for faster and more flexible delivery solutions.
Key players operating in the Global Sea Air Logistics Market include Kuehne + Nagel, DHL Global Forwarding, DSV, Expeditors, C.H. Robinson, CEVA Logistics, Sinotrans, Nippon Express, UPS Supply Chain Solutions, and Kerry Logistics. Companies in the Sea Air Logistics Market are focusing on expanding integrated service offerings, digital transformation, and global network optimization to strengthen their market position. Investments in advanced tracking systems and supply chain visibility tools are enabling improved shipment coordination and operational efficiency. Firms are also forming strategic partnerships and alliances to enhance geographic reach and service capabilities. Diversification of logistics solutions, including flexible multimodal options, is helping companies cater to evolving customer requirements. Additionally, businesses are prioritizing automation, data analytics, and real-time monitoring to improve decision-making and reduce transit delays. Expansion into emerging trade corridors is further supporting growth and enhancing competitive positioning across global markets.
Table of Contents
Chapter 1 Methodology
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Transportation Mode
- 2.2.3 Service
- 2.2.4 Industry Vertical
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin analysis
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Geopolitical maritime disruptions and rerouting
- 3.2.1.2 China Plus One" manufacturing shift
- 3.2.1.3 Cross-border e-commerce boom
- 3.2.1.4 Inventory strategy shifts
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 Volatile air freight rates and capacity constraints
- 3.2.2.2 Infrastructure bottlenecks at transit hubs
- 3.2.3 Market opportunities
- 3.2.3.1 Expansion of CEIV Pharma and cold-chain logistics
- 3.2.3.2 Digitalization and AI in customs brokerage
- 3.2.3.3 Investment in emerging MEA hubs
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.1.1 United States freight transport and cargo security regulations
- 3.4.1.2 United States customs and border compliance framework
- 3.4.1.3 Canada freight transport and customs regulations
- 3.4.2 Europe
- 3.4.2.1 European Union customs and trade compliance framework
- 3.4.2.2 European Union air and maritime safety regulations
- 3.4.2.3 Environmental regulations for freight transport
- 3.4.3 Asia Pacific
- 3.4.3.1 China trade and customs regulations
- 3.4.3.2 India logistics and customs compliance standards
- 3.4.3.3 Japan cargo safety and transport regulations
- 3.4.3.4 Australia biosecurity and import export regulations
- 3.4.3.5 ASEAN trade and logistics frameworks
- 3.4.4 Latin America
- 3.4.4.1 Brazil customs and freight regulations
- 3.4.4.2 Argentina trade and logistics compliance
- 3.4.4.3 Mexico transport and customs regulations
- 3.4.5 Middle East & Africa
- 3.4.5.1 United Arab Emirates logistics and free zone regulations
- 3.4.5.2 Saudi Arabia freight and inspection regulations
- 3.4.5.3 South Africa customs and transport compliance
- 3.4.1 North America
- 3.5 Porter's analysis
- 3.6 PESTEL analysis
- 3.7 Technology and innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Pricing Analysis (Driven by primary research)
- 3.8.1 Historical Price Trend Analysis
- 3.8.2 Pricing Strategy by Player Type
- 3.9 Cost breakdown analysis
- 3.10 Sustainability and environmental aspects
- 3.10.1 Sustainable practices
- 3.10.2 Waste reduction strategies
- 3.10.3 Energy efficiency in production
- 3.10.4 Eco-friendly Initiatives
- 3.10.5 Carbon footprint considerations
- 3.11 Trade flow analysis (Driven by paid database)
- 3.11.1 Key global trade corridors
- 3.11.2 Major origin and destination hubs
- 3.11.3 Cargo flow patterns by region
- 3.12 Contract and pricing model analysis
- 3.12.1 Long term contracts vs spot pricing
- 3.12.2 Pricing determinants across routes
- 3.12.3 Margin variability by service type
- 3.13 Impact of AI and Generative AI on the Market
- 3.13.1 AI Driven Disruption of Existing Business Models
- 3.13.2 GenAI Use Cases and Adoption Roadmap by Segment
- 3.13.3 Risks Limitations and Regulatory Considerations
- 3.14 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.14.1 Base Case- Key Macro & Industry Variables Driving CAGR
- 3.14.2 Optimistic Scenarios- Favorable macro and industry tailwinds
- 3.14.3 Pessimistic Scenario - Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 LATAM
- 4.2.5 MEA
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New Product Launches
- 4.5.4 Expansion Plans and funding
Chapter 5 Market Estimates & Forecast, By Transportation Mode, 2022 - 2035 (USD Mn, Tons)
- 5.1 Key trends
- 5.2 Sea-Air
- 5.3 Air-Sea
- 5.4 Others
Chapter 6 Market Estimates & Forecast, By Service, 2022 - 2035 (USD Mn, Tons)
- 6.1 Key trends
- 6.2 Freight forwarding
- 6.3 Warehousing and distribution
- 6.4 Customs brokerage
- 6.5 Value-added services
Chapter 7 Market Estimates & Forecast, By Industry Vertical, 2022 - 2035 (USD Mn, Tons)
- 7.1 Key trends
- 7.2 E-commerce
- 7.3 Automotive
- 7.4 Machinery & equipment
- 7.5 Pharmaceuticals
- 7.6 Consumer goods
- 7.7 Others
Chapter 8 Market Estimates & Forecast, By Region, 2022 - 2035 (USD Mn, Tons)
- 8.1 Key trends
- 8.2 North America
- 8.2.1 US
- 8.2.2 Canada
- 8.3 Europe
- 8.3.1 Germany
- 8.3.2 UK
- 8.3.3 France
- 8.3.4 Italy
- 8.3.5 Spain
- 8.3.6 Russia
- 8.3.7 Norway
- 8.3.8 Netherlands
- 8.3.9 Sweden
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 India
- 8.4.3 Japan
- 8.4.4 Australia
- 8.4.5 South Korea
- 8.4.6 Singapore
- 8.4.7 Thailand
- 8.4.8 Indonesia
- 8.4.9 Vietnam
- 8.5 Latin America
- 8.5.1 Brazil
- 8.5.2 Mexico
- 8.5.3 Argentina
- 8.6 MEA
- 8.6.1 South Africa
- 8.6.2 Saudi Arabia
- 8.6.3 UAE
- 8.6.4 Turkey
Chapter 9 Company Profiles
- 9.1 Global Players
- 9.1.1 CEVA Logistics
- 9.1.2 DHL Global Forwarding
- 9.1.3 DSV
- 9.1.4 Expeditors
- 9.1.5 Kuehne+Nagel
- 9.1.6 Nippon Express
- 9.1.7 Sinotrans
- 9.1.8 UPS Supply Chain Solutions
- 9.2 Regional Players
- 9.2.1 Aramex
- 9.2.2 Dachser
- 9.2.3 Dimerco Express
- 9.2.4 GWC (Gulf Warehousing Company)
- 9.2.5 Hellmann Worldwide Logistics
- 9.2.6 Kerry Logistics
- 9.2.7 Toll
- 9.3 Emerging Players/Disruptors
- 9.3.1 Beacon
- 9.3.2 Flexport
- 9.3.3 Forto
- 9.3.4 OVRSEA
- 9.3.5 Zencargo

 全球氣管市場規模、佔有率、趨勢及成長分析報告(2026-2034)
 大型航空貨運市場:2026-2032年全球市場預測(依服務、飛機類型、載貨能力、貨物類型、裝卸通道及最終用途產業分類)航空貨運市場:2026-2032年全球市場預測(按貨物類型、服務類型、飛機類型、應用和最終用戶分類)
 呼吸空氣軟管市場:按類型、應用和地區分類
 氣管市場商機、成長要素、產業趨勢分析及2026-2035年預測。
 2026-2030年全球航空貨運市場
 飛機貨物運輸系統市場報告:趨勢、預測與競爭分析(至2035年)
 2026年全球航空貨運和物流市場報告2026年全球航空貨運服務市場報告全球航空貨運市場規模、佔有率、趨勢和成長分析報告(2026-2034)