

 |
市場調查報告書
商品編碼
2083245
空中下載 (OTA) 測試市場機會、成長促進因素、產業趨勢分析及 2026-2035 年預測Over-the-Air Testing Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

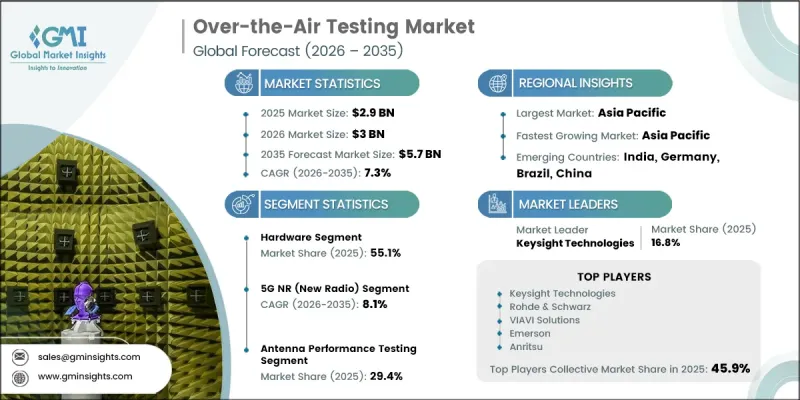
2025 年全球空中下載 (OTA) 測試市場價值為 29 億美元,預計到 2035 年將以 7.3% 的複合年成長率成長至 57 億美元。
市場擴張的驅動力來自下一代無線通訊技術的快速發展和連網設備日益成長的複雜性。隨著先進無線網路的部署,對能夠精確評估輻射性能、訊號完整性和互通性。全球市場不斷變化的監管要求和認證標準也在推動需求,促使企業加強對測試能力和基礎設施的投資。此外,無線通訊標準的持續演進也使業界受益,這要求在多個頻段、天線配置和連接環境下進行更全面的性能檢驗。消費性電子產品、工業系統和通訊設備中互聯技術的日益普及,正在擴大 OTA 測試服務和設備的潛在市場。隨著無線生態系統規模和複雜性的不斷成長,OTA 測試正成為全球產品開發、認證和品質保證流程中不可或缺的環節。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 起始金額 | 29億美元 |
| 預測金額 | 57億美元 |
| 複合年成長率 | 7.3% |
硬體部分佔55.1%的市場佔有率,預計2026年至2035年將以4.2%的複合年成長率成長。此部分構成OTA測試基礎設施的核心,包括用於精確評估無線性能的專用設備。由於實體測試環境和高精度測量系統在滿足認證要求和確保設備性能可靠性方面發揮著至關重要的作用,因此市場需求仍然強勁。與OTA測試設施相關的先進技術能力和基礎設施投資將繼續鞏固該部分在市場中的主導地位。
預計到2025年,天線性能測試市場將佔據29.4%的市場。該市場專注於評估關鍵的無線通訊特性,包括訊號傳播效率、輻射特性、波束管理性能和先進天線功能。現代無線設備中日益複雜的天線系統的應用,推動了對專業測試能力的需求。製造商持續將天線性能檢驗置於產品開發的重要位置,以最佳化連接性、提升用戶體驗並滿足監管合規要求。
中國空中下載(OTA)測試市場佔據50%的市場佔有率,預計2025年市場規模將達到5.404億美元。中國在該領域的主導地位得益於其龐大的無線設備製造生態系統、強大的通訊業實力以及互聯技術的大規模生產。對無線產品認證日益成長的需求、先進通訊基礎設施的擴展以及對下一代連接解決方案的持續投資,正在推動OTA測試在開發和合規環境中的發展。這些因素進一步鞏固了中國作為亞太地區OTA測試中心的重要地位。
目錄
第1章:調查方法
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率分析
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 成長促進因素
- 5G NR 的加速部署和毫米波頻率的擴展正在推動對先進 OTA 測試基礎設施的需求。
- 由於世界各國(FCC、CE、3GPP、PTCRB)的嚴格監管和認證要求,OTA檢驗已成為所有設備類別的強制性要求。
- 物聯網和連網型設備的爆炸性成長導致測試總量增加。
- 隨著汽車電氣化和V2X技術的引入,獨特的OTA檢驗要求正在出現。
- 產業潛在風險與挑戰
- 先進的OTA測試實驗室基礎設施需要大量的資本投資(毫米波測試實驗室:每個設施250萬美元至400萬美元)。
- 在全球範圍內,熟練的射頻工程師和毫米波測量技術專家嚴重短缺。
- 市場機遇
- 人工智慧整合自動化測試平台可縮短認證時間並降低營運成本。
- 新興非地面網路(NB-NTN)和低地球軌道衛星通訊設備的測試段
- 醫療穿戴式和植入式裝置的OTA認證要求迅速擴展。
- 智慧城市和工業IoT基礎設施的發展正在開闢新的試驗領域。
- 成長促進因素
- 成長潛力分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格分析
- 對過去價格趨勢的分析
- 定價策略:按業務類型分類
- 監理情勢
- 北美洲
- 美國國家標準與技術研究院 (NIST) 測量標準與射頻測量框架
- 美國聯邦通訊委員會 (FCC) 設備認證和 OTA 合規性要求
- 職業安全與健康管理局 (OSHA) 實驗室安全標準
- 美國國家標準協會 (ANSI) 制定的測試和測量標準化標準
- ISO/IEC 17025 實驗室認可要求
- 歐洲
- CENELEC 電磁相容性和電氣測試標準
- 電磁相容性(EMC)指令
- 低電壓指令(LVD)
- 無線電設備指令(RED 2014/53/EU)
- ISO/IEC 17025 認證框架
- 亞太地區
- 國家市場監督管理總局(SAMR)對計量科學的監管
- 中國國家認可服務(CNAS)實驗室認可標準
- 日本工業標準委員會(JISC)測試和射頻測量標準
- 國家檢測和校準實驗室認可委員會(NABL)
- 印度標準局 (BIS) 電子設備測試和認證框架
- 拉丁美洲
- 國家計量、品質和技術研究院 (INMETRO) 計量和校準標準
- 標準、測試和認證機構總局
- 美洲計量體系(SIM)區域框架
- ISO/IEC 17025 實驗室認可要求
- 中東和非洲
- ESMA(阿拉伯聯合大公國標準與計量局)的測試與認證標準
- 沙烏地阿拉伯標準、計量和品質組織(SASO)產品測試法規
- 海灣標準化組織(GSO)區域測試框架
- 非洲標準化組織(ARSO)區域框架
- ISO/IEC 17025 實驗室認可框架
- 北美洲
- 波特的分析
- PESTLE分析
- 專利分析
- 成本細分分析
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 永續性和環境方面
- 永續計劃
- 減少廢棄物策略
- 生產中的能源效率
- 具有環保意識的舉措
- 考慮碳足跡
- 預測假設和情境分析
- 基本案例:驅動複合年成長率的關鍵宏觀經濟與產業變量
- 樂觀情境:宏觀經濟與產業的順風
- 悲觀情景:宏觀經濟放緩或產業逆風
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 排名分類標準與遴選標準
- 按收入、地區和創新能力分類的層級定位矩陣。
第5章 市場估算與預測:依產品類型分類,2022-2035年
- 硬體
- 消音室和殘響室系統
- 射頻測量設備
- 天線探針與定位系統
- 用於緊湊型天線測試場(CATR)的反射器系統
- 多探針陣列系統
- 軟體分析
- 測試編配和管理平台
- 射頻模擬與電磁場建模軟體
- 數據分析、視覺化和報告工具
- 人工智慧驅動的測試自動化軟體
- 服務
- 專業服務
- 託管服務
第6章 市場估計與預測:依技術標準分類,2022-2035年
- 5G NR(New Radio)
- 4G LTE
- Wi-Fi
- Bluetooth
- 低功耗廣域網路(LPWAN)
- 其他
第7章 市場估計與預測:依檢測類型分類,2022-2035年
- 天線性能測試
- 一致性測試
- 相容性測試
- 生產線測試
第8章 市場估算與預測:依測試環境分類,2022-2035年
- 遠場消音室
- 小型天線測試場地(CATR)
- 近場通訊系統
- 殘響室
第9章 市場估計與預測:依最終用途產業分類,2022-2035年
- 消費性電子產品
- 車
- 電訊
- 航太/國防
- 衛生保健
- 工業IoT和智慧設備
- 其他
第10章 市場估價與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 挪威
- 荷蘭
- 瑞典
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 新加坡
- 泰國
- 印尼
- 越南
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
- 土耳其
第11章:公司簡介
- 世界公司
- Rohde &Schwarz
- Keysight Technologies
- Anritsu
- NI(Emerson)
- VIAVI Solutions
- ETS-Lindgren
- MVG(Microwave Vision)
- LitePoint
- NSI-MI Technologies
- ANSYS
- Altair Engineering
- Remcom
- Cadence Design Systems
- Bureau Veritas
- Intertek
- TUV SUD
- SGS
- TUV Rheinland
- 本地公司
- Bluetest
- EMITE Ingenieria
- Sporton International
- Allion Labs
- CETECOM Advanced
The Global Over-The-Air Testing Market was valued at USD 2.9 billion in 2025 and is estimated to grow at a CAGR of 7.3% to reach USD 5.7 billion by 2035.
Market expansion is fueled by the rapid advancement of next-generation wireless communication technologies and the increasing complexity of connected devices. The growing deployment of advanced wireless networks is creating significant demand for testing infrastructure capable of accurately evaluating radiated performance, signal integrity, and connectivity reliability. As wireless devices become more sophisticated and incorporate advanced antenna architectures, manufacturers are increasingly relying on over-the-air testing solutions to ensure performance, compliance, and interoperability. Evolving regulatory requirements and certification standards across global markets are also contributing to demand, encouraging greater investment in testing capabilities and infrastructure. The industry is further benefiting from the continued evolution of wireless communication standards, which require more comprehensive performance validation across multiple frequency bands, antenna configurations, and connectivity environments. Increasing adoption of connected technologies across consumer electronics, industrial systems, and communication devices is expanding the addressable market for OTA testing services and equipment. As wireless ecosystems continue to grow in scale and complexity, over-the-air testing is becoming an essential component of product development, certification, and quality assurance processes worldwide.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $2.9 Billion |
| Forecast Value | $5.7 Billion |
| CAGR | 7.3% |
The hardware segment accounted for 55.1% share and is projected to grow at a CAGR of 4.2% from 2026 to 2035. The segment forms the core foundation of OTA testing infrastructure and includes specialized equipment required to conduct accurate wireless performance evaluations. Demand remains strong due to the essential role of physical testing environments and precision measurement systems in supporting certification requirements and ensuring reliable device performance. The high level of technical sophistication and infrastructure investment associated with OTA testing facilities continues to support the segment's leading market position.
The antenna performance testing segment held a 29.4% share in 2025. The segment focuses on evaluating critical wireless communication characteristics, including signal propagation efficiency, radiation behavior, beam management performance, and advanced antenna functionality. Growing adoption of increasingly complex antenna systems across modern wireless devices is driving demand for specialized testing capabilities. Manufacturers continue to prioritize antenna performance validation during product development to optimize connectivity, improve user experiences, and support regulatory compliance requirements.
China Over-The-Air Testing Market held a 50% share, generating USD 540.4 million in 2025. The country's leadership position is supported by its extensive wireless device manufacturing ecosystem, strong telecommunications industry presence, and large-scale production of connected technologies. Growing demand for wireless product certification, expanding deployment of advanced communication infrastructure, and continued investment in next-generation connectivity solutions are contributing to high OTA testing volumes across both development and compliance environments. These factors continue to strengthen China's position as a major hub for over-the-air testing activities within the Asia Pacific region.
Leading companies operating in the global over-the-air testing market include Rohde & Schwarz, Keysight Technologies, MVG, Emerson, VIAVI Solutions, ETS-Lindgren, and Anritsu. Companies operating in the over-the-air testing market are implementing a range of strategic initiatives to strengthen their competitive position and expand market share. Significant investments in research and development remain a key focus as organizations work to enhance testing accuracy, support emerging wireless technologies, and improve automation capabilities. Market participants are expanding their testing portfolios to address evolving connectivity standards and increasingly sophisticated wireless architectures. Strategic partnerships, acquisitions, and collaborations with device manufacturers, telecommunications companies, and technology providers are helping companies broaden their customer reach and accelerate innovation. Investments in advanced testing facilities, software-driven analytics platforms, and integrated validation solutions are also supporting competitive differentiation.
Table of Contents
Chapter 1 Research Methodology
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Offering
- 2.2.3 Technology Standard
- 2.2.4 Test Type
- 2.2.5 Test Environment
- 2.2.6 End-Use Industry
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin analysis
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Accelerating 5G NR Rollout & mmWave Frequency Expansion Driving Demand for Advanced OTA Test Infrastructure
- 3.2.1.2 Stringent Global Regulatory Certification Requirements (FCC, CE, 3GPP, PTCRB) Mandating OTA Validation Across Device Categories
- 3.2.1.3 Explosive Proliferation of IoT & Connected Devices Expanding Total Addressable Testing Volumes
- 3.2.1.4 Rising Automotive Electrification & V2X Deployment Creating Specialized OTA Validation Requirements
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High Capital Investment Requirements for Advanced OTA Test Chamber Infrastructure (mmWave Chambers: USD 2.5-4M per Facility)
- 3.2.2.2 Critical Shortage of Skilled RF Engineers & mmWave Measurement Expertise Globally
- 3.2.3 Market opportunities
- 3.2.3.1 AI-Integrated Automated Testing Platforms Reducing Time-to-Certification & Operational Overhead
- 3.2.3.2 Emerging Non-Terrestrial Network (NB-NTN) & LEO Satellite Communication Device Testing Segment
- 3.2.3.3 Rapid Expansion of Healthcare Wearable & Implantable Device OTA Certification Requirements
- 3.2.3.4 Smart City & Industrial IoT Infrastructure Buildout Opening New Testing Verticals
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Technology and innovation landscape
- 3.4.1 Current technological trends
- 3.4.2 Emerging technologies
- 3.5 Pricing Analysis (Driven by primary research)
- 3.5.1 Historical Price Trend Analysis
- 3.5.2 Pricing Strategy by Player Type
- 3.6 Regulatory landscape
- 3.6.1 North America
- 3.6.1.1 National Institute of Standards and Technology (NIST) Measurement Standards & RF Metrology Framework
- 3.6.1.2 Federal Communications Commission (FCC) Equipment Authorization & OTA Compliance Requirements
- 3.6.1.3 Occupational Safety and Health Administration (OSHA) Laboratory Safety Standards
- 3.6.1.4 American National Standards Institute (ANSI) Testing & Measurement Standardization
- 3.6.1.5 ISO/IEC 17025 Laboratory Accreditation Requirements
- 3.6.2 Europe
- 3.6.2.1 CENELEC EMC & Electrical Testing Standards
- 3.6.2.2 Electromagnetic Compatibility (EMC) Directive
- 3.6.2.3 Low Voltage Directive (LVD)
- 3.6.2.4 Radio Equipment Directive (RED 2014/53/EU)
- 3.6.2.5 ISO/IEC 17025 Accreditation Framework
- 3.6.3 Asia Pacific
- 3.6.3.1 State Administration for Market Regulation (SAMR) Metrology & Measurement Oversight
- 3.6.3.2 China National Accreditation Service for Conformity Assessment (CNAS) Laboratory Accreditation Standards
- 3.6.3.3 Japanese Industrial Standards Committee (JISC) Testing & RF Measurement Standards
- 3.6.3.4 National Accreditation Board for Testing and Calibration Laboratories (NABL)
- 3.6.3.5 Bureau of Indian Standards (BIS) Electronics Testing & Certification Framework
- 3.6.4 Latin America
- 3.6.4.1 National Institute of Metrology, Quality and Technology (INMETRO) Metrology & Calibration Standards
- 3.6.4.2 Directorate General of Standards Testing & Certification Authorities
- 3.6.4.3 Inter-American Metrology System (SIM) Regional Framework
- 3.6.4.4 ISO/IEC 17025 Laboratory Accreditation Requirements
- 3.6.5 Middle East & Africa
- 3.6.5.1 Emirates Authority for Standardization and Metrology (ESMA) Testing & Certification Standards
- 3.6.5.2 Saudi Standards, Metrology and Quality Organization (SASO) Product Testing Regulations
- 3.6.5.3 Gulf Standardization Organization (GSO) Regional Testing Framework
- 3.6.5.4 African Organisation for Standardisation (ARSO) Regional Framework
- 3.6.5.5 ISO/IEC 17025 Laboratory Accreditation Framework
- 3.6.1 North America
- 3.7 Porter’s analysis
- 3.8 PESTEL analysis
- 3.9 Patent analysis (Driven by primary research)
- 3.10 Cost breakdown analysis
- 3.11 Impact of AI and Generative AI on the Market
- 3.11.1 AI Driven Disruption of Existing Business Models
- 3.11.2 GenAI Use Cases and Adoption Roadmap by Segment
- 3.11.3 Risks Limitations and Regulatory Considerations
- 3.12 Sustainability and environmental aspects
- 3.12.1 Sustainable practices
- 3.12.2 Waste reduction strategies
- 3.12.3 Energy efficiency in production
- 3.12.4 Eco-friendly Initiatives
- 3.12.5 Carbon footprint considerations
- 3.13 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.13.1 Base Case- Key Macro & Industry Variables Driving CAGR
- 3.13.2 Optimistic Scenarios- Favorable macro and industry tailwinds
- 3.13.3 Pessimistic Scenario - Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 LATAM
- 4.2.5 MEA
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New Product Launches
- 4.5.4 Expansion Plans and funding
- 4.6 Company tier benchmarking
- 4.6.1 Tier classification criteria & qualifying thresholds
- 4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates & Forecast, By Offering, 2022 - 2035 (USD Mn)
- 5.1 Key trends
- 5.2 Hardware
- 5.2.1 Anechoic & Reverberation Chamber Systems
- 5.2.2 RF Measurement Instruments
- 5.2.3 Antenna Probes & Positioning Systems
- 5.2.4 Compact Antenna Test Range (CATR) Reflector Systems
- 5.2.5 Multi-Probe Array Systems
- 5.3 Software & Analytics
- 5.3.1 Test Orchestration & Management Platforms
- 5.3.2 RF Simulation & Electromagnetic Modeling Software
- 5.3.3 Data Analytics, Visualization & Reporting Tools
- 5.3.4 AI-Powered Test Automation Software
- 5.4 Services
- 5.4.1 Professional Services
- 5.4.2 Managed Services
Chapter 6 Market Estimates & Forecast, By Technology Standard, 2022 - 2035 (USD Mn)
- 6.1 Key trends
- 6.2 5G NR (New Radio)
- 6.3 4G LTE
- 6.4 Wi-Fi
- 6.5 Bluetooth
- 6.6 Low-Power Wide-Area Network (LPWAN)
- 6.7 Others
Chapter 7 Market Estimates & Forecast, By Test Type, 2022 - 2035 (USD Mn)
- 7.1 Key trends
- 7.2 Antenna Performance Testing
- 7.3 Conformance Testing
- 7.4 Compatibility Testing
- 7.5 Production Line Testing
Chapter 8 Market Estimates & Forecast, By Test Environment, 2022 - 2035 (USD Mn)
- 8.1 Key trends
- 8.2 Far-Field Anechoic Chambers
- 8.3 Compact Antenna Test Range (CATR)
- 8.4 Near-Field Systems
- 8.5 Reverberation Chambers
Chapter 9 Market Estimates & Forecast, By End-Use Industry, 2022 - 2035 (USD Mn)
- 9.1 Key trends
- 9.2 Consumer Electronics
- 9.3 Automotive
- 9.4 Telecommunications
- 9.5 Aerospace & Defense
- 9.6 Healthcare
- 9.7 Industrial IoT & Smart Devices
- 9.8 Others
Chapter 10 Market Estimates & Forecast, By Region, 2022 - 2035 (USD Mn)
- 10.1 Key trends
- 10.2 North America
- 10.2.1 US
- 10.2.2 Canada
- 10.3 Europe
- 10.3.1 Germany
- 10.3.2 UK
- 10.3.3 France
- 10.3.4 Italy
- 10.3.5 Spain
- 10.3.6 Russia
- 10.3.7 Norway
- 10.3.8 Netherlands
- 10.3.9 Sweden
- 10.4 Asia Pacific
- 10.4.1 China
- 10.4.2 India
- 10.4.3 Japan
- 10.4.4 Australia
- 10.4.5 South Korea
- 10.4.6 Singapore
- 10.4.7 Thailand
- 10.4.8 Indonesia
- 10.4.9 Vietnam
- 10.5 Latin America
- 10.5.1 Brazil
- 10.5.2 Mexico
- 10.5.3 Argentina
- 10.6 MEA
- 10.6.1 South Africa
- 10.6.2 Saudi Arabia
- 10.6.3 UAE
- 10.6.4 Turkey
Chapter 11 Company Profiles
- 11.1 Global Players
- 11.1.1 Rohde & Schwarz
- 11.1.2 Keysight Technologies
- 11.1.3 Anritsu
- 11.1.4 NI (Emerson)
- 11.1.5 VIAVI Solutions
- 11.1.6 ETS-Lindgren
- 11.1.7 MVG (Microwave Vision)
- 11.1.8 LitePoint
- 11.1.9 NSI-MI Technologies
- 11.1.10 ANSYS
- 11.1.11 Altair Engineering
- 11.1.12 Remcom
- 11.1.13 Cadence Design Systems
- 11.1.14 Bureau Veritas
- 11.1.15 Intertek
- 11.1.16 TUV SUD
- 11.1.17 SGS
- 11.1.18 TUV Rheinland
- 11.2 Regional Players
- 11.2.1 Bluetest
- 11.2.2 EMITE Ingenieria
- 11.2.3 Sporton International
- 11.2.4 Allion Labs
- 11.2.5 CETECOM Advanced

 全球汽車OTA升級市場(至2033年):依技術、應用(資訊娛樂與遠端資訊處理、ADAS、安全與安防、動力系統與車身控制、其他)、車輛類型(乘用車、輕型商用車)、電動車(純電動車、插電式混合動力車)、通訊方式與地區分類
 空中下載 (OTA) 測試:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)
 OTA傳輸平台市場報告:按組件、平台類型、最終用戶和地區分類(2026-2034年)
 無線測試市場:按交付類型、技術、應用和行業分類 - 2026-2032 年全球預測無線測試市場報告:按技術、應用、行業和地區分類(2026-2034 年)
 無線測試市場分析及預測(至2035年):依類型、產品類型、服務、技術、組件、應用、設備、流程、最終用戶、安裝類型分類
 全球OTA(空中下載)測試市場(至2035年):依技術類型、應用領域、產業、組件、公司規模和地區劃分
 到 2030 年 OTA(無線)測試市場預測:按組件、技術、最終用戶和地區分類的全球分析