

 |
市場調查報告書
商品編碼
2083124
人工智慧助理市場機會、成長要素、產業趨勢分析及2026-2035年預測AI Assistant Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球人工智慧助手市場預計到 2025 年價值 191 億美元,並將以 19.6% 的複合年成長率成長,到 2035 年達到 1,141 億美元。
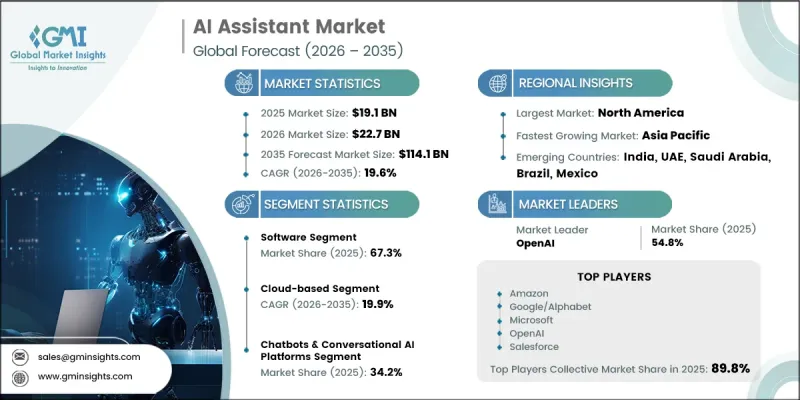
人工智慧技術的快速發展推動了這個市場的快速演進,顯著提升了人工智慧助理的功能和商業價值。各行各業的組織機構都在日益重視數位轉型(DX)計劃,以提高生產力、簡化營運並最佳化決策流程。因此,人工智慧助理已成為自動化工作流程、組織企業知識和支援商業智慧活動的關鍵工具。隨著互聯技術、智慧職場和數位整合生態系統的普及,人工智慧助理的角色範圍正進一步超越傳統軟體平台。現代人工智慧助理嵌入到各種數位環境中,能夠實現無縫通訊、智慧任務執行、營運監控和自動化決策支援。企業也正在利用人工智慧驅動的互動式解決方案來增強客戶參與、提升服務品質並提供持續支援。快速回應、增強使用者體驗和不間斷可用性等功能極大地促進了市場成長,並進一步提升了人工智慧助理在現代企業技術基礎設施中的戰略重要性。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 191億美元 |
| 預測金額 | 1141億美元 |
| 複合年成長率 | 19.6% |
預計到2025年,軟體領域將佔據67.3%的市場佔有率,並在2026年至2035年間以18.9%的複合年成長率成長。此領域涵蓋人工智慧助理平台、軟體即服務(SaaS)解決方案、應用程式介面(API)、嵌入式人工智慧應用及相關軟體技術。對雲端人工智慧解決方案的強勁需求以及企業對先進生成式人工智慧技術的日益普及,持續推動著該領域的成長。企業正擴大採用基於軟體的人工智慧助理來提高營運效率、自動化日常流程並提升業務績效。
預計到2025年,雲端解決方案的市佔率將達到73.4%,並在2026年至2035年間以19.9%的複合年成長率成長。雲端採用模式具有許多顯著優勢,包括擴充性、持續的效能提升、簡化的部署以及更低的基礎設施需求。這些優勢正加速推動尋求靈活且經濟高效的AI助理解決方案的企業採用雲端解決方案。雲端平台的快速部署和更新能力進一步鞏固了其在市場中的主導地位。
美國人工智慧助手市場預計到2025年將達到63億美元,並在2035年之前以20.2%的複合年成長率成長。當年,美國是全球市場最大的收入貢獻者,這得益於其強大的人工智慧創新者、技術供應商和雲端基礎設施公司生態系統。未來十年,對先進人工智慧技術和企業自動化舉措的投資增加預計將創造巨大的成長機會。在客戶參與、員工生產力、軟體工程和業務流程最佳化等領域的廣泛應用,預計將在整個預測期內繼續成為市場擴張的關鍵驅動力。
目錄
第1章:調查方法
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 自然語言處理和語言學習的快速發展
- 企業數位轉型的發展
- 物聯網和智慧型設備的普及
- 人們對全年365天、每天24小時的個人化互動需求日益成長。
- 產業潛在風險與挑戰
- 資料隱私和安全問題
- 整合舊有系統的複雜性
- 市場機遇
- 產業專用的人工智慧助理的發展
- 多模態人工智慧助理的擴展
- 混合動力車的普及程度越來越高。
- 擴大對新興市場的滲透
- 促進因素
- 成長潛力分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 成本細分分析
- 監理情勢
- 北美洲
- 美國國家標準與技術研究院(NIST)
- 人工智慧與數據法(加拿大)
- 歐洲
- 一般資料保護規則(德國)
- 義大利資料保護局(義大利)
- 亞太地區
- 中國資料安全法
- 印度人工智慧使命(印度)
- 拉丁美洲
- 巴西國家資料保護局
- 國家數位戰略(墨西哥)
- 中東和非洲
- 阿拉伯聯合大公國個人資料保護法(杜拜)
- 沙烏地阿拉伯資料與人工智慧局(沙烏地阿拉伯)
- 北美洲
- 波特的分析
- PESTLE分析
- 專利分析
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 永續性和環境方面
- 永續計劃
- 減少廢棄物策略
- 生產中的能源效率
- 具有環保意識的舉措
- 考慮碳足跡
- 預測假設和情境分析
- 基本案例:驅動複合年成長率的關鍵宏觀經濟與產業變量
- 樂觀情境:宏觀經濟與產業的順風
- 悲觀情景:宏觀經濟放緩或產業逆風
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 北美洲
- 歐洲
- 亞太地區
- LATAM
- 中東和非洲
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 排名分類標準與遴選標準
- 按銷售額、地區和創新能力分類的層級定位矩陣。
第5章 市場估計與預測:依組件分類,2022-2035年
- 軟體
- SaaS平台和訂閱制的AI助手
- 用於開發者整合的 API 和 SDK
- 適用於裝置的嵌入式人工智慧軟體
- 其他
- 服務
- 專業服務
- 託管服務
第6章 市場估算與預測:依部署模式分類,2022-2035年
- 基於雲端的
- 現場
- 混合
第7章 市場估計與預測:依類型分類,2022-2035年
- 虛擬助理(IVA)
- 語音助理和智慧音箱助手
- 聊天機器人和互動式人工智慧平台
- 面向企業和職場的人工智慧助手
第8章 市場估計與預測:依應用領域分類,2022-2035年
- 客戶支援和服務自動化
- 個人效率和虛擬助手
- 企業和業務自動化
- 醫療保健和臨床支持
- 智慧家庭和物聯網控制
- 汽車人工智慧援助
- 教育和數位學習
- 其他
第9章 市場估計與預測:依最終用途分類,2022-2035年
- 主要趨勢
- IT/通訊
- 醫療保健和生命科學
- BFSI
- 零售與電子商務
- 製造業
- 教育
- 政府/國防
- 其他
第10章 市場估價與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 北歐的
- 俄羅斯
- 荷蘭
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 澳洲
- 東南亞
- LATAM
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第11章:公司簡介
- 世界公司
- Amazon
- Google/Alphabet
- IBM
- Kore.ai
- Microsoft
- OpenAI
- Salesforce
- SoundHound AI
- 本地公司
- Alibaba
- Baidu
- Cognigy
- iFLYTEK
- Mistral AI
- SAP
- Yandex
- Yellow.ai
- 新興企業
- Anthropic
- DeepSeek
- ElevenLabs
- Sierra AI
The Global AI Assistant Market was valued at USD 19.1 billion in 2025 and is estimated to grow at a CAGR of 19.6% to reach USD 114.1 billion by 2035.
The market's rapid evolution is driven by major advancements in artificial intelligence technologies that have substantially expanded the functionality and business value of AI-powered assistants. Organizations across industries are increasingly prioritizing digital transformation initiatives to improve productivity, streamline operations, and enhance decision-making processes. As a result, AI assistants have emerged as critical tools for automating workflows, organizing enterprise knowledge, and supporting business intelligence activities. The growing adoption of connected technologies, smart work environments, and digitally integrated ecosystems has further expanded the role of AI assistants beyond conventional software platforms. Modern AI assistants are now embedded across a broad range of digital environments, enabling seamless communication, intelligent task execution, operational monitoring, and automated decision support. Businesses are also leveraging AI-driven conversational solutions to strengthen customer engagement, improve service quality, and provide continuous support capabilities. The ability to deliver rapid responses, enhance user experiences, and maintain uninterrupted availability is contributing significantly to market growth while reinforcing the strategic importance of AI assistants within modern enterprise technology infrastructures.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $19.1 Billion |
| Forecast Value | $114.1 Billion |
| CAGR | 19.6% |
The software segment accounted for 67.3% share in 2025 and is anticipated to grow at a CAGR of 18.9% between 2026 and 2035. This segment encompasses AI assistant platforms, software-as-a-service solutions, application programming interfaces, embedded AI applications, and related software technologies. Strong demand for cloud-enabled AI solutions and growing enterprise adoption of advanced generative artificial intelligence capabilities continue to support segment growth. Organizations are increasingly implementing software-based AI assistants to improve operational efficiency, automate routine processes, and enhance business performance.
The cloud-based segment held a 73.4% share in 2025 and is forecast to grow at a CAGR of 19.9% from 2026 to 2035. Cloud deployment models offer significant advantages, including scalability, continuous performance enhancements, simplified implementation, and reduced infrastructure requirements. These benefits have accelerated adoption among organizations seeking flexible and cost-effective AI assistant solutions. The ability to rapidly deploy and update cloud-based platforms continues to strengthen the segment's leading market position.
U.S. AI Assistant Market generated USD 6.3 billion in 2025 and is expected to grow at a CAGR of 20.2% through 2035. The country represented the largest revenue contributor to the global market during the year, supported by a strong ecosystem of artificial intelligence innovators, technology providers, and cloud infrastructure companies. Rising investments in advanced AI technologies and enterprise automation initiatives are expected to create substantial growth opportunities over the coming decade. Increasing adoption across customer engagement, employee productivity enhancement, software engineering, and business process optimization applications is anticipated to remain a key driver of market expansion throughout the forecast period.
Major companies operating in the Global AI assistant market include Apple, Baidu, OpenAI, Amazon, Microsoft, Salesforce, and Google/Alphabet. Companies competing in the AI assistant market are implementing a range of strategic initiatives to strengthen their market presence and gain competitive advantages. Significant investments in research and development remain a primary focus as organizations work to improve language understanding, contextual awareness, personalization capabilities, and overall AI performance. Strategic partnerships, technology collaborations, and ecosystem expansion efforts are also helping companies broaden their customer reach and accelerate innovation. Many market participants are integrating AI assistants across enterprise applications, productivity platforms, and digital services to increase adoption and customer retention.
Table of Contents
Chapter 1 Methodology
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Component
- 2.2.3 Deployment mode
- 2.2.4 Type
- 2.2.5 Application
- 2.2.6 End use
- 2.3 TAM analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rapid NLP & LLM advances
- 3.2.1.2 Enterprise digital transformation growth
- 3.2.1.3 IoT & smart devices proliferation
- 3.2.1.4 24/7 personalized engagement demand
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 Data privacy & security concerns
- 3.2.2.2 Legacy system integration complexity
- 3.2.3 Market opportunities
- 3.2.3.1 Industry-specific AI assistants growth
- 3.2.3.2 Multimodal AI assistant expansion
- 3.2.3.3 Hybrid deployment adoption rising
- 3.2.3.4 Emerging market penetration increase
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Technology and innovation landscape
- 3.4.1 Current technological trends
- 3.4.2 Emerging technologies
- 3.5 Cost breakdown analysis
- 3.6 Regulatory landscape
- 3.6.1 North America
- 3.6.1.1 National Institute of Standards and Technology (U.S.)
- 3.6.1.2 Artificial Intelligence and Data Act (Canada)
- 3.6.2 Europe
- 3.6.2.1 General Data Protection Regulation (Germany)
- 3.6.2.2 Italian Data Protection Authority (Italy)
- 3.6.3 Asia Pacific
- 3.6.3.1 Data Security Law (China)
- 3.6.3.2 IndiaAI Mission (India)
- 3.6.4 Latin America
- 3.6.4.1 National Data Protection Authority (Brazil)
- 3.6.4.2 National Digital Strategy (Mexico)
- 3.6.5 Middle East & Africa
- 3.6.5.1 UAE Personal Data Protection Law (Dubai)
- 3.6.5.2 Saudi Data and Artificial Intelligence Authority (Saudi Arabia)
- 3.6.1 North America
- 3.7 Porter’s analysis
- 3.8 PESTEL analysis
- 3.9 Patent analysis (Driven by primary research)
- 3.10 Impact of AI & Generative AI on the Market
- 3.10.1 AI-driven disruption of existing business models
- 3.10.2 Gen AI use cases & adoption roadmap by segment
- 3.10.3 Risks, limitations & regulatory considerations
- 3.11 Sustainability and environmental aspects
- 3.11.1 Sustainable practices
- 3.11.2 Waste reduction strategies
- 3.11.3 Energy efficiency in production
- 3.11.4 Eco-friendly initiatives
- 3.11.5 Carbon footprint considerations
- 3.12 Forecast assumptions & scenario analysis (Driven by primary research)
- 3.12.1 Base Case - key macro & industry variables driving CAGR
- 3.12.2 Optimistic Scenarios - Favorable macro and industry tailwinds
- 3.12.3 Pessimistic Scenario - Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 LATAM
- 4.2.5 MEA
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New product launches
- 4.5.4 Expansion plans and funding
- 4.6 Company tier benchmarking
- 4.6.1 Tier classification criteria & qualifying thresholds
- 4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates & Forecast, By Component, 2022 - 2035 ($Mn)
- 5.1 Key trends
- 5.2 Software
- 5.2.1 SaaS Platforms & Subscription-Based AI Assistants
- 5.2.2 APIs & SDKs for developer integration
- 5.2.3 Embedded AI software for devices
- 5.2.4 Others
- 5.3 Services
- 5.3.1 Professional services
- 5.3.2 Managed services
Chapter 6 Market Estimates & Forecast, By Deployment Mode, 2022 - 2035 ($Mn)
- 6.1 Key trends
- 6.2 Cloud-based
- 6.3 On-premises
- 6.4 Hybrid
Chapter 7 Market Estimates & Forecast, By Type, 2022 - 2035 ($Mn)
- 7.1 Key trends
- 7.2 Virtual assistants (IVA)
- 7.3 Voice assistants & smart speaker assistants
- 7.4 Chatbots & conversational AI platforms
- 7.5 Enterprise/workplace AI assistants
Chapter 8 Market Estimates & Forecast, By Application, 2022 - 2035 ($Mn)
- 8.1 Key trends
- 8.2 Customer support & service automation
- 8.3 Personal productivity & virtual assistance
- 8.4 Enterprise & business automation
- 8.5 Healthcare & clinical assistance
- 8.6 Smart home & IoT control
- 8.7 Automotive AI assistance
- 8.8 Education & E-learning
- 8.9 Others
Chapter 9 Market Estimates & Forecast, By End Use, 2022 - 2035 ($Mn)
- 9.1 Key Trends
- 9.2 IT & Telecom
- 9.3 Healthcare & life sciences
- 9.4 BFSI
- 9.5 Retail & E-commerce
- 9.6 Manufacturing
- 9.7 Education
- 9.8 Government & defense
- 9.9 Others
Chapter 10 Market Estimates & Forecast, By Region, 2022 - 2035 ($Mn)
- 10.1 Key trends
- 10.2 North America
- 10.2.1 U.S.
- 10.2.2 Canada
- 10.3 Europe
- 10.3.1 Germany
- 10.3.2 UK
- 10.3.3 France
- 10.3.4 Italy
- 10.3.5 Spain
- 10.3.6 Nordics
- 10.3.7 Russia
- 10.3.8 Netherlands
- 10.4 Asia Pacific
- 10.4.1 China
- 10.4.2 India
- 10.4.3 Japan
- 10.4.4 South Korea
- 10.4.5 Australia
- 10.4.6 Southeast Asia
- 10.5 LATAM
- 10.5.1 Brazil
- 10.5.2 Mexico
- 10.5.3 Argentina
- 10.6 MEA
- 10.6.1 South Africa
- 10.6.2 Saudi Arabia
- 10.6.3 UAE
Chapter 11 Company Profiles
- 11.1 Global players
- 11.1.1 Amazon
- 11.1.2 Google/Alphabet
- 11.1.3 IBM
- 11.1.4 Kore.ai
- 11.1.5 Microsoft
- 11.1.6 OpenAI
- 11.1.7 Salesforce
- 11.1.8 SoundHound AI
- 11.2 Regional players
- 11.2.1 Alibaba
- 11.2.2 Baidu
- 11.2.3 Cognigy
- 11.2.4 iFLYTEK
- 11.2.5 Mistral AI
- 11.2.6 SAP
- 11.2.7 Yandex
- 11.2.8 Yellow.ai
- 11.3 Emerging players
- 11.3.1 Anthropic
- 11.3.2 DeepSeek
- 11.3.3 ElevenLabs
- 11.3.4 Sierra AI


