

 |
市場調查報告書
商品編碼
2071377
家用清潔產品市場:商機、成長要素、產業趨勢分析及 2026-2035 年預測。Household Cleaning Products Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球家用清潔產品市場預計到 2025 年價值 2,150 億美元,並將以 6.2% 的複合年成長率成長,到 2035 年達到 3,900 億美元。
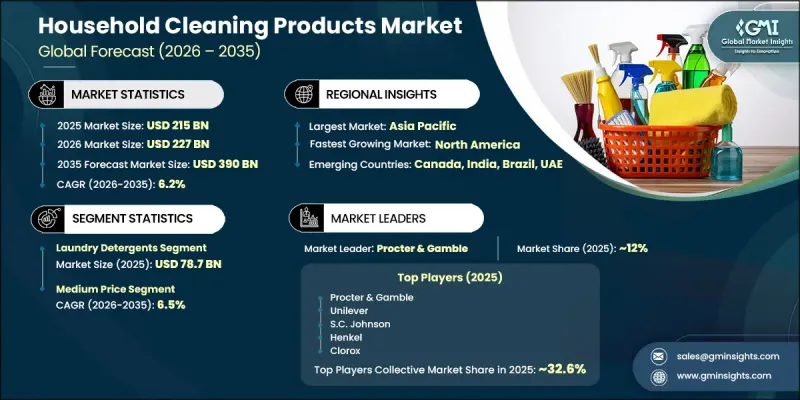
市場持續受惠於消費者在洗衣精、清潔劑、表面清潔劑、地板清潔劑和特殊清潔劑等類別上的強勁支出。這些產品類型滿足了基本的家庭清潔需求,支撐著市場的高度韌性和本質上的「非選擇性」。長期市場擴張的驅動力來自多方面因素,包括衛生意識的提高、消費者對高階清潔解決方案日益成長的偏好以及環保配方產品的廣泛應用。購買行為的轉變和對產品性能的日益重視正在重塑已開發國家和開發中國家的產業競爭格局。市場正逐漸從簡單的日常家庭支出轉變為消費者積極重視價值、功效、永續性和成分透明度的領域。近年來養成的良好清潔習慣已深深融入日常生活,從而在多個產品類型中創造了持續的需求。市場觀察顯示,高所得地區的家庭清潔活動仍比2020年之前的水準高出約18%至22%。更重要的是,消費者越來越願意投資於清潔性能更佳、外形創新、安全性更高、成分資訊更透明的產品,這為該品類的持續成長創造了有利條件。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 2150億美元 |
| 預測金額 | 3900億美元 |
| 複合年成長率 | 6.2% |
預計到2025年,洗衣精市場規模將達到787億美元,並在2035年之前維持6%的複合年成長率。由於洗衣護理的普遍性以及消費者對高附加價值產品的持續需求,洗衣液市場仍然是最大的產品類型。市場發展正從傳統的大包裝產品轉向濃縮型和便利的單次使用型產品,這些產品與傳統產品相比,每次洗滌的價值顯著提高。洗衣精市場的產品創新主要受三大因素驅動:透過先進的配方技術提升清潔力;日益重視永續和環保成分;以及消費者對便捷易用、簡化日常洗衣流程的產品設計的需求不斷成長。
中價位產品佔了45.8%的市場。其強勁的市場地位得益於均衡的價值提案,能夠吸引廣泛的消費者群體。隨著消費者購買力的提升,他們逐漸從低價產品轉向高階產品,同時,該細分市場也吸引了成本績效、追求卓越性能但又不願選擇高價產品的消費者。知名品牌產品憑藉其強大的消費者信任度、廣泛的零售通路以及兼具價格優勢和卓越性能的特點,在該細分市場佔據主導地位,使其成為全球最大的消費品市場類別。
預計2025年,美國家用清潔產品市場規模將達到412億美元,預測期內複合年成長率(CAGR)為6.5%。市場成長的主要驅動力是日益嚴格的產品透明度要求以及對永續產品開發的日益重視。監管舉措,尤其是關注成分揭露、消費者安全和環境責任的舉措,持續影響產品配方和行銷策略。這些不斷發展的標準鼓勵製造商優先考慮透明度、更安全的成分組成和永續創新,同時也增強了消費者對整個家用清潔產品產業的信心。因此,監管趨勢正日益成為產品差異化和市場長期成長的催化劑。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 每個階段增加的價值
- 影響價值鏈的因素
- 影響產業的因素
- 促進因素
- 疫情後,人們的衛生意識增強,家庭清潔頻率也改變了。
- 消費者對環保、植物來源和永續配方產品的需求日益成長。
- 電子商務和DTC(直接面對消費者)分銷管道的快速成長
- 都市化和可支配收入的增加正在推動高級產品的普及。
- 濃縮型、可重複填充型和單劑量產品形式的創新
- 產業潛在風險與挑戰
- 在天然和有機配方中平衡成本、性能和永續性
- 原料採購中的供應鏈脆弱性和關稅風險。
- 在日益細分、價格敏感的品類中,如何客戶維繫。
- 應對關鍵區域多個司法管轄區的監管合規要求
- 機會
- 優質化健康清潔產品(基於神經科學原理,無香料,低過敏性)
- 東南亞、非洲和拉丁美洲等新興市場存在尚未開發的需求
- 訂閱和儲值經營模式能夠提供穩定的收入來源。
- B2B/商業通路拓展:飯店餐飲、醫療保健與機構領域
- 促進因素
- 成長潛力分析
- 未來市場趨勢
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 監理情勢
- 標準和合規要求
- 區域監理框架
- 認證標準
- 貿易數據分析
- 進出口量及進口額趨勢
- 主要貿易路線及關稅的影響
- 價格分析
- 對過去價格趨勢的分析
- 按業務類型(高階/低階/大眾市場)分類的定價策略
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 波特的分析
- PESTLE分析
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 企業矩陣分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃
第5章 市場估算與預測:依產品類型分類,2022-2035年
- 洗衣精
- 表面清潔劑
- 清潔劑
- 馬桶清潔劑
- 空氣清新劑和除臭劑
- 其他(管道疏通劑和堵塞清除劑)
第6章 市場估計與預測:依成分類型分類,2022-2035年
- 化學/合成
- 天然/有機
第7章 市場估算與預測:依產品類型分類,2022-2035年
- 液體
- 粉末
- 凝膠/乳霜
- 噴霧(觸發式和氣霧式)
- 擦拭巾/紙巾(一次性水溶性)
- 片劑/膠囊/藥丸
第8章 市場估計與預測:依價格分類,2022-2035年
- 低的
- 中等的
- 高的
第9章 市場估計與預測:依最終用途分類,2022-2035年
- 住宅
- 商業
- HoReCa(飯店、餐廳、餐飲)
- 醫療和社會福利機構
- 企業、辦公室和教育設施
第10章 市場估價與預測:依通路分類,2022-2035年
- 線上
- 電子商務
- 公司網站
- 離線
- 超級市場和大賣場
- 專賣店
- 其他零售店
第11章 市場估價與預測:按地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 澳洲
- 印尼
- 馬來西亞
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 沙烏地阿拉伯
- UAE
- 南非
第12章:公司簡介
- 世界頂尖公司
- Procter & Gamble Co.
- Unilever PLC
- Reckitt Benckiser Group PLC
- Henkel AG & Co. KGaA
- Colgate-Palmolive Company
- The Clorox Company
- 該地區的領先企業
- SC Johnson & Son Inc.
- Kao Corporation
- Church & Dwight Co., Inc.
- Godrej Consumer Products Ltd.
- McBride PLC
- LG Household & Health Care Ltd.
- 新興企業
- Method Products PBC(SC Johnson)
- Seventh Generation Inc.
- Werner & Mertz GmbH
- Ecover
The Global Household Cleaning Products Market was valued at USD 215 billion in 2025 and is estimated to grow at a CAGR of 6.2% to reach USD 390 billion by 2035.
Market continues to benefit from consistent consumer spending across categories such as laundry care, dishwashing products, surface cleaners, floor care solutions, and specialty cleaning formulations. Together, these product categories serve essential household cleaning needs, making the market highly resilient and fundamentally non-discretionary. Long-term market expansion is supported by a combination of heightened hygiene awareness, increasing consumer preference for premium cleaning solutions, and rising adoption of environmentally responsible formulations. Across both developed and developing economies, evolving purchasing behaviors and growing emphasis on product performance are reshaping competitive dynamics within the industry. The market is increasingly transitioning away from being viewed solely as a routine household expense and toward a category where consumers actively evaluate value, efficacy, sustainability, and ingredient transparency. Elevated cleaning habits established during recent years have remained firmly embedded in daily routines, creating lasting demand across multiple product categories. Market observations indicate that household cleaning activity in higher-income regions remains approximately 18% to 22% above levels recorded before 2020. More importantly, consumers are demonstrating greater willingness to invest in products offering improved cleaning performance, innovative formats, enhanced safety profiles, and transparent ingredient disclosures, creating favorable conditions for continued category growth.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $215 Billion |
| Forecast Value | $390 Billion |
| CAGR | 6.2% |
The laundry detergents segment accounted for USD 78.7 billion in 2025 and is forecast to grow at a CAGR of 6% through 2035. The segment remains the largest product category due to the universal nature of laundry care and the continued shift toward higher-value product offerings. Market development has progressed from traditional bulk formulations toward concentrated alternatives and increasingly convenient single-use formats that generate significantly higher per-use value compared to conventional products. Product innovation within the laundry detergent segment is being driven by three major factors: enhanced cleaning effectiveness through advanced formulation technologies, increased emphasis on sustainable and environmentally conscious ingredients, and growing consumer demand for convenience-focused product designs that simplify daily cleaning routines.
The medium-priced segment held a 45.8% share. Its strong position is supported by a balanced value proposition that appeals to a broad consumer base. The segment benefits from consumers shifting upward from economy products as purchasing power improves, while also attracting value-conscious buyers seeking quality performance without entering premium price tiers. Established branded products dominate this segment due to strong consumer trust, widespread retail availability, and a competitive combination of affordability and effectiveness, making it the largest accessible market category globally.
United States Household Cleaning Products Market generated USD 41.2 billion in 2025 and is projected to expand at a CAGR of 6.5% over the forecast period. Market growth is being influenced by increasingly stringent product transparency requirements and growing emphasis on sustainable product development. Regulatory initiatives focused on ingredient disclosure, consumer safety, and environmental responsibility continue to shape product formulation and marketing strategies. These evolving standards are encouraging manufacturers to prioritize transparency, safer ingredient profiles, and sustainable innovation while strengthening consumer confidence across the household cleaning products industry. As a result, regulatory developments are increasingly serving as a catalyst for product differentiation and long-term market growth.
Major companies operating in the global household cleaning products market include Werner & Mertz GmbH, Church & Dwight Co., Inc., Kao Corporation, Reckitt Benckiser Group PLC, The Clorox Company, Henkel AG & Co. KGaA, Unilever PLC, Method Products PBC, Ecover, Procter & Gamble Co., Colgate-Palmolive Company, Godrej Consumer Products Ltd., S.C. Johnson & Son Inc., LG Household & Health Care Ltd., McBride PLC, and Seventh Generation Inc. Companies operating in the household cleaning products market are implementing a combination of product innovation, sustainability initiatives, brand premiumization, and digital expansion strategies to strengthen their competitive positions. Manufacturers are increasingly investing in environmentally friendly formulations, biodegradable ingredients, refillable packaging solutions, and reduced-plastic product designs to align with evolving consumer preferences and regulatory expectations. Firms are also expanding premium product portfolios featuring enhanced cleaning performance, ingredient transparency, and convenience-focused formats. Strategic partnerships with retailers, growth in direct-to-consumer channels, and stronger e-commerce capabilities are helping companies broaden market reach and improve customer engagement.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Product type
- 2.2.3 Ingredient type
- 2.2.4 Product form
- 2.2.5 Price
- 2.2.6 End user
- 2.2.7 Distribution channel
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising hygiene awareness & post-pandemic behavioral shift in household cleaning frequency
- 3.2.1.2 Accelerating consumer demand for eco-friendly, plant-based & sustainable formulations
- 3.2.1.3 Rapid growth of e-commerce & direct-to-consumer (DTC) distribution channels
- 3.2.1.4 Urbanization & rising disposable incomes driving premium product adoption
- 3.2.1.5 Innovation in concentrated, refillable & unit-dose product formats
- 3.2.2 Industry pitfalls & challenges
- 3.2.2.1 Balancing cost-performance-sustainability in natural/organic formulations
- 3.2.2.2 Supply chain fragility & tariff exposure in raw material procurement
- 3.2.2.3 Consumer retention in a highly fragmented, price-sensitive category
- 3.2.2.4 Navigating multi-jurisdictional regulatory compliance across key geographies
- 3.2.3 Opportunities
- 3.2.4 Premiumization & wellness-oriented cleaning products (neuroscience-backed, fragrance-free, hypoallergenic)
- 3.2.5 Emerging markets untapped demand in southeast Asia, Africa & Latin America
- 3.2.6 Subscription & refill business models enabling recurring revenue streams
- 3.2.7 B2B/commercial channel expansion HoReCa, healthcare & institutional segments
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Future market trends
- 3.5 Technology and innovation landscape
- 3.5.1 Current technological trends
- 3.5.2 Emerging technologies
- 3.6 Regulatory landscape
- 3.6.1 Standards and compliance requirements
- 3.6.2 Regional regulatory frameworks
- 3.6.3 Certification standards
- 3.7 Trade data analysis (HS Code 3402)
- 3.7.1 Import/export volume & value trends
- 3.7.2 Key trade corridors & tariff impact
- 3.8 Pricing analysis
- 3.8.1 Historical price trend analysis (driven by primary research)
- 3.8.2 Pricing strategy by player type (premium / value / mass market)
- 3.9 Impact of AI & generative AI on the market
- 3.9.1 AI-driven disruption of existing business models
- 3.9.2 GenAI use cases & adoption roadmap by segment
- 3.9.3 Risks, limitations & regulatory considerations
- 3.10 Porter's analysis
- 3.11 PESTEL analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By Region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.1 By Region
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates & Forecast, By Product Type, 2022 - 2035, (USD Billion) (Million Units)
- 5.1 Key trends
- 5.2 Laundry detergents
- 5.3 Surface cleaners
- 5.4 Dishwashing products
- 5.5 Toilet bowl cleaners
- 5.6 Air fresheners & deodorizers
- 5.7 Others (drain cleaners & uncloggers)
Chapter 6 Market Estimates & Forecast, By Ingredient Type, 2022 - 2035, (USD Billion) (Million Units)
- 6.1 Key trends
- 6.2 Chemical/synthetic
- 6.3 Natural/organic
Chapter 7 Market Estimates & Forecast, By Product Form, 2022 - 2035, (USD Billion) (Million Units)
- 7.1 Key trends
- 7.2 Liquid
- 7.3 Powder
- 7.4 Gel/cream
- 7.5 Spray (trigger & aerosol)
- 7.6 Wipes/sheets (disposable & dissolvable)
- 7.7 Tablets/pods/capsules
Chapter 8 Market Estimates & Forecast, By Price, 2022 - 2035, (USD Billion) (Million Units)
- 8.1 Key trends
- 8.2 Low
- 8.3 Medium
- 8.4 High
Chapter 9 Market Estimates & Forecast, By End-Use, 2022 - 2035, (USD Billion) (Million Units)
- 9.1 Key trends
- 9.2 Residential
- 9.3 Commercial
- 9.3.1 HoReCa (hotels, restaurants & catering)
- 9.3.2 Healthcare & institutional facilities
- 9.3.3 Corporate/office & educational facilities
Chapter 10 Market Estimates & Forecast, By Distribution Channel, 2022 - 2035, (USD Billion) (Million Units)
- 10.1 Key trends
- 10.2 Online
- 10.2.1 E-commerce
- 10.2.2 Company websites
- 10.3 Offline
- 10.3.1 Supermarkets & hypermarkets
- 10.3.2 Specialty stores
- 10.3.3 Others retail stores
Chapter 11 Market Estimates & Forecast, By Region, 2022 - 2035, (USD Billion) (Million Units)
- 11.1 Key trends
- 11.2 North America
- 11.2.1 U.S.
- 11.2.2 Canada
- 11.3 Europe
- 11.3.1 Germany
- 11.3.2 UK
- 11.3.3 France
- 11.3.4 Italy
- 11.3.5 Spain
- 11.4 Asia Pacific
- 11.4.1 China
- 11.4.2 India
- 11.4.3 Japan
- 11.4.4 South Korea
- 11.4.5 Australia
- 11.4.6 Indonesia
- 11.4.7 Malaysia
- 11.5 Latin America
- 11.5.1 Brazil
- 11.5.2 Mexico
- 11.5.3 Argentina
- 11.6 MEA
- 11.6.1 Saudi Arabia
- 11.6.2 UAE
- 11.6.3 South Africa
Chapter 12 Company Profiles
- 12.1 Top Global Players
- 12.1.1 Procter & Gamble Co.
- 12.1.2 Unilever PLC
- 12.1.3 Reckitt Benckiser Group PLC
- 12.1.4 Henkel AG & Co. KGaA
- 12.1.5 Colgate-Palmolive Company
- 12.1.6 The Clorox Company
- 12.2 Regional Champions
- 12.2.1 S.C. Johnson & Son Inc.
- 12.2.2 Kao Corporation
- 12.2.3 Church & Dwight Co., Inc.
- 12.2.4 Godrej Consumer Products Ltd.
- 12.2.5 McBride PLC
- 12.2.6 LG Household & Health Care Ltd.
- 12.3 Emerging Players
- 12.3.1 Method Products PBC (SC Johnson)
- 12.3.2 Seventh Generation Inc.
- 12.3.3 Werner & Mertz GmbH
- 12.3.4 Ecover

 家用清潔產品市場規模、佔有率、成長、全球產業分析、區域趨勢及2026年至2034年預測。
 2026-2030年全球家用清潔產品市場
 零浪費快速消費品市場預測至2034年-按產品類型、包裝類型、材料類型、通路、應用、最終用戶和地區分類的全球分析
 家用清潔產品市場:依產品類型、產品形式、最終用戶和分銷管道分類-2026-2032年全球市場預測
 家用清潔產品市場分析及預測(至2035年):類型、產品類型、應用、形式、最終用戶、技術、材質類型、功能
 家用清潔用品市場規模、佔有率和成長分析(按產品類型、分銷管道、應用和地區分類)-2026-2033年產業預測