


 |
市場調查報告書
商品編碼
2071252
汽車電腦視覺市場:商業機會、成長要素、產業趨勢分析及2026-2035年預測Automotive Computer Vision Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

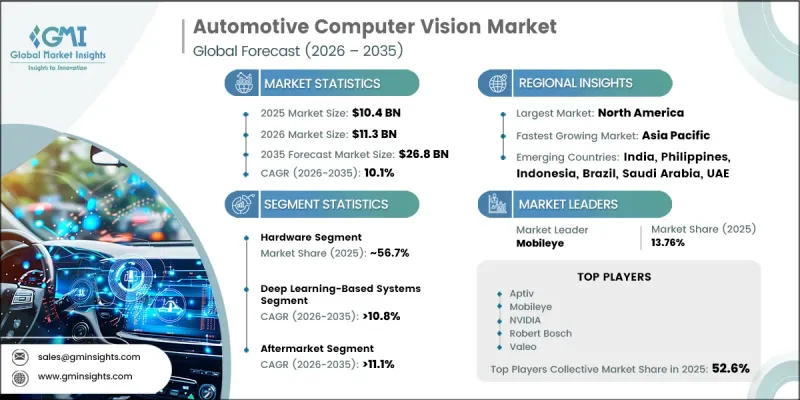
全球汽車電腦視覺市場預計到 2025 年將達到 104 億美元,並以 10.1% 的複合年成長率成長,到 2035 年達到 268 億美元。
這一成長主要得益於乘用車和商用車中高級駕駛輔助系統 (ADAS)、自動駕駛功能和智慧安全技術的日益普及。汽車製造商和技術供應商正擴大將人工智慧驅動的視覺系統融入車輛,以提升情境察覺、降低碰撞風險並增強即時環境感知。隨著各國政府實施更嚴格的車輛安全要求並推廣下一代出行標準,交通安全監管機構的壓力進一步加速了這些技術的應用。電動車和聯網汽車的日益普及也推動了對能夠支援半自動駕駛和自動駕駛功能的高性能視覺系統的需求。人工智慧、感測器融合和即時資料處理技術的不斷進步正在重塑汽車設計的優先順序,電腦視覺已成為全球汽車生態系統中現代車輛架構的核心組成部分。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 104億美元 |
| 預測金額 | 268億美元 |
| 複合年成長率 | 10.1% |
預計到2025年,硬體領域的市佔率將達到56.7%,並在2035年之前以9.2%的複合年成長率成長。這一主導地位源於即時車輛識別所需的高級感測和計算組件的日益整合。汽車視覺系統高度依賴高性能影像處理和感測技術,以支援精確的環境測繪和快速決策。隨著智慧安全和駕駛輔助功能的日益普及,對能夠在動態駕駛環境中處理複雜數據需求的強大硬體系統的需求持續成長。
基於深度學習的系統預計在2025年佔據49%的市場佔有率,並在2035年之前以10.8%的複合年成長率成長。該細分市場的主導地位源自於其能夠高精度、高適應性地處理大量視覺數據。深度學習技術提升了目標偵測、分類和識別能力,使車輛能夠在各種條件下解讀複雜的道路環境。利用大規模資料集進行持續的模型學習能夠隨著時間的推移不斷提高效能,使得這些系統非常適用於先進的行動出行應用。
美國汽車電腦視覺市場佔83.5%的全球佔有率,預計2025年市場規模將達到30億美元。推動美國市場成長的主要因素是高階駕駛輔助系統(ADAS)、自動駕駛技術和互聯出行平台在各類車型的快速普及。領先的科技公司和汽車製造商的積極佈局正在加速人工智慧驅動的感知系統、感測器整合和即時分析領域的創新。成熟的創新生態系統進一步鞏固了美國在汽車電腦視覺發展領域的領先地位。
目錄
第1章:調查方法
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率分析
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- ADAS(進階駕駛輔助系統)的廣泛應用
- 自動駕駛和半自動駕駛車輛的發展進展
- 政府加強汽車安全法規和強制規定
- 電動車和聯網汽車生態系統的擴展
- 產業潛在風險與挑戰
- 視覺系統的開發和整合成本很高。
- 即時數據處理和感測器校準的複雜性。
- 市場機遇
- 對駕駛監控和車載感測系統的需求日益成長
- 機器人計程車和自動駕駛出行服務的擴展
- 擴大商用車輛中人工智慧視覺系統的應用
- 新興的智慧城市和智慧交通基礎設施項目
- 促進因素
- 成長潛力分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格分析
- 對過去價格趨勢的分析
- 依球員類型分類的定價策略(高級球員、超值球員、成本加成球員)
- 成本細分分析
- 監管指南
- 北美洲
- 美國:ADAS合規法規是基於NHTSA車輛安全標準和FMVSS。
- 加拿大:加拿大運輸部的車輛安全法規與自動駕駛車輛測試框架
- 歐洲
- 德國:歐盟通用安全法規 (GSR) 和 KBA 自動駕駛合規標準
- 英國:《自動駕駛車輛法案》和DVSA車輛安全合規框架
- 法國:CNIL的汽車資料保護條例與智慧型運輸系統(ITS)標準
- 義大利:歐盟強制要求ADAS和聯合國歐洲經濟委員會制定汽車網路安全法規
- 亞太地區
- 中國:智慧網聯汽車(ICV)法規與汽車資料安全法
- 印度:Bharat NCAP 安全標準和 AIS-140智慧型運輸系統(ITS) 法規
- 日本:國土交通省自動駕駛安全指南和APPI資料保護框架
- 韓國:KNCAP汽車安全標準與個人資訊保護法(PIPA)
- 澳洲:澳洲自動駕駛汽車設計規則(ADR)和安全框架
- 拉丁美洲
- 巴西:CONTRAN 的汽車安全法規和智慧出行合規標準
- 墨西哥:NOM汽車安全標準與聯網汽車法規結構
- 阿根廷:國家公路安全局 (ANSV) ADAS 合規性指南
- 中東和非洲
- 阿拉伯聯合大公國:阿拉伯聯合大公國的自動駕駛出行戰略和智慧車輛安全法規
- 沙烏地阿拉伯:SASO的汽車安全標準與智慧運輸法規結構
- 南非:《國家道路交通法》和《車輛安全合規條例》
- 北美洲
- 波特的分析
- PESTLE分析
- 專利趨勢
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 預測假設和情境分析
- 基本案例:驅動複合年成長率的關鍵宏觀經濟與產業變量
- 樂觀情境:宏觀經濟與產業的順風
- 悲觀情景:宏觀經濟放緩或產業逆風
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 排名分類標準與遴選標準
- 按銷售額、地區和創新能力分類的層級定位矩陣。
第5章 市場估計與預測:依組件分類,2022-2035年
- 硬體
- 軟體
- 服務
第6章 市場估算與預測:依銷售管道分類,2022-2035年
- OEM
- 售後市場
第7章 市場估計與預測:依技術分類,2022-2035年
- 基於機器視覺的系統
- 基於深度學習的系統
- 基於感測器融合的系統
第8章 市場估計與預測:依應用領域分類,2022-2035年
- 高級駕駛輔助系統(ADAS)
- 自動駕駛
- 車上監控
- 交通和基礎設施願景
- 其他
第9章 市場估價與預測:依車輛類型分類,2022-2035年
- 搭乘用車
- 掀背車
- 轎車
- SUV
- 商用車輛
- 輕型商用車
- 大型商用車輛
- 電動車(EV)
- 電池式電動車(BEV)
- 插電式混合動力車(PHEV)
- 自動駕駛汽車
- 無人駕駛計程車和共用自動駕駛出行
- 自動駕駛卡車和貨運
第10章 市場估價與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 荷蘭
- 比利時
- 瑞典
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 菲律賓
- 印尼
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第11章:公司簡介
- 世界公司
- Aptiv
- Continental
- Mobileye
- NVIDIA
- NXP Semiconductors
- Onsemi
- Qualcomm Technologies
- Renesas Electronics
- Robert Bosch
- Sony Semiconductor
- Valeo
- 當地公司
- Black Sesame Technologies
- Denso
- FORVIA HELLA
- Hikvision Automotive
- Hitachi Astemo
- Horizon Robotics
- Hyundai Mobis
- Magna International
- ZF Friedrichshafen
- 新興企業
- Ambarella
- Autobrains Technologies
- indie Semiconductor
- STRADVision
The Global Automotive Computer Vision Market was valued at USD 10.4 billion in 2025 and is estimated to grow at a CAGR of 10.1% to reach USD 26.8 billion by 2035.
Growth is driven by the rising deployment of advanced driver assistance systems, autonomous driving capabilities, and intelligent safety technologies across passenger and commercial vehicles. Automotive manufacturers and technology providers are increasingly embedding AI-powered vision systems to enhance situational awareness, reduce collision risks, and improve real-time environmental perception. Regulatory pressure from transportation safety authorities is further accelerating adoption, as governments enforce stricter vehicle safety requirements and promote next-generation mobility standards. Expanding penetration of electric and connected vehicles is also reinforcing demand for high-performance vision systems capable of supporting semi-autonomous and autonomous driving functions. Continuous advancements in artificial intelligence, sensor fusion, and real-time data processing are reshaping automotive design priorities, making computer vision a core component of modern vehicle architecture across global automotive ecosystems.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $10.4 Billion |
| Forecast Value | $26.8 Billion |
| CAGR | 10.1% |
The hardware segment held 56.7% share in 2025 and is projected to grow at a CAGR of 9.2% through 2035. Its dominance is attributed to the increasing integration of advanced sensing and computing components required for real-time vehicle perception. Automotive vision systems rely heavily on high-performance imaging and detection technologies that support accurate environmental mapping and rapid decision-making. Rising deployment of intelligent safety and driver assistance features continues to drive demand for robust hardware systems capable of handling complex data processing requirements in dynamic driving environments.
The deep learning-based systems segment accounted for 49% share in 2025 and is expected to grow at a CAGR of 10.8% through 2035. This segment leads due to its ability to process vast volumes of visual data with high precision and adaptability. Deep learning technologies enhance object detection, classification, and recognition capabilities, allowing vehicles to interpret complex road environments under varying conditions. Continuous model training using large datasets enables performance improvements over time, making these systems highly suitable for advanced mobility applications.
United States Automotive Computer Vision Market held an 83.5% share, generating USD 3 billion in 2025. Market growth in the country is supported by the rapid integration of advanced driver assistance systems, autonomous driving technologies, and connected mobility platforms across vehicle categories. Strong participation from leading technology firms and automotive manufacturers is accelerating innovation in AI-driven perception systems, sensor integration, and real-time analytics. The presence of established innovation ecosystems continues to reinforce the country's leadership in automotive computer vision development.
Key companies operating in the global automotive computer vision market include Valeo, Robert Bosch, Renesas Electronics, Qualcomm Technologies, Onsemi, NXP Semiconductors, NVIDIA, Mobileye, Continental, and Aptiv. Market participants are focusing on strengthening their competitive positioning through continuous investment in artificial intelligence, machine learning, and high-performance computing technologies. Companies are enhancing their product portfolios with advanced vision sensors, AI-enabled processors, and integrated software platforms designed for real-time vehicle perception. Strategic collaborations with automotive OEMs and mobility service providers are accelerating deployment across next-generation vehicle platforms. Firms are also investing in research and development to improve object detection accuracy, system reliability, and processing speed under diverse driving conditions. Expansion of global manufacturing capabilities and localization of supply chains are further supporting scalability.
Table of Contents
Chapter 1 Methodology
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation
- 1.7 Forecast Model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Component
- 2.2.3 Sales channel
- 2.2.4 Technology
- 2.2.5 Application
- 2.2.6 Vehicle
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin analysis
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising adoption of advanced driver assistance systems (ADAS)
- 3.2.1.2 Growing development of autonomous and semi-autonomous vehicles
- 3.2.1.3 Increasing government vehicle safety regulations and mandates
- 3.2.1.4 Expansion of electric and connected vehicle ecosystems
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High development and integration costs of vision systems
- 3.2.2.2 Complexity in real-time data processing and sensor calibration
- 3.2.3 Market opportunities
- 3.2.3.1 Growing demand for driver monitoring and in-cabin sensing systems
- 3.2.3.2 Expansion of robotaxi and autonomous mobility services
- 3.2.3.3 Increasing integration of Ai-powered vision systems in commercial vehicles
- 3.2.3.4 Emerging smart city and intelligent transportation infrastructure projects
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Technology and Innovation landscape
- 3.4.1 Current technological trends
- 3.4.2 Emerging technologies
- 3.5 Pricing Analysis (Driven by Primary Research)
- 3.5.1 Historical Price Trend Analysis
- 3.5.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
- 3.6 Cost breakdown analysis
- 3.7 Regulatory guidline
- 3.7.1 North America
- 3.7.1.1 U.S.: NHTSA Vehicle Safety Standards & FMVSS ADAS Compliance Regulations
- 3.7.1.2 Canada: Transport Canada Motor Vehicle Safety Regulations & Autonomous Vehicle Testing Frameworks.
- 3.7.2 Europe
- 3.7.2.1 Germany: EU General Safety Regulation (GSR) & KBA Autonomous Driving Compliance Standards
- 3.7.2.2 UK: Automated Vehicles Act & DVSA Vehicle Safety Compliance Framework
- 3.7.2.3 France: CNIL Automotive Data Protection Regulations & Intelligent Transport System Standards
- 3.7.2.4 Italy: EU ADAS Mandates & UNECE Vehicle Cybersecurity Regulations
- 3.7.3 Asia Pacific
- 3.7.3.1 China: Intelligent Connected Vehicle (ICV) Regulations & Automotive Data Security Laws
- 3.7.3.2 India: Bharat NCAP Safety Standards & AIS-140 Intelligent Transportation Regulations
- 3.7.3.3 Japan: MLIT Autonomous Driving Safety Guidelines & APPI Data Protection Framework
- 3.7.3.4 South Korea: KNCAP Vehicle Safety Standards & Personal Information Protection Act (PIPA)
- 3.7.3.5 Australia: Australian Design Rules (ADR) & Automated Vehicle Safety Frameworks
- 3.7.4 Latin America
- 3.7.4.1 Brazil: CONTRAN Vehicle Safety Regulations & Intelligent Mobility Compliance Standards
- 3.7.4.2 Mexico: NOM Vehicle Safety Standards & Connected Vehicle Regulatory Framework
- 3.7.4.3 Argentina: National Road Safety Agency (ANSV) ADAS Compliance Guidelines
- 3.7.5 MEA
- 3.7.5.1 UAE: UAE Autonomous Mobility Strategy & Smart Vehicle Safety Regulations
- 3.7.5.2 Saudi Arabia: SASO Vehicle Safety Standards & Smart Mobility Regulatory Framework
- 3.7.5.3 South Africa: National Road Traffic Act & Vehicle Safety Compliance Regulations
- 3.7.1 North America
- 3.8 Porter's analysis
- 3.9 PESTEL analysis
- 3.10 Patent Landscape (Driven by Primary Research)
- 3.11 Impact of AI & Generative AI on the Market (Driven by Primary Research)
- 3.11.1 AI-Driven Disruption of Existing Business Models
- 3.11.2 GenAI Use Cases & Adoption Roadmap by Segment
- 3.11.3 Risks, Limitations & Regulatory Considerations
- 3.12 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.12.1 Base Case - Key Macro & Industry Variables Driving CAGR
- 3.12.2 Optimistic Scenarios - Favourable macro and industry tailwinds
- 3.12.3 Pessimistic Scenario - Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 Latin America
- 4.2.5 MEA
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New Product Launches
- 4.5.4 Expansion Plans and funding
- 4.6 Company Tier Benchmarking
- 4.6.1 Tier Classification Criteria & Qualifying Thresholds
- 4.6.2 Tier Positioning Matrix by Revenue, Geography & Innovation
Chapter 5 Market Estimates & Forecast, By Component, 2022 - 2035 ($Bn)
- 5.1 Key trends
- 5.2 Hardware
- 5.3 Software
- 5.4 Services
Chapter 6 Market Estimates & Forecast, By Sales channel, 2022 - 2035 ($Bn)
- 6.1 Key trends
- 6.2 OEM
- 6.3 Aftermarket
Chapter 7 Market Estimates & Forecast, By Technology, 2022 - 2035 ($Bn, Units)
- 7.1 Key trends
- 7.2 Machine Vision-Based Systems
- 7.3 Deep Learning-Based Systems
- 7.4 Sensor Fusion-Based Systems
Chapter 8 Market Estimates & Forecast, By Application, 2022 - 2035 ($Bn)
- 8.1 Key trends
- 8.2 Advanced Driver Assistance Systems (ADAS)
- 8.3 Autonomous Driving
- 8.4 In-Cabin Monitoring
- 8.5 Traffic & Infrastructure Vision
- 8.6 Others
Chapter 9 Market Estimates & Forecast, By Vehicle, 2022 - 2035 ($Bn)
- 9.1 Key trends
- 9.2 Passenger Cars
- 9.2.1 Hatchbacks
- 9.2.2 Sedans
- 9.2.3 SUVs
- 9.3 Commercial Vehicles
- 9.3.1 Light Commercial Vehicles
- 9.3.2 Heavy Commercial Vehicles
- 9.4 Electric Vehicles (EVs)
- 9.4.1 Battery Electric Vehicles (BEV)
- 9.4.2 Plug-In Hybrid Electric Vehicles (PHEV)
- 9.5 Autonomous Vehicles
- 9.5.1 Robotaxis & Shared Autonomous Mobility
- 9.5.2 Self-Driving Trucks & Freight
Chapter 10 Market Estimates & Forecast, By Region, 2022 - 2035 ($Bn)
- 10.1 Key trends
- 10.2 North America
- 10.2.1 US
- 10.2.2 Canada
- 10.3 Europe
- 10.3.1 Germany
- 10.3.2 UK
- 10.3.3 France
- 10.3.4 Italy
- 10.3.5 Spain
- 10.3.6 Russia
- 10.3.7 Netherlands
- 10.3.8 Belgium
- 10.3.9 Sweden
- 10.4 Asia Pacific
- 10.4.1 China
- 10.4.2 India
- 10.4.3 Japan
- 10.4.4 Australia
- 10.4.5 South Korea
- 10.4.6 Philippines
- 10.4.7 Indonesia
- 10.5 Latin America
- 10.5.1 Brazil
- 10.5.2 Mexico
- 10.5.3 Argentina
- 10.6 MEA
- 10.6.1 South Africa
- 10.6.2 Saudi Arabia
- 10.6.3 UAE
Chapter 11 Company Profiles
- 11.1 Global Players
- 11.1.1 Aptiv
- 11.1.2 Continental
- 11.1.3 Mobileye
- 11.1.4 NVIDIA
- 11.1.5 NXP Semiconductors
- 11.1.6 Onsemi
- 11.1.7 Qualcomm Technologies
- 11.1.8 Renesas Electronics
- 11.1.9 Robert Bosch
- 11.1.10 Sony Semiconductor
- 11.1.11 Valeo
- 11.2 Regional Players
- 11.2.1 Black Sesame Technologies
- 11.2.2 Denso
- 11.2.3 FORVIA HELLA
- 11.2.4 Hikvision Automotive
- 11.2.5 Hitachi Astemo
- 11.2.6 Horizon Robotics
- 11.2.7 Hyundai Mobis
- 11.2.8 Magna International
- 11.2.9 ZF Friedrichshafen
- 11.3 Emerging Players
- 11.3.1 Ambarella
- 11.3.2 Autobrains Technologies
- 11.3.3 indie Semiconductor
- 11.3.4 STRADVision

 全球醫療保健領域認知運算與人工智慧系統市場
 2026-2034年全球汽車電腦視覺市場規模、佔有率、趨勢和成長分析報告
 智慧駕駛測試解決方案市場:按車輛類型、應用、技術、國家和地區分類-全球產業分析、市場規模、市場佔有率及2026年至2033年預測
 2026年全球智慧道路系統市場報告2026年全球智慧駕駛解決方案市場報告
 智慧道路系統市場-全球產業規模、佔有率、趨勢、機會、預測:按類型、應用、地區和競爭格局分類,2021-2031年
 汽車電腦視覺人工智慧市場機會、成長要素、產業趨勢分析及2026年至2035年預測
 智慧駕駛測試解決方案市場按組件、自動駕駛等級、測試環境、車輛類型和最終用戶分類,全球預測(2026-2032年)
 全球車輛智慧中間件市場預測至2032年:按中間件類型、組件、技術、應用、最終用戶和地區分類全球合約智慧市場:依組件、部署方式、公司規模、應用和地區劃分 - 市場規模、行業趨勢、機會分析和預測(2025-2033 年)