


 |
市場調查報告書
商品編碼
2071200
氣候風險管理市場機會、成長要素、產業趨勢分析及2026-2035年預測Climate Risk Management Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球氣候風險管理市場預計到 2025 年將價值 74 億美元,並將以 14.8% 的複合年成長率成長,到 2035 年達到 303 億美元。
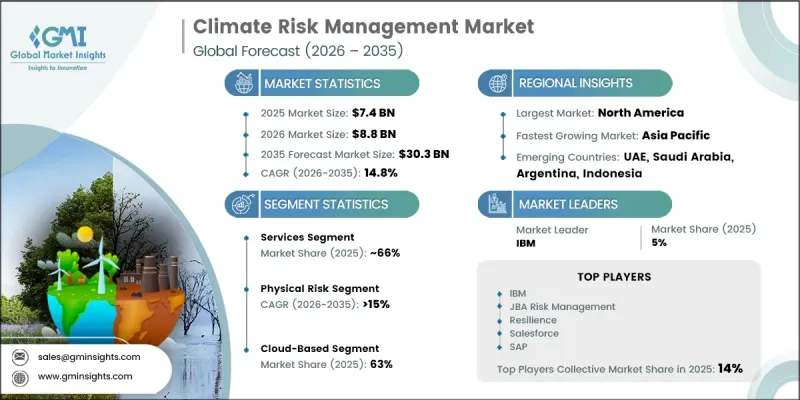
市場成長的驅動力在於,企業越來越需要識別、評估和緩解可能影響長期業務營運和財務表現的氣候相關風險。氣候風險管理市場的一個重大轉變是,人們日益認知到,僅憑傳統的歷史損失資料集已不足以準確評估未來的氣候風險敞口。因此,企業、金融機構和公共部門組織正擴大採用基於情境和機率的建模工具,以提高預測準確性並增強其風險規劃能力。多個地區的法律規範也正從自願報告轉向強制性合規要求,這進一步刺激了對先進氣候風險解決方案的需求。人工智慧、機器學習和氣候數據分析的進步正在進一步提高氣候風險評估的準確性。資料收集能力的提升和高解析度氣候監測系統的完善,使解決方案供應商能夠提供更詳細、更具可操作性的洞察。這些發展趨勢正將氣候風險管理定位為全球各產業企業韌性、合規性和長期策略規劃的關鍵要素。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 74億美元 |
| 預測金額 | 303億美元 |
| 複合年成長率 | 14.8% |
亞太地區氣候風險管理市場正迅速崛起為成長最快的區域市場,其主要驅動力包括日益加劇的氣候變遷相關衝擊、快速的城市化進程以及人們對環境風險管理意識的不斷提高。隨著氣候變遷對經濟和營運的影響日益顯著,該地區的各組織機構越來越重視氣候韌性規劃。對氣候智慧平台、預測分析和風險評估技術的投資不斷增加,推動了公共和私營部門市場的強勁成長。隨著各國政府和企業加強調適策略並提升長期永續性,預計全部區域對氣候風險管理解決方案的需求將顯著成長。
預計到2025年,服務板塊將佔據66%的市場佔有率,並在2026年至2035年間以14%的複合年成長率成長。該板塊的主導地位源於氣候風險緩解專案的複雜性,這些專案通常需要專業知識和客製化解決方案。各組織經常依賴專業服務供應商進行氣候風險建模、合規支援、情境規劃、風險評估框架和資料整合等工作。對客製化諮詢和實施服務日益成長的需求,進一步鞏固了該板塊的市場主導地位。
物理風險領域佔市場佔有率的46%,預計2035年將以15%的複合年成長率成長。隨著氣候變遷相關干擾的日益加劇,各行各業對物理風險評估能力的需求不斷成長。企業、基礎設施營運商和政府機構擴大利用先進的分析和預測智慧工具來評估脆弱性、改善緊急準備策略、最大限度地減少干擾,並為明智的投資決策提供支援。隨著各組織將韌性和長期資產保護置於優先地位,物理風險管理仍然是更廣泛的氣候風險管理產業中的關鍵關注領域。
美國氣候風險管理市場佔88%的佔有率,預計2025年市場規模將達24億美元。隨著氣候變遷相關破壞造成的經濟損失日益增加,美國各地對先進的氣候風險評估和預測解決方案的需求也不斷成長。各組織機構逐漸認知到預測性氣候情報在識別潛在脆弱性、保護關鍵基礎設施、加強業務永續營運計劃以及提高營運韌性方面的重要性。隨著氣候變遷相關的不確定性在企業決策中日益凸顯,氣候風險管理技術在美國各行各業的應用也不斷擴展。
目錄
第1章:調查方法
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率分析
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 極端天氣事件發生的頻率和強度不斷增加,導致人們面臨的風險日益擴大。
- 日益成長的監管壓力和氣候變遷資訊揭露義務(TCFD、CSRD、巴塞爾協議III)
- ESG投資者和機構投資者的影響力日益增強
- 人工智慧驅動的氣候建模和情境分析的進展
- 產業潛在風險與挑戰
- 高品質、標準化的氣候數據供應有限。
- 實施成本高且需要技術專長
- 市場機遇
- 全球金融服務業對氣候風險緩解的需求日益成長
- 擴大綠色基礎設施並管理能夠抵禦氣候變遷的供應鏈
- 氣候變遷帶來的脆弱性和監管協調正在推動新興市場的成長。
- 促進因素
- 成長潛力分析
- 監理情勢
- 北美洲
- 美國證券交易委員會(SEC)氣候變遷資訊揭露要求
- 聯準會氣候情境分析框架
- OSFI 指南 B-15(加拿大)
- 全國保險監督官協會 (NAIC) 氣候風險揭露調查
- 加州氣候企業資料課責法案(SB 253)
- 歐洲
- 企業永續發展報告指令(CSRD)
- 歐洲永續發展報告標準(ESRS)
- 永續金融資訊揭露規則(SFDR)
- 歐盟分類法規
- 歐洲銀行管理局 (EBA) ESG風險管理指南
- 亞太地區
- 中國的環境資訊揭露措施
- 中國綠色金融指南
- 印度的企業責任與永續發展報告(BRSR)
- 新加坡金融管理局(MAS)環境風險管理指南
- 日本金融廳(JFSA)氣候變遷資訊揭露指南
- 拉丁美洲
- 巴西中央銀行關於氣候和環境風險管理的法規
- 巴西證券委員會(CVM)ESG資訊揭露要求
- 墨西哥永續分類框架
- 墨西哥銀行證券委員會(CNBV)關於ESG資訊揭露的指導原則
- 智利金融市場委員會 (CMF) 氣候變遷資訊揭露要求
- 中東和非洲
- 沙烏地綠色措施永續發展報告框架
- 沙烏地阿拉伯資本市場管理局 (CMA) ESG 資訊揭露指南
- 阿拉伯聯合大公國永續金融框架
- 南非氣候變遷法案和氣候風險報告工作
- 約翰內斯堡證券交易所(JSE)關於永續發展和氣候變遷的資訊揭露指南
- 北美洲
- 波特的分析
- PESTLE分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格分析
- 對過去價格趨勢的分析
- 依球員類型分類的定價策略(高級球員、超值球員、成本加成球員)
- 成本細分分析
- 專利分析
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 永續性和環境方面
- 永續計劃
- 減少廢棄物策略
- 生產中的能源效率
- 具有環保意識的舉措
- 考慮碳足跡
- 預測假設和情境分析
- 基本案例:驅動複合年成長率的關鍵宏觀經濟與產業變量
- 樂觀情境:宏觀經濟與產業的順風
- 悲觀情景:宏觀經濟放緩或產業逆風
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 北美洲
- 歐洲
- 亞太地區
- LATAM
- 中東和非洲
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 排名分類標準與遴選標準
- 按銷售額、地區和創新能力分類的層級定位矩陣。
第5章 市場估計與預測:依解法分類,2022-2035年
- 軟體和平台
- 風險評估與情境分析平台
- 氣候風險建模軟體
- 監管報告和合規平台
- 碳計量和排放追蹤軟體
- 綜合氣候風險管理套件
- 服務
- 數據分析服務
- 專業諮詢服務
- 策略與諮詢服務
- 實施和整合服務
- 培訓、支援和管理服務
第6章 市場估計與預測:依風險等級分類,2022-2035年
- 物理風險
- 轉型風險
- 責任風險
第7章 市場估算與預測:依部署模式分類,2022-2035年
- 基於雲端的
- 現場
- 混合
第8章 市場估計與預測:依應用領域分類,2022-2035年
- 碳核算和排放管理
- 災害應變和預警系統
- ESG與永續投資的風險分析
- 天氣與農業風險管理
- 商業和投資風險管理
- 氣候變遷訴訟與責任風險管理
- 監理報告和合規性
- 其他
第9章 市場估計與預測:依最終用途分類,2022-2035年
- BFSI
- 能源與公共產業
- 政府/公共部門
- 房地產和基礎設施
- 農業/林業
- 製造業
- 運輸/物流
- 衛生保健
- 其他
第10章 市場估價與預測:依公司規模分類,2022-2035年
- 大公司
- 小型企業
第11章 市場估價與預測:按地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 北歐的
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 東南亞
- 印尼
- 馬來西亞
- 新加坡
- 泰國
- 越南
- ANZ
- 拉丁美洲
- 巴西
- 阿根廷
- 墨西哥
- 中東和非洲
- UAE
- 沙烏地阿拉伯
- 南非
第12章:公司簡介
- 世界公司
- Fathom Global
- First Street
- IBM(Envizi)
- JBA Risk Management
- Jupiter Intelligence
- Salesforce
- SAP
- XDI(Cross Dependency Initiative)
- 當地公司
- Climate X
- ClimateAi
- Mitiga Solutions
- Resilience
- RiskThinking.AI
- StepChange
- Sust Global
- 新興企業
- Climafin
- Correntics
- Entelligent
- Intensel
- Vyzrd
The Global Climate Risk Management Market was valued at USD 7.4 billion in 2025 and is estimated to grow at a CAGR of 14.8% to reach USD 30.3 billion by 2035.
Market growth is driven by the increasing need for organizations to identify, evaluate, and mitigate climate-related risks that can affect long-term operational and financial performance. A major shift within the climate risk management market is the growing recognition that traditional historical loss datasets are no longer sufficient for accurately assessing future climate exposure. As a result, businesses, financial institutions, and public-sector organizations are increasingly adopting scenario-based and probabilistic modeling tools to improve forecasting accuracy and strengthen risk planning capabilities. Regulatory frameworks across multiple regions are also evolving from voluntary reporting practices toward mandatory compliance requirements, creating additional demand for advanced climate risk solutions. Technological advancements in artificial intelligence, machine learning, and climate data analytics are further enhancing the precision of climate risk assessments. Improved data collection capabilities and higher-resolution climate monitoring systems are enabling solution providers to deliver more detailed and actionable insights. These developments are positioning climate risk management as a critical component of enterprise resilience, regulatory compliance, and long-term strategic planning across industries worldwide.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $7.4 Billion |
| Forecast Value | $30.3 Billion |
| CAGR | 14.8% |
The Asia Pacific climate risk management market is emerging as the fastest-growing regional market, supported by increasing exposure to climate-related disruptions, rapid urban development, and growing awareness of environmental risk management. Organizations throughout the region are placing greater emphasis on climate resilience planning as the economic and operational consequences of changing climate conditions become more pronounced. Rising investments in climate intelligence platforms, predictive analytics, and risk assessment technologies are supporting strong market expansion across both public and private sectors. As governments and enterprises seek to strengthen adaptation strategies and improve long-term sustainability outcomes, demand for climate risk management solutions is expected to accelerate significantly throughout the region.
The services segment accounted for 66% share in 2025 and is anticipated to grow at a CAGR of 14% between 2026 and 2035. The segment's leadership reflects the complex nature of climate risk implementation projects, which often require specialized expertise and customized solutions. Organizations frequently rely on professional service providers for climate risk modeling, regulatory compliance support, scenario planning, risk assessment frameworks, and data integration activities. The growing need for tailored advisory and implementation services continues to reinforce the segment's dominant position within the market.
The physical risk segment held a 46% share and is projected to grow at a CAGR of 15% through 2035. Increasing climate-related disruptions are intensifying demand for physical risk assessment capabilities across industries. Businesses, infrastructure operators, and government agencies are increasingly utilizing advanced analytics and predictive intelligence tools to evaluate vulnerabilities, improve preparedness strategies, minimize operational disruptions, and support informed investment decisions. As organizations prioritize resilience and long-term asset protection, physical risk management remains a key focus area within the broader climate risk management industry.
United States Climate Risk Management Market held an 88% share, generating USD 2.4 billion in 2025. Growing economic losses associated with climate-related disruptions are increasing demand for sophisticated climate risk assessment and forecasting solutions across the country. Organizations are recognizing the importance of predictive climate intelligence for identifying potential vulnerabilities, protecting critical infrastructure, strengthening business continuity planning, and improving operational resilience. As climate-related uncertainties become a greater consideration in corporate decision-making, adoption of climate risk management technologies continues to expand across multiple sectors within the United States.
Leading companies operating in the global climate risk management market include IBM, SAP, Salesforce, JBA Risk Management, Resilience, First Street, and Fathom Global. Companies in the climate risk management market are implementing a range of strategies to strengthen their market position and expand their customer base. Major industry participants are investing heavily in artificial intelligence, machine learning, and advanced analytics to improve the accuracy and scalability of climate risk assessments. Strategic partnerships with financial institutions, government agencies, and sustainability organizations are helping companies broaden their market reach and enhance solution capabilities. Many providers are expanding their service portfolios by integrating climate intelligence, regulatory compliance tools, and scenario modeling platforms into comprehensive risk management ecosystems. Businesses are also focusing on product innovation, cloud-based deployment models, and real-time data integration to improve user experience and decision-making capabilities.
Table of Contents
Chapter 1 Methodology
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.2 Sources, by region
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Solution
- 2.2.2 Risk
- 2.2.3 Deployment Mode
- 2.2.4 Application
- 2.2.5 Enterprise Size
- 2.2.6 End Use
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin analysis
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Increasing frequency and intensity of extreme weather events amplifying risk exposure
- 3.2.1.2 Mounting regulatory pressure and mandatory climate disclosure requirements (TCFD, CSRD, Basel III)
- 3.2.1.3 Growing influence of ESG investors and institutional capital allocators
- 3.2.1.4 Advances in AI-powered climate modeling and scenario analytics
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 Limited availability of high-quality, standardized climate data
- 3.2.2.2 High implementation costs and technical expertise requirements
- 3.2.3 Market opportunities
- 3.2.3.1 Growing demand for climate risk solutions in global financial services
- 3.2.3.2 Expansion of green infrastructure and climate-resilient supply chain management
- 3.2.3.3 Emerging market adoption driven by climate vulnerability and regulatory convergence
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.1.1 U.S. Securities and Exchange Commission (SEC) Climate Disclosure Requirements
- 3.4.1.2 Federal Reserve Climate Scenario Analysis Framework
- 3.4.1.3 Office of the Superintendent of Financial Institutions (OSFI) Guideline B-15 (Canada)
- 3.4.1.4 National Association of Insurance Commissioners (NAIC) Climate Risk Disclosure Survey
- 3.4.1.5 California Climate Corporate Data Accountability Act (SB 253)
- 3.4.2 Europe
- 3.4.2.1 Corporate Sustainability Reporting Directive (CSRD)
- 3.4.2.2 European Sustainability Reporting Standards (ESRS)
- 3.4.2.3 Sustainable Finance Disclosure Regulation (SFDR)
- 3.4.2.4 EU Taxonomy Regulation
- 3.4.2.5 European Banking Authority (EBA) ESG Risk Management Guidelines
- 3.4.3 Asia Pacific
- 3.4.3.1 China Environmental Information Disclosure Measures
- 3.4.3.2 China Green Finance Guidelines
- 3.4.3.3 India Business Responsibility and Sustainability Reporting (BRSR)
- 3.4.3.4 Monetary Authority of Singapore (MAS) Environmental Risk Management Guidelines
- 3.4.3.5 Japan Financial Services Agency (JFSA) Climate Disclosure Guidance
- 3.4.4 Latin America
- 3.4.4.1 Brazil Central Bank Climate and Environmental Risk Management Regulations
- 3.4.4.2 Brazilian Securities Commission (CVM) ESG Disclosure Requirements
- 3.4.4.3 Mexico Sustainable Taxonomy Framework
- 3.4.4.4 Mexico Banking and Securities Commission (CNBV) ESG Disclosure Guidelines
- 3.4.4.5 Chile Financial Market Commission (CMF) Climate Disclosure Requirements
- 3.4.5 Middle East & Africa
- 3.4.5.1 Saudi Green Initiative Sustainability Reporting Framework
- 3.4.5.2 Saudi Capital Market Authority (CMA) ESG Disclosure Guidelines
- 3.4.5.3 UAE Sustainable Finance Framework
- 3.4.5.4 South African Climate Change Bill and Climate Risk Reporting Initiatives
- 3.4.5.5 Johannesburg Stock Exchange (JSE) Sustainability and Climate Disclosure Guidance
- 3.4.1 North America
- 3.5 Porter's analysis
- 3.6 PESTEL analysis
- 3.7 Technology and innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price analysis (Driven by Primary Research)
- 3.8.1 Historical Price Trend Analysis
- 3.8.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
- 3.9 Cost breakdown analysis
- 3.10 Patent analysis (Driven by Primary Research)
- 3.11 Impact of AI & generative AI on the market
- 3.11.1 AI-driven disruption of existing business models
- 3.11.2 GenAI use cases & adoption roadmap by segment
- 3.11.3 Risks, limitations & regulatory considerations
- 3.12 Sustainability and environmental aspects
- 3.12.1 Sustainable practices
- 3.12.2 Waste reduction strategies
- 3.12.3 Energy efficiency in production
- 3.12.4 Eco-friendly Initiatives
- 3.12.5 Carbon footprint considerations
- 3.13 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.13.1 Base Case - key macro & industry variables driving CAGR
- 3.13.2 Optimistic Scenarios - Favorable macro and industry tailwinds
- 3.13.3 Pessimistic Scenario - Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 LATAM
- 4.2.5 MEA
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New Product Launches
- 4.5.4 Expansion Plans and funding
- 4.6 Company tier benchmarking
- 4.6.1 Tier classification criteria & qualifying thresholds
- 4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates & Forecast, By Solution, 2022 - 2035 ($Mn)
- 5.1 Key trends
- 5.2 Software & Platforms
- 5.2.1 Risk Assessment & Scenario Analysis Platforms
- 5.2.2 Climate Risk Modeling Software
- 5.2.3 Regulatory Reporting & Compliance Platforms
- 5.2.4 Carbon Accounting & Emissions Tracking Software
- 5.2.5 Integrated Climate Risk Management Suites
- 5.3 Services
- 5.3.1 Data & Analytics Services
- 5.3.2 Professional & Consulting Services
- 5.3.2.1 Strategy & Advisory Services
- 5.3.2.2 Implementation & Integration Services
- 5.3.2.3 Training, Support & Managed Services
Chapter 6 Market Estimates & Forecast, By Risk, 2022 - 2035 ($Mn)
- 6.1 Key trends
- 6.2 Physical Risk
- 6.3 Transition Risk
- 6.4 Liability Risk
Chapter 7 Market Estimates & Forecast, By Deployment Mode, 2022 - 2035 ($Mn)
- 7.1 Key trends
- 7.2 Cloud-Based
- 7.3 On-Premises
- 7.4 Hybrid
Chapter 8 Market Estimates & Forecast, By Application, 2022 - 2035 ($Mn)
- 8.1 Key trends
- 8.2 Carbon Accounting & Emissions Management
- 8.3 Disaster Preparedness & Early Warning Systems
- 8.4 ESG & Sustainable Investment Risk Analysis
- 8.5 Weather & Agriculture Risk Management
- 8.6 Business & Investment Risk Management
- 8.7 Climate Litigation & Liability Risk Management
- 8.8 Regulatory Reporting & Compliance
- 8.9 Others
Chapter 9 Market Estimates & Forecast, By End Use, 2022 - 2035 ($Mn)
- 9.1 Key trends
- 9.2 BFSI
- 9.3 Energy & Utilities
- 9.4 Government & Public Sector
- 9.5 Real Estate & Infrastructure
- 9.6 Agriculture & Forestry
- 9.7 Manufacturing
- 9.8 Transportation & Logistics
- 9.9 Healthcare
- 9.10 Others
Chapter 10 Market Estimates & Forecast, By Enterprise Size, 2022 - 2035 ($Mn)
- 10.1 Key trends
- 10.2 Large Enterprises
- 10.3 SME
Chapter 11 Market Estimates & Forecast, By Region, 2022 - 2035 ($Mn, Units)
- 11.1 Key trends
- 11.2 North America
- 11.2.1 U.S.
- 11.2.2 Canada
- 11.3 Europe
- 11.3.1 UK
- 11.3.2 Germany
- 11.3.3 France
- 11.3.4 Italy
- 11.3.5 Spain
- 11.3.6 Russia
- 11.3.7 Nordics
- 11.4 Asia Pacific
- 11.4.1 China
- 11.4.2 India
- 11.4.3 Japan
- 11.4.4 South Korea
- 11.4.5 Southeast Asia
- 11.4.5.1 Indonesia
- 11.4.5.2 Malaysia
- 11.4.5.3 Singapore
- 11.4.5.4 Thailand
- 11.4.5.5 Vietnam
- 11.4.6 ANZ
- 11.5 Latin America
- 11.5.1 Brazil
- 11.5.2 Argentina
- 11.5.3 Mexico
- 11.6 MEA
- 11.6.1 UAE
- 11.6.2 Saudi Arabia
- 11.6.3 South Africa
Chapter 12 Company Profiles
- 12.1 Global Players
- 12.1.1 Fathom Global
- 12.1.2 First Street
- 12.1.3 IBM (Envizi)
- 12.1.4 JBA Risk Management
- 12.1.5 Jupiter Intelligence
- 12.1.6 Salesforce
- 12.1.7 SAP
- 12.1.8 XDI (Cross Dependency Initiative)
- 12.2 Regional Players
- 12.2.1 Climate X
- 12.2.2 ClimateAi
- 12.2.3 Mitiga Solutions
- 12.2.4 Resilience
- 12.2.5 RiskThinking.AI
- 12.2.6 StepChange
- 12.2.7 Sust Global
- 12.3 Emerging Players
- 12.3.1 Climafin
- 12.3.2 Correntics
- 12.3.3 Entelligent
- 12.3.4 Intensel
- 12.3.5 Vyzrd

 氣候變遷諮詢:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 氣候變遷諮詢市場:規模、佔有率、成長、全球產業分析、區域趨勢及2026年至2034年預測氣候風險分析市場規模、佔有率、成長、全球產業分析、區域趨勢及2026-2034年預測
 氣候風險融資平台市場預測至2034年:按風險類型、金融用例、分析能力、部署模式和最終用戶分類的全球分析
 全球氣候風險管理市場(至2031年):依軟體及交付方式分類
 巨量資料、物聯網和氣候變遷市場:按組件、連接方式、應用和產業分類-2026年至2032年全球市場預測
 2026年全球天基氣候工程市場報告2026年全球氣候變遷諮詢市場報告城市噪音映射市場預測至2034年-按組件、部署模式、噪音類型、應用、最終用戶和地區分類的全球分析
 氣候風險市場:依服務類型、產業和地區分類