


 |
市場調查報告書
商品編碼
2071165
可攜式包裝機市場機會、成長促進因素、產業趨勢分析及2026-2035年預測Portable Packaging Machines Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球可攜式包裝機市場預計到 2025 年將達到 37 億美元,年複合成長率為 6.7%,到 2035 年將達到 70 億美元。
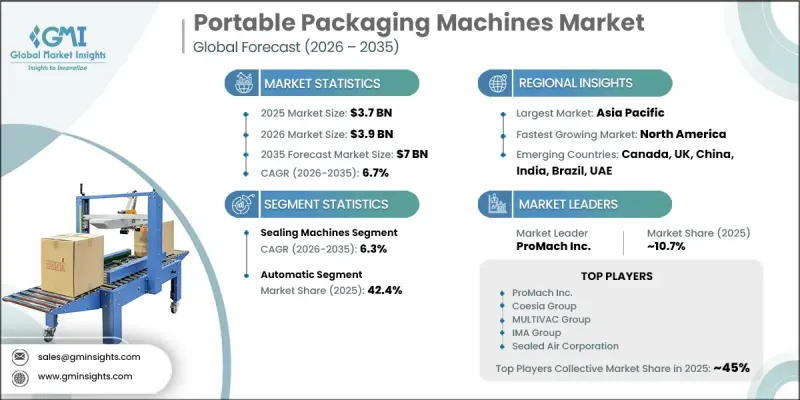
這一成長主要得益於分散式物流網路的快速發展、對模組化生產系統日益成長的依賴,以及中小型製造商對無需改動固定基礎設施即可重新配置的、資本效率高的設備的偏好。向敏捷製造模式的轉變——包裝作業必須快速適應不斷變化的需求模式——也對市場產生了積極影響。可攜式包裝系統因其操作靈活、易於安裝且能適應各種生產環境,正擴大應用於分散式履約環境中。從靜態的集中式包裝線轉向靈活的按需配置的轉變,正在重塑各行業的設備採購趨勢。對更高自動化程度和效率的需求不斷成長,進一步強化了對能夠在動態生產環境中運作的緊湊型高性能包裝系統的需求,從而推動了可攜式包裝機械市場的長期成長。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 起始金額 | 37億美元 |
| 預測金額 | 70億美元 |
| 複合年成長率 | 6.7% |
預計到2025年,封口機市場銷售額將達到8.079億美元,並在2035年之前以6.3%的複合年成長率成長。此類別涵蓋多種設備,例如脈衝式封口機、真空封口系統、熱封機和帶式封口解決方案。封口在幾乎所有包裝流程中都扮演著至關重要的角色,這支撐了該細分市場的強勁地位。封口機在各行業的廣泛應用確保了其穩定的需求,使其成為可攜式包裝機械市場中最基礎、最穩定的細分市場之一。
預計到2025年,自動化可攜式包裝機的市佔率將達到42.4%,並在2035年之前以7.1%的複合年成長率成長。這一強勁成長主要歸功於自動化技術的日益普及,旨在提高生產效率並減少對人工的依賴。企業越來越重視那些能夠提供更高處理能力、更佳一致性和更低長期營運成本的系統,即使這意味著更高的初始投資。這種轉變正在加速全自動可攜式包裝解決方案在工業應用領域的普及。
預計到2025年,北美可攜式包裝機械市場規模將達到9.96億美元,市場佔有率為27.2%,預計在2035年之前以7%的複合年成長率成長。電子商務的擴張、物流基礎設施的持續投資以及對包裝合規標準的日益重視是推動市場發展的主要因素。線上零售在整體商業活動中佔有率的不斷成長,進一步增強了整個履約配送網路對可攜式包裝設備的需求。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 每個階段增加的價值
- 影響價值鏈的因素
- 影響產業的因素
- 成長促進因素
- 電子商務活動的擴張以及最後一公里包裝需求的成長
- 擴大中小企業對靈活、低成本包裝解決方案的採用。
- 各行各業的包裝需求都在快速成長,無論是現場包裝還是移動包裝。
- 加強對防篡改和合規包裝的監管要求。
- 產業潛在風險與挑戰
- 跨境法規結構內標準化的不一致
- 來自未經授權製造商的仿冒品和低價替代品
- 透過維護現場部署的可攜式設備來減少停機時間
- 滿足永續性和循環經濟監管要求的壓力
- 機會
- 攜帶式包裝在分銷領域向新興市場和農村地區擴展
- 野外作業中對無線和電池供電的可攜式設備的需求日益成長。
- 智慧感測器和預測性維護功能的整合
- 在醫藥低溫運輸和醫療設備包裝領域得到更廣泛的應用。
- 成長促進因素
- 成長潛力分析
- 未來市場趨勢
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 監理情勢
- 標準和合規要求
- 區域監理框架
- 認證標準
- 貿易數據分析
- 進出口量及進口額趨勢
- 主要貿易路線及關稅的影響
- 價格分析
- 對過去價格趨勢的分析
- 按業務類型(高階/低階/大眾市場)分類的定價策略
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 波特的分析
- PESTLE分析
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 企業矩陣分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃
第5章 市場估價與預測:依機器類型分類,2022-2035年
- 封口機
- 包裝/裝訂機
- 裝袋機
- 封蓋機
- 貼標機
- FFS(成型、填充、封口)機
第6章 市場估計與預測:依營運模式分類,2022-2035年
- 自動的
- 半自動
- 手動的
第7章 市場估計與預測:依動力來源,2022-2035年
- 電的
- 電池供電
- 氣動型
- 手動的
第8章 市場估算與預測:依最終用途產業分類,2022-2035年
- 食品/飲料
- 藥品和醫療保健
- 電子商務與零售
- 化妝品和個人護理
- 工業和化學
- 電子設備
第9章 市場估價與預測:依通路分類,2022-2035年
- 直銷
- 間接銷售
第10章 市場估價與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 澳洲
- 印尼
- 馬來西亞
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 沙烏地阿拉伯
- UAE
- 南非
第11章:公司簡介
- MULTIVAC Group
- Syntegon Technology GmbH
- Matrix Packaging Machinery
- IMA Group
- Volpak
- Reepack
- ULMA Packaging
- SEALPAC International BV
- Hualian Machinery Group Co., Ltd.
- Foshan Soonk Packaging Machine Co., Ltd.
- Minipack-Torre SpA
- Wenzhou JOIE Machinery Co., Ltd.
- Accu-Seal Corporation
- Kinex Cappers LLC
- KHS Group
The Global Portable Packaging Machines Market was valued at USD 3.7 billion in 2025 and is estimated to grow at a CAGR of 6.7% to reach USD 7 billion in 2035.
Growth is supported by the rapid evolution of distributed logistics networks, increasing reliance on modular production setups, and the growing preference among small and medium-scale manufacturers for capital-efficient equipment that can be repositioned without requiring fixed infrastructure changes. The market is also benefiting from the shift toward agile manufacturing models, where packaging operations must adapt quickly to fluctuating demand patterns. Portable packaging systems are increasingly being adopted across decentralized fulfillment environments due to their operational mobility, reduced installation complexity, and adaptability across production settings. The transition from static, centralized packaging lines to flexible, demand-responsive configurations is reshaping equipment purchasing behavior across industries. Rising automation levels and efficiency requirements are further strengthening demand for compact, high-performance packaging systems capable of operating in dynamic production environments, reinforcing the long-term growth trajectory of the portable packaging machines market.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $3.7 Billion |
| Forecast Value | $7 Billion |
| CAGR | 6.7% |
The sealing machines segment generated USD 807.9 million in 2025 and is expected to grow at a CAGR of 6.3% through 2035. This category includes a wide range of equipment such as impulse sealers, vacuum sealing systems, heat sealing machines, and band sealing solutions. The strong position of this segment is supported by the essential role sealing plays across nearly all packaging operations. Its widespread applicability across diverse industries ensures consistent demand, making it one of the most fundamental and stable segments within the portable packaging machines landscape.
Automatic portable packaging machines accounted for 42.4% share in 2025 and are projected to grow at a CAGR of 7.1% through 2035. The strong performance of this segment is largely attributed to the increasing adoption of automation to improve productivity and reduce operational dependence on manual labor. Businesses are increasingly prioritizing systems that deliver higher throughput, improved consistency, and lower long-term operating costs, even if they require higher initial investment. This shift is accelerating the adoption of fully automated portable packaging solutions across industrial applications.
North America Portable Packaging Machines Market held a 27.2% share in 2025, reaching USD 996 million and is expected to grow at a CAGR of 7% through 2035. Expansion in e-commerce operations, ongoing investment in logistics infrastructure, and increasing emphasis on packaging compliance standards are key factors supporting market development. The growing share of online retail within total commerce activity is further strengthening demand for portable packaging equipment across fulfillment and distribution networks.
Major companies operating in the global portable packaging machines market include MULTIVAC Group, Syntegon Technology GmbH, Matrix Packaging Machinery, IMA Group, Volpak, Reepack, ULMA Packaging, SEALPAC International BV, Hualian Machinery Group Co., Ltd., Foshan Soonk Packaging Machine Co., Ltd., Minipack-Torre SpA, Wenzhou JOIE Machinery Co., Ltd., Accu-Seal Corporation, Kinex Cappers LLC, KHS Group, ProMach Inc., Coesia Group, and Sealed Air Corporation. Companies operating in the portable packaging machines market are focusing on several strategic initiatives to strengthen their market position and enhance competitiveness. A key approach involves increasing investment in automation technologies to improve machine efficiency, speed, and operational precision. Manufacturers are also prioritizing modular and lightweight designs that enhance portability and simplify deployment across diverse production environments. Expansion of product portfolios through technological upgrades and integration of smart control systems is another major strategy. Companies are strengthening global distribution networks and forming partnerships with logistics and manufacturing firms to expand market reach.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Machine type
- 2.2.3 Mode of operation
- 2.2.4 Power source
- 2.2.5 End-use industry
- 2.2.6 Distribution channel
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising e-commerce activity & last-mile packaging demand
- 3.2.1.2 Growing SME adoption of flexible, low-capex packaging solutions
- 3.2.1.3 Surge in on-site & mobile packaging requirements across industries
- 3.2.1.4 Increasing regulatory mandates for tamper-evident & compliant packaging
- 3.2.2 Industry pitfalls & challenges
- 3.2.2.1 Standardization gaps across cross-border regulatory frameworks
- 3.2.2.2 Counterfeiting & low-cost substitutes from unorganized manufacturers
- 3.2.2.3 Managing maintenance downtime for field-deployed portable units
- 3.2.2.4 Pressure to meet sustainability & circular economy mandates
- 3.2.3 Opportunities
- 3.2.3.1 Expansion of portable packaging into emerging markets & rural distribution
- 3.2.3.2 Growing demand for cordless & battery-powered portable units in field operations
- 3.2.3.3 Integration of smart sensors & predictive maintenance capabilities
- 3.2.3.4 Rising adoption in pharmaceutical cold chain & medical device packaging
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Future market trends
- 3.5 Technology and innovation landscape
- 3.5.1 Current technological trends
- 3.5.2 Emerging technologies
- 3.6 Regulatory landscape
- 3.6.1 Standards and compliance requirements
- 3.6.2 Regional regulatory frameworks
- 3.6.3 Certification standards
- 3.7 Trade data analysis (HS Code 8422)
- 3.7.1 Import/export volume & value trends
- 3.7.2 Key trade corridors & tariff impact
- 3.8 Pricing analysis
- 3.8.1 Historical price trend analysis (driven by primary research)
- 3.8.2 Pricing strategy by player type (premium / value / mass market)
- 3.9 Impact of AI & generative AI on the market
- 3.9.1 AI-driven disruption of existing business models
- 3.9.2 GenAI use cases & adoption roadmap by segment
- 3.9.3 Risks, limitations & regulatory considerations
- 3.10 Porter's analysis
- 3.11 PESTEL analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By Region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.1 By Region
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates & Forecast, By Machine Type, 2022 - 2035, (USD Million) (Thousand Units)
- 5.1 Key trends
- 5.2 Sealing machines
- 5.3 Wrapping & strapping machines
- 5.4 Bagging machines
- 5.5 Capping machines
- 5.6 Labeling machines
- 5.7 Form-fill-seal (FFS) machines
Chapter 6 Market Estimates & Forecast, By Mode of Operation, 2022 - 2035, (USD Million) (Thousand Units)
- 6.1 Key trends
- 6.2 Automatic
- 6.3 Semi-automatic
- 6.4 Manual
Chapter 7 Market Estimates & Forecast, By Power Source, 2022 - 2035, (USD Million) (Thousand Units)
- 7.1 Key trends
- 7.2 Electric
- 7.3 Battery-powered
- 7.4 Pneumatic
- 7.5 Manual
Chapter 8 Market Estimates & Forecast, By End-Use Industry, 2022 - 2035, (USD Million) (Thousand Units)
- 8.1 Key trends
- 8.2 Food & beverage
- 8.3 Pharmaceutical & medical
- 8.4 E-commerce & retail
- 8.5 Cosmetics & personal care
- 8.6 Industrial & chemical
- 8.7 Electronics
Chapter 9 Market Estimates & Forecast, By Distribution Channel, 2022 - 2035, (USD Million) (Thousand Units)
- 9.1 Key trends
- 9.2 Direct sales
- 9.3 Indirect sales
Chapter 10 Market Estimates & Forecast, By Region, 2022 - 2035, (USD Million) (Thousand Units)
- 10.1 Key trends
- 10.2 North America
- 10.2.1 U.S.
- 10.2.2 Canada
- 10.3 Europe
- 10.3.1 Germany
- 10.3.2 UK
- 10.3.3 France
- 10.3.4 Italy
- 10.3.5 Spain
- 10.4 Asia Pacific
- 10.4.1 China
- 10.4.2 India
- 10.4.3 Japan
- 10.4.4 South Korea
- 10.4.5 Australia
- 10.4.6 Indonesia
- 10.4.7 Malaysia
- 10.5 Latin America
- 10.5.1 Brazil
- 10.5.2 Mexico
- 10.5.3 Argentina
- 10.6 MEA
- 10.6.1 Saudi Arabia
- 10.6.2 UAE
- 10.6.3 South Africa
Chapter 11 Company Profiles
- 11.1 MULTIVAC Group
- 11.2 Syntegon Technology GmbH
- 11.3 Matrix Packaging Machinery
- 11.4 IMA Group
- 11.5 Volpak
- 11.6 Reepack
- 11.7 ULMA Packaging
- 11.8 SEALPAC International BV
- 11.9 Hualian Machinery Group Co., Ltd.
- 11.10 Foshan Soonk Packaging Machine Co., Ltd.
- 11.11 Minipack-Torre SpA
- 11.12 Wenzhou JOIE Machinery Co., Ltd.
- 11.13 Accu-Seal Corporation
- 11.14 Kinex Cappers LLC
- 11.15 KHS Group

 桌上型製冰機:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)
 2026年全球製冰機市場報告
 可重複使用冰塊市場 - 全球產業規模、佔有率、趨勢、機會、預測:按應用、材料、分銷管道、地區和競爭格局分類,2021-2031年
 製冰冷藏庫市場報告:趨勢、預測與競爭分析(至2035年)
 製冰機市場規模、佔有率、趨勢和預測:按產品類型、最終用途和地區分類,2026-2034 年
 商用製冰機市場:2026-2032年全球市場預測(按型號、冷凝器類型、製冰能力、冰的類型、最終用戶和銷售管道)製冰機市場:2026-2032年全球市場預測(依產品、技術、製冰方法、運作狀態、產能、應用及通路分類)管式製冰機市場:依產品類型、產能、應用、終端用戶及通路分類-2026-2032年全球預測
 全球管式製冰機市場規模、佔有率、趨勢及成長分析報告(2026-2034年)桌上型製冰機市場-全球產業規模、佔有率、趨勢、機會和預測:按類型、應用、分銷管道、地區和競爭格局分類,2021-2031年