


 |
市場調查報告書
商品編碼
2061344
飛機輔助動力裝置(APU)市場機會、成長要素、產業趨勢分析及2026-2035年預測Aircraft Auxiliary Power Unit (APU) Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

預計到 2025 年,全球飛機輔助動力裝置 (APU) 市場規模將達到 70 億美元,並以 7.3% 的複合年成長率成長,到 2035 年達到 140 億美元。
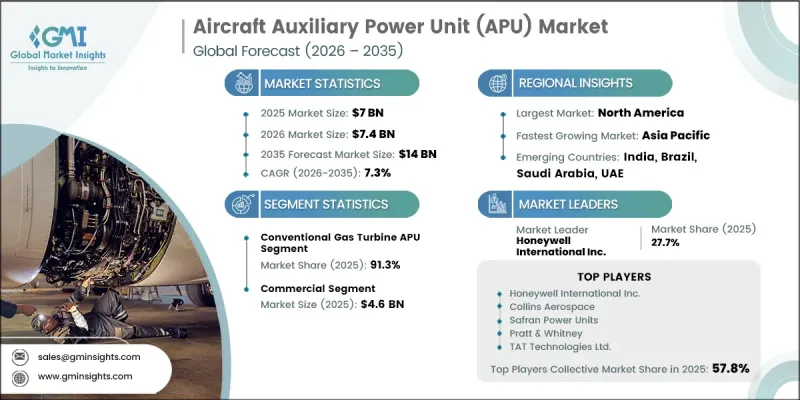
飛機輔助動力裝置(APU)產業的整體成長主要受以下因素驅動:機身的持續現代化、飛機運作週期的延長以及飛行頻率提高所帶來的維護需求增加。航空公司和國防營運商優先考慮高效可靠的輔助系統,這促使他們對先進的機載電源技術加大投資,從而推動了產業的擴張。與傳統的渦輪系統相比,混合動力和燃料電池APU效率更高,成本也更高,因此其應用創造了更多商機。此外,隨著飛機平台向「全改裝」化轉型,現代輔助動力解決方案在維修和工廠出貨時裝載應用中都成為不可或缺的組件,市場需求也隨之成長。全球航空運輸量的成長、飛機產量的增加以及對自主機載電源供給能力的日益青睞,都將持續增強民用和軍用航空領域的長期市場需求。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 70億美元 |
| 預測金額 | 140億美元 |
| 複合年成長率 | 7.3% |
飛機輔助動力裝置(APU)產業持續成長,這主要得益於全球飛機交付量的穩定提升。運作中。機隊規模的擴大不僅強勁推動了新機Line-Fit需求,也隨著飛機運作的累積,催生了對長期維護和大修的需求。此外,航空公司越來越重視獨立的機載發電系統,以減少飛機週轉過程中對機場基礎設施的依賴。這一趨勢在地面支援能力有限的區域機場和新興航空樞紐地區催生了更強勁的採購需求。營運柔軟性的提升、週轉效率的提高以及對機場基礎設施依賴性的降低,都進一步促進了市場成長。
預計到2035年,混合動力電動輔助動力裝置(APU)市場將以15.3%的複合年成長率成長。日益嚴格的環保法規和下一代飛機項目的研發正推動航空公司和營運商採用更節能的機載動力技術。電力推進系統和整合式飛機動力架構的進步進一步加速了這些技術的普及。隨著製造商持續關注永續航空技術和低排放飛機解決方案,該行業的長期發展潛力預計將保持強勁。
預計到2025年,商用飛機市場規模將達46億美元。該市場的成長主要得益於全球龐大的商用飛機機隊以及日常維護、修理和大修(MRO)活動。高飛機運轉率持續推動輔助動力系統和替換零件的售後市場需求穩定成長。航空公司網路的不斷擴張、客運量的成長以及航線頻率的提高,也為民航業的持續需求做出了貢獻。大規模和持續的維護需求進一步鞏固了該市場領域的主導地位。
到2025年,北美飛機輔助動力裝置(APU)市佔率將達到37.4%。支線飛機市場持續受益於高飛機運轉率和嚴格的維修法規,這些法規要求對APU進行系統性的檢查和大修。民用和支線飛機機隊的穩定運作支撐了全部區域強勁的售後市場需求。同時,持續的飛機生產和新飛機的交付推動了原始設備製造商(OEM)對先進輔助動力系統的需求。成熟的航太製造商、完善的航空基礎設施和持續的技術投資進一步促進了支線市場的擴張。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 世界飛機機隊的擴張
- 飛機現代化和維修計畫的增加
- 航空旅客人數增加
- 擴大飛機維修、修理和大修 (MRO) 活動
- 人們越來越關注如何最佳化飛機運作效率和地面保障。
- 產業潛在風險與挑戰
- 先進輔助動力裝置(APU)系統的高成本和複雜性
- 供應鏈中斷與零件採購挑戰
- 市場機遇
- 混合動力和純電動飛機架構的融合
- 數位輔助動力裝置 (APU) 監控和預測性維護的進展
- 促進因素
- 成長潛力分析
- 監理情勢
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 波特的分析
- PESTLE分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格趨勢
- 按地區
- 依產品
- 定價策略
- 新興經營模式
- 合規要求
- 專利和智慧財產權分析
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 市場集中度分析
- 按地區
- 主要公司的競爭標竿分析
- 財務績效比較
- 收入
- 利潤率
- R&D
- 產品系列比較
- 產品線寬度
- 科技
- 創新
- 區域擴張比較
- 全球擴張分析
- 服務網路覆蓋
- 按地區分類的市場滲透率
- 競爭定位矩陣
- 領導者
- 挑戰者
- 追蹤者
- 小眾玩家
- 戰略展望矩陣
- 財務績效比較
- 主要進展
- 併購
- 夥伴關係和聯盟
- 技術進步
- 擴張和投資策略
- 數位轉型計劃
- 新興企業競爭公司和新創企業的發展趨勢
第5章 市場估計與預測:依技術類型分類,2022-2035年
- 主要趨勢
- 傳統燃氣渦輪機動力裝置
- 混合動力輔助動力裝置(APU)
- 電動/電池驅動輔助動力裝置
- 燃料電池輔助動力裝置(APU)
- 最終用戶
第6章 市場估算與預測:依飛機平台分類,2022-2035年
- 商業航空
- 窄體飛機
- 寬體飛機
- 支線噴射機
- 軍事航空
- 戰鬥機和作戰飛機
- 運輸和加油設備
- 特種任務平台
- 商務及通用航空
- 公務機
- 小型通用飛機
- 旋翼飛機
- 商用直升機
- 軍用直升機
- 無人駕駛飛行器(UAV)
- 中高度,遠程(男性)
- 高空遠端(HALE)
第7章 市場估算與預測:額定功率,2022-2035年
- 低功率APU(小於50 kVA)
- 中功率輔助動力裝置(50-150 kVA)
- 高功率輔助動力裝置(>150 kVA)
第8章 市場估算與預測:依銷售管道分類,2022-2035年
- OEM(Line-Fit/全新安裝)
- 售後市場
第9章 市場估價與預測:依最終用戶分類,2022-2035年
- 軍隊
- 商業
- 私人/政府
第10章 市場估價與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 俄羅斯
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第11章:公司簡介
- 全球主要公司
- Honeywell International Inc.
- Collins Aerospace
- Safran Power Units
- Pratt &Whitney
- TAT Technologies Ltd.
- 該地區的主要公司
- 北美洲
- Hamilton Sundstrand
- Dewey Electronics Corporation
- 亞太地區
- Aerosila JSC
- Klimov
- Motor Sich JSC
- Technodinamika
- 歐洲
- PBS Aerospace Inc.
- Microturbo
- Jenoptik AG
- Middle East &Africa
- Kinetics Ltd.
- 北美洲
The Global Aircraft Auxiliary Power Unit Market accounted for USD 7 billion in 2025 and is estimated to grow at a CAGR of 7.3% to reach USD 14 billion by 2035.
Growth across the aircraft auxiliary power unit industry is being fueled by continuous fleet modernization, increasing aircraft operational cycles, and higher maintenance requirements linked to rising flight frequencies. Growing investments in advanced onboard power technologies are also supporting industry expansion as airlines and defense operators prioritize efficient and reliable auxiliary systems. The adoption of hybrid-electric and fuel-cell-powered APUs is creating additional revenue opportunities due to their enhanced efficiency and premium pricing compared to traditional turbine-based systems. Demand is also benefiting from the transition toward more-electric aircraft platforms, where modern auxiliary power solutions are becoming essential components in both retrofit and factory-installed applications. Expanding global air traffic, rising aircraft production, and increasing preference for self-sufficient onboard power capabilities continue to strengthen long-term market demand across commercial and military aviation sectors.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $7 Billion |
| Forecast Value | $14 Billion |
| CAGR | 7.3% |
The aircraft auxiliary power unit industry continues to gain momentum due to the steady rise in worldwide aircraft deliveries, which is increasing the number of active aircraft equipped with onboard power systems across both defense and commercial aviation. The expanding fleet base is driving strong line-fit demand while also generating long-term servicing and overhaul requirements as aircraft accumulate operational hours. In addition, airlines are increasingly prioritizing independent onboard power generation to reduce reliance on airport-based support infrastructure during turnaround procedures. This trend is creating stronger procurement demand at regional airports and developing aviation hubs where ground support capabilities remain limited. Greater operational flexibility, improved turnaround efficiency, and reduced dependence on airport infrastructure are further contributing to market growth.
The hybrid-electric APU segment is forecast to witness a CAGR of 15.3% throughout 2035. Growing environmental regulations and the development of next-generation aircraft programs are encouraging airlines and operators to adopt more energy-efficient onboard power technologies. Increasing advancements in electric propulsion systems and integrated aircraft power architectures are further accelerating adoption. Long-term industry potential is expected to remain strong as manufacturers continue to focus on sustainable aviation technologies and low-emission aircraft solutions.
The commercial segment generated USD 4.6 billion in 2025. Segment growth is primarily supported by extensive global commercial aircraft fleets and recurring maintenance, repair, and overhaul activities. High aircraft utilization rates continue to create stable aftermarket demand for auxiliary power systems and replacement components. Ongoing airline network expansion, rising passenger traffic, and increasing route frequencies are also contributing to sustained demand across the commercial aviation sector. The large installed fleet base and consistent servicing requirements continue to reinforce the segment's leading market position.
North America Aircraft Auxiliary Power Unit Market held a 37.4% share in 2025. The regional market continues to benefit from high aircraft usage rates and strict maintenance regulations that require structured APU inspection and overhaul cycles. Consistent aircraft operations across commercial and regional aviation fleets are supporting strong aftermarket demand throughout the region. At the same time, continuous aircraft production and new fleet deliveries are strengthening OEM installation demand for advanced auxiliary power systems. The presence of established aerospace manufacturers, extensive aviation infrastructure, and ongoing technological investments further support regional market expansion.
Key companies operating in the Global Aircraft Auxiliary Power Unit Market include Honeywell International Inc., Pratt & Whitney, Safran Power Units, Collins Aerospace, Hamilton Sundstrand, PBS Aerospace Inc., Aerosila JSC, Klimov, TAT Technologies Ltd., Technodinamika, Motor Sich JSC, Microturbo, Jenoptik AG, Dewey Electronics Corporation, and Kinetics Ltd. Companies operating in the aircraft auxiliary power unit market are focusing on advanced product innovation, strategic collaborations, and long-term supply agreements to strengthen their market position. Leading manufacturers are investing heavily in hybrid-electric and fuel-efficient APU technologies to align with evolving aviation sustainability targets and next-generation aircraft requirements. Many industry participants are expanding their maintenance, repair, and overhaul capabilities to capture growing aftermarket revenue opportunities generated by increasing aircraft utilization rates. Strategic partnerships with aircraft OEMs and airline operators are also helping companies secure long-term installation and servicing contracts. In addition, market players are prioritizing geographic expansion, production capacity enhancement, and technology integration to improve operational efficiency and broaden customer reach. Continuous investments in lightweight materials, digital monitoring systems, and low-emission power solutions are further enabling companies to strengthen their competitive presence within the global aircraft auxiliary power unit industry.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Technology type trends
- 2.2.2 Aircraft platform trends
- 2.2.3 Power rating trends
- 2.2.4 Sales channel trends
- 2.2.5 End users trends
- 2.2.6 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Expansion of global aircraft fleet
- 3.2.1.2 Increasing aircraft modernization and retrofit programs
- 3.2.1.3 Growth in air passenger traffic
- 3.2.1.4 Expansion of aircraft maintenance, repair, and overhaul (MRO) activities
- 3.2.1.5 Rising focus on aircraft operational efficiency and ground support optimization
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High cost and complexity of advanced APU systems
- 3.2.2.2 Supply chain disruptions and component availability challenges
- 3.2.3 Market opportunities
- 3.2.3.1 Integration of hybrid-electric and more-electric aircraft architectures
- 3.2.3.2 Advancements in digital APU monitoring and predictive maintenance
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter’s analysis
- 3.6 PESTEL analysis
- 3.7 Technology and Innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By product
- 3.9 Pricing Strategies
- 3.10 Emerging Business Models
- 3.11 Compliance Requirements
- 3.12 Patent and IP analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.2 Market concentration analysis
- 4.2.1 By region
- 4.3 Competitive benchmarking of key players
- 4.3.1 Financial performance comparison
- 4.3.1.1 Revenue
- 4.3.1.2 Profit margin
- 4.3.1.3 R&D
- 4.3.2 Product portfolio comparison
- 4.3.2.1 Product range breadth
- 4.3.2.2 Technology
- 4.3.2.3 Innovation
- 4.3.3 Geographic presence comparison
- 4.3.3.1 Global footprint analysis
- 4.3.3.2 Service network coverage
- 4.3.3.3 Market penetration by region
- 4.3.4 Competitive positioning matrix
- 4.3.4.1 Leaders
- 4.3.4.2 Challengers
- 4.3.4.3 Followers
- 4.3.4.4 Niche players
- 4.3.5 Strategic outlook matrix
- 4.3.1 Financial performance comparison
- 4.4 Key developments
- 4.4.1 Mergers and acquisitions
- 4.4.2 Partnerships and collaborations
- 4.4.3 Technological advancements
- 4.4.4 Expansion and investment strategies
- 4.4.5 Digital transformation initiatives
- 4.5 Emerging/ startup competitors landscape
Chapter 5 Market Estimates and Forecast, By Technology Type, 2022 - 2035 (USD Million)
- 5.1 Key trend
- 5.2 Conventional gas turbine APUs
- 5.3 Hybrid-electric APUs
- 5.4 Electric/battery-powered APUs
- 5.5 Fuel cell-based APUs
- 5.6 By End Users
Chapter 6 Market Estimates and Forecast, By Aircraft Platform, 2022 - 2035 (USD Million)
- 6.1 Key trends
- 6.2 Commercial aviation
- 6.2.1 Narrow-body aircraft
- 6.2.2 Wide-body aircraft
- 6.2.3 Regional jets
- 6.3 Military aviation
- 6.3.1 Fighter & combat aircraft
- 6.3.2 Transport & tanker aircraft
- 6.3.3 Special mission platforms
- 6.4 Business & general aviation
- 6.4.1 Business jets
- 6.4.2 Light general aviation aircraft
- 6.5 Rotorcraft
- 6.5.1 Commercial helicopters
- 6.5.2 Military helicopters
- 6.6 Unmanned aerial vehicles (UAVs)
- 6.6.1 Medium-altitude long-endurance (MALE)
- 6.6.2 High-altitude long-endurance (HALE)
Chapter 7 Market Estimates and Forecast, By Power Rating, 2022 - 2035 (USD Million)
- 7.1 Key trends
- 7.2 Low power APUs (<50 kVA)
- 7.3 Medium power APUs (50-150 kVA)
- 7.4 High power APUs (>150 kVA)
Chapter 8 Market Estimates and Forecast, By Sales Channel, 2022 - 2035 (USD Million)
- 8.1 Key trends
- 8.2 OEM (line-fit/new installation)
- 8.3 Aftermarket
Chapter 9 Market Estimates and Forecast, By End Users, 2022 - 2035 (USD Million)
- 9.1 Key trends
- 9.2 Military
- 9.3 Commercial
- 9.4 Civil & government
Chapter 10 Market Estimates and Forecast, By Region, 2022 - 2035 (USD Million)
- 10.1 Key trends
- 10.2 North America
- 10.2.1 U.S.
- 10.2.2 Canada
- 10.3 Europe
- 10.3.1 Germany
- 10.3.2 UK
- 10.3.3 France
- 10.3.4 Spain
- 10.3.5 Italy
- 10.3.6 Russia
- 10.4 Asia Pacific
- 10.4.1 China
- 10.4.2 India
- 10.4.3 Japan
- 10.4.4 Australia
- 10.4.5 South Korea
- 10.5 Latin America
- 10.5.1 Brazil
- 10.5.2 Mexico
- 10.5.3 Argentina
- 10.6 Middle East and Africa
- 10.6.1 South Africa
- 10.6.2 Saudi Arabia
- 10.6.3 UAE
Chapter 11 Company Profiles
- 11.1 Global Key Players
- 11.1.1 Honeywell International Inc.
- 11.1.2 Collins Aerospace
- 11.1.3 Safran Power Units
- 11.1.4 Pratt & Whitney
- 11.1.5 TAT Technologies Ltd.
- 11.2 Regional key players
- 11.2.1 North America
- 11.2.1.1 Hamilton Sundstrand
- 11.2.1.2 Dewey Electronics Corporation
- 11.2.2 Asia Pacific
- 11.2.2.1 Aerosila JSC
- 11.2.2.2 Klimov
- 11.2.2.3 Motor Sich JSC
- 11.2.2.4 Technodinamika
- 11.2.3 Europe
- 11.2.3.1 PBS Aerospace Inc.
- 11.2.3.2 Microturbo
- 11.2.3.3 Jenoptik AG
- 11.2.4 Middle East & Africa
- 11.2.4.1 Kinetics Ltd.
- 11.2.1 North America

 飛機輔助動力系統市場報告:趨勢、預測與競爭分析(至2035年)
 航太與軍用輔助動力系統市場-2026-2032年全球市場預測
 軍用輔助電源系統市場機會、成長要素、產業趨勢分析及2026-2035年預測全球輔助動力裝置市場:2026-2036年全球國防輔助動力裝置(APU)市場:2026-2036年
 全球飛機輔助動力裝置(APU)市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 2026年全球飛機輔助動力系統市場報告飛機輔助動力裝置(APU)市場規模、佔有率、成長及全球產業分析:按類型、應用和地區分類的洞察,2026-2034年預測
 全球飛機輔助動力裝置(APU)市場評估:依飛機類型、安裝類型、燃料類型、地區、機會及預測,2018-2032
 輔助動力裝置市場 - 全球產業規模、佔有率、趨勢、機會和預測,按 APU 類型、按功率輸出(小型 APU、中型 APU、大型 APU)、按行業垂直、按地區和競爭細分,2020-2030 年